
 Microcontroller Unit (MCU) Market | 2026-2036
Microcontroller Unit (MCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Microcontroller Unit (MCU) Market Foresight
Silicon carbide substrate costs are consolidating around 150mm wafer transitions, altering power-MCU companion chip economics. NXP Semiconductors leverages its S32 platform to anchor automotive real-time compute requirements across domain architectures. STMicroelectronics competes through in-house SiC and MCU co-development, while Infineon Technologies extends its TriCore family into zone-controller designs.
A microcontroller unit integrates a processor core, volatile and non-volatile memory, and programmable peripherals onto a single die, typically fabricated at 40nm to 90nm nodes for automotive reliability. Its primary purpose is deterministic, low-latency control of electromechanical systems in cost-constrained volumes. The 32-bit MCU category captures the dominant margin pool as automotive and industrial automation applications demand higher clock speeds and richer peripheral sets. Embedded technology remains the foundational architecture, though wireless connectivity modules are gaining attach rates in IoT endpoints and smart metering infrastructure.
The EU Cyber Resilience Act and ISO 26262 functional-safety framework are mandating traceable software supply chains and fault-tolerant hardware designs for automotive MCUs. In the United States, NHTSA guidelines and FDA software-validation requirements for medical devices are extending qualification timelines and favoring vendors with established regulatory dossiers. Stakeholders must monitor how regional cybersecurity certification schemes fragment market access before committing to single-qualification strategies.
Market Dynamics
Automotive electrification is compressing MCU qualification timelines while simultaneously expanding functional-safety requirements, forcing silicon vendors to reconcile faster time-to-market with stricter ISO 26262 traceability mandates.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory software-bill-of-materials disclosure for connected devices is accelerating demand for pre-certified, secure-by-design automotive MCUs with hardware root-of-trust capabilities.
- EV powertrain integration:Battery management systems and motor controllers require deterministic real-time control, pulling 32-bit MCUs into domain-controller architectures previously served by discrete logic.
- China mature-node expansion:Domestic foundry capacity at 40nm-90nm nodes is reducing lead times for automotive-grade silicon, supporting localized supply chains for domestic EV manufacturers.
Market Restraints
- Silicon carbide substrate scarcity:150mm SiC wafer supply constraints are elevating companion power-device costs, compressing margins on integrated power-MCU modules.
- Automotive qualification backlog:AEC-Q100 testing capacity at third-party labs is concentrated in Germany and Japan, creating 18-24 month bottlenecks for new entrants.
- Legacy 8-bit MCU substitution:Cost-optimized RISC-V cores are displacing proprietary architectures in white-goods and metering applications, eroding royalty streams for incumbent IP holders.
Strategic Opportunities
- Zone-controller consolidation:Centralized vehicle E/E architectures are creating white space for high-core-count MCUs that aggregate sensor inputs across multiple physical domains.
- Medical device connectivity:FDA software-validation requirements for wireless-enabled diagnostic equipment are favoring MCU vendors with established 510(k) dossiers and deterministic wireless stacks.
- Industrial edge AI:Convergence of TinyML inference engines with deterministic control loops is opening attach-rate expansion for MCUs with vector extensions in packaging automation.
Industry Challenges
- Functional-safety talent scarcity:ISO 26262 certified software architects and hardware verification engineers command 40-60% compensation premiums, constraining R&D scaling for mid-tier vendors.
- Multi-die integration complexity:Heterogeneous packaging of logic, memory, and power devices is extending design-validation cycles and elevating non-recurring engineering costs for advanced node migration.
- Traceability toolchain fragmentation:Incompatible requirements-management platforms across OEMs are forcing MCU vendors to maintain parallel software supply-chain documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcontroller Unit (MCU) Market |
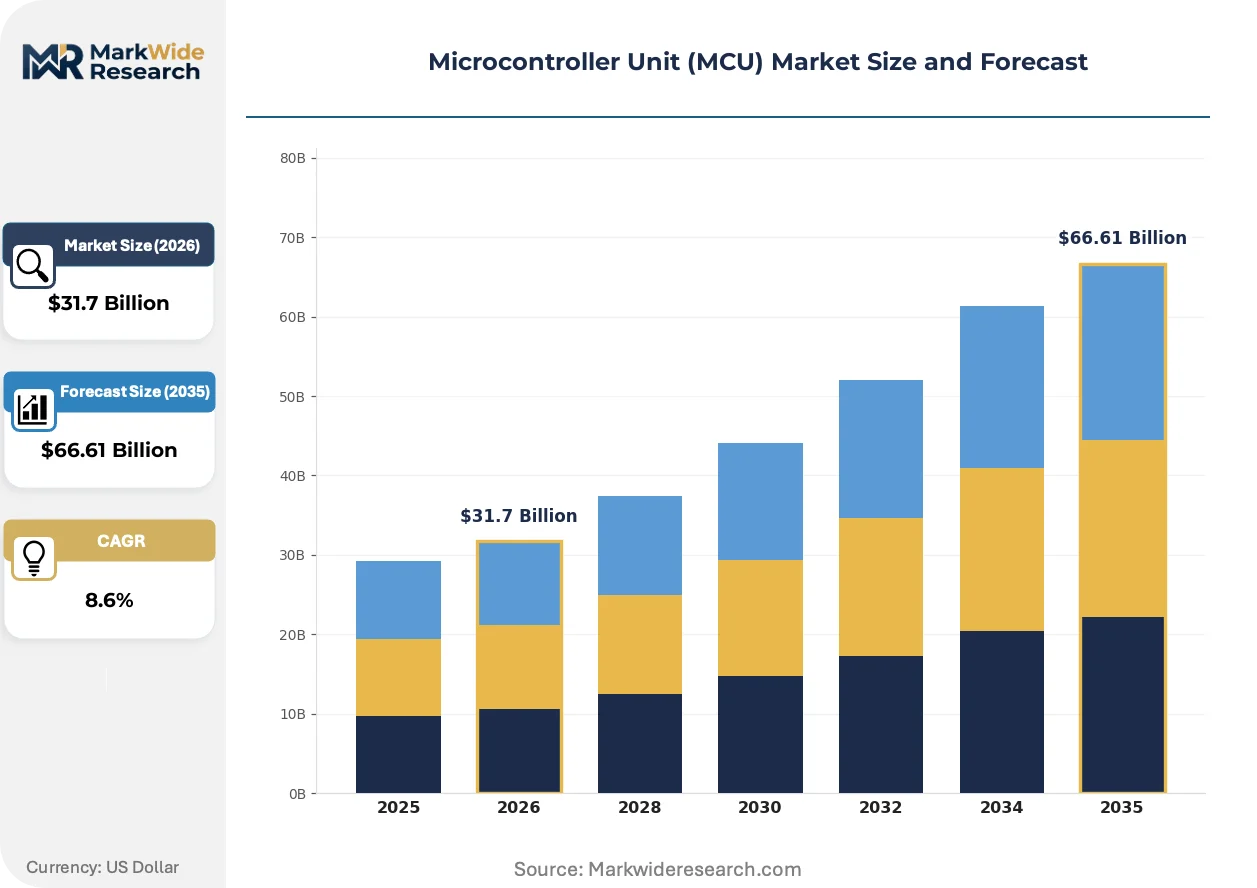
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $66.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit MCU, 16-bit MCU, 32-bit MCU, Digital Signal Controller Application: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Technology: Embedded, Wireless, Analog, Mixed Signal End User: OEMs, Telecom, Aerospace, Robotics |
| Companies Covered | NXP Semiconductors, Microchip Technology, Renesas Electronics, STMicroelectronics, Infineon Technologies, Texas Instruments, Toshiba, Rohm, Silicon Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcontroller Unit (MCU) Market Shifts & Advancements
Deterministic edge computing is displacing cloud-dependent control loops in safety-critical applications, while regulatory pressure on software supply-chain transparency is reshaping how MCU vendors architect security and documentation.
Silicon carbide power integration is electrifying automotive traction-inverter designs by enabling higher switching frequencies at elevated temperatures. Tier-1 suppliers are adopting SiC-agnostic gate-driver MCUs at accelerated pace to preserve platform flexibility across OEM programs. This technology convergence is compressing the discrete-component count in power stages and elevating thermal-management requirements for control silicon.
REACH substance restrictions on persistent organic pollutants are forcing MCU packaging houses to qualify halogen-free mold compounds and lead-free bump metallurgies. The industrial consequence is extended material-characterization timelines and elevated qualification costs for automotive-grade products. European automotive OEMs are responding by consolidating approved-vendor lists to suppliers with pre-validated green-material portfolios.
Buyer concentration among EV-native OEMs is compressing MCU procurement cycles from annual blanket orders to quarterly demand-signal adjustments. Direct OEM engagement is displacing traditional tiered distribution in high-volume programs, particularly for domain-controller silicon. This pattern is most visible in China, where domestic EV manufacturers are vertically integrating power electronics design teams and negotiating direct foundry allocations.
Microcontroller Unit (MCU) Market Segmentation
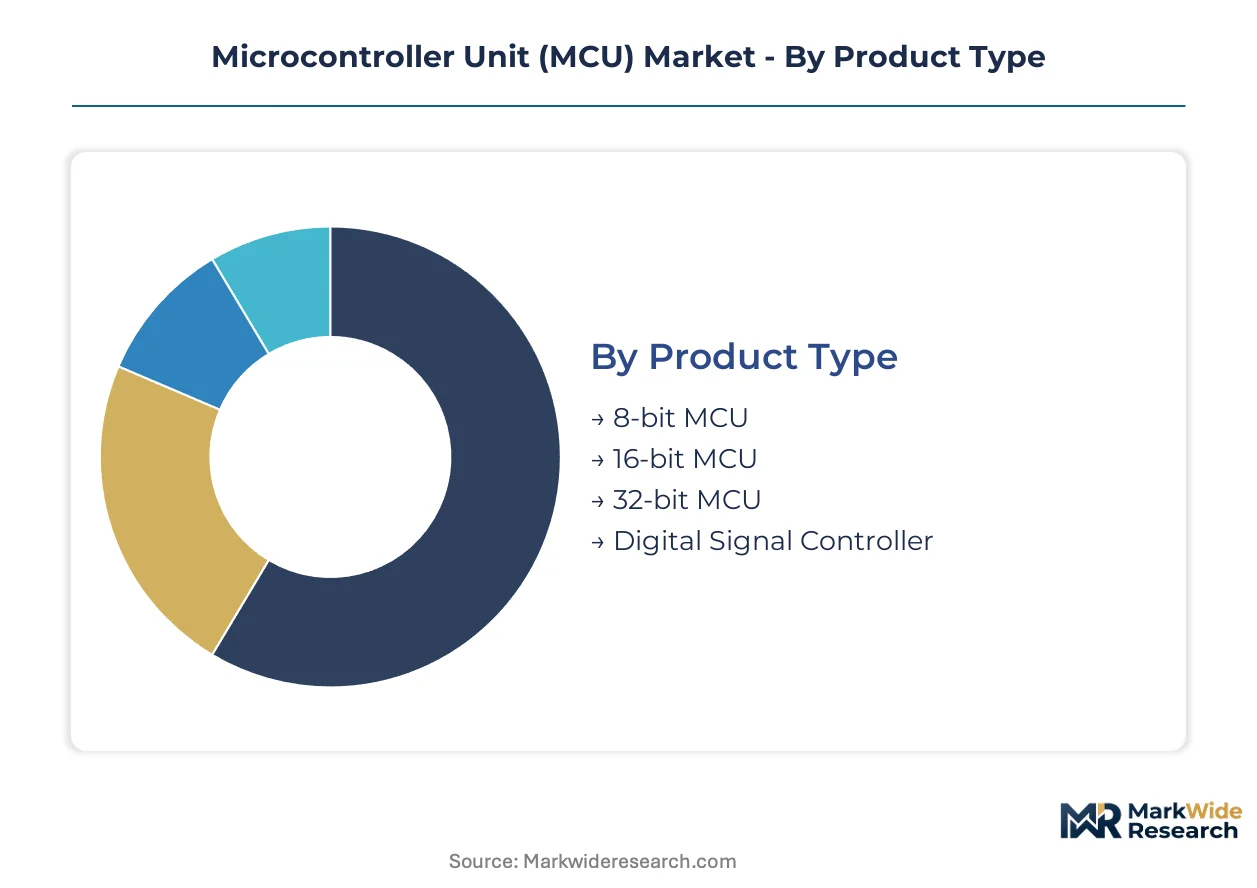
MCU segmentation reveals how bit-width architectures, application-specific reliability requirements, and connectivity integration reshape procurement priorities across automotive electrification and industrial automation. Technology vendors align product roadmaps to these axes to capture margin concentration in safety-critical and high-volume IoT deployments.
Product Type:
Bit-width specifications determine real-time processing capability, memory addressing range, and peripheral integration density for deterministic control applications.
- 32-bit MCU:ARM Cortex-M and RISC-V cores dominate this category with clock speeds exceeding 100 MHz and embedded flash densities above 512 KB. Automotive domain controllers in Germany and Japan absorb the highest volumes as ISO 26262 ASIL-D requirements intensify for EV powertrain management.
- 8-bit MCU:Legacy architectures fabricated at 180nm-350nm nodes persist in cost-constrained electromechanical systems. White-goods manufacturers in China and appliance OEMs in Mexico sustain procurement volumes despite RISC-V displacement pressure at the low end.
- 16-bit MCU:Mid-range processing for motor control and digital power conversion bridges 8-bit cost structures with 32-bit performance envelopes.
- Digital Signal Controller:Hybrid DSP-MCU architectures optimize multiply-accumulate throughput for power-factor correction and sensor-fusion algorithms.
Mature deployment sits with 8-bit MCU. Newer deployment is concentrated in 32-bit MCU.
Application:
End-use reliability tiers and qualification timelines fragment vendor strategies across consumer, automotive, and industrial safety domains.
- Automotive:AEC-Q100 Grade 0 qualification mandates temperature operation from -40°C to 150°C with zero defect ppm targets. NHTSA guidelines and EU Cyber Resilience Act traceability requirements are extending software-validation cycles for battery management and zone-controller silicon.
- Industrial Automation:IEC 61508 SIL-2 and SIL-3 certifications govern programmable logic controllers and robotic motion systems. German automotive suppliers and Japanese factory-equipment OEMs specify extended-temperature packages with 10-15 year supply guarantees.
- Consumer Electronics:Smartphone accessory controllers and wearable devices prioritize die-size minimization and aggressive cost-down roadmaps over extended reliability.
- Medical Devices:FDA 510(k) and EU MDR software-validation requirements constrain wireless-enabled diagnostic equipment to vendors with pre-established regulatory dossiers.
Revenue concentration clusters in Automotive. Volume expansion is climbing the fastest in Industrial Automation.
Technology:
Integration depth—from pure digital logic to RF-analog hybrids—determines foundry process selection and packaging complexity.
- Embedded:Deterministic control without external connectivity remains the foundational architecture for safety-critical applications. Foundry capacity at 40nm-90nm nodes in Taiwan and China supports automotive-grade flash MCUs with 10-year data retention.
- Wireless:Sub-GHz and 2.4 GHz radio integration is gaining attach rates in smart metering infrastructure and IoT endpoints. FCC Part 15 and ETSI EN 300 220 certification costs are favoring module suppliers with pre-qualified protocol stacks.
- Analog:Precision ADCs and operational amplifiers integrated alongside digital cores reduce discrete component counts in sensor-interface applications.
- Mixed Signal:Combined analog front-end and digital processing enables single-chip solutions for power-management and signal-conditioning functions.
Volume leadership rests with Embedded. Technology differentiation is expanding most quickly in Wireless.
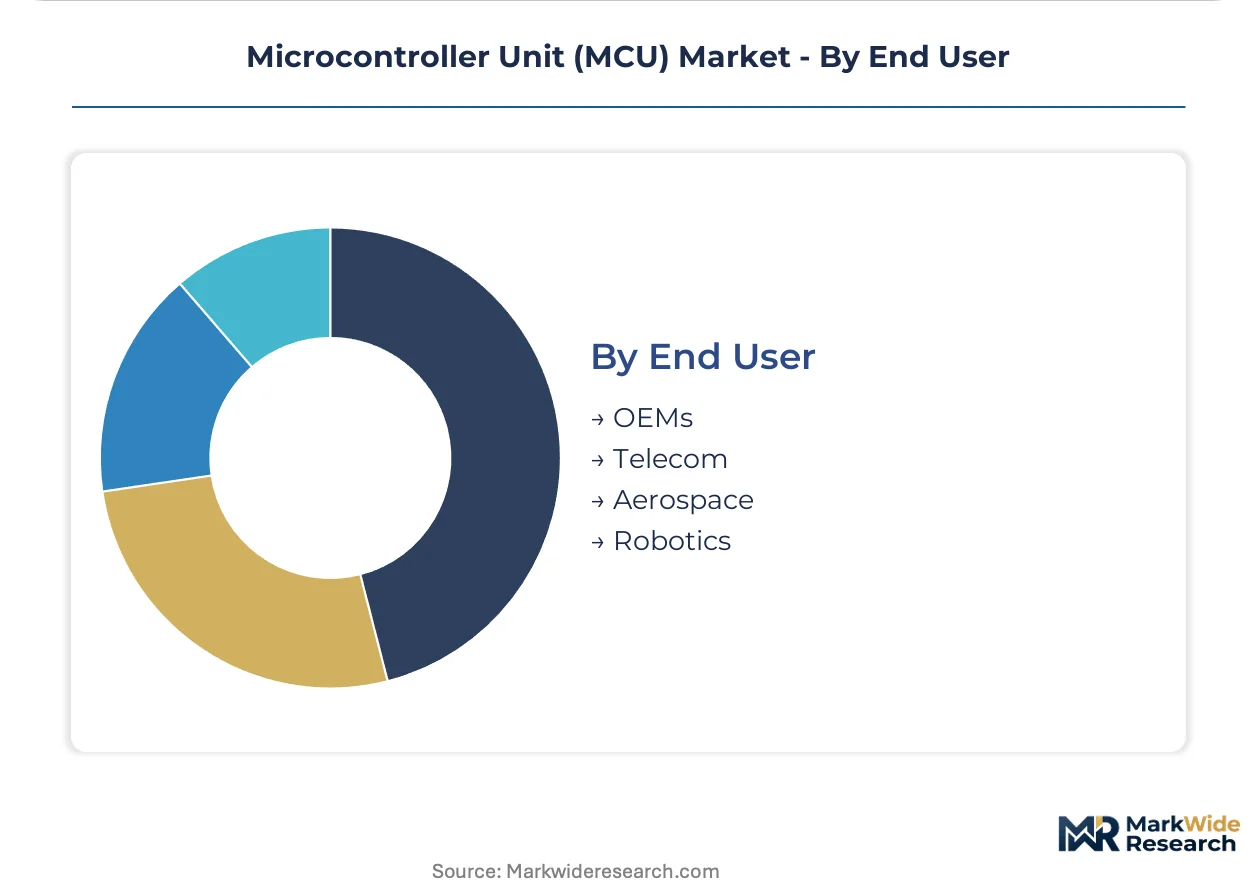
End User:
Procurement scale and qualification authority concentrate demand patterns across direct OEM engagement and tiered distribution channels.
- OEMs:Direct foundry allocations and quarterly demand-signal adjustments characterize high-volume programs. Chinese EV-native manufacturers are consolidating power electronics design teams and negotiating bypass of traditional semiconductor distribution.
- Telecom:Base-station controllers and network infrastructure equipment specify extended-temperature industrial-grade MCUs with supply-chain traceability documentation.
- Aerospace:DO-178C software certification and MIL-STD-883 screening impose qualification timelines exceeding 24 months for flight-control and avionics applications.
- Robotics:Collaborative robot arms and autonomous mobile platforms fuse deterministic motor control with AI acceleration, pulling heterogeneous MCUs into joint-controller architectures.
Procurement scale concentrates with OEMs. Emerging specification authority is gathering fastest in Robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hengqin-Macao In-depth Cooperation Zone in Zhuhai accelerates MCU assembly concentration through 15% corporate income tax holidays for advanced semiconductor enterprises. This incentive architecture redirects packaging and test capacity toward automotive-grade silicon serving domestic EV manufacturers.
China
Domestic EV production scales demand for 32-bit automotive MCUs in battery management and motor control applications. MIIT mandates local content ratios in intelligent vehicle supply chains through its Made in China 2025 semiconductor targets. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates foundry capacity at 40nm-90nm nodes, with SMIC and Hua Hong ramping automotive-qualified output.
Germany
Automotive OEMs in Stuttgart and Munich specify ASIL-D certified MCUs for domain-controller architectures in premium EV platforms. KBA enforces UNECE R155 cybersecurity management system audits for vehicle type approval, extending software-validation timelines. The Baden-Württemberg silicon corridor anchors Infineon and Bosch semiconductor operations, with AEC-Q100 testing labs in Reutlingen experiencing 18-month qualification backlogs.
United States
Tesla, Rivian, and legacy Detroit manufacturers absorb high-core-count MCUs for zone-controller consolidation in centralized E/E architectures. NHTSA guidelines on vehicle cybersecurity and software transparency impose documentation burdens comparable to EU Cyber Resilience Act requirements. Austin, Texas, and Phoenix, Arizona, concentrate fabless MCU design operations alongside Tesla's vertically integrated power electronics teams.
Japan
Toyota, Honda, and Nissan procurement specifications favor deterministic control silicon with 10-15 year supply guarantees for hybrid powertrain programs. METI's semiconductor industry revitalization plan subsidizes domestic 40nm MCU fabrication at Kioxia and Sony joint ventures. The Kyushu silicon island hosts Renesas Naka and Saijo fabs, with Kumamoto earthquake resilience investments securing automotive-grade capacity.
South Korea
Hyundai-Kia and Samsung SDI demand MCUs with integrated gate drivers for SiC traction inverter platforms in Genesis and Ioniq EV lines. MFDS alignment with EU MDR streamlines medical device MCU qualification for Korean diagnostic equipment exporters. The Seoul Capital Area concentrates fabless design houses serving robotics and industrial automation segments.
Microcontroller Unit (MCU) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDMs commanding automotive safety-critical sockets and foundry partners capturing cost-optimized consumer volumes. The vendor base organizes into three tiers: integrated device manufacturers with in-house SiC co-development, fabless specialists licensing ARM or RISC-V cores, and captive semiconductor divisions of tier-1 automotive suppliers. Consolidation pressures favor M&A between MCU vendors and power-semiconductor specialists, while qualification backlog constraints limit new entrant penetration.
Within the integrated device manufacturer tier, NXP Semiconductors, Infineon Technologies, and STMicroelectronics exemplify the convergence of automotive functional-safety certification with power-device integration. These European-anchored firms occupy positions defined by ISO 26262 traceability dossiers and AEC-Q100 Grade 0 qualification breadth. Their competitive positioning reflects decades of automotive OEM direct engagement rather than module supplier mediation.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Microchip Technology |
| Renesas Electronics |
| STMicroelectronics |
| Infineon Technologies |
| Texas Instruments |
| Toshiba |
| Rohm |
| Silicon Labs |
| Others |
Supply & Pricing Matrix
150mm silicon carbide wafer spot indices cascade through automotive MCU supply chains, compressing margins on integrated power modules while amplifying premiums for AEC-Q100 Grade 0 qualified inventory with sub-quarter lead times. Tier 1 suppliers in Germany and Japan absorb these cost transfers through annual contract renegotiations, whereas Chinese EV-native OEMs exploit domestic foundry scale to neutralize substrate volatility.
Pricing Analysis
Lead-time premiums dominate MCU procurement, with AEC-Q100 Grade 0 silicon commanding substantial markups for delivery under 12 weeks against discounted spot inventory carrying 6-month-plus availability. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels segments buyer willingness-to-pay, with ISO 26262 ASIL-D traceability adding further differentiation. Cost compression in 8-bit legacy tiers is intensifying because RISC-V cores displace proprietary royalty-bearing architectures. White-goods manufacturers in Mexico exhibit highest price sensitivity, while German automotive OEMs prioritize supply security over unit economics.
Supply Chain Analysis
Container freight rates from Taiwan and South Korea to Hamburg and Long Beach directly alter landed costs for packaged MCU volumes, with 40ft container pricing volatility passing through to quarterly contract adjustments. Foundry concentration in Taiwan, China, and South Korea anchors wafer supply, while AEC-Q100 testing capacity clusters in Germany and Japan. Silicon carbide substrates, copper leadframes, and halogen-free mold compounds constitute critical input dependencies. Single-source vulnerability permeates 150mm SiC wafer supply. Distribution runs through authorized distributors for long-tail industrial accounts and direct OEM engagement for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AEC-Q100 testing capacity scarcity props automotive-grade MCU pricing, with 18-24 month qualification backlogs at third-party labs constraining new entrant supply expansion and preserving incumbent margin structures.
For Market Incumbents: Deploy backward integration into SiC substrate supply to secure companion power-device cost positions against STMicroelectronics and Infineon captive sourcing advantages. Accelerate ISO 26262 certified software architect recruitment in Baden-Württemberg and Tokyo to offset 40-60% compensation premiums eroding R&D scaling. Consolidate zone-controller reference designs with Chinese EV-native OEMs before quarterly demand-signal procurement displaces annual blanket orders entirely. For New Entrants and Emerging Players: Industrial edge AI attach-rate expansion in German packaging automation represents the most penetrable white-space, with TinyML vector-extension MCUs underserved by incumbent real-time control roadmaps. Target medical device connectivity in South Korea through MFDS-aligned 510(k) dossier partnerships, exploiting FDA software-validation bottlenecks favoring pre-qualified vendors. Pursue fabless RISC-V core licensing with Chinese foundry direct allocation to bypass AEC-Q100 testing queues. For Investors and Strategic Acquirers: The window for entry favors power-semiconductor specialists with SiC gate-driver MCU co-development capabilities, as consolidation pressures intensify between MCU vendors and traction-inverter component suppliers. Mid-tier vendors with automotive functional-safety certification breadth but constrained testing capacity represent prime acquisition targets. Monitor 150mm SiC wafer spot price normalization as the inflection signal for integrated power-MCU margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Testing Capacity Expansion | Third-party lab investment in Germany and Japan alleviates 18-24 month qualification bottlenecks constraining new entrant supply. |
| SiC-Agnostic Gate-Driver MCU Development | Platform flexibility preserves Tier 1 supplier positioning across divergent OEM traction-inverter architectures. |
| Zone-Controller Reference Design Partnerships | Direct OEM engagement in China secures quarterly demand-signal allocation before distribution displacement accelerates. |
| ISO 26262 Certified Talent Acquisition | Software architect recruitment in Stuttgart and Tokyo offsets compensation premiums threatening R&D scaling economics. |
| Halogen-Free Mold Compound Qualification | REACH compliance pre-validation secures European automotive OEM approved-vendor list consolidation. |
Research Methodology
Document review covered SEC semiconductor filings, AEC-Q100 test house certification records, and MIIT Made in China 2025 policy documents, complemented by interviews with MCU product line managers at integrated device manufacturers, automotive Tier 1 procurement directors, and foundry capacity planning officers. Secondary validation drew from customs wafer import data, IHS Markit vehicle production databases, and ECHA REACH substance restriction advisories. Bottom-up unit demand modeling and top-down semiconductor industry revenue triangulation anchored forecast integrity.
Projected value outputs across bit-width architectures, application reliability tiers, and connectivity integration depths reflect a structured analytical framework spanning the projection horizon. Segmentation dimensions encompassed 32-bit versus 8-bit core deployment, automotive AEC-Q100 versus industrial IEC 61508 certification tracks, and embedded versus wireless technology attach rates. CAGRs derived from historical foundry capacity expansion patterns correlated with EV powertrain MCU content-per-vehicle trajectories and regional regulatory mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 150mm SiC substrate supply normalization, China-U.S. technology export control evolution, and ISO 26262 talent pool expansion rates. Forecasts reflect documented assumptions around foundry yield improvements and automotive qualification timeline compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
VR Gaming Hardware Chipsets Market