
 Global Graphic Processors Market | 2026-2036
Global Graphic Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphic Processors Market Analysis
The EU AI Act is realigning procurement criteria for high-performance graphic processors across European data center operators. NVIDIA Corporation leverages its CUDA software ecosystem to sustain developer lock-in across enterprise AI deployments. Advanced Micro Devices competes aggressively on price-performance in cloud gaming and mainstream datacenter acceleration. Intel Corporation anchors its strategy around integrated GPU-CPU packages for edge AI inference workloads.
Graphic processors are specialized parallel compute engines containing thousands of shader cores optimized for simultaneous floating-point operations, fabricated on advanced semiconductor nodes with high-bandwidth memory interfaces. Their primary commercial purpose centers on rendering visual output and accelerating matrix-heavy computations for artificial intelligence, scientific simulation, and real-time graphics. Dedicated GPUs command the dominant revenue share in gaming and professional visualization, while integrated GPUs capture volume leadership in consumer laptops where thermal constraints limit discrete solutions. The AI and Deep Learning application segment exhibits the steepest growth trajectory as training runs for large language models consume ever-larger GPU clusters.
The US FCC governs electromagnetic emissions from GPU-powered devices, while the EU RoHS directive restricts hazardous substances in semiconductor packaging, and China's GB standards mandate energy efficiency benchmarks for computing equipment. These frameworks collectively push manufacturers toward cleaner fabrication processes and lower-power architectures without compromising compute density. Stakeholders must monitor how export control regimes on advanced chip manufacturing equipment reshape supply availability across major consuming regions.
Market Dynamics
Generative AI training clusters are consuming GPU silicon at unprecedented scale, forcing foundries to prioritize high-bandwidth memory architectures over traditional consumer graphics dies. This demand concentration is reshaping allocation rules across Taiwan's semiconductor fabrication network.
Growth Catalysts
- EU AI Act compliance mandates:European data center operators must upgrade to certified high-performance compute systems, creating immediate procurement pull for compliant GPU architectures.
- Cloud gaming infrastructure buildouts:Streaming service providers are deploying edge GPU nodes to reduce latency, expanding addressable silicon demand beyond traditional gaming hardware.
- Scientific simulation workloads:Weather modeling and molecular dynamics research institutions are procuring dedicated GPU clusters for parallel floating-point computation.
Market Restraints
- CoWoS packaging bottleneck:Taiwan's advanced substrate capacity constrains output of high-bandwidth memory stacks essential for datacenter accelerators.
- Export control friction:US Bureau of Industry and Security licensing requirements delay shipment of advanced GPU variants to designated end-users.
- Power density limits:Thermal design constraints in air-cooled facilities cap rack-scale GPU deployment density regardless of silicon availability.
Strategic Opportunities
- India's semiconductor PLI scheme:Assembly and test incentives attract GPU packaging investments to diversify supply geography beyond Taiwan.
- Automotive inference at the edge:Autonomous driving compute platforms require low-power GPU IP for real-time sensor fusion processing.
- Chiplets and 3D stacking convergence:Disaggregated GPU architectures enable mix-and-match compute and memory tiles for workload-specific optimization.
Industry Challenges
- CUDA software stack portability:Enterprise AI teams face retraining costs when migrating optimized models to alternative GPU instruction sets.
- Cleanroom construction timelines:New leading-edge fab capacity requires multi-year capital deployment before contributing to supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphic Processors Market |
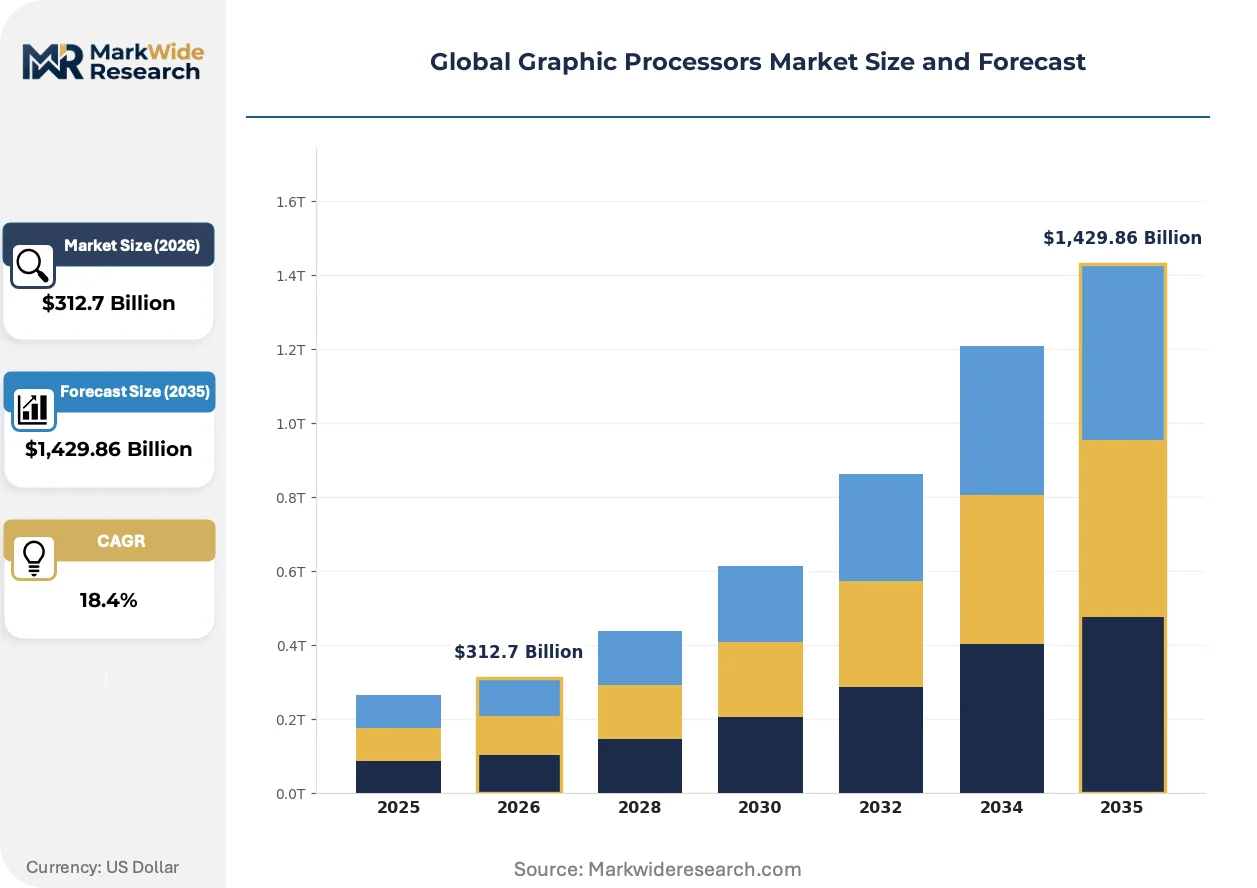
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,429.86 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated GPUs, Integrated GPUs, Workstation GPUs, Mobile GPUs Application: Gaming, AI & Deep Learning, Data Visualization, Cryptocurrency Mining End User: Gaming Industry, Graphic Design Firms, Data Centers, Education Sector Technology: Ray Tracing, Parallel Processing, Machine Learning, DirectX |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Intel Corporation, Qualcomm Incorporated, Samsung Electronics, Imagination Technologies, ARM Limited, Sony Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphic Processors Market Emerging Trajectories
Silicon architectures are fragmenting into workload-specialized designs as the one-size-fits-all GPU model yields to domain-optimized compute engines. This specialization is redrawing competitive boundaries between discrete and integrated solutions.
Chiplet-based GPU designs are expanding into datacenter acceleration by decoupling compute dies from memory stacks and I/O controllers. Hyperscale cloud operators are qualifying these modular architectures for internal AI training clusters. The approach is compressing time-to-market for new process nodes by reusing proven interconnect IP across generations.
China's GB standards for computing equipment energy efficiency are tightening operational requirements for GPU-powered systems sold domestically. Manufacturers must now submit certified power consumption metrics at varying utilization levels. Datacenter GPU product lines destined for the Chinese market are being electrically bin-strapped to meet these thresholds.
Enterprise buyers are consolidating GPU procurement through direct foundry partnerships rather than traditional distributor channels. Large cloud operators now negotiate wafer starts and capacity reservations years ahead of silicon availability. This pattern is most visible in North American hyperscaler campuses where custom silicon programs bypass standard component supply chains entirely.
Global Graphic Processors Market Segmentation
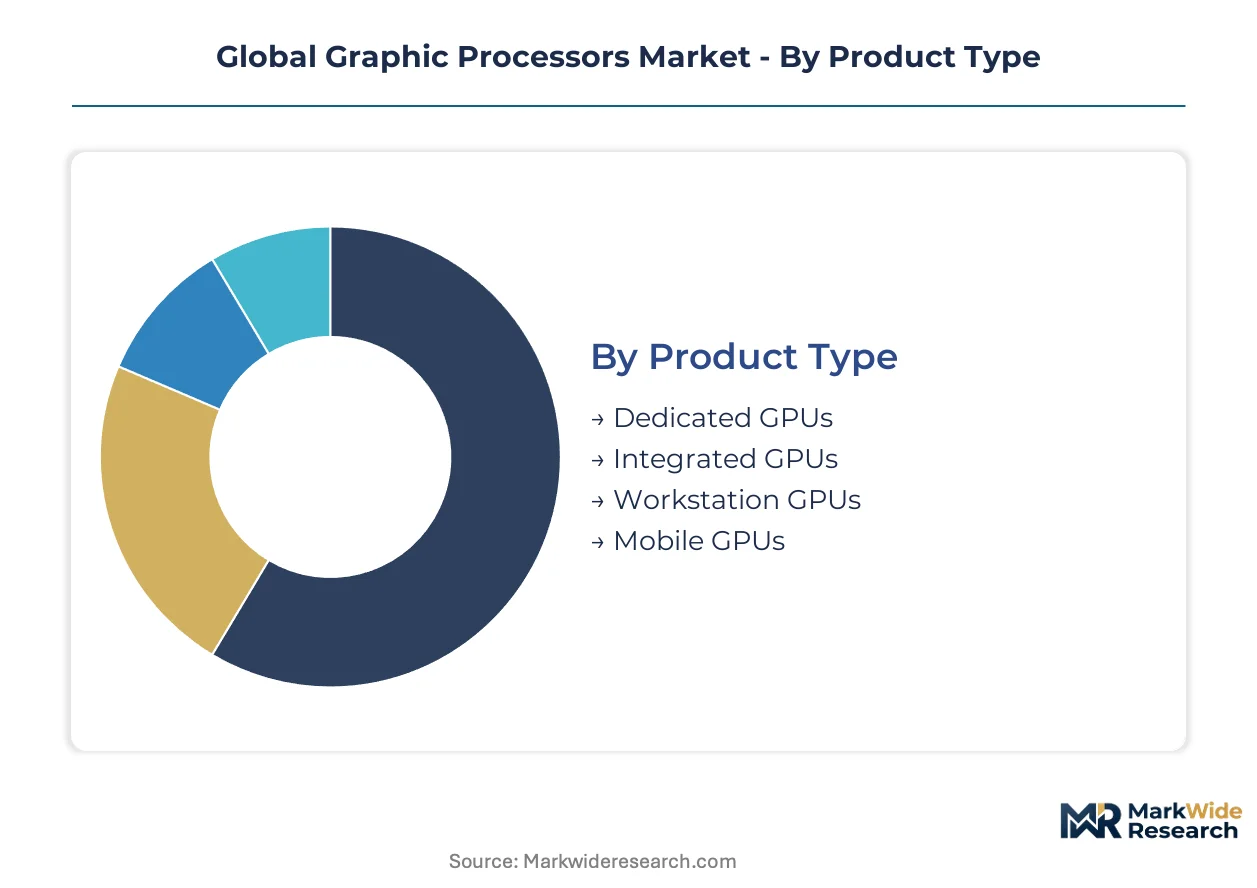
GPU market segmentation reveals divergent silicon architectures optimized for thermal envelopes, memory bandwidth, and parallel compute intensity. Volume leadership concentrates in integrated solutions, while revenue gravity pulls toward discrete accelerators for datacenter AI training.
Product Type:
Dedicated GPUs command premium pricing through discrete memory subsystems and massive shader arrays, while integrated solutions dominate shipment volumes by embedding graphics within CPU packages.
- Dedicated GPUs:Discrete silicon dies with dedicated GDDR6X or HBM3 memory stacks enable the highest floating-point throughput for AI training clusters. Hyperscale cloud operators in the United States are reserving wafer capacity years ahead for these accelerators, constrained by CoWoS packaging bottlenecks at Taiwan foundries.
- Integrated GPUs:Graphics cores embedded within CPU dies share system memory and thermal budgets, optimizing for battery life in thin-form-factor laptops. Consumer OEMs in Japan and South Korea specify these solutions for ultraportable segments where discrete graphics exceed power envelopes.
- Workstation GPUs:ISV-certified drivers and ECC memory support professional visualization pipelines. Engineering firms in Germany deploy these for CAD and simulation workloads requiring computational precision.
- Mobile GPUs:Thermally constrained variants with aggressive clock gating target smartphone and tablet form factors. Chinese handset OEMs integrate these for gaming-optimized sub-flagship tiers.
Mature deployment sits with Integrated GPUs. Newer deployment is concentrated in Dedicated GPUs.
Application:
Application segmentation tracks how matrix computation intensity and real-time latency requirements reshape silicon procurement patterns across consumer and enterprise verticals.
- Gaming:Real-time rasterization and ray-traced lighting effects demand high fill rates and memory bandwidth. Esports venues in South Korea and streaming-first markets in Brazil are upgrading display refresh infrastructure to match GPU output capabilities.
- AI & Deep Learning:Transformer model training requires massive parallel floating-point operations across thousands of cores. Research institutions in the United Kingdom and commercial labs in Singapore are provisioning dedicated clusters for foundation model development.
- Data Visualization:Medical imaging and geospatial rendering leverage GPU texture mapping for interactive dataset exploration. Hospital networks in France deploy these for radiology workstation acceleration.
- Cryptocurrency Mining:Proof-of-work algorithms favor GPUs with optimal hash-per-watt efficiency. Mining operations in Kazakhstan and Texas continue procuring prior-generation silicon for cost-optimized deployments.
Revenue expansion is steepest in AI & Deep Learning. Volume foundation remains in Gaming.
End User:
End user segmentation reflects divergent procurement cycles, with consumer gaming refreshing on 2-3 year horizons while datacenter infrastructure extends across decade-long depreciation schedules.
- Gaming Industry:Console manufacturers and PC peripheral OEMs drive cyclical demand tied to title release schedules. Japanese platform holders are negotiating custom silicon variants for next-generation hardware refreshes.
- Graphic Design Firms:Adobe Creative Cloud and Autodesk certification requirements dictate GPU selection for creative workstations. Boutique agencies in Italy and Spain prioritize driver stability over raw compute specifications.
- Data Centers:Hyperscale operators and colocation providers deploy rack-scale GPU clusters for training and inference. Facilities in Virginia and Frankfurt are retrofitting liquid cooling to accommodate thermal densities exceeding 50kW per rack.
- Education Sector:University research computing and vocational training labs procure mid-tier solutions balancing capability against budget constraints. Indian technical institutes are expanding GPU access through centralized cluster models.
Procurement scale concentrates with Data Centers. Refresh velocity is highest in Gaming Industry.
Technology:
Technology segmentation captures architectural differentiation in rendering pipelines, with hardware-accelerated ray tracing now standard across premium tiers and machine learning silicon dominating datacenter allocations.
- Ray Tracing:Dedicated RT cores accelerate bounding volume hierarchy traversal for photorealistic lighting simulation. Game engines from Swedish and Polish developers are mandating hardware ray tracing for flagship titles.
- Parallel Processing:Thousands of concurrent shader threads execute SIMT instructions across massive data arrays. Scientific computing facilities in Switzerland leverage this for molecular dynamics and climate modeling.
- Machine Learning:Tensor cores and matrix multiply engines optimize neural network training throughput. Chinese AI labs are qualifying domestic alternatives as export controls limit access to leading-edge silicon.
- DirectX:Microsoft's graphics API stack drives compatibility requirements for Windows gaming ecosystems. Certification testing occurs at Redmond and Taipei validation labs.
Hardware integration is deepest in Parallel Processing. Acceleration is most rapid in Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's most concentrated GPU foundry ecosystem, where Taiwan Semiconductor Manufacturing Company fabricates advanced silicon for hyperscale AI training clusters across three continents.
United States
Virginia's Loudoun County and Texas's Austin metro host the densest concentrations of GPU-powered data center capacity. The FCC governs electromagnetic emissions from high-density compute racks, while the Bureau of Industry and Security administers export licensing for advanced accelerators. Northern California's Santa Clara Valley remains the design headquarters locus for fabless GPU architects.
China
Beijing and Shanghai municipal governments are channeling state capital into domestic GPU design houses to circumvent foreign silicon dependencies. MIIT's GB standards mandate stringent energy efficiency certifications for computing equipment sold domestically. The Yangtze River Delta fabrication corridor is expanding trailing-edge capacity for automotive and industrial GPU variants.
Germany
Frankfurt's Rhine-Main data center cluster is retrofitting liquid cooling infrastructure to accommodate thermal densities exceeding 50 kilowatts per rack. The EU AI Act's compliance mandates are accelerating procurement cycles for certified high-performance compute systems. Bavaria's Munich-Ingolstadt corridor hosts automotive OEMs integrating edge GPU modules for autonomous driving platforms.
Japan
Tokyo's Kanto region concentrates demand for workstation GPUs powering semiconductor design and automotive simulation workflows. METI coordinates national strategy for advanced packaging capacity to reduce CoWoS substrate bottlenecks. Kyushu's Kumamoto prefecture is attracting foreign packaging investments through subsidized cleanroom construction.
India
Bangalore and Hyderabad are emerging as design centers for GPU IP cores targeting mobile and automotive inference applications. The PLI scheme for semiconductors is incentivizing assembly and test investments to diversify supply geography. Gujarat's Dholera special investment region is positioning for advanced packaging capacity through infrastructure concessions.
Global Graphic Processors Market Vendor Landscape
The competitive structure tilts toward vertically integrated fabless architects commanding software ecosystems that lock in enterprise developer workflows. Market concentration is pronounced at the high-performance accelerator tier, where CUDA-compatible toolchains create substantial migration friction. Two strategic archetypes dominate: full-stack platform vendors bundling silicon with proprietary middleware, and modular IP licensors enabling custom silicon programs. Capacity reservation agreements with Taiwan foundries and multi-year cloud service provider commitments represent the dominant competitive moves.
Within the full-stack platform tier, NVIDIA Corporation exemplifies the vertically integrated archetype through its captive software ecosystem, while Advanced Micro Devices occupies a position as the primary alternative architecture vendor competing on price-performance metrics. Intel Corporation represents the integrated device manufacturer archetype pursuing edge inference dominance through CPU-GPU packaging convergence.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Qualcomm Incorporated |
| Samsung Electronics |
| Imagination Technologies |
| ARM Limited |
| Sony Corporation |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud operators in the United States negotiate multi-year capacity reservations directly with Taiwan foundries, anchoring contract-based pricing that decouples datacenter GPU procurement from spot-market volatility. This buyer concentration forces fabless architects to prioritize volume commitments over margin expansion in allocation decisions.
Pricing Analysis
Value-based pricing tied to training throughput per watt anchors datacenter GPU contracts, with hyperscalers benchmarking total cost of ownership across competing silicon architectures. Price differentiation rests on memory bandwidth tiers and CoWoS packaging availability, with HBM3-equipped accelerators commanding substantial premiums over GDDR6X variants. Cost compression in mainstream gaming silicon is intensifying because foundry capacity prioritizes AI training dies. Consumer OEMs in Japan and South Korea exhibit highest price sensitivity, while North American cloud operators prioritize performance-per-watt over unit economics.
Supply Chain Analysis
Cleanroom engineer availability in Hsinchu and Taichung constrains expansion velocity at advanced packaging facilities, forcing lead time extensions for high-bandwidth memory stacks. Silicon fabrication concentrates in Taiwan, South Korea, and the United States, with substrate lamination and final test operations drawing from Malaysia and Vietnam. Raw material dependencies center on silicon wafers from Shin-Etsu, photoresists from JSR, and palladium for plating from Russian and South African refiners. Single-source vulnerability around CoWoS substrate capacity represents the dominant structural risk. Distribution runs through direct foundry partnerships for hyperscalers, with tier-one distributors serving mid-market enterprise and gaming OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet-based disaggregation is displacing monolithic GPU architectures, with modular compute-memory tiles enabling workload-specific optimization that legacy designs cannot match.
For Market Incumbents: Deepen captive software ecosystem investments to heighten migration friction for enterprise AI teams evaluating alternative instruction sets. Expand CoWoS packaging partnerships in Japan's Kyushu region to diversify substrate supply beyond Taiwan's Hsinchu corridor. Foundry capacity reservation agreements with TSMC and Samsung anchor competitive positioning against emerging domestic Chinese alternatives.
For New Entrants and Emerging Players: The gap between premium datacenter accelerators and economy-tier gaming silicon creates white-space opportunity for mid-range inference-optimized dies. India's PLI-subsidized assembly and test infrastructure offers the most penetrable geography for packaging investments without Taiwan's capacity constraints. Automotive edge inference modules for German and Japanese OEMs provide a defensible go-to-market angle bypassing hyperscaler procurement consolidation.
For Investors and Strategic Acquirers: The window for entry favors chiplet interconnect IP specialists and advanced packaging equipment vendors ahead of modular architecture proliferation. Long-term viability centers on five-to-ten-year foundry service agreements that outlast current supply bottlenecks. Watch for MIIT certification approvals of domestic Chinese GPU designs as the inflection signal for accelerated import substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Deployment | Enables mix-and-match compute tiles for workload-specific optimization at TSMC and Intel foundries. |
| HBM3E Memory Stack Qualification | Secures bandwidth advantage for training clusters against competitors limited to HBM3. |
| CUDA Ecosystem Expansion | Deepens developer lock-in through optimized libraries for transformer model training pipelines. |
| India Packaging Investment | Diversifies CoWoS substrate supply beyond Taiwan through Gujarat and Karnataka facilities. |
| Automotive Edge Certification | Qualifies low-power inference dies for German OEM autonomous driving platforms in Bavaria. |
Methodological Framework
Document review covered SEC 10-K filings from fabless semiconductor architects, hyperscaler capex disclosures, and Taiwan foundry utilization reports, complemented by interviews with GPU product managers at cloud operators, foundry planning officers in Hsinchu, and procurement leads at Japanese consumer OEMs. Secondary validation drew from Bureau of Industry and Security export license databases, EU AI Act implementation guidance, and customs data for GPU silicon trade flows. Bottom-up wafer start estimates triangulated against top-down AI training cluster deployment forecasts.
Historical shipment data cross-referenced against primary panel input from datacenter infrastructure planners anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture type, memory subsystem technology, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to foundry capacity expansion schedules and AI model parameter scaling trends. Forecast inputs incorporated CoWoS packaging capacity constraints and Bureau of Industry and Security licensing approval velocities.
Underlying measurement precision varies by segment; datacenter accelerator forecasts carry tighter precision than consumer gaming estimates due to direct procurement visibility. Forecasts reflect assumptions around foundry yield improvement, export control enforcement consistency, and energy efficiency regulatory tightening. Material deviation in CoWoS capacity expansion, MIIT domestic certification timelines, or hyperscaler capex reduction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Coprocessor Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
France Data Center Processor Market