
 Europe MPU Market | 2026-2036
Europe MPU Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MPU Market Insights
The gap between premium automotive-grade MPUs and commodity consumer-tier processors is realigning procurement strategies across European supply chains. STMicroelectronics NV leverages its Grenoble R&D base and captive fabs to dominate automotive-embedded processor supply. Intel Corporation competes through its planned Magdeburg foundry complex, anchoring x86 manufacturing capacity inside the EU regulatory perimeter. Nvidia differentiates via AI-training and inference silicon for European automotive and data center customers.
A microprocessor unit (MPU) is an integrated semiconductor device containing a central processing core, memory management unit, and system bus interfaces fabricated on silicon wafers using sub-7nm to 28nm process nodes, designed to execute sequential instruction sets for computing tasks in electronic systems. ARM-based application processors lead European automotive electronics adoption due to power-performance ratios suited to electric vehicle powertrain controllers. RISC-V technology represents the fastest-expanding architecture as Continental and Bosch-affiliated design houses pursue instruction-set autonomy from licensed IP. Microcontrollers remain the mature volume pool across industrial automation, though margin concentrates in automotive-grade application processors with ASIL-D safety certification.
The EU Chips Act, REACH substance restrictions, and CE marking under the Radio Equipment Directive shape MPU material sourcing, packaging chemistry, and market access across the European Economic Area. ECHA scrutiny of fluorinated gases in etching processes is forcing foundries to qualify alternative chemistries in Dresden and Leuven pilot lines. Stakeholders must monitor how the EU AI Act's risk-classification framework redefines processor validation requirements for autonomous systems before committing to long-term architecture roadmaps.
Market Dynamics
Automotive electrification is restructuring European MPU procurement, as powertrain controllers and ADAS modules displace legacy engine-management units with multi-core application processors requiring ASIL-D certification. Tier-1 suppliers now specify silicon at vehicle program inception, compressing traditional component-selection timelines.
Growth Catalysts
- EU Chips Act capital subsidies:German and French foundry investments are accelerating domestic 28nm to sub-7nm capacity, reducing import dependency for automotive-grade wafers.
- ADAS penetration:Level-2 and Level-3 autonomous driving mandates from KBA and EU type-approval bodies are mandating redundant processor architectures in new vehicle platforms.
- RISC-V ecosystem maturation:Open-source instruction-set architectures are attracting Bosch and Continental design centers seeking IP autonomy from ARM licensing structures.
Market Restraints
- Fluorinated gas chemistry constraints:ECHA scrutiny of etching gases under REACH is forcing Dresden and Leuven pilot lines to qualify alternative chemistries, extending process development cycles.
- Advanced packaging substrate shortage:Ajinomoto Build-up Film and glass-core substrate supply concentrates in East Asian suppliers, creating bottlenecks for European automotive module producers.
- Neon and palladium supply concentration:Ukrainian neon purification and Russian palladium extraction disruptions have exposed lithography laser and plating chemistry vulnerabilities.
Strategic Opportunities
- Eastern European module assembly expansion:Romania and Poland are attracting automotive electronics manufacturing investments due to skilled labor pools and EU structural fund access.
- Edge AI inference at vehicle level:Transformer-based neural networks for occupancy monitoring and predictive maintenance are creating demand for INT8-optimized NPUs in cabin electronics.
- CE marking under Radio Equipment Directive:Harmonized cybersecurity requirements are enabling modular certification approaches that reduce time-to-market for connected vehicle platforms.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certified architects and verification specialists command premium compensation, constraining program staffing at Continental and Valeo development centers.
- Legacy vehicle network integration:CAN-FD and Ethernet backbone coexistence demands gateway processors with heterogeneous protocol support, complicating software stack validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MPU Market |
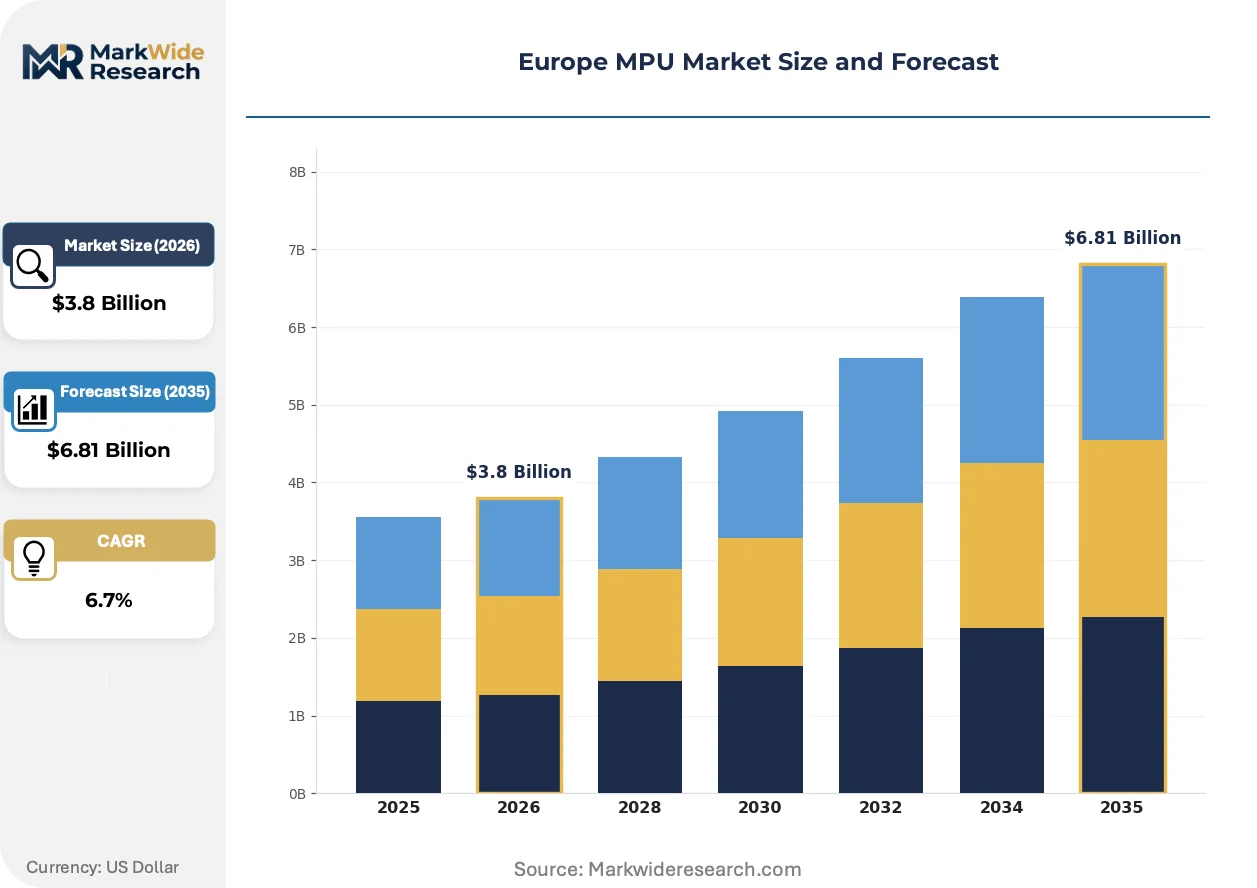
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Embedded Processors, Application Processors Technology: ARM, x86, RISC-V, MIPS Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers |
| Companies Covered | STMicroelectronics NV, Intel Corporation, SK Hynix Inc, Nvidia, Qualcomm Technologies, Renesas Electronics Corporation, Micron Technology, TSMC, Samsung Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MPU Market Trends and Innovations
Chiplets and disaggregated die architectures are displacing monolithic SoC designs across European automotive electronics, enabling mixed-node integration that balances cost and performance for domain controllers.
Chiplet-based multi-die packaging is overtaking traditional monolithic silicon for zonal vehicle architectures. Continental and ZF Friedrichshafen are specifying UCIe-based interconnects for 2027 platform generations. This modularity is overtaking single-vendor SoC lock-in, allowing OEMs to source compute, memory, and I/O dies from separate suppliers.
REACH substance restrictions on PFAS in semiconductor manufacturing are forcing wet-chemistry substitutions at STMicroelectronics' Crolles and Agrate fabs. The F-Gas Regulation's phasedown of fluorinated etchants is accelerating dry-etch process development for high-aspect-ratio memory structures. Automotive-grade MPU packaging is most affected, with mold compound reformulation timelines extending qualification cycles by 8-12 months.
Long-term supply agreements with prepayment structures are displacing spot-market wafer purchasing among German automotive OEMs. BMW and Mercedes-Benz procurement divisions are locking 2026-2029 capacity at GlobalFoundries Dresden and Intel Magdeburg through take-or-pay contracts. This shift is most visible in powertrain and chassis domains, where dual-sourcing requirements demand secured second-source capacity.
Europe MPU Market Segmentation
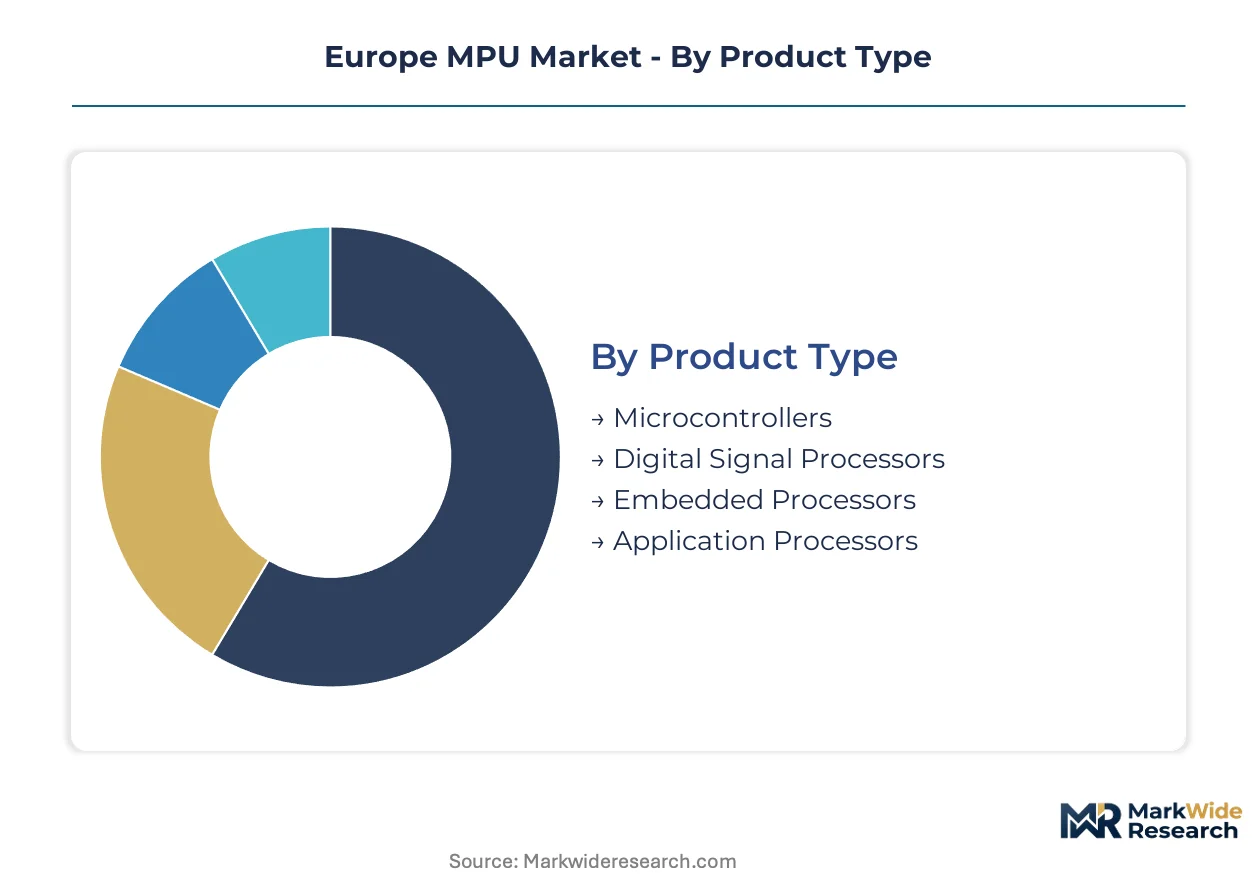
Processor architecture selection in European automotive and industrial systems hinges on power budgets, safety certification tiers, and software ecosystem maturity. Segmentation reveals where ARM licensing premiums, x86 legacy investments, and RISC-V autonomy strategies compete for design wins across German OEM supply chains.
Product Type:
Silicon complexity and software stack requirements separate commodity controllers from high-performance compute engines in European procurement specifications.
- Application Processors:Multi-core SoCs with integrated GPUs and neural processing units execute infotainment, ADAS fusion, and cockpit domain workloads. German premium OEMs now specify these at vehicle program inception for zonal E/E architectures, compressing traditional 18-month component-selection cycles into 8-month windows.
- Microcontrollers:Single to dual-core deterministic processors with embedded flash memory manage real-time control loops in powertrain and chassis subsystems. France's aerospace-electronics cluster and Germany's automotive corridor absorb the highest volumes, though margin concentrates in automotive-grade variants with ASIL-D certification.
- Embedded Processors:Network-attached compute modules for industrial gateways and edge servers.
- Digital Signal Processors:Specialized arithmetic units for sensor fusion and audio processing in cabin electronics.
Microcontrollers lead on scale; Application Processors lead on momentum.
Technology:
Instruction-set licensing economics and ecosystem lock-in determine procurement flexibility across Continental and Bosch design centers.
- ARM:Cortex-A and Cortex-R cores dominate European automotive electronics through power-performance ratios optimized for electric vehicle thermal constraints. BMW, Mercedes-Benz, and Volkswagen Group procurement divisions have standardized on ARM-based domain controllers, creating volume concentration that sustains premium licensing costs.
- RISC-V:Open-source instruction-set architectures enable Bosch, Continental, and ZF-affiliated design houses to pursue IP autonomy from ARM's per-unit royalty structure. French and German engineering centers are expanding RISC-V verification teams fastest, though production silicon remains 2-3 years behind ARM maturity.
- x86:Intel's planned Magdeburg foundry anchors legacy enterprise and emerging automotive edge compute demand.
- MIPS:Niche presence in legacy networking equipment and industrial control systems.
ARM commands current procurement volume; RISC-V climbs the fastest.
Application:
Functional safety requirements and environmental qualification tiers create distinct qualification pathways for each vertical.
- Automotive Electronics:Powertrain controllers, ADAS modules, and cockpit systems demand AEC-Q100 qualification and ISO 26262 safety ratings. German KBA type-approval mandates for Level-2 autonomy are accelerating redundant processor architectures, with dual-core lockstep configurations becoming baseline for 2027 vehicle platforms.
- Industrial Automation:PLC controllers, motion systems, and robotics drives prioritize deterministic latency over peak throughput. Siemens and ABB procurement specifications favor extended temperature range MPUs with 10-15 year supply guarantees.
- Consumer Electronics:Low-margin tablets and smart home devices with minimal European manufacturing presence.
- Telecommunications:Baseband processing and edge infrastructure for 5G network densification.
Automotive Electronics dominates margin capture; Industrial Automation sustains longest program lifecycles.
End User:
Procurement authority and technical specification control vary sharply across the supply chain hierarchy.
- Tier-1 Suppliers:Continental, Bosch, and ZF Friedrichshafen now specify silicon architectures at vehicle program inception, shifting influence from OEM component divisions. These suppliers aggregate demand across multiple OEM customers, achieving volume pricing that individual manufacturers cannot match.
- OEMs:BMW and Mercedes-Benz retain direct procurement for powertrain and chassis domains where dual-sourcing requirements demand secured second-source capacity. Their procurement divisions are locking 2026-2029 foundry capacity through take-or-pay contracts with GlobalFoundries Dresden and Intel Magdeburg.
- Distributors:Arrow Electronics and Avnet channel mid-volume industrial and aftermarket demand.
- Aftermarket Providers:Replacement module suppliers serving vehicle repair networks.
Tier-1 Suppliers concentrate specification authority; OEMs retain direct capacity contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized semiconductor engineering talent concentrates in Grenoble, Dresden, and Eindhoven, anchoring European MPU design and fabrication capabilities. This workforce distribution shapes where foundry investments cluster and which national subsidy programs gain traction.
Germany
Automotive OEM procurement of ASIL-D certified application processors for ADAS and zonal architectures drives demand concentration. The KBA mandates Level-2 autonomy compliance for new vehicle platforms from 2026. Magdeburg and Dresden host Intel and GlobalFoundries foundry complexes securing 2026-2029 wafer capacity through take-or-pay contracts with BMW and Mercedes-Benz procurement divisions.
France
Aerospace-electronics clusters in Toulouse and Paris-Saclay absorb embedded processors for avionics and satellite systems. ANSM and DGAC certification requirements extend qualification timelines for safety-critical silicon. STMicroelectronics leverages its Grenoble R&D base and Crolles captive fab to supply automotive-grade MPUs across the Rhine-Alpes corridor.
Netherlands
ASML lithography equipment dominance creates upstream leverage over sub-7nm process development across the Eindhoven-Randstad axis. REACH and F-Gas Regulation compliance costs concentrate at NXP Semiconductors' Nijmegen design centers. The country's central logistics position enables just-in-time substrate delivery to German automotive module assemblers.
Italy
Industrial automation demand from Emilia-Romagna machinery manufacturers sustains microcontroller volumes with 10-15 year supply guarantees. STMicroelectronics operates captive fabrication at Agrate Brianza serving PLC and motion control OEMs. CE marking under the Radio Equipment Directive shapes cybersecurity validation for connected factory gateways.
United Kingdom
Fabless design houses in Cambridge and Bristol pursue RISC-V architectures for automotive edge compute. The UK Semiconductor Advisory Panel coordinates national strategy without matching continental subsidy scales. ARM's Cambridge headquarters maintains licensing influence over European OEM processor specifications despite SoftBank ownership.
Europe MPU Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in European MPU supply. Foundry operators bearing multi-billion euro facility investments confront fabless specialists outsourcing fabrication to TSMC and GlobalFoundries. Three archetypes dominate: integrated device manufacturers with captive fabs, fabless application processor designers, and pure-play foundry operators. Competitive moves concentrate on long-term capacity contracting and architecture licensing rather than price competition.
Among integrated device manufacturers with European manufacturing presence, STMicroelectronics NV anchors automotive-embedded supply through its Grenoble R&D base and French-Italian fab network. Intel Corporation exemplifies the capital-heavy foundry entrant, with its planned Magdeburg complex anchoring x86 capacity inside the EU regulatory perimeter. Nvidia occupies a position within the AI-training and inference silicon tier, supplying European automotive and data center customers. These three represent distinct strategic postures: captive fab integration, greenfield foundry investment, and architecture-specific acceleration.
| Leading Market Players |
|---|
| STMicroelectronics NV |
| Intel Corporation |
| SK Hynix Inc |
| Nvidia |
| Qualcomm Technologies |
| Renesas Electronics Corporation |
| Micron Technology |
| TSMC |
| Samsung Technologies |
| Others |
Pricing and Supply Chain Analysis
Wafer fabrication costs at sub-7nm nodes cascade through automotive-grade MPU procurement tiers, with EUV lithography energy intensity and fluorinated gas chemistry constraints feeding into premium pricing for ASIL-D certified silicon at German OEM component divisions.
Pricing Analysis
Die-level IP licensing and foundry service bundling separate ARM royalty-inclusive contracts from RISC-V unlicensed procurement models. Price differentiation stems from ASIL-D safety certification tier and volume scale under long-term take-or-pay agreements. Cost compression in commodity microcontrollers is intensifying because Tier-1 suppliers aggregate demand across multiple OEM customers. Aftermarket distributors exhibit highest price sensitivity; powertrain domain controllers at BMW and Mercedes-Benz procurement divisions show lowest.
Supply Chain Analysis
Neon gas purification for lithography lasers rests on Ukrainian and Russian supply concentration disrupted by regional conflict. Ajinomoto Build-up Film and glass-core substrates draw from Japanese and Taiwanese specialty material producers. Single-source vulnerability concentrates in advanced packaging substrate supply. Distribution runs through Arrow Electronics and Avnet channeling mid-volume industrial demand alongside direct OEM contracting for automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe MPU Market functions as a stable compounder anchored by automotive electrification mandates from KBA and EU type-approval bodies that institutionalize processor demand across multi-year vehicle platform cycles.
For Market Incumbents: Acquire functional safety engineering talent pools to address ISO 26262 certified architect scarcity constraining Continental and Valeo development centers. Deepen backward integration into captive 28nm to sub-7nm fabrication capacity at Dresden and Magdeburg to reduce import dependency exposure. Lock second-source wafer supply through prepayment structures before alternative foundry investments mature.
For New Entrants and Emerging Players: RISC-V core verification expertise offers entry into Bosch and Continental design center procurement specifications seeking IP autonomy from ARM licensing structures. White-space concentrates in edge AI inference NPUs for cabin electronics transformer networks. Pursue modular CE marking certification under the Radio Equipment Directive to reduce connected vehicle platform time-to-market.
For Investors and Strategic Acquirers: Consolidation pressure builds where Tier-1 supplier specification authority concentrates procurement influence away from fragmented OEM component divisions. Five-to-ten year viability favors fabless designers with secured foundry capacity allocation over capital-heavy greenfield fab entrants. Watch RISC-V production silicon maturity as inflection indicator for architecture licensing economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Chips Act Capacity Subsidy Capture | Intel Magdeburg and GlobalFoundries Dresden secure automotive-grade wafer supply inside EU regulatory perimeter. |
| ASIL-D Safety Certification Investment | STMicroelectronics Crolles and Agrate fabs extend mold compound qualification cycles for automotive MPU packaging. |
| RISC-V Architecture Licensing Pivot | Bosch and Continental design centers reduce per-unit royalty exposure through open-source instruction-set adoption. |
| Long-Term Take-or-Pay Contracting | BMW and Mercedes-Benz procurement divisions lock 2026-2029 foundry capacity reducing spot-market price volatility. |
| Chiplet-Based Multi-Die Packaging Shift | Continental and ZF Friedrichshafen specify UCIe interconnects enabling mixed-node sourcing for zonal domain controllers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and semiconductor distribution channel heads. Secondary validation drew from EU Chips Act implementation documents, ECHA REACH substance restriction filings, KBA type-approval regulatory updates, and SEC semiconductor manufacturer disclosures. Bottom-up die-level demand modeling and top-down automotive production forecasts were cross-referenced for triangulation.
Segment-weighting applied processor architecture, application vertical, and end-user procurement authority as core dimensions across the projection horizon. CAGRs were derived from vehicle platform cycle timing, foundry capacity ramp schedules, and regulatory mandate compliance deadlines. Forecast inputs incorporated ADAS penetration curves, RISC-V ecosystem maturation timelines, and fluorinated gas chemistry substitution progress at Dresden and Leuven pilot lines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act risk-classification implementation, Ukrainian neon supply chain restoration, and Intel Magdeburg construction schedule adherence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Connecting Chiplets Market