
 Global Automotive Self-Driving Chip Market | 2026-2036
Global Automotive Self-Driving Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Self-Driving Chip Market Analysis
Taiwanese foundry capacity allocation is rebalancing as automotive-grade silicon commands priority wafer starts. NVIDIA Corporation leverages its CUDA software ecosystem to lock in OEM design cycles. Mobileye sustains integrated camera-processor bundles that reduce Tier-1 integration burden. Qualcomm Incorporated anchors next-generation cockpit-autonomy convergence through its Snapdragon Ride platform.
Automotive self-driving chips are semiconductor devices engineered to process sensor fusion data, execute path-planning algorithms, and meet ASIL-D functional safety thresholds under thermal and vibration stress. Their primary purpose is to replace human perception and decision-making in controlled driving environments. Processing units currently capture the deepest margin pools due to complexity barriers in neural acceleration architectures. Machine learning technology segments are expanding fastest as transformer-based perception models displace convolutional networks. Sensor chips remain volume-heavy but price-commoditized across lidar and radar front-ends.
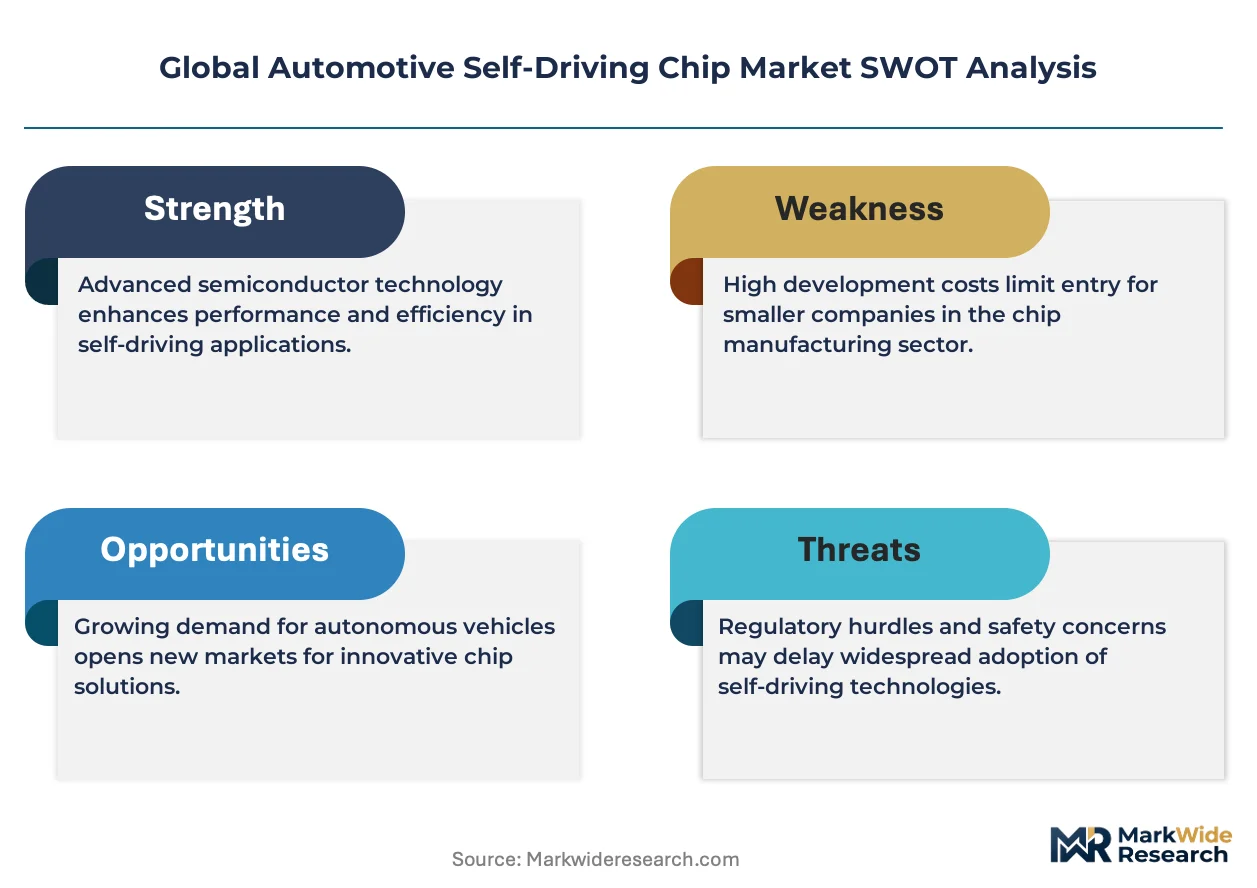
The U.S. NHTSA, the EU AI Act, and China's MIIT GB standards collectively dictate chip validation protocols, data governance, and cybersecurity baselines for autonomous systems. These frameworks force silicon vendors to maintain parallel certification tracks across jurisdictions, raising fixed compliance costs. Stakeholders must monitor divergence between EU algorithmic transparency mandates and U.S. performance-based safety thresholds when allocating R&D budgets.
Market Dynamics
Taiwanese foundry capacity reallocation toward automotive-grade silicon is compressing lead times for advanced node allocation while forcing fabless designers into multi-source qualification programs.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Tier-1 suppliers accelerate chip procurement to meet 2027 compliance deadlines for autonomous system logging and explainability requirements.
- Transformer-based perception architectures:Neural network topology shifts from convolutional to attention-based models, demanding tensor-core density that legacy automotive silicon cannot deliver.
- China's MIIT GB standard proving grounds:Designated autonomous vehicle test zones in Beijing, Shanghai, and Chongqing validate chip performance under domestic traffic conditions, creating localized demand pull.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and InFO capacity constraints at leading OSATs bottleneck high-bandwidth memory integration for L4 compute platforms.
- ISO 26262 ASIL-D certification timelines:Functional safety validation cycles extend 18-24 months, freezing silicon architectures before tape-out and eroding competitive windows.
- Silicon carbide power stage substitution:Centralized zonal architectures reduce discrete compute node counts versus distributed ECU topologies, compressing unit volumes per vehicle.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Subsidized domestic manufacturing incentives attract chip packaging and testing investments for export-oriented autonomous component production.
- Cockpit-autonomy convergence:Unified SoC architectures consolidate infotainment and ADAS pipelines, eliminating redundant sensor interfaces and reducing BOM complexity for OEMs.
- Edge-cloud collaborative inference:Split-model execution between vehicle-resident NPU and 5G network edge enables lighter onboard silicon footprints for highway-only autonomy scenarios.
Industry Challenges
- Functional safety verification engineer scarcity:ASIL-D competent verification specialists command 40% salary premiums, constraining validation throughput at mid-tier semiconductor houses.
- Legacy CAN-FD to Ethernet-TSN migration:Mixed-signal PHY integration complexity delays platform consolidation roadmaps for established Tier-1 module suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Self-Driving Chip Market |
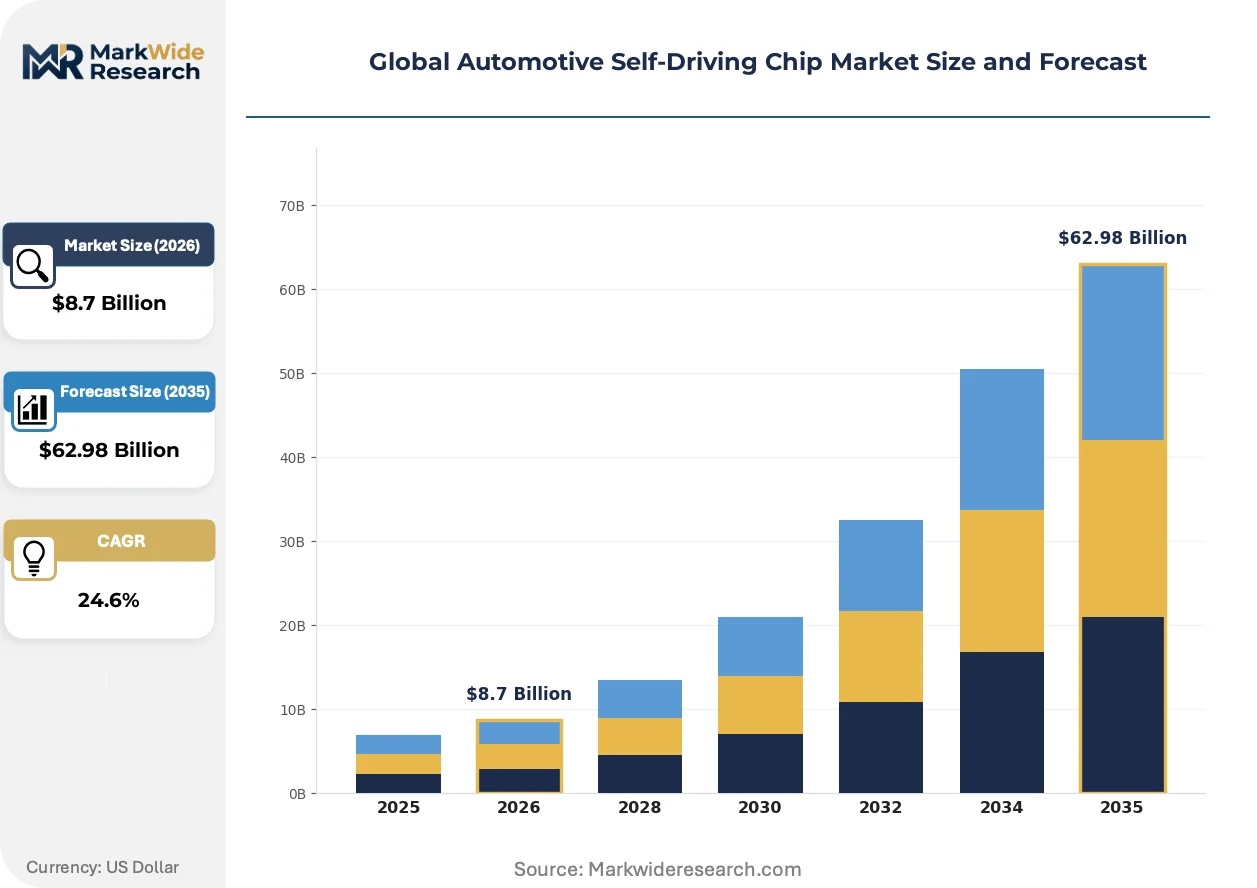
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Chips, Processing Units, Connectivity Modules, Power Management ICs Technology: Computer Vision, Lidar, Radar, Machine Learning Application: Passenger Vehicles, Commercial Trucks, Robotics, Drones End User: OEMs, Tier-1 Suppliers, Fleet Operators, Research Institutions |
| Companies Covered | NVIDIA Corporation, Mobileye, Intel Corporation, Qualcomm Incorporated, Advanced Micro Devices, Infineon Technologies AG, Renesas Electronics Corporation, Samsung Electronics Co., Ltd., Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Self-Driving Chip Market Emerging Trajectories
Neuromorphic and photonic compute fabrics are challenging von Neumann architectures for perception-heavy autonomous workloads, while regulatory divergence forces parallel silicon tape-outs.
Transformer-based neural accelerators are electrifying the inference pipeline for multi-modal sensor fusion. European premium OEMs now specify 500+ TOPS dense compute as baseline for urban L3 functionality. This architectural shift is electrifying the competitive landscape, relegating fixed-function CNN engines to entry-level lane-keeping applications.
REACH substance restrictions on halogenated flame retardants in PCB substrates are forcing laminate material transitions. German KBA type-approval authorities now require documentation of alternative flame-suppression chemistries for ECU housings. High-layer-count substrate vendors serving Stuttgart and Munich automotive clusters face accelerated qualification cycles to maintain supply continuity.
Fleet operators in the United States now specify chip longevity guarantees as primary selection criteria over nominal TOPS benchmarks. Long-haul trucking procurement contracts demand 15-year silicon supply assurances with pin-compatible successor migration paths. This durability-first evaluation framework is most pronounced among Arizona and Texas-based autonomous freight deployers building dedicated transfer hub networks.
Global Automotive Self-Driving Chip Market Segmentation
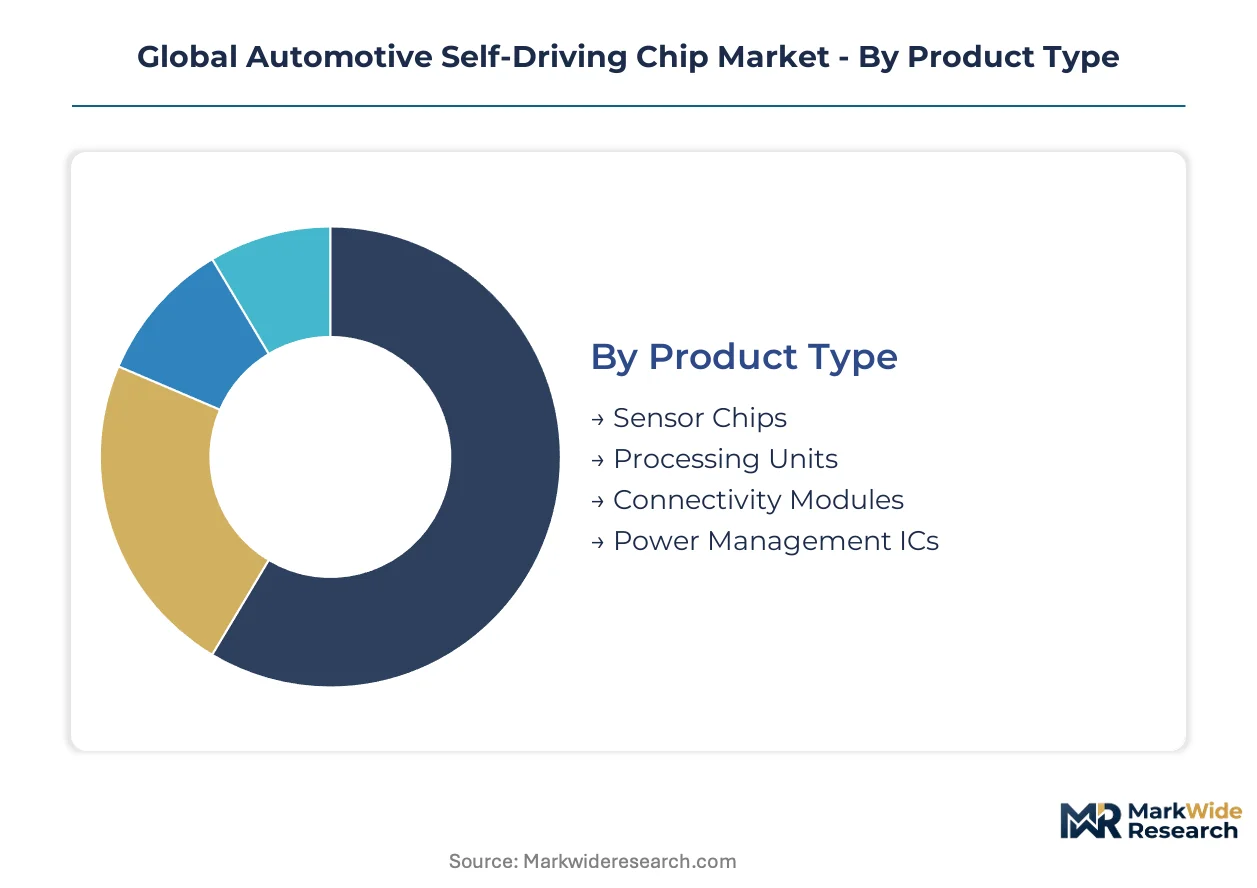
Automotive self-driving chips segment across four distinct dimensions that shape procurement patterns and technical roadmaps. Product type determines margin capture and foundry allocation priority. Technology orientation dictates neural architecture requirements and sensor fusion complexity.
Product Type:
Standalone processing units command the deepest integration cycles, while sensor chips and power management ICs embed directly into module assemblies.
- Sensor Chips:CMOS image sensors, lidar receivers, and radar transceivers convert optical and electromagnetic inputs into digital signals. Demand clusters in Stuttgart and Detroit as premium OEMs specify 8MP+ camera resolutions for urban L3 perception stacks. REACH substance restrictions on halogenated flame retardants complicate PCB substrate qualification for these front-end components.
- Processing Units:Neural processing units and system-on-chip architectures execute sensor fusion algorithms under ASIL-D constraints. NVIDIA and Mobileye design cycles dominate procurement conversations among German and U.S. OEMs seeking 500+ TOPS dense compute for transformer-based perception models.
- Connectivity Modules:V2X transceivers and 5G modems enable over-the-air updates and edge-cloud collaborative inference. China's MIIT GB standards mandate domestic certification for these modules in Beijing and Shanghai proving grounds.
- Power Management ICs:Voltage regulators and battery management circuits condition supply rails for noise-sensitive compute fabrics. Silicon carbide power stage adoption in centralized zonal architectures reduces discrete node counts per vehicle.
Processing units lead volumes today; sensor chips are gaining share fastest as camera-processor bundles displace discrete component sourcing.
Technology:
Cost tiers separate legacy convolutional approaches from attention-based architectures demanding tensor-core density.
- Computer Vision:Edge-detection and semantic segmentation pipelines process camera feeds for lane-keeping and traffic-sign recognition. Entry-level ADAS systems in India and Brazil still specify these fixed-function engines for cost-constrained vehicle platforms.
- Lidar:Time-of-flight and frequency-modulated continuous-wave sensors generate dense 3D point clouds for obstacle detection. Austin and Phoenix fleet operators specify chip longevity guarantees exceeding 15 years for long-haul autonomous freight deployments.
- Radar:77GHz and 4D imaging radar chips penetrate weather and darkness where optical sensors fail. Continental and Bosch module designs integrate these front-ends with processing backbones in Ingolstadt and Wolfsburg supply clusters.
- Machine Learning:Transformer-based neural accelerators displace CNN engines for multi-modal sensor fusion. EU AI Act algorithmic transparency mandates accelerate procurement of these architectures to meet explainability logging requirements.
Computer vision anchors installed base; machine learning is climbing the fastest as OEMs retool for urban L3 functionality.
Application:
Volume concentration varies sharply between consumer-facing passenger platforms and commercial fleet specifications.
- Passenger Vehicles:Cockpit-autonomy convergence drives unified SoC architectures consolidating infotainment and ADAS pipelines. European premium OEMs in Munich and Stuttgart specify the most aggressive compute density requirements.
- Commercial Trucks:Hub-to-hub autonomous freight routes in Arizona and Texas prioritize chip durability and pin-compatible successor migration over nominal TOPS benchmarks. Procurement contracts demand 15-year silicon supply assurances.
- Robotics:Industrial and last-mile delivery platforms repurpose automotive-grade silicon for lower-speed controlled environments. Research institutions in Pittsburgh and Beijing validate chip performance under non-standard kinematic constraints.
- Drones:Weight-constrained aerial platforms drive demand for ultra-low-power inference engines. Applications remain experimental with limited regulatory sandbox approvals outside China's designated test zones.
Passenger vehicles dominate unit economics; commercial trucks show steepest expansion trajectory as fleet operators accelerate procurement of autonomous-capable platforms.
End User:
Customer type determines certification burden and design-in cycle length, with OEMs and Tier-1 suppliers representing opposing procurement philosophies.
- OEMs:Volkswagen, Ford, and BYD pursue direct silicon relationships to differentiate software-defined vehicle architectures. These buyers specify full-stack autonomy platforms and demand ISO 26262 ASIL-D documentation for entire compute subsystems.
- Tier-1 Suppliers:Bosch, Continental, and Denso aggregate chip procurement across multiple OEM programs to amortize validation costs. Mobileye's integrated camera-processor bundles reduce their integration burden for lane-keeping and highway pilot functions.
- Fleet Operators:Aurora, Waymo Via, and TuSimple specify chip longevity guarantees as primary selection criteria. Arizona and Texas-based autonomous freight deployers building dedicated transfer hub networks drive this durability-first evaluation framework.
- Research Institutions:Carnegie Mellon, Tsinghua University, and TU Munich access pre-production silicon for algorithm development. Their procurement volumes remain limited but influence architectural roadmaps through publication and talent pipelines.
Tier-1 suppliers lead procurement volumes today; fleet operators are expanding most quickly as commercial deployment timelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping foundry allocation as compliance-cost differentials between jurisdictions redirect automotive-grade silicon investment. Taiwan Semiconductor Manufacturing anchors advanced-node supply, while government subsidies in India and Germany pull packaging and testing capacity toward lower-cost certification environments.
United States
Arizona and Texas fleet operators specify 15-year chip longevity guarantees for autonomous freight hubs, prioritizing durability over nominal compute benchmarks. The NHTSA mandates cybersecurity baselines for autonomous systems, extending validation timelines. Phoenix hosts dedicated proving grounds where long-haul trucking deployers validate silicon under desert thermal stress.
China
Beijing, Shanghai, and Chongqing proving grounds validate chip performance under domestic traffic conditions, creating localized demand pull for domestic suppliers. The MIIT GB standards mandate domestic certification for V2X modules, forcing parallel silicon tape-outs. Yangtze River Delta clusters concentrate foundry and OSAT capacity for automotive-grade packaging.
Germany
Stuttgart and Munich OEMs specify 500+ TOPS dense compute for urban L3 functionality, driving premium-tier procurement. The KBA requires documentation of alternative flame-suppression chemistries for ECU housings under REACH restrictions. Bavarian automotive clusters face accelerated substrate qualification cycles to maintain supply continuity.
India
The PLI scheme for automotive electronics subsidizes domestic packaging and testing investments for export-oriented autonomous component production. BIS certification requirements create compliance barriers that favor established multinational assembly partners. Gujarat and Tamil Nadu industrial corridors attract chip testing facilities serving European and North American OEM programs.
Japan
METI standardization efforts align domestic semiconductor roadmaps with ISO 26262 ASIL-D thresholds, preserving quality premiums for Japanese suppliers. Kansai and Chubu manufacturing belts maintain legacy automotive module expertise while integrating neural accelerators into consolidated zonal architectures. Domestic OEMs prioritize functional safety documentation over raw compute specifications.
Global Automotive Self-Driving Chip Market Vendor Landscape
United States-based semiconductor designers anchor the premium compute tier; Taiwanese foundry specialists hold process technology leverage. The vendor base concentrates around three strategic archetypes: full-stack autonomy platform providers, integrated camera-processor bundle suppliers, and cockpit-convergence SoC architects. Competitive moves center on multi-source qualification programs and CUDA ecosystem lock-in strategies that extend design cycle capture.
Within the full-stack platform tier, NVIDIA Corporation exemplifies software-ecosystem dominance through CUDA-based design cycle retention. Mobileye occupies a position as the integrated camera-processor bundle archetype, reducing Tier-1 integration burdens for highway pilot functions. Qualcomm Incorporated anchors the cockpit-autonomy convergence vector through Snapdragon Ride platform consolidation of infotainment and ADAS pipelines.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Mobileye |
| Intel Corporation |
| Qualcomm Incorporated |
| Advanced Micro Devices |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| Samsung Electronics Co., Ltd. |
| Texas Instruments |
| Others |
Supply Flow & Price Mechanics
Fleet operators demanding 15-year silicon longevity guarantees in Arizona and Texas freight hubs force foundries into dedicated capacity reservation contracts, compressing margin flexibility for automotive-grade wafers and elevating pricing premiums for ASIL-D certified architectures.
Pricing Analysis
Direct-to-OEM discount structures dominate high-volume procurement for processing units, with NVIDIA and Mobileye commanding premium tiers through software-ecosystem lock-in while sensor chips trade on commodity spot dynamics. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified silicon from ASIL-B and non-automotive grades, with EU AI Act compliance documentation adding certification-driven premiums. Cost compression in entry-level computer vision chips is intensifying because Chinese domestic suppliers are flooding lane-keeping ADAS segments. Tier-1 suppliers exhibit highest price sensitivity due to amortization pressures across multiple OEM programs, whereas fleet operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Advanced packaging substrate supply rests on Taiwanese OSAT capacity for CoWoS and InFO integration, with Japanese specialty chemical producers anchoring photoresist and high-purity gas inputs for automotive-grade wafer fabrication. Taiwan, South Korea, and the United States concentrate foundry supply for neural processing units, drawing from silicon wafers, high-bandwidth memory stacks, and organic substrate laminates. Single-source vulnerability at leading-edge nodes creates chokepoint exposure when automotive demand spikes compete with AI accelerator allocations. Distribution runs through Tier-1 module suppliers who aggregate chip procurement across OEM programs, consolidating bargaining power upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Automotive Self-Driving Chip Market functions as a stable compounder anchored by regulatory mandates that mandate silicon refresh cycles across jurisdictions, ensuring replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Anticipate neuromorphic and photonic compute fabrics challenging von Neumann architectures for perception-heavy workloads by securing exclusive foundry allocation for automotive-grade nodes through multi-year offtake agreements. Defensive consolidation moves should prioritize backward integration into advanced packaging capabilities and accelerated ISO 26262 ASIL-D certification pipelines to freeze out mid-tier competitors.
For New Entrants and Emerging Players: Begin with India's PLI-subsidized packaging and testing corridors for export-oriented autonomous component production, where BIS certification barriers favor established multinational assembly partnerships but white-space exists in sensor fusion middleware. The most penetrable segment sits in robotics and last-mile delivery platforms repurposing automotive-grade silicon for lower-speed controlled environments, with go-to-market angles targeting Pittsburgh and Beijing research institutions for algorithm validation partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with neuromorphic compute specialists possessing automotive-qualified architectures and functional safety documentation capabilities. Long-term viability across the 5-10 year window favors acquisition targets with captive foundry relationships or exclusive OSAT partnerships rather than pure fabless designers exposed to allocation volatility. The specific signal to watch as inflection indicator is transformer-based neural accelerator procurement acceleration among European premium OEMs specifying 500+ TOPS dense compute baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Foundry Qualification | Taiwanese capacity rebalancing forces fabless designers into parallel silicon tape-outs across jurisdictions to secure supply continuity. |
| Cockpit-Autonomy SoC Convergence | Qualcomm's Snapdragon Ride platform consolidation eliminates redundant sensor interfaces and reduces BOM complexity for Munich and Stuttgart OEMs. |
| Functional Safety Certification Investment | ASIL-D validation cycles extending 18-24 months create competitive moats for incumbents with established verification engineer pipelines. |
| Edge-Cloud Collaborative Inference Deployment | Split-model execution between vehicle-resident NPU and 5G network edge enables lighter onboard silicon footprints for highway-only autonomy scenarios. |
| Substrate Material Transition Acceleration | German KBA type-approval authorities now require REACH-compliant alternative flame-suppression chemistries for ECU housings. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, foundry capacity planners, and functional safety verification specialists grounded this analysis, cross-referenced against SEC 10-K semiconductor disclosures, MIIT GB standard filings, EU AI Act regulatory texts, and IHS Markit vehicle production databases. Bottom-up unit economics triangulated against top-down market sizing across processing unit, sensor chip, and connectivity module categories.
Market value and volume trajectories across the projection horizon reflect segmented modeling by vehicle class, autonomy level, neural architecture type, and regional regulatory cluster, with CAGRs derived from installed base penetration curves and content-per-vehicle escalation paths. Key inputs included transformer-based perception model compute requirements, ISO 26262 certification timeline distributions, and foundry allocation priority shifts between automotive and datacenter demand.
Several conditions sit outside the modeled scope, including unannounced geopolitical trade restrictions, breakthroughs in quantum or biological computing architectures, and catastrophic supply chain disruptions at leading-edge nodes. Forecasts embed assumptions around regulatory timeline adherence and foundry capacity expansion schedules. A small set of named triggers warrants ongoing watch: EU AI Act enforcement severity, NHTSA cybersecurity rulemaking finalization, and Chinese domestic substitution acceleration in V2X module certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Application Processor Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
System on Chip (Soc) Market