
 Quantum Processing Units (QPU) Market | 2026-2036
Quantum Processing Units (QPU) Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Processing Units (QPU) Market Analytics
Superconducting niobium is pivoting toward higher-coherence alternatives as aluminum and tantalum compounds reshape qubit fabrication economics. IBM leverages extensive cryogenic infrastructure to sustain volume prototyping across its Quantum Network. Quantinuum anchors trapped-ion commercialization through integrated hardware-software stacks. Google dominates superconducting gate fidelity benchmarks with proprietary two-qubit gate designs.
A Quantum Processing Unit is a specialized computational device that manipulates quantum bits through superposition and entanglement to execute algorithms intractable for classical processors, typically operating at millikelvin temperatures in dilution refrigerators with coherence times measured in microseconds. Superconducting QPUs currently occupy the majority of installed base due to semiconductor fabrication compatibility, while photonic QPUs are attracting investment for room-temperature operation potential. Trapped Ion QPUs lead in gate fidelity metrics, though scaling beyond one thousand qubits remains technically demanding.
The US NIST post-quantum cryptography standards and the EU Chips Act quantum provisions together shape product roadmaps by mandating cryptographic migration timelines and subsidizing European fabrication capacity. China's MIIT quantum technology guidelines direct state-backed capital toward domestic superconducting and photonic platforms. Stakeholders must monitor regulatory fragmentation around export controls on cryogenic test equipment and quantum-specific software as these barriers increasingly determine market access rather than technical performance alone.
Market Dynamics
The superconducting-to-photonic platform transition is compressing cryogenic infrastructure requirements while fragmenting supply chains across dilution refrigerator manufacturers and room-temperature photonic component suppliers.
Growth Catalysts
- NIST Post-Quantum Cryptography Standards:The US cryptographic migration timeline accelerates enterprise procurement of quantum-safe infrastructure. Federal agencies must inventory vulnerable systems by 2025.
- Pharmaceutical molecular simulation:Drug developers deploy QPUs for protein folding and reaction pathway modeling. Roche and Merck have established dedicated quantum chemistry divisions.
- German Quantum Computing Initiative:Berlin directs €2 billion toward domestic fabrication capacity. Fraunhofer institutes anchor public-private consortia for trapped-ion scaling.
Market Restraints
- Helium-3 supply concentration:Russian and Qatari sources dominate isotope production for dilution refrigerators. Export licensing delays extend equipment lead times to 18 months.
- Cryogenic test equipment controls:US Bureau of Industry and Security restricts blue-laser interferometer exports. Chinese foundries face qualification barriers for superconducting qubit metrology.
- Coherence time ceilings:Superconducting qubits remain bounded by two-level system defects at material interfaces. Tantalum substitution yields only incremental gains.
Strategic Opportunities
- India semiconductor mission:The country's PLI scheme now includes quantum component fabrication. Bengaluru and Hyderabad clusters attract photonic foundry investment.
- Edge quantum sensing convergence:Atomic clock and gravimeter applications merge with QPU architectures. Defense contractors seek compact trapped-ion modules for navigation denial environments.
- EU Chips Act quantum provisions:Subsidized European fabrication capacity lowers barriers for fabless QPU designers. IMEC expands cleanroom access for superconducting process development.
Industry Challenges
- Cryogenic engineering talent scarcity:Millikelvin system design requires hybrid physics and mechanical engineering skills. University programs produce fewer than 200 qualified graduates annually across North America and Europe.
- Legacy HPC integration complexity:Financial services firms struggle to partition workloads between classical clusters and quantum accelerators. API standardization remains incomplete.
- Calibration protocol fragmentation:Each hardware platform demands proprietary gate characterization routines. Software vendors must maintain parallel validation stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Processing Units (QPU) Market |
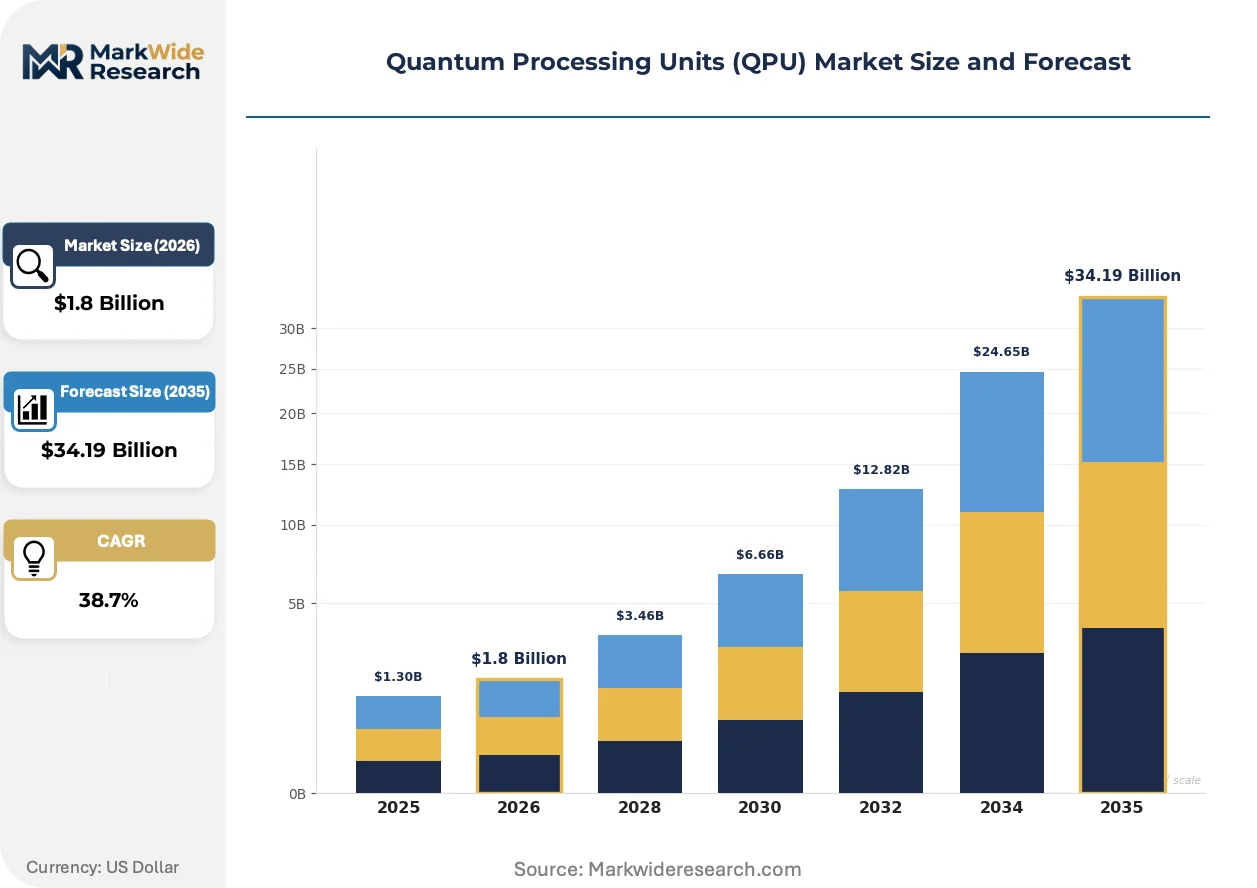
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $34.19 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superconducting QPUs, Trapped Ion QPUs, Photonic QPUs, Topological QPUs End User: Academics, Enterprises, Labs, Government Agencies Application: Cryptography, Drug Discovery, Optimization, Machine Learning Technology: Quantum Superposition, Entanglement, Quantum Algorithms, Quantum Error Correction |
| Companies Covered | D-Wave Systems, Quantinuum, IBM, Amazon Web Services, Microsoft, Google, Rigetti Computing, Infleqtion, IonQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Processing Units (QPU) Market Evolving Landscape
Photonic interconnect architectures are dissolving the thermal bottleneck that has constrained superconducting QPU scaling. This shift enables modular designs that separate quantum processing from classical control electronics.
Silicon nitride waveguides are integrating single-photon sources with CMOS-compatible foundry processes. PsiQuantum and Xanadu have committed to 300mm wafer production at GlobalFoundries facilities. This integration is compressing the cost curve for photonic QPUs toward parity with superconducting alternatives by the end of the decade.
The EU AI Act's high-risk system classification is extending to quantum-enhanced machine learning deployments. Developers must document training data provenance and algorithmic interpretability. Pharmaceutical and financial services adopters in Germany and France are restructuring procurement contracts to allocate compliance liability between hardware vendors and end-users.
Buyers are consolidating vendor relationships around full-stack providers rather than assembling discrete hardware, software, and cloud access components. Research institutions and national laboratories now issue single-source contracts for integrated quantum computing services. This concentration is most visible in the United States, where the Department of Energy's national quantum centers negotiate enterprise-wide licensing with Quantinuum and IBM rather than procuring bare-metal QPUs.
Quantum Processing Units (QPU) Market Segmentation
QPU procurement cycles diverge sharply across deployment contexts. Academic buyers prioritize gate fidelity benchmarks for fundamental research, while enterprise adopters demand API-ready cloud access with classical integration layers.
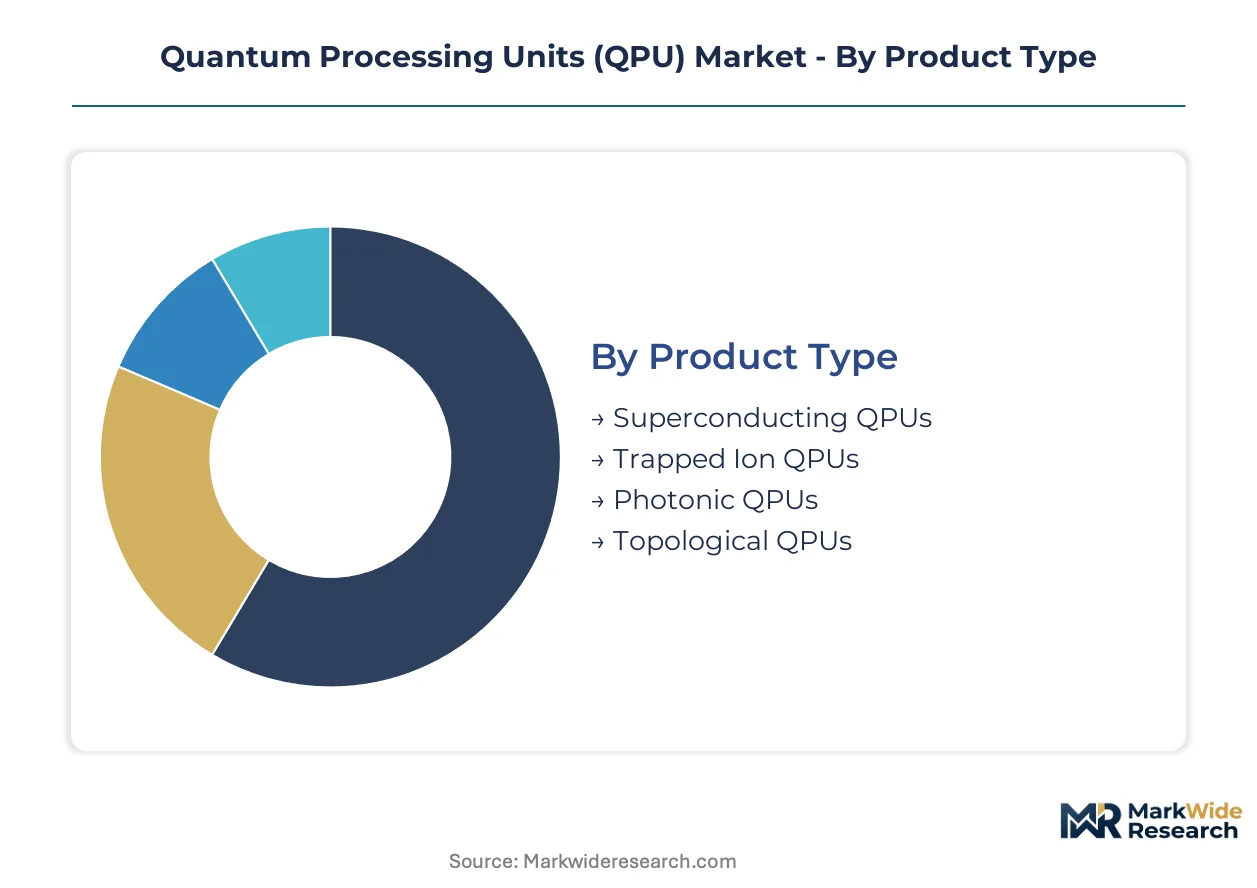
Product Type:
Upgrade trajectories favor platforms with semiconductor fabrication compatibility, though cryogenic infrastructure requirements are compressing as room-temperature alternatives mature.
- Superconducting QPUs:Niobium and aluminum-based transmon qubits operate at millikelvin temperatures in dilution refrigerators. Demand concentrates among US national laboratories and IBM's Quantum Network partners, constrained by helium-3 supply bottlenecks from Russian and Qatari sources.
- Trapped Ion QPUs:Ytterbium and calcium ion chains achieve highest gate fidelity metrics through laser-based manipulation. German Fraunhofer institutes and Quantinuum's commercial deployments anchor European demand, driven by the EU Chips Act quantum fabrication subsidies.
- Photonic QPUs:Silicon nitride waveguides integrate single-photon sources with CMOS-compatible foundry processes at GlobalFoundries facilities.
- Topological QPUs:Microsoft Azure Quantum and Danish research consortia pursue Majorana zero modes for intrinsically error-protected qubits.
Volume placements concentrate in superconducting platforms; the faster expansion belongs to photonic architectures.
End User:
Cost tier stratification separates bare-metal procurement from managed cloud services, with pricing spreading across capital expenditure, subscription, and pay-per-shot models.
- Academics:University physics departments and national laboratories secure QPUs through NSF, DOE, and Horizon Europe instrumentation grants. MIT, TU Munich, and Tsinghua operate on-premise systems for qubit coherence research.
- Enterprises:Roche and Merck maintain dedicated quantum chemistry divisions for molecular simulation workloads. Financial services firms at Goldman Sachs and JPMorgan Chase partition optimization problems between classical clusters and quantum accelerators.
- Labs:US Department of Energy national quantum centers negotiate enterprise-wide licensing with full-stack providers rather than procuring discrete hardware.
- Government Agencies:NIST post-quantum cryptography standards mandate federal inventory of vulnerable systems by 2025, accelerating procurement timelines.
Enterprise subscriptions generate recurring revenue concentration; government agency deployments are climbing the fastest.
Application:
Customer type specialization fragments software stacks, with pharmaceutical buyers demanding molecular simulation SDKs while defense contractors require compact navigation modules.
- Cryptography:NIST post-quantum migration timelines and China's MIIT quantum technology guidelines drive hardware procurement for cryptographic agility testing.
- Drug Discovery:Protein folding and reaction pathway modeling attract Roche, Merck, and dedicated biotech quantum chemistry divisions. The EU AI Act's high-risk system classification extends to quantum-enhanced molecular property prediction.
- Optimization:Portfolio optimization and supply chain routing problems dominate financial services and logistics adopters.
- Machine Learning:Quantum kernel methods and variational quantum circuits attract AI-first enterprises, though training data provenance requirements complicate procurement.
Drug discovery commands premium pricing; machine learning integration is gaining share fastest.
Technology:
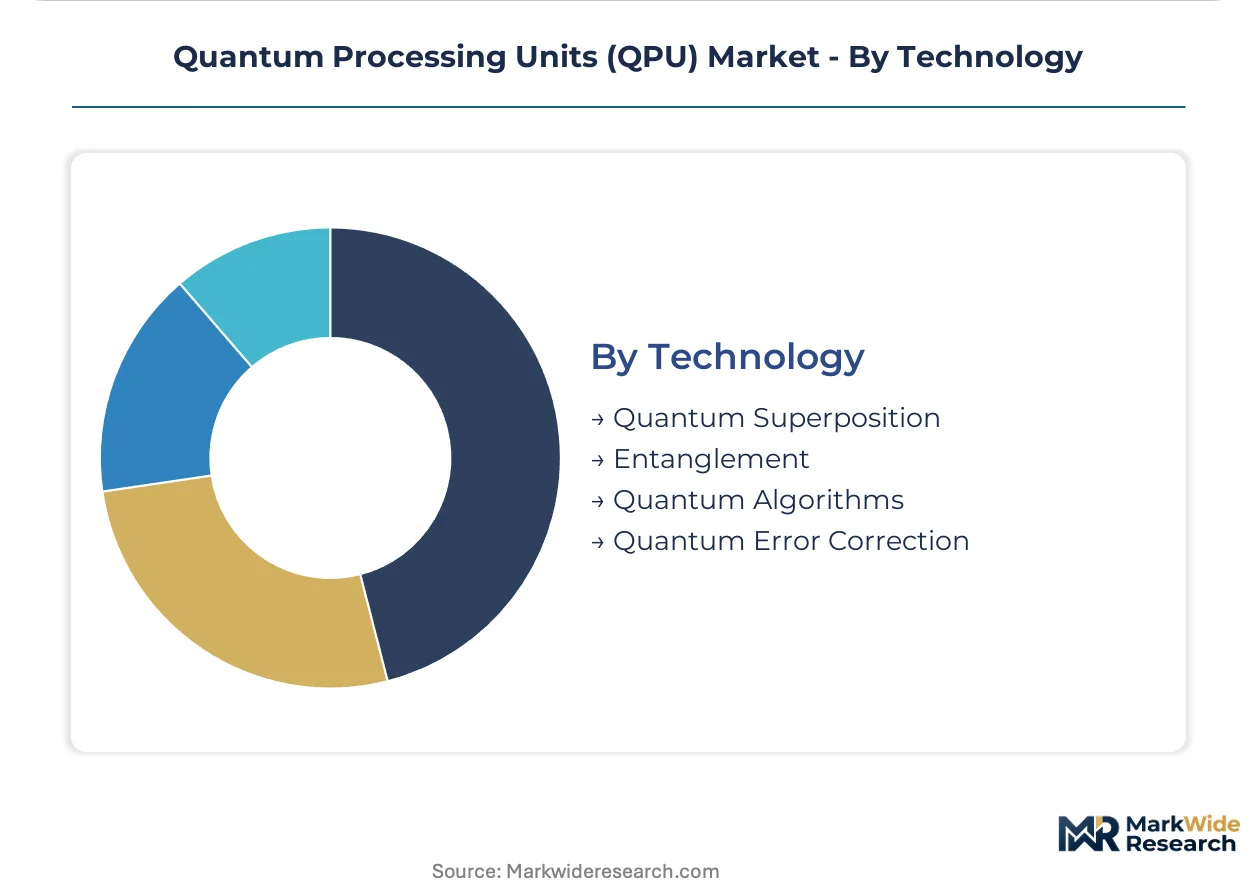
Maturity gradients separate foundational physics from engineering implementation, with error correction demanding the longest development horizons.
- Quantum Superposition:State preparation and readout fidelity determine effective qubit counts for algorithm execution.
- Entanglement:Two-qubit gate fidelity benchmarks differentiate hardware platforms, with Google dominating superconducting designs.
- Quantum Algorithms:Variational quantum eigensolvers and quantum approximate optimization algorithms require hardware-agnostic compilation layers.
- Quantum Error Correction:Surface code implementations and logical qubit encoding demand physical qubit overhead ratios exceeding 1000:1, constraining near-term feasibility.
Algorithm development attracts venture funding; error correction research shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Quantum Processing Units concentrates in the United States, China, and Germany as national quantum initiatives compete for technical leadership in superconducting, trapped-ion, and photonic platforms.
United States
The US CHIPS and Science Act directs federal funding toward domestic quantum fabrication capacity, with NIST post-quantum cryptography standards mandating federal inventory of vulnerable systems by 2025. MIT and national laboratories anchor superconducting QPU research clusters, while the Department of Energy negotiates enterprise-wide licensing with full-stack providers.
China
China's MIIT quantum technology guidelines direct state-backed capital toward domestic superconducting and photonic platforms. Tsinghua University operates on-premise systems for qubit coherence research. Export licensing delays for cryogenic test equipment from the US Bureau of Industry and Security extend equipment lead times for Chinese foundries.
Germany
Berlin directs €2 billion through the German Quantum Computing Initiative toward domestic fabrication capacity. Fraunhofer institutes anchor public-private consortia for trapped-ion scaling in Munich and Stuttgart. The EU Chips Act quantum provisions subsidize European fabrication capacity for fabless QPU designers.
India
The country's semiconductor mission now includes quantum component fabrication through its PLI scheme. Bengaluru and Hyderabad clusters attract photonic foundry investment from domestic and international players. The central bank and national technology missions coordinate quantum-safe infrastructure pilots for financial services.
United Kingdom
Quantinuum anchors trapped-ion commercialization through integrated hardware-software stacks with significant operations in Cambridge and London. National quantum centers negotiate procurement contracts for integrated quantum computing services. The country's national standards body coordinates with NIST on cryptographic migration timelines.
Quantum Processing Units (QPU) Market Competitive Landscape
Strategic partnerships dominate the current landscape as full-stack providers consolidate vendor relationships around integrated hardware-software-cloud offerings rather than discrete component sales. The competitive structure fragments across superconducting, trapped-ion, and photonic platform specialists, with each archetype pursuing distinct scaling roadmaps. Technology licensing agreements and cryogenic infrastructure sharing arrangements represent the two dominant competitive moves as players address helium-3 supply bottlenecks and millikelvin engineering talent scarcity.
Within the superconducting platform tier, IBM and Google occupy positions exemplifying divergent approaches to volume prototyping and gate fidelity optimization. Quantinuum represents the trapped-ion commercialization archetype through its integrated stack positioning. Among cloud-access providers, Amazon Web Services anchors the quantum-as-a-service model that research institutions and national laboratories increasingly favor over bare-metal procurement.
| Leading Market Players |
|---|
| D-Wave Systems |
| Quantinuum |
| IBM |
| Amazon Web Services |
| Microsoft |
| Rigetti Computing |
| Infleqtion |
| IonQ |
| Others |
Value Network & Pricing Analysis
Superconducting-to-photonic platform divergence splits the market into cryogenic-premium and room-temperature-economy tiers, with helium-3 dependency concentrating pricing power among Russian and Qatari isotope suppliers while photonic CMOS compatibility unlocks volume scaling at GlobalFoundries facilities.
Pricing Analysis
Volume placements favor superconducting platforms at capital-intensive price points, while photonic architectures compress unit economics through semiconductor foundry integration. Pricing stratifies across full-stack integrated providers, bare-metal hardware vendors, and pay-per-shot cloud access tiers, with gate fidelity benchmarks and coherence time specifications commanding premiums. Cost compression in cloud-access tiers is intensifying because national laboratories consolidate procurement around single-source contracts. Academic buyers exhibit highest price sensitivity due to NSF and Horizon Europe grant constraints; enterprise pharmaceutical adopters at Roche and Merck demonstrate lowest sensitivity given molecular simulation ROI timelines.
Supply Chain Analysis
Domestic-content mandates in the US CHIPS and Science Act, EU Chips Act, and India's PLI scheme are reshaping sourcing toward localized fabrication clusters in the United States, Germany, and Bengaluru. Supply chains draw from helium-3 isotope extraction in Russia and Qatar, niobium and tantalum mining operations, and dilution refrigerator manufacturing concentrated among European and Japanese specialists. Single-source vulnerability around cryogenic test equipment exposes Chinese foundries to US Bureau of Industry and Security export licensing delays. Distribution runs through direct procurement contracts for national laboratories and cloud-service intermediaries for enterprise subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NIST post-quantum cryptography standards erect a compliance moat that favors incumbent full-stack providers with federal certification pathways, raising capital requirements for new entrants lacking cryogenic infrastructure and helium-3 supply relationships.
For Market Incumbents: Hedge against photonic platform displacement by securing trapped-ion and superconducting capacity simultaneously. IBM and Quantinuum should deepen backward integration into dilution refrigerator manufacturing to offset helium-3 supply bottlenecks. Defensive patent clustering around two-qubit gate designs protects against Google and IonQ fidelity advances. For New Entrants and Emerging Players: Room-temperature photonic interconnect architectures offer the most penetrable wedge for fabless designers seeking GlobalFoundries partnerships without cryogenic engineering talent requirements. Target India's PLI-subsidized Bengaluru clusters for foundry access. A go-to-market angle through API-ready molecular simulation SDKs bypasses hardware procurement barriers facing academic buyers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated hardware-software-stack providers given NIST procurement timeline acceleration and EU Chips Act subsidy flows. Long-term viability hinges on error-correction roadmap credibility across the next decade. Watch trapped-ion gate fidelity benchmarks as the inflection indicator for platform consolidation versus fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-3 Supply Diversification | Reduces Russian and Qatari concentration risk for dilution refrigerator manufacturers. |
| Photonic Foundry Partnership | GlobalFoundries 300mm wafer commitments compress photonic QPU cost curves toward parity. |
| Full-Stack Cloud Licensing | US Department of Energy contracts validate integrated service models over bare-metal sales. |
| Cryogenic Engineering Talent Pipeline | University program expansion addresses North American and European graduate scarcity. |
| Post-Quantum Cryptography Certification | NIST compliance timelines accelerate federal procurement for quantum-safe infrastructure. |
Research Methodology
Independent corroboration across quantum hardware engineering leads, pharmaceutical computational chemistry directors, and cloud-service procurement officers underwrites the qualitative findings. Primary interviews with dilution refrigerator manufacturers, trapped-ion system architects, and national laboratory instrumentation grant administrators combined with secondary validation from US CHIPS Act funding disclosures, EU Chips Act implementation reports, and NIST post-quantum cryptography standardization documents. Bottom-up triangulation across superconducting, trapped-ion, and photonic platform deployments reconciled with top-down market sizing from federal procurement databases and venture capital flow tracking.
Rate-of-change decomposition across the analysis window separates volume expansion in cloud-access subscriptions from value concentration in full-stack integrated contracts. Segmentation dimensions modeled include QPU platform type, end-user archetype, application domain, and national quantum initiative funding cluster. CAGRs derived from installed base projections, procurement cycle analysis, and technology substitution elasticity estimates. Industry-specific forecast inputs incorporate helium-3 supply lead times and cryogenic engineering graduate pipeline constraints.
Several conditions sit outside the modeled scope, including breakthrough advances in room-temperature superconducting materials, geopolitical disruption of isotope supply chains, and fundamental error-correction threshold achievements that could accelerate or compress commercialization timelines. Forecasts reflect documented assumptions around coherence time improvement trajectories and regulatory fragmentation around export controls. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Spain Data Center Processor Market