
 Global Database Management System (DBMS) Market | 2026-2036
Global Database Management System (DBMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Database Management System (DBMS) Market Intelligence
The rapid expansion of hyperscale data center infrastructure in India and Brazil is reconfiguring the competitive landscape for cloud-based DBMS deployments. Amazon Web Services leverages its dominant public cloud platform to offer a wide array of specialized database services. Microsoft sustains its enterprise footprint by integrating its Azure SQL and Cosmos DB offerings with its broader software ecosystem. Oracle Corporation competes by focusing on high-performance, on-premises and hybrid cloud solutions for mission-critical workloads.
A Database Management System is a software suite that enables users to create, read, update, and delete data in a structured manner. These systems utilize query languages like SQL to manage data integrity, security, and concurrent access for multiple users. Within solution types, NoSQL DBMS variants like document and key-value stores are gaining share for unstructured data applications. Cloud deployment models now dominate new workloads, though on-premises systems remain critical for legacy applications in regulated industries.
Data governance and residency requirements are heavily shaped by regulations like the EU's GDPR and the US's HIPAA. These frameworks mandate strict technical and organizational controls on how personal and sensitive information is stored, processed, and accessed. Navigating the trade-offs between open-source flexibility, proprietary vendor support, and the operational complexity of multi-cloud deployments remains a central strategic decision for enterprise IT leaders.
Market Dynamics
The central tension shaping the DBMS market is the architectural divergence between specialized, high-performance systems for mission-critical workloads and the rapid proliferation of scalable, managed cloud-native databases designed for developer agility and unstructured data applications.
Growth Catalysts
- Regulatory Mandates:The EU AI Act is compelling organizations to invest in DBMS with advanced data governance, lineage, and audit capabilities to ensure compliance for artificial intelligence applications.
- Real-Time Processing:Financial institutions are driving demand for in-memory and high-throughput databases to support instantaneous transaction processing, fraud detection, and algorithmic trading.
- Infrastructure Expansion:The build-out of hyperscale data centers in India and Brazil is lowering the barrier to entry for cloud DBMS adoption, unlocking new regional workload deployments.
Market Restraints
- Multi-Cloud Complexity:The operational overhead of managing data consistency, security, and portability across multiple public cloud providers creates significant technical and cost challenges for enterprises.
- Open-Source Substitution:The maturity and broad community support for open-source databases like PostgreSQL and MongoDB present a viable, lower-cost alternative to proprietary commercial licenses.
- Data Sovereignty Laws:Strict data residency requirements, such as those within the EU's GDPR, complicate the architecture of global applications and limit the choice of cloud regions.
Strategic Opportunities
- Industrial IoT Data:Managing time-series data from sensors in manufacturing and energy sectors presents a significant opportunity for specialized DBMS optimized for high-volume ingestion and query.
- Serverless Database Models:Offering fully abstracted, event-driven database services that scale to zero provides a compelling value proposition for developers building ephemeral or bursty applications.
- MLOps Integration:Embedding machine learning model training and inference capabilities directly within the database engine can streamline analytical workflows and reduce data movement.
Industry Challenges
- Specialized Skills Scarcity:A persistent talent gap exists for database administrators and engineers who possess deep expertise in both legacy on-premises systems and modern distributed cloud databases.
- Legacy System Integration:Connecting modern cloud-native databases with decades-old mainframe and relational systems remains a complex, costly, and resource-intensive hurdle for large enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Database Management System (DBMS) Market |
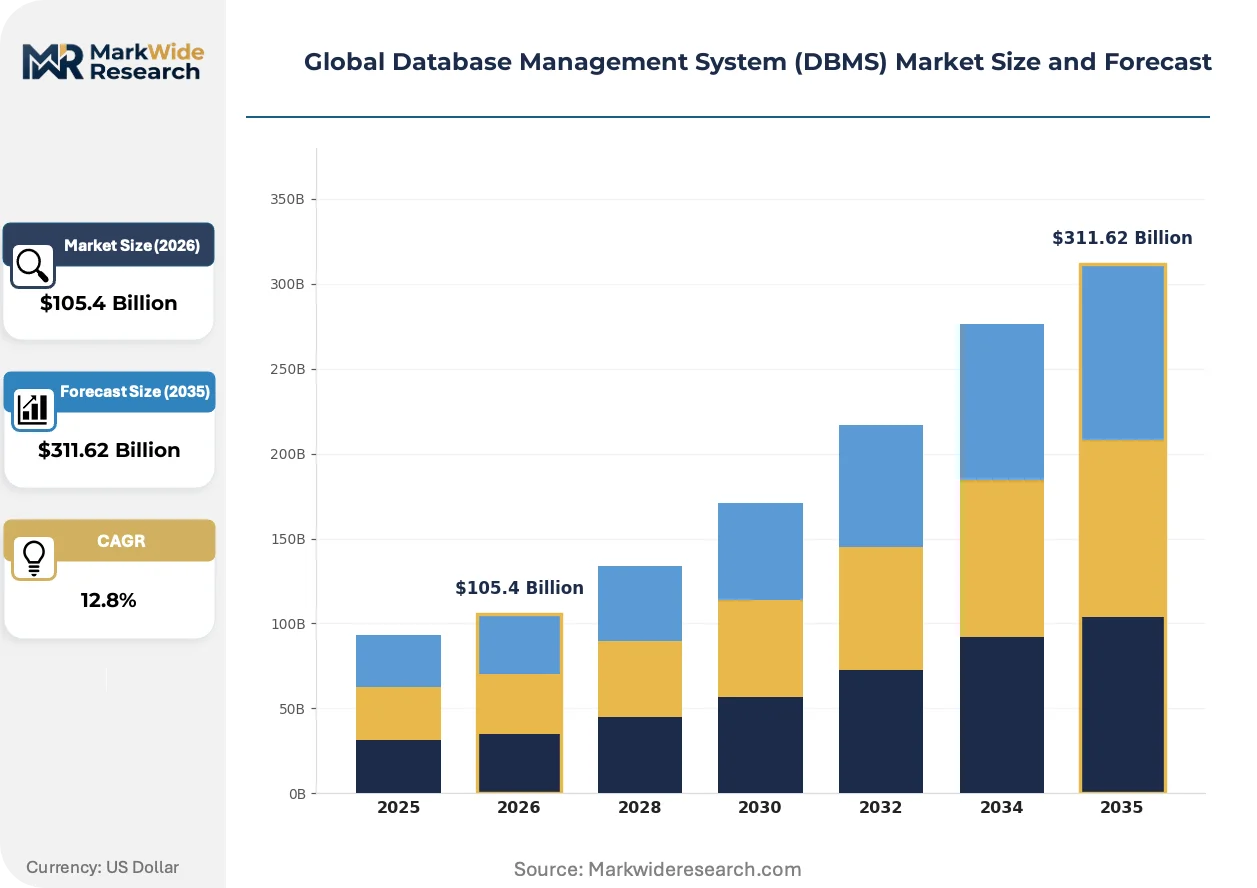
| Market Size in 2026 | $105.4 Billion |
| Market Size in 2035 | $311.62 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge, Multi-Cloud Solution Type: Relational DBMS, NoSQL DBMS, NewSQL DBMS, Time-Series DBMS, Graph DBMS Use Case: Transaction Processing, Data Warehousing, Analytics, Content Management, Customer Relationship Management End User: Banking Institutions, Telecommunication Operators, E-Commerce Firms, Government Agencies, Educational Institutions |
| Companies Covered | Google Cloud, PostgreSQL Global Development Group, Oracle Corporation, MongoDB, MySQL (Oracle), Microsoft, IBM, Redis Labs, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Database Management System (DBMS) Market Strategic Shifts & Innovations
The evolution of DBMS is defined by a fundamental shift towards data-centric architectures. This change positions the database not merely as a passive repository but as an active, intelligent component of the application and governance stack.
Vector databases are specialized systems designed to store, manage, and query high-dimensional data embeddings for AI applications. Adoption by data science teams building generative AI and semantic search functions is accelerating. The market's focus is migrating from purely relational data management toward natively supporting these complex data structures for modern machine learning.
Upcoming regulations like the European Union's AI Act mandate stringent data quality, transparency, and governance controls for systems deemed high-risk. This directive is forcing DBMS providers to embed sophisticated data lineage, auditing, and bias-detection features directly into their platforms. Financial services and healthcare sectors are most impacted, prioritizing database solutions that can demonstrate verifiable compliance.
A significant change in enterprise purchasing behavior involves moving from perpetual software licenses toward consumption-based, pay-as-you-go pricing for cloud database services. This model displaces large capital expenditures with flexible operational spending, aligning costs directly with actual usage. The shift is most visible among technology companies and digital-native businesses in North America and Europe.
Global Database Management System (DBMS) Market Segmentation
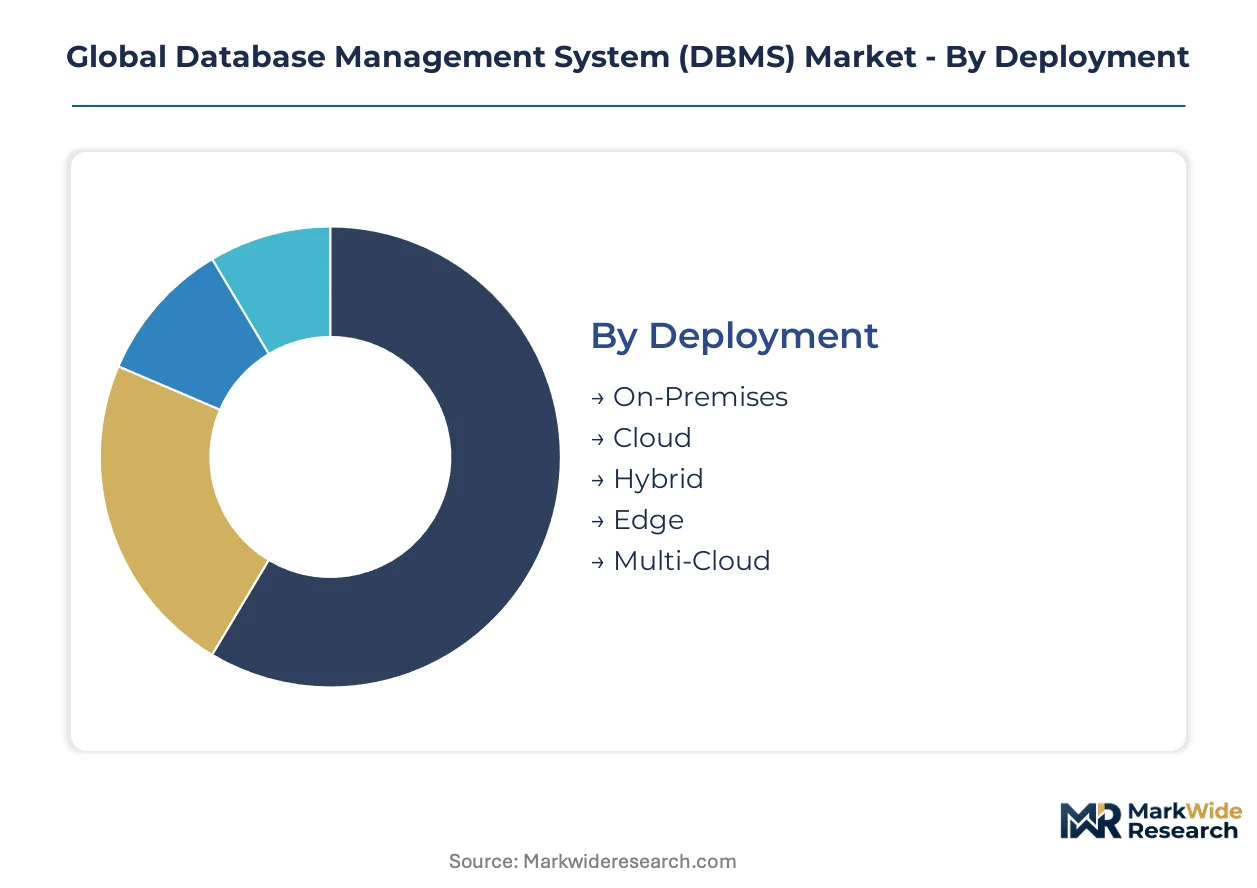
The segmentation of the Global Database Management System (DBMS) Market provides a granular understanding of how diverse architectural requirements and operational models influence technology adoption. This detailed breakdown highlights specific demand drivers and deployment preferences across various industry verticals and application scenarios.
Deployment:
The deployment model for a DBMS directly influences the intensity and complexity of required after-sales support and ongoing maintenance.
- On-Premises:Deployed within an organization's own data centers, providing complete control over infrastructure and data, often preferred by highly regulated industries for security.
- Cloud:Hosted by a third-party provider, offering scalability, managed services, and reduced operational overhead. Demand concentrates in North America and Europe, driven by consumption-based pricing models.
- Hybrid:Combines on-premises infrastructure with cloud resources, allowing data portability and workload flexibility. Enterprises in financial services and healthcare adopt this for balancing legacy systems and new cloud initiatives.
- Edge:Processes data closer to the source, reducing latency for Industrial IoT applications and real-time analytics in manufacturing.
- Multi-Cloud:Utilizes services from multiple public cloud providers, enhancing resilience and avoiding vendor lock-in for global enterprises.
On-Premises holds the largest share for legacy applications; momentum sits with Cloud for new workloads.
Solution Type:
Each solution type offers distinct architectural advantages tailored to specific data structures and application requirements.
- Relational DBMS:Organizes data into tables with predefined schemas, ensuring data integrity through ACID properties. Financial institutions and government agencies rely on these for structured transaction processing.
- NoSQL DBMS:Provides flexible schema-less data models, optimized for handling large volumes of unstructured or semi-structured data. E-commerce firms and social media platforms leverage NoSQL for user profiles and content management.
- NewSQL DBMS:Combines the scalability of NoSQL with the transactional guarantees of traditional relational databases for high-performance applications.
- Time-Series DBMS:Optimized for storing and querying data points indexed by time, crucial for IoT sensor data and operational monitoring.
- Graph DBMS:Represents data as nodes and edges, enabling efficient querying of complex relationships in social networks and fraud detection systems.
The market exhibits a shift from Relational DBMS towards NoSQL DBMS for new deployments.
Use Case:
The varied use cases for DBMS solutions impose different demands regarding data volume, velocity, and query complexity.
- Transaction Processing:Manages real-time data operations, ensuring atomicity, consistency, isolation, and durability for critical business processes. Banking institutions and e-commerce platforms depend on this for core operations.
- Data Warehousing:Consolidates historical data from various sources for reporting and analytical purposes, supporting business intelligence initiatives.
- Analytics:Supports complex queries and aggregations across large datasets, enabling business intelligence and predictive modeling. Telecommunication operators and financial services use this for strategic insights.
- Content Management:Organizes and stores digital assets, documents, and rich media for easy access and retrieval in various industries.
- Customer Relationship Management:Manages customer interactions and data to improve service, personalize experiences, and optimize sales processes.
While Transaction Processing remains foundational, Analytics demonstrates the steepest expansion trajectory.
End User:
Different end-user industries impose distinct requirements concerning regulatory compliance, data sensitivity, and operational uptime for their DBMS solutions.
- Banking Institutions:Require highly secure and compliant DBMS for financial transactions, fraud detection, and regulatory reporting. GDPR and HIPAA compliance are critical for these entities.
- Telecommunication Operators:Utilize DBMS for subscriber management, network monitoring, and billing systems, handling vast quantities of call detail records.
- E-Commerce Firms:Demand scalable and high-performance databases to manage product catalogs, customer orders, and real-time user interactions. These firms prioritize agility and global reach.
- Government Agencies:Implement DBMS for public records, citizen services, and national security data, often requiring stringent data residency controls.
- Educational Institutions:Deploy databases for student information systems, research data, and administrative functions, supporting academic operations.
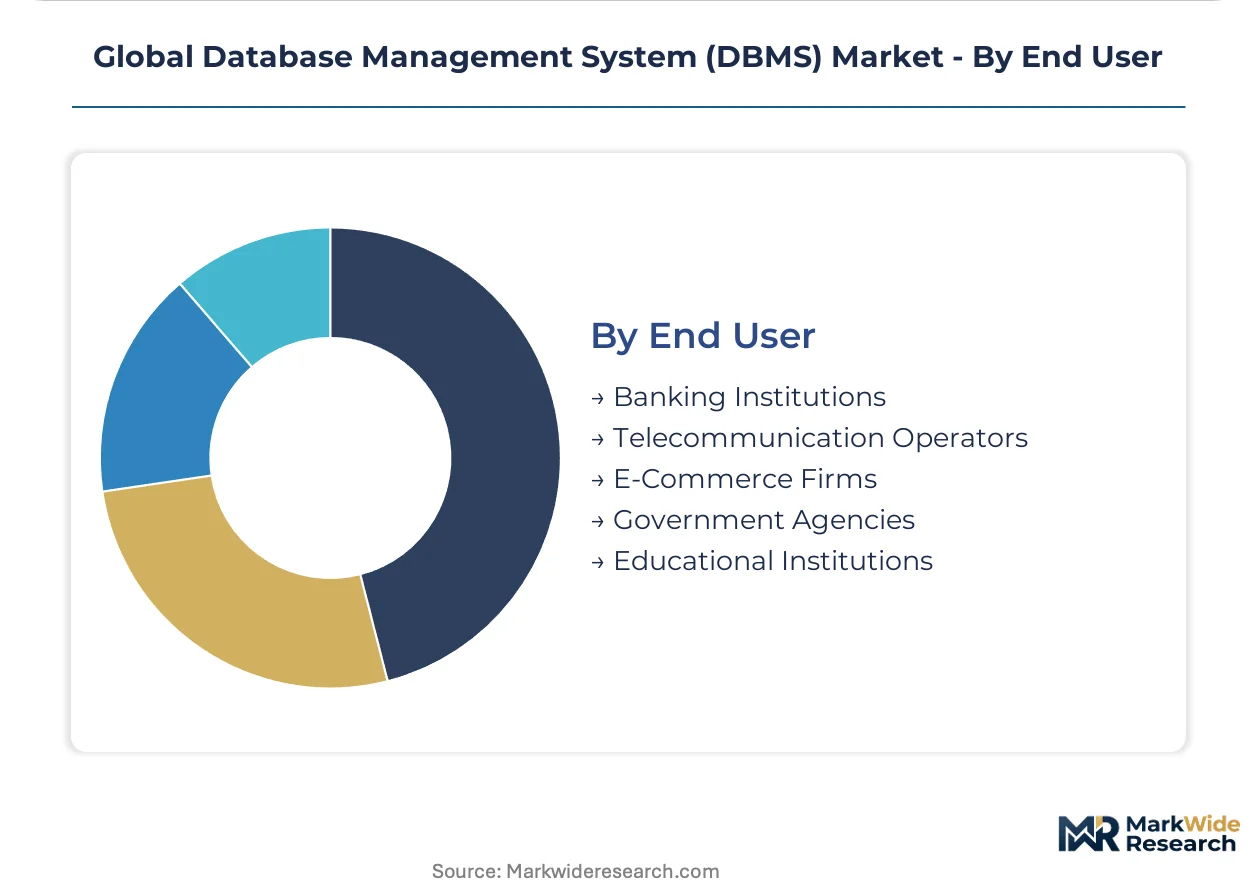
A substantial portion of demand originates from Banking Institutions, with E-Commerce Firms showing considerable growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of cloud infrastructure and advanced technology development significantly shapes demand for Database Management Systems. Key global players leverage established data center networks and regulatory environments to influence regional market dynamics. This creates distinct patterns of adoption and innovation across different economic blocs.
United States
Demand for advanced DBMS solutions in the United States stems from its robust technology sector and the pervasive adoption of cloud-native architectures. The HIPAA framework mandates stringent data security and privacy controls, particularly within healthcare applications. Silicon Valley and major tech hubs like Seattle and Austin continue to drive innovation in serverless database models and vector database technologies.
Germany
Germany exhibits strong demand for hybrid DBMS solutions, balancing established on-premises systems with new cloud deployments. The EU's GDPR and the impending EU AI Act compel organizations to prioritize data governance and compliance capabilities. Major industrial centers such as Munich and Frankfurt are investing in specialized time-series databases for Industrial IoT applications in manufacturing.
India
India's rapid expansion of hyperscale data center infrastructure is a primary catalyst for cloud DBMS adoption. Government initiatives like the Digital India program encourage the use of scalable database solutions for public services and e-commerce platforms. Technology hubs in Bengaluru and Hyderabad are experiencing significant growth in demand for NoSQL databases to support new digital businesses.
Brazil
Brazil's market for DBMS is accelerating due to increasing digitalization across various sectors and the build-out of new data center facilities. Regulatory frameworks, including the LGPD, influence data residency and processing requirements for local enterprises. São Paulo, as a major financial and commercial hub, shows strong interest in high-performance relational databases for transaction processing.
Singapore
Singapore serves as a critical data center cluster and technology hub, fostering demand for advanced cloud DBMS and multi-cloud strategies. Its strategic location and supportive regulatory environment attract global enterprises for data management operations. The city-state's financial services sector actively adopts in-memory databases for real-time analytics and fraud detection capabilities.
Global Database Management System (DBMS) Market Key Industry Players
Hyperscale cloud providers and specialized database vendors split the market for Database Management Systems. The competitive structure features both heavily resourced platform players and agile, technology-focused specialists. Dominant competitive moves include strategic partnerships to expand ecosystem integration and continuous portfolio diversification into emerging database categories like vector and time-series systems.
Among global technology providers, Oracle Corporation occupies a position focused on high-performance, mission-critical workloads, offering both on-premises and hybrid cloud solutions. Microsoft exemplifies an enterprise-centric approach, integrating its Azure SQL and Cosmos DB offerings deeply within its broader software ecosystem. Amazon Web Services anchors the public cloud segment, leveraging its dominant platform to provide a wide array of specialized database services for diverse application requirements.
| Leading Market Players |
|---|
| Google Cloud |
| PostgreSQL Global Development Group |
| Oracle Corporation |
| MongoDB |
| MySQL (Oracle) |
| Microsoft |
| IBM |
| Redis Labs |
| Amazon Web Services |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud infrastructure development in key data center regions like the United States and Singapore concentrates upstream supply. This concentration allows dominant platform providers to capture significant margin pools in managed database services.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for advanced data governance features within DBMS. Consumption-based, pay-as-you-go models dominate cloud database services, with pricing differentiating on performance tiers and managed service levels. Pricing pressure stems from the maturity of open-source alternatives, particularly for non-mission-critical workloads. Regulated industries like banking exhibit lower price sensitivity for solutions guaranteeing stringent compliance and data residency.
Supply Chain Analysis
Regulatory restrictions on data localization dominate the supply chain for global DBMS deployments. Core cloud infrastructure development concentrates in the United States, Germany, and Singapore, relying on specialized software development talent and high-performance server components. A structural risk involves the scarcity of database administrators skilled in both legacy and modern distributed systems. Distribution runs through hyperscale cloud platforms and specialized software vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global DBMS market is entering a cyclical recovery, driven by renewed enterprise investment in digital transformation initiatives. Organizations are modernizing legacy systems and adopting cloud-native architectures at an accelerated pace.
For Market Incumbents: Harden core relational database offerings with advanced security and compliance certifications for regulated industries. Integrate vector database capabilities directly into existing platforms to counter specialized vendors and address generative AI demand. Investment in R&D for embedded MLOps features strengthens competitive positioning. This mitigates specialized skills scarcity.
For New Entrants and Emerging Players: Build out specialized database offerings for high-growth segments like Industrial IoT time-series data and serverless applications. Target digital-native businesses and mid-market enterprises in expanding regions like India and Brazil. A developer-centric go-to-market angle, emphasizing ease of use and flexible consumption-based pricing, accelerates adoption.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed providers of specialized NoSQL and cloud-native databases. The DBMS market represents essential infrastructure for the digital economy, offering sustained long-term viability. Target acquisition archetypes include niche providers with strong intellectual property in vector databases or advanced data governance. Increased M&A activity among hyperscalers serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Vector Database) | Addresses growing demand from data science teams for generative AI and semantic search applications. |
| Platform Integration (MLOps) | Streamlines analytical workflows and reduces data movement for machine learning model training and inference. |
| Strategic Partnership (Data Governance) | Enhances compliance capabilities for organizations navigating regulations like the EU AI Act. |
| Acquisition of Specialist Firm (Time-Series) | Expands market reach into Industrial IoT and real-time operational monitoring use cases. |
| Geographic Expansion (India/Brazil) | Captures new regional workload deployments driven by hyperscale data center build-outs. |
Research Approach
A standing panel of CTOs, IT procurement officers, and database architects provided ongoing calibration for market sizing and trend validation. This involved combining primary interviews with industry stakeholders and secondary validation from sources like SEC filings and hyperscaler capital expenditure disclosures. Bottom-up data aggregation and top-down market assessments ensured comprehensive triangulation.
Scenario-bracketing projected market trajectories over the projection horizon, accounting for various adoption rates. The analytical framework modeled segmentation dimensions including deployment model, solution type, use case, and end user. Compound Annual Growth Rates derived from historical growth and projected adoption rates. Enterprise IT spending forecasts and data center build-out plans served as key forecast inputs.
Stress conditions across enterprise IT budgets, regulatory compliance stringency, and cloud infrastructure availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Dynamic Data Management System Market