
 Ireland Data Center Networking Market | 2026-2036
Ireland Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Networking Market Insights
Buyer concentration among hyperscale cloud operators is hardening across Ireland's data center corridor. Cisco Systems Inc. leverages its switching portfolio to anchor enterprise campus-to-data-center transitions, while Arista Networks Inc. competes on low-latency fabric density for cloud-scale environments. Dell EMC sustains server-storage-network convergence plays that simplify procurement for mid-market colocation tenants.
Ireland data center networking encompasses the switching, routing, and interconnect infrastructure that enables compute-to-storage traffic flow within and between facilities, typically operating at 100G/400G port speeds with sub-microsecond latency targets for AI workloads. Ethernet dominates fabric backbones due to cost-scale economics, though InfiniBand gains traction in GPU clusters where bandwidth aggregation matters. Colocation deployments absorb the largest share of connectivity investment as enterprises outsource footprint, while managed services models expand among financial institutions seeking operational offload.
EPA licensing frameworks constrain power-density expansion, pushing operators toward liquid cooling and higher-efficiency switch architectures. BSI standards for electromagnetic compatibility and CE marking requirements shape equipment import and deployment protocols. Stakeholders must weigh regulatory compliance timelines against the acceleration of AI training clusters demanding non-blocking network topologies.
Market Dynamics
EPA licensing requirements for data center energy consumption are compressing facility expansion timelines across Ireland's data center corridor. Operators must redesign power architectures and cooling systems to secure operating permits.
Growth Catalysts
- AI training cluster deployment:Hyperscale cloud providers are commissioning non-blocking network topologies to support GPU-intensive workloads across Dublin and Cork facilities.
- Financial services outsourcing:Banks and insurance operators are migrating core infrastructure to colocation environments, driving demand for managed connectivity services.
- RoHS and CE marking alignment:Equipment import standardization is streamlining procurement cycles for switch and router deployments.
Market Restraints
- Power density constraints:EPA licensing caps on energy consumption per facility are limiting rack-level expansion for high-performance computing deployments.
- Switch silicon supply concentration:Merchant silicon for 400G ports concentrates among a handful of foundry operators, creating procurement bottlenecks.
- Liquid cooling retrofit costs:Existing facilities face substantial capital requirements to convert air-cooled halls for next-generation chip thermal profiles.
Strategic Opportunities
- Edge interconnect for rural zones:Secondary markets in Limerick and Galway present greenfield deployment opportunities for latency-sensitive applications.
- EU AI Act compliance services:Managed network verification and audit capabilities are emerging as differentiated service offerings for regulated tenants.
- Photonic switching convergence:Integration of optical circuit switching with electronic packet fabrics is enabling new power-efficient architectures for AI clusters.
Industry Challenges
- Network engineering specialization:Shortages of talent proficient in spine-leaf topology design and InfiniBand fabric configuration are extending deployment timelines.
- BSI electromagnetic compatibility certification:Extended testing protocols for high-speed signaling equipment are delaying product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Networking Market |
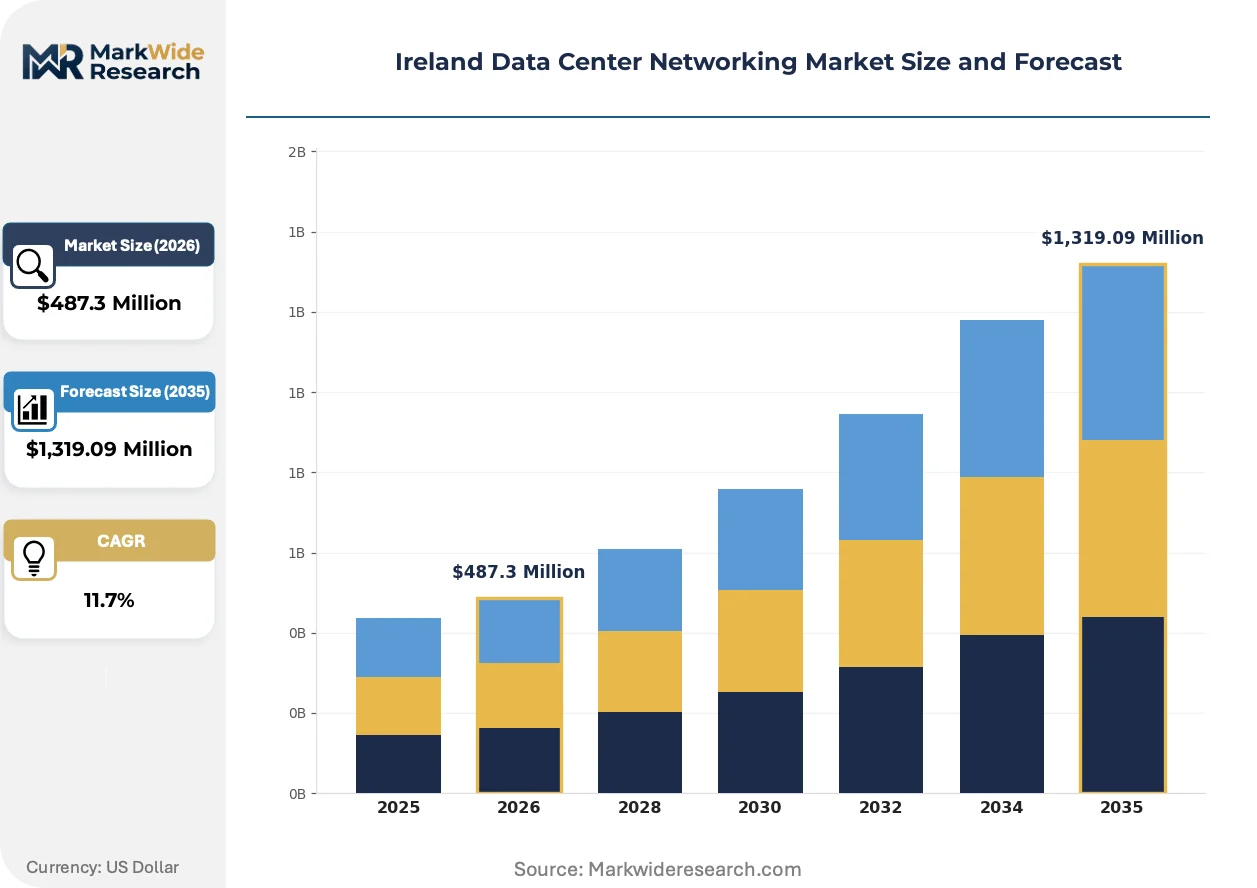
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Type: Ethernet, Fibre Channel, InfiniBand, MPLS Connectivity Technology: Wired, Wireless, Optical, Coaxial End User: Cloud Providers, Enterprises, Telecoms, Financial Institutions Deployment Model: On-Premises, Colocation, Hybrid, Managed Services |
| Companies Covered | Cisco Systems Inc., Arista Networks Inc., Dell EMC, HP Development Company, Huawei Technologies, Schneider Electric, Microsoft Corporation, Fujitsu Ltd., Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Networking Market Trends and Innovations
Silicon photonics is compressing power budgets and port densities across Ireland's data center switching layer. Regulatory pressure on energy consumption is accelerating architectural experimentation. Buyer behavior is pivoting toward operational expenditure models that offload complexity.
Co-packaged optics is integrating electro-optical conversion directly onto switch ASIC substrates, eliminating discrete transceiver modules. Hyperscale operators in Dublin are piloting these designs for 51.2Tbps-class systems. This integration is reducing per-bit energy consumption by removing signal conditioning stages between electrical and optical domains.
EU CSRD disclosure mandates are compelling facility operators to document Scope 2 emissions from network equipment power draw. Colocation providers must now supply tenant-specific carbon accounting for switching infrastructure. Financial services tenants are responding by inserting sustainability clauses into connectivity procurement contracts.
Consumption-based billing for cross-connect and inter-facility bandwidth is displacing traditional port-lease arrangements. Mid-market SaaS operators are favoring metered models that align network costs with actual traffic volumes. This pattern is most visible among Dublin-based fintech clusters seeking operational flexibility during growth phases.
Ireland Data Center Networking Market Segmentation
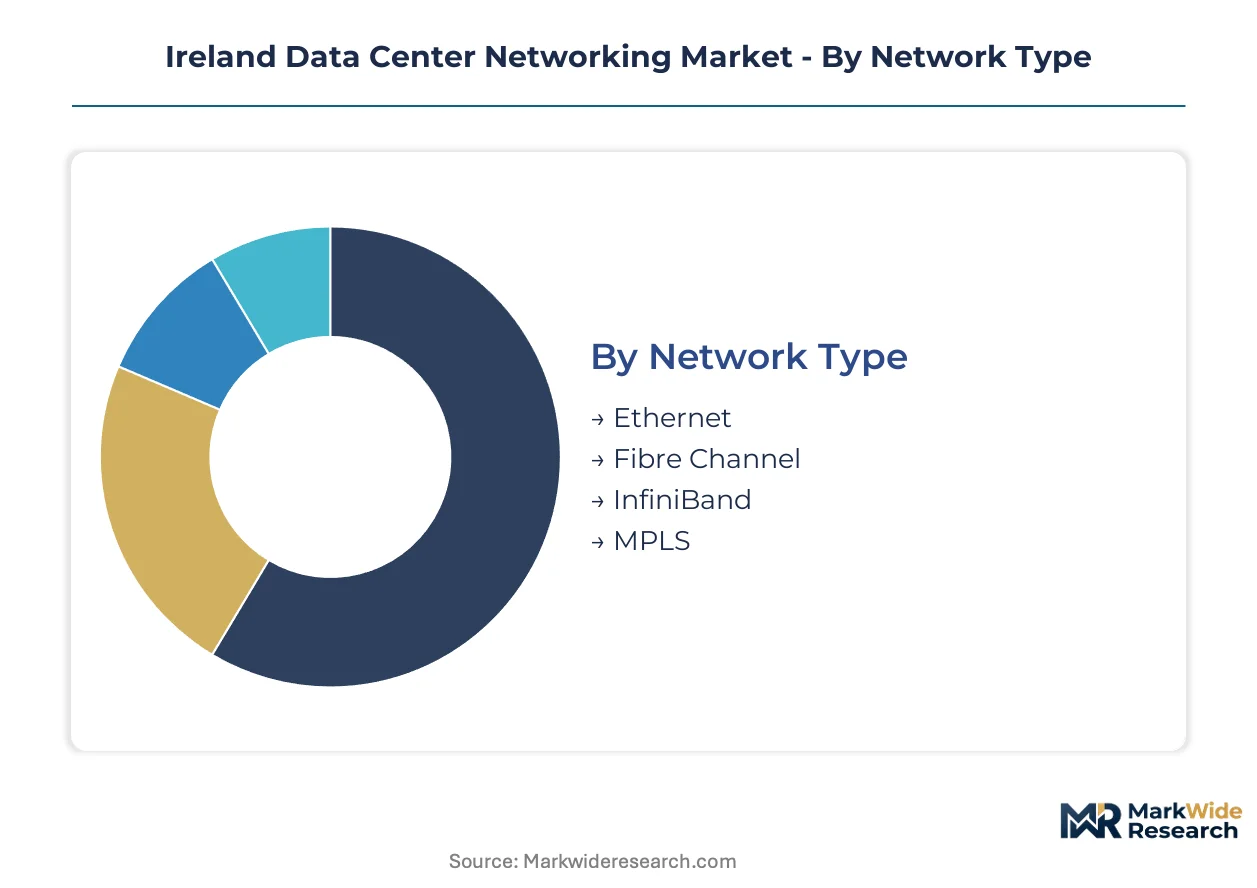
Ireland's data center networking market fragments across protocol standards, physical media, customer archetypes, and operational models. Each segment carries distinct certification burdens from EPA licensing, BSI electromagnetic compatibility standards, and CE marking requirements that shape procurement timelines and facility design.
Network Type:
Ethernet, InfiniBand, and Fibre Channel each face BSI electromagnetic compatibility certification for high-speed signaling equipment, while MPLS deployments trigger additional carrier-grade compliance protocols.
- Ethernet:Dominates fabric backbones with 100G/400G port speeds and sub-microsecond latency targets. Cloud providers in Dublin and Cork facilities drive procurement volumes for spine-leaf architectures serving AI training clusters constrained by EPA power-density caps.
- InfiniBand:Delivers bandwidth aggregation for GPU-intensive workloads through non-blocking network topologies. Demand concentrates among hyperscale operators retrofitting liquid-cooled halls to accommodate next-generation chip thermal profiles under licensing constraints.
- Fibre Channel:Sustains storage-area network connectivity for financial institutions outsourcing core infrastructure to colocation environments.
- MPLS:Supports managed WAN services for enterprises seeking operational offload of branch-to-data-center traffic engineering.
Leading the category by volume: Ethernet. Expanding most quickly: InfiniBand.
Connectivity Technology:
Physical layer choices determine power budgets, port densities, and retrofit capital requirements across Ireland's constrained facility expansion timeline.
- Optical:Silicon photonics and co-packaged optics are compressing energy consumption for 51.2Tbps-class systems. Hyperscale operators pilot these designs in Dublin to meet EPA licensing thresholds while maintaining fabric density for AI clusters.
- Wired:Copper cabling dominates cost-sensitive enterprise campus extensions and mid-market colocation tenant connectivity. Procurement concentrates among SaaS operators in Dublin-based fintech clusters favoring metered bandwidth models.
- Wireless:Supports edge interconnect for rural zones in Limerick and Galway where greenfield deployment avoids retrofit constraints.
- Coaxial:Retains niche presence in legacy facility interconnections and broadcast media ingestion points.
Dominant by deployment scale: Optical. Steepest adoption curve: Wireless.
End User:
Customer concentration among hyperscale operators hardens procurement patterns, while financial services outsourcing creates managed service opportunities with sustainability clause insertion.
- Cloud Providers:Anchor procurement volumes across Dublin and Cork facilities, commissioning non-blocking topologies for GPU-intensive workloads. EPA licensing requirements compress expansion timelines and push toward liquid cooling and higher-efficiency switch architectures.
- Financial Institutions:Banks and insurance operators migrate core infrastructure to colocation environments, driving demand for managed connectivity with EU CSRD-mandated Scope 2 emissions documentation.
- Enterprises:Mid-market SaaS operators favor consumption-based billing for cross-connect bandwidth to align costs with traffic volumes during growth phases.
- Telecoms:Provide inter-facility backhaul and edge interconnect infrastructure for latency-sensitive applications.
Category leader by infrastructure spend: Cloud Providers. Fastest contract value expansion: Financial Institutions.
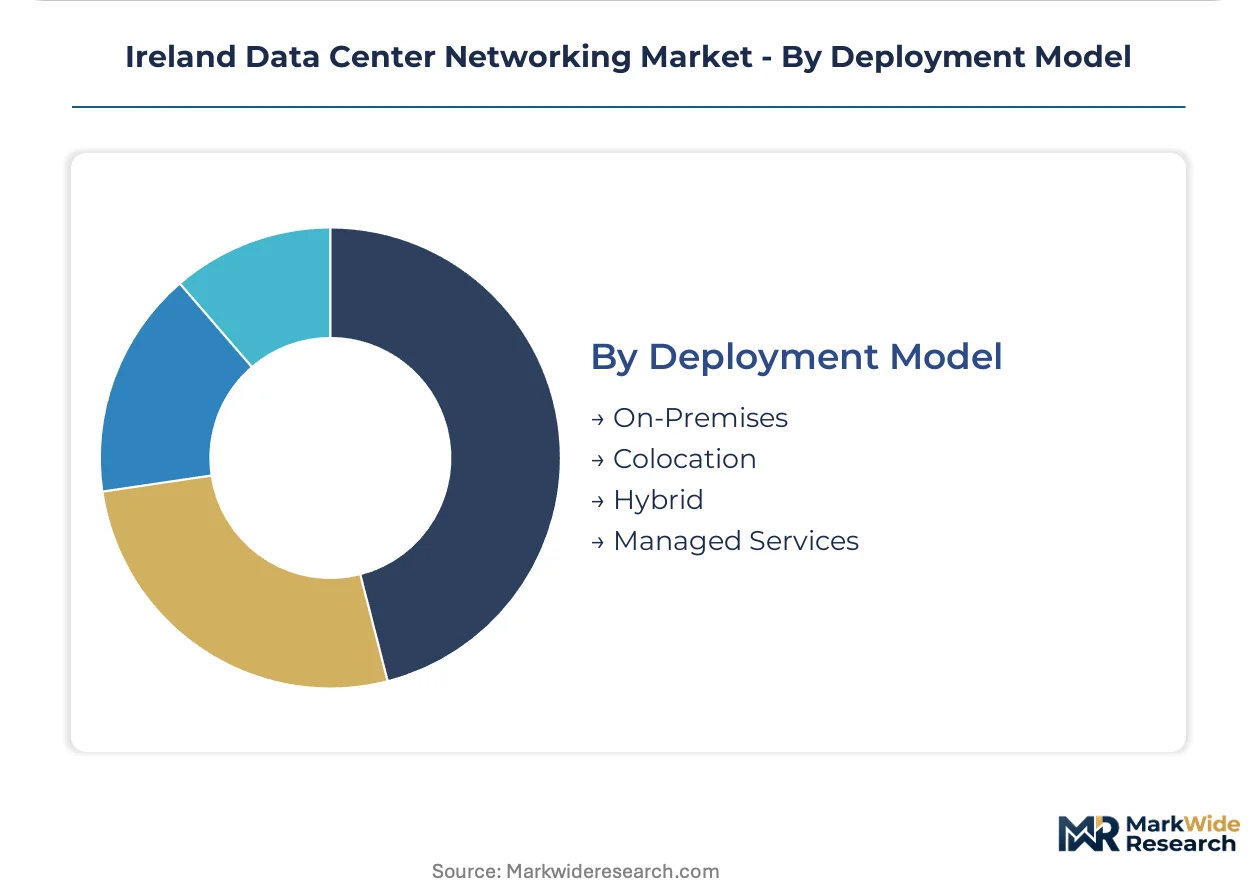
Deployment Model:
Operational complexity offloading trends are pivoting buyer behavior toward expenditure models that transfer engineering specialization burdens.
- Colocation:Absorbs the largest share of connectivity investment as enterprises outsource footprint. Providers must supply tenant-specific carbon accounting for switching infrastructure under EU CSRD mandates.
- Managed Services:Expands among financial institutions seeking operational offload of network engineering functions including spine-leaf topology design and InfiniBand fabric configuration.
- Hybrid:Combines on-premises control with burst capacity into colocation facilities for variable AI training workloads.
- On-Premises:Retains presence among regulated entities requiring direct control over data sovereignty and audit trails.
Highest facility count: Colocation. Quickest model shift: Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate procurement volumes across Ireland's data center corridor, with facility expansion timelines compressed by regulatory licensing frameworks. Dublin and Cork anchor deployment activity, while secondary markets emerge for latency-sensitive edge applications.
Dublin
Cloud providers commission non-blocking network topologies for GPU-intensive AI training clusters across multiple facilities. EPA licensing requirements constrain power-density expansion, pushing operators toward liquid cooling and higher-efficiency switch architectures. The capital region hosts the densest concentration of colocation deployments serving financial services and SaaS operators.
Cork
Hyperscale operators establish secondary campuses to diversify geographic risk within the national corridor. BSI electromagnetic compatibility standards shape equipment qualification cycles for high-speed signaling infrastructure. The southern hub attracts managed services investment from insurance operators seeking operational offload.
Galway
Edge interconnect opportunities emerge for latency-sensitive applications targeting rural connectivity gaps. Wireless infrastructure investments bypass retrofit constraints facing established facilities. The western city presents greenfield deployment potential outside EPA-licensed power caps affecting Dublin and Cork.
Limerick
Mid-market SaaS operators favor metered bandwidth models to align network costs with traffic volumes during growth phases. Consumption-based billing for cross-connect infrastructure displaces traditional port-lease arrangements. The Shannon region develops as a cost-sensitive alternative to capital-region colocation.
Ireland Data Center Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized fabric density for cloud-scale environments. The vendor base stratifies across switching portfolio breadth, low-latency optimization, and server-storage-network convergence capabilities. Three archetypes dominate: full-stack infrastructure providers, cloud-optimized fabric specialists, and power-management integrated suppliers. Competitive moves concentrate on strategic partnerships for silicon supply security and portfolio diversification into sustainability-verified equipment lines.
Among networking infrastructure specialists, Cisco Systems Inc., Arista Networks Inc., and Dell EMC anchor the competitive landscape. Cisco represents the established tier with campus-to-data-center transition capabilities. Arista exemplifies the cloud-optimized fabric specialist archetype targeting hyperscale latency requirements. Dell EMC occupies a convergence-focused position simplifying procurement for mid-market colocation tenants. Each sits within distinct competitive vectors shaped by buyer concentration among hyperscale operators and financial services outsourcing demand.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Arista Networks Inc. |
| Dell EMC |
| HP Development Company |
| Huawei Technologies |
| Schneider Electric |
| Microsoft Corporation |
| Fujitsu Ltd. |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Copper pricing indices and silicon wafer cost benchmarks cascade through Ireland's data center networking supply chain, compressing margins at the merchant silicon tier while hyperscale buyers extract volume discounts that widen spreads between premium and standard switch configurations.
Pricing Analysis
Volume procurement by hyperscale cloud providers captures margin at the 400G switch tier, while mid-market colocation tenants face cost-plus structures. Three-tier pricing stratifies across premium InfiniBand fabrics, standard Ethernet spine-leaf architectures, and economy copper-copper configurations. Pricing pressure stems from EPA licensing constraints that extend facility deployment timelines and delay revenue recognition. Financial institutions demonstrate lowest price sensitivity due to sustainability clause requirements, while SaaS operators in Limerick and Galway drive hardest bargain for metered bandwidth models.
Supply Chain Analysis
Dual-sourcing mandates from hyperscale buyers force qualification of switch ASIC suppliers across Taiwan, South Korea, and the United States, reducing single-foundry vulnerability for 51.2Tbps-class silicon. Supply chains draw from photonic component foundries in Germany, fiber optic cable manufacturers in China, and precision cooling systems from Denmark. Tariff exposure on Chinese optical transceivers creates procurement bottlenecks during qualification cycles. Distribution runs through direct OEM relationships for hyperscale accounts and value-added resellers serving mid-market colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ireland's data center networking sector sits in a technology-transition phase where co-packaged optics displaces discrete transceiver modules, forcing incumbents and challengers to reposition around power-efficient fabric architectures.
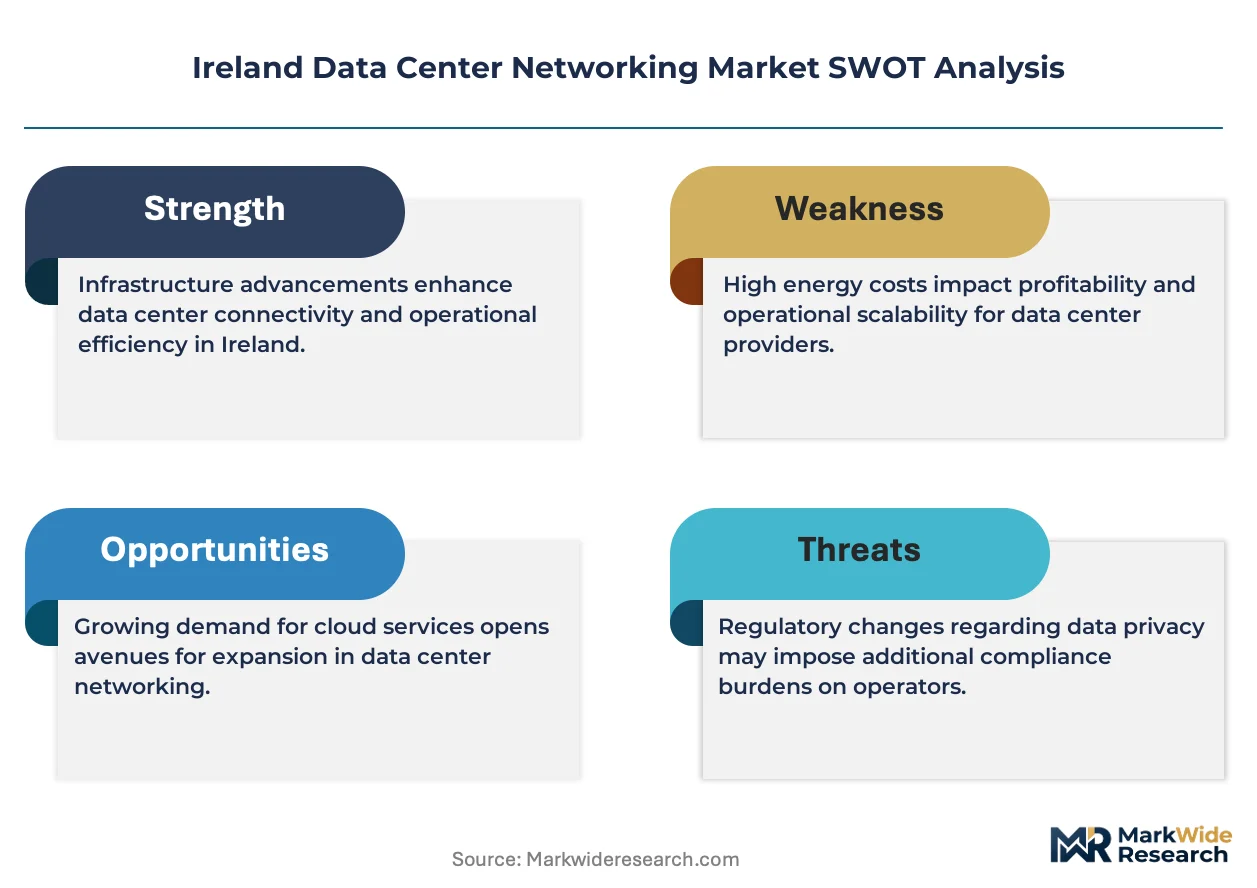
For Market Incumbents: Hedge against merchant silicon supply concentration by qualifying secondary foundry sources for 400G and 800G switch ASICs. Anchor enterprise campus relationships through managed services bundles that offload spine-leaf design complexity. EPA licensing timeline compression threatens facility expansion schedules; secure early power allocation commitments from EirGrid to defend installation slots.
For New Entrants and Emerging Players: Launch via consumption-based billing platforms targeting mid-market SaaS operators in Limerick and Galway seeking operational flexibility. Photonic switching convergence presents white-space opportunity for AI cluster optimization. Lead with EU CSRD compliance tooling as differentiated service layer for financial services tenants.
For Investors and Strategic Acquirers: Distressed-cycle entries favor liquid-cooling infrastructure specialists in Cork and Dublin corridors where retrofit capital requirements strain balance sheets. Long-term viability hinges on positioning for photonic-electronic integration architectures. Watch InfiniBand penetration rates in GPU clusters as inflection signal for fabric technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Co-packaged optics reduce per-bit energy consumption for EPA-compliant 51.2Tbps systems in Dublin facilities. |
| Liquid Cooling Retrofit Partnership | Joint ventures with precision cooling specialists address thermal constraints from next-generation chip deployments. |
| EU CSRD Compliance Service Launch | Tenant-specific carbon accounting capabilities differentiate colocation providers serving financial institutions. |
| Secondary Market Edge Expansion | Greenfield wireless interconnect in Galway and Limerick bypasses power-density caps constraining Dublin expansion. |
| InfiniBand Fabric Specialization | Non-blocking topology expertise captures GPU-intensive AI training cluster demand from hyperscale operators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center facility operators, network engineering directors at hyperscale cloud providers, colocation procurement managers, and EPA licensing officers combined with secondary validation from EirGrid interconnection queues, BSI certification databases, and EU CSRD disclosure registries. Bottom-up triangulation across switch port shipment data and top-down reconciliation against facility power allocation permits established volume estimates.
Granularity-level modeling segmented the market by protocol standard, connectivity technology, end-user archetype, and deployment model across the projection horizon. CAGRs derived from regression analysis of historical port speed transitions and power-density constraints. InfiniBand penetration assumptions and liquid cooling adoption curves served as key forecast inputs for AI cluster demand.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics integration would alter the outlook. Forecasts reflect assumptions around EPA licensing timeline stability and merchant silicon supply continuity. Deviation in EirGrid interconnection queue prioritization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Global Database Management System (DBMS) Market