
 In-Memory Analytics Tools Market | 2026-2036
In-Memory Analytics Tools Market Size, Share, and Industry Trends Forecast 2026-2036
In-Memory Analytics Tools Market Foresight
Packaging of analytics capabilities into modular, API-first components is shifting how enterprises evaluate vendor relationships. SAP SE leverages its HANA-centric ecosystem to anchor large manufacturing deployments across Germany and Japan. IBM competes through hybrid cloud architectures that extend mainframe-resident data into memory-optimized layers. Microsoft dominates the mid-market with Azure Synapse integrations that embed in-memory engines inside broader data platform subscriptions.
In-memory analytics tools execute queries directly within random-access memory rather than reading from disk-based storage, achieving sub-second response times on datasets exceeding terabyte scale while eliminating input/output bottlenecks that constrain traditional relational databases. Their primary commercial purpose centers on enabling operational decision-making at the moment data generates rather than in overnight batch windows. Integrated solutions capture the deepest margin pools because vendors bundle memory-optimized engines with data preparation, visualization, and governance layers that lock in recurring revenue. Cloud-based platforms represent the fastest-expanding deployment category as Amazon Web Services and Microsoft push serverless in-memory offerings that eliminate provisioning overhead. Standalone tools occupy a narrowing niche where specialized quantitative teams in telecommunications and retail demand direct engine control without platform overhead.
The EU AI Act imposes algorithmic transparency requirements that shape how predictive analytics modules within in-memory platforms document training data lineage and decision logic. HIPAA in the United States constrains healthcare deployments by requiring audit trails for any real-time analytics touching protected health information, while Japan's METI promotes memory-computing standards through its Society 5.0 digitization framework. Enterprises must weigh sovereignty requirements against latency gains when selecting deployment architectures, as regulators on three continents tighten data localization rules faster than cloud regions proliferate.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing in-memory analytics vendors to rearchitect their predictive modules around documented data lineage, compressing deployment timelines for financial services and healthcare buyers who require auditable real-time decision systems.
Growth Catalysts
- GDPR Article 17 (Right to Erasure):European enterprises are accelerating migration to in-memory architectures that enable rapid data purging without batch processing delays, particularly in German automotive supply chains.
- Real-time fraud detection:Banking and payment networks now require sub-100 millisecond transaction scoring, driving replacement of disk-based data warehouses with memory-optimized query engines.
- Japan METI Society 5.0 framework:Smart factory initiatives across Osaka and Nagoya industrial clusters mandate edge-resident analytics for predictive maintenance on connected production lines.
Market Restraints
- DDR5 memory cost volatility:Server-grade RAM constitutes 40-60% of platform TCO, with spot price swings directly compressing vendor margins on fixed-price enterprise contracts.
- Silicon supply concentration:Advanced memory fabrication concentrates in South Korean and Taiwanese facilities, exposing deployment timelines to geopolitical friction in semiconductor supply chains.
- Persistence limitations:Volatile memory architectures require redundant battery-backed or Optane-class storage layers, adding architectural complexity that slows adoption in risk-averse healthcare IT environments.
Strategic Opportunities
- India's PLI scheme for data centers:Domestic cloud infrastructure incentives are creating greenfield demand for localized in-memory processing among Mumbai and Bangalore fintech clusters.
- Federated analytics convergence:Integration of differential privacy techniques with in-memory engines enables cross-border data collaboration without raw data movement, opening regulated pharmaceutical R&D use cases.
- Serverless consumption models:AWS and Azure pay-per-query offerings are lowering entry barriers for mid-market retailers in São Paulo and Mexico City seeking seasonal demand forecasting without capital commitment.
Industry Challenges
- SAP HANA migration expertise scarcity:German industrial manufacturers face 12-18 month talent acquisition timelines for certified memory-optimized database architects, delaying supply chain modernization programs.
- HIPAA audit trail engineering:US healthcare systems must reconstruct query-level provenance for every real-time analytics touch on protected health information, requiring custom instrumentation that extends implementation cycles.
- Hybrid cloud data gravity:Financial services firms struggle to maintain performance parity when splitting in-memory workloads across on-premise mainframe data and cloud-resident compute layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Memory Analytics Tools Market |
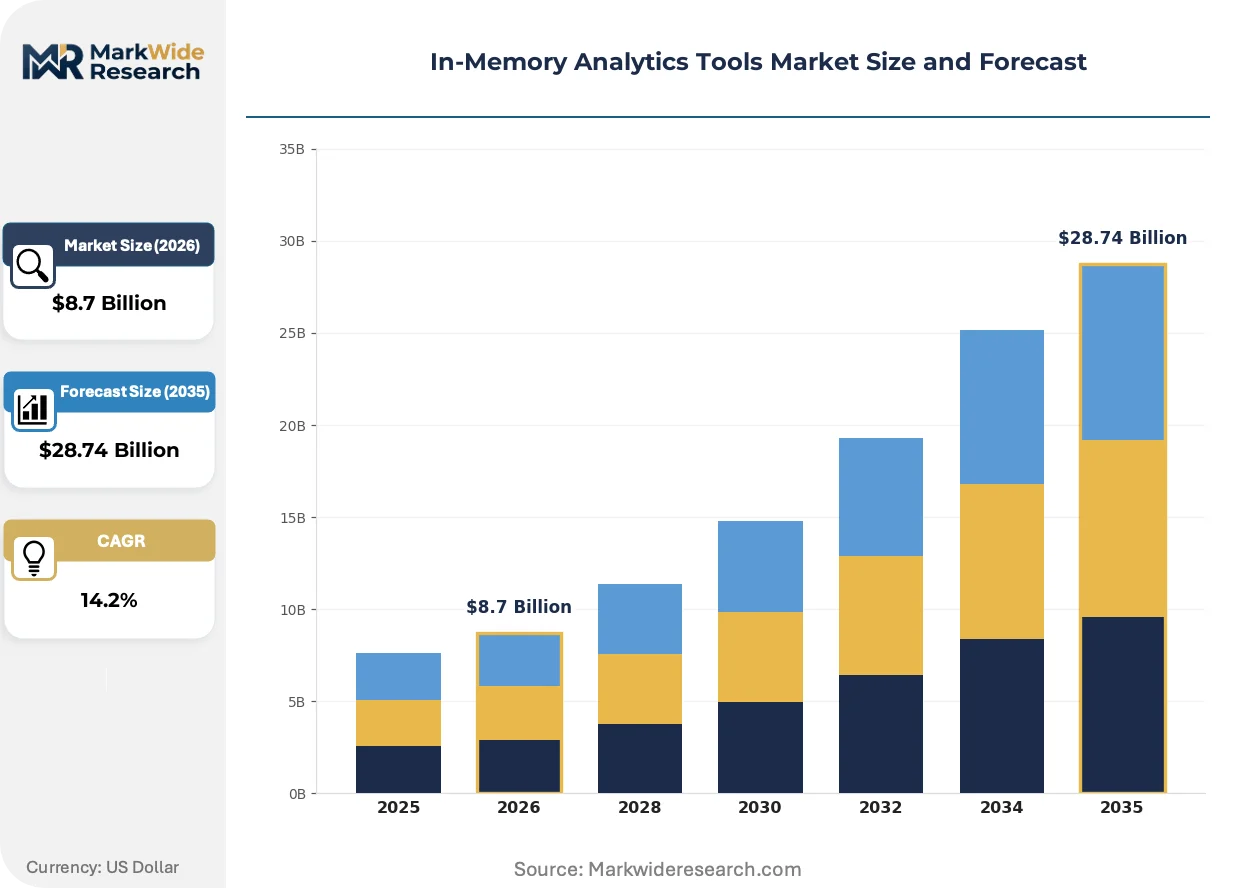
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Tools, Integrated Solutions, Cloud-based Platforms, Desktop Applications Deployment: On-premises, Cloud, Hybrid, Managed Services End User: Retail, Telecommunications, Healthcare, Manufacturing Solution: Real-time Analytics, Predictive Analytics, Business Intelligence, Data Integration |
| Companies Covered | SAP SE, IBM, Oracle, Amazon Web Services, SAS Institute, Microsoft, TIBCO Software, Software AG, Teradata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Memory Analytics Tools Market Shifts & Advancements
Query execution architectures are fragmenting across edge, regional, and centralized memory tiers as latency requirements tighten and data sovereignty rules multiply. This decomposition is reshaping vendor roadmaps and buyer evaluation criteria simultaneously.
Disaggregated memory pools using CXL interconnects are decentralizing how analytics platforms provision capacity. Automotive manufacturers in Stuttgart and Wolfsburg now deploy fabric-attached memory that scales independently from CPU cores, enabling SAP HANA environments to absorb supply chain volatility without hardware overprovisioning. This topology is compressing refresh cycles from five years to eighteen months as memory technology outpaces processor roadmaps.
The EU AI Act's risk-based classification system is mandating technical documentation standards for high-stakes predictive models. Financial services deployers in Frankfurt and Paris must now maintain immutable logs of training data provenance and feature engineering decisions within their in-memory platforms. Healthcare analytics vendors are responding with embedded governance layers that auto-generate regulatory submission packages.
Consumption-based pricing is displacing perpetual licensing across mid-market analytics procurement. Brazilian retail chains and Southeast Asian telecom operators now prioritize serverless in-memory offerings that eliminate capacity planning overhead. This preference shift favors hyperscaler bundled platforms over standalone engine vendors, concentrating purchasing authority within CFO rather than CIO functions.
In-Memory Analytics Tools Market Segmentation
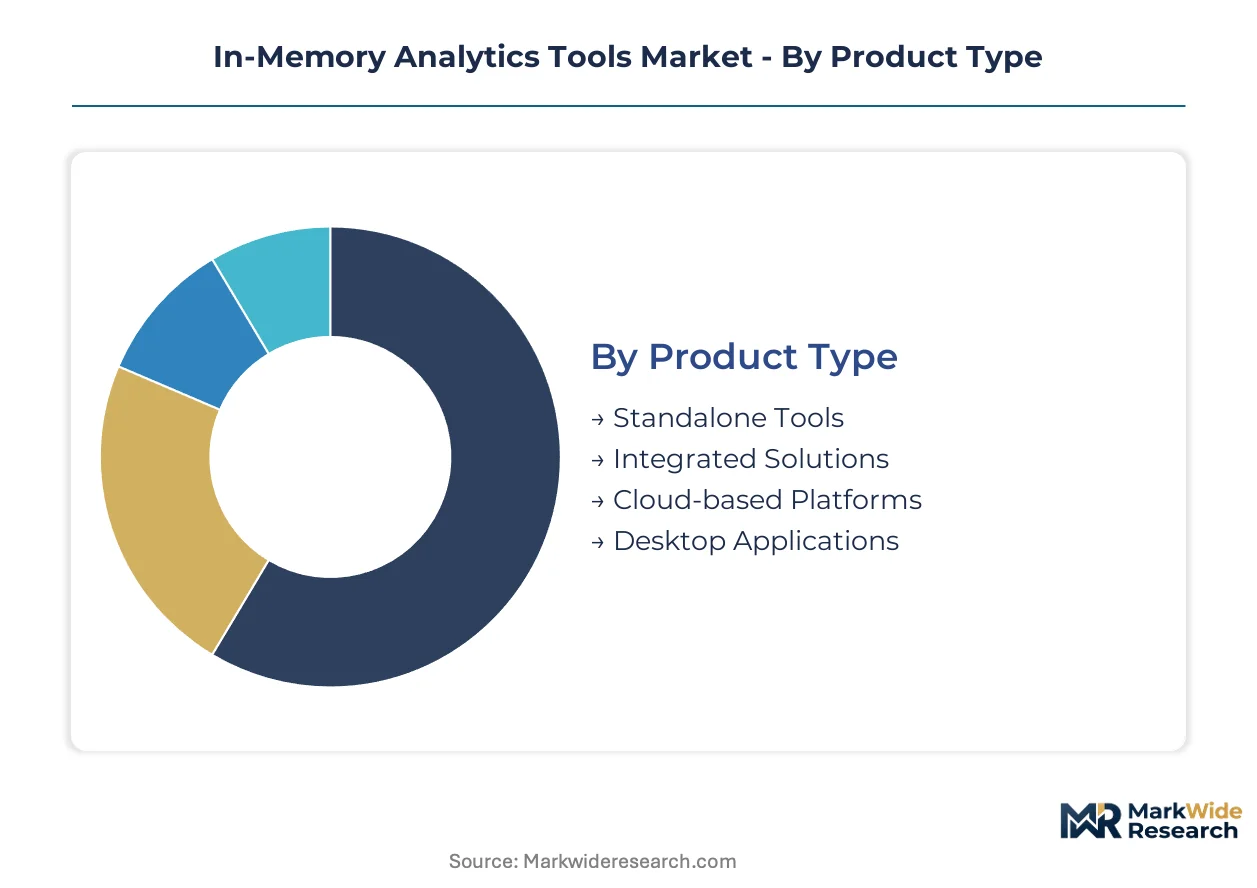
In-memory analytics tools fragment across product architectures, deployment topologies, and functional layers that determine performance boundaries and commercial packaging. Buyers evaluate segments based on query latency requirements, data sovereignty constraints, and integration depth with existing data infrastructure.
Product Type:
Memory-optimized engines differentiate by how tightly they bundle visualization, governance, and data preparation capabilities around the core query execution layer.
- Standalone Tools:Specialized engines expose direct SQL or Python interfaces without platform overhead. Quantitative teams in telecommunications and retail procurement favor these for sub-millisecond query control on proprietary algorithms.
- Integrated Solutions:Vendors bundle memory-optimized engines with data preparation, visualization, and governance layers that lock in recurring revenue. These capture the deepest margin pools by eliminating multi-vendor integration complexity.
- Cloud-based Platforms:Serverless offerings from hyperscalers eliminate provisioning overhead. São Paulo retailers and Mexico City fintechs adopt these for seasonal demand forecasting without capital commitment.
- Desktop Applications:Single-node memory processing for analyst workstations. Limited to datasets under 100GB, serving exploratory analytics before production deployment.
Mature deployment sits with Integrated Solutions. Newer deployment is concentrated in Cloud-based Platforms.
Deployment:
Architecture choice hinges on where data generates versus where regulators permit processing.
- On-premises:Dedicated hardware in enterprise data centers. German automotive manufacturers deploy these for SAP HANA environments that must satisfy GDPR data localization requirements.
- Cloud:Hyperscaler-managed infrastructure with elastic memory scaling. Expanding most quickly as AWS and Azure push serverless offerings that compress procurement cycles.
- Hybrid:Split workloads across mainframe-resident data and cloud-resident compute. Financial services firms struggle to maintain performance parity across this topology.
- Managed Services:Third-party operation of memory-optimized platforms. Appeals to mid-market buyers lacking certified database architect talent.
Established deployments cluster in On-premises. Hybrid architectures show the steepest expansion trajectory among regulated industries.
End User:
Sector-specific latency requirements and compliance exposure shape procurement priorities.
- Retail:Real-time inventory optimization and demand forecasting. Brazilian chains prioritize serverless consumption models to match seasonal volatility.
- Telecommunications:Network performance analytics and customer churn prediction. Sub-100 millisecond requirements drive memory-optimized replacements of disk-based warehouses.
- Healthcare:Real-time clinical decision support and operational analytics. HIPAA audit trail requirements extend implementation cycles for protected health information workloads.
- Manufacturing:Predictive maintenance and supply chain optimization. Stuttgart and Wolfsburg automotive clusters deploy fabric-attached memory for SAP HANA resilience.
Manufacturing holds the deepest incumbent penetration. Healthcare represents the most constrained expansion pathway due to compliance engineering overhead.
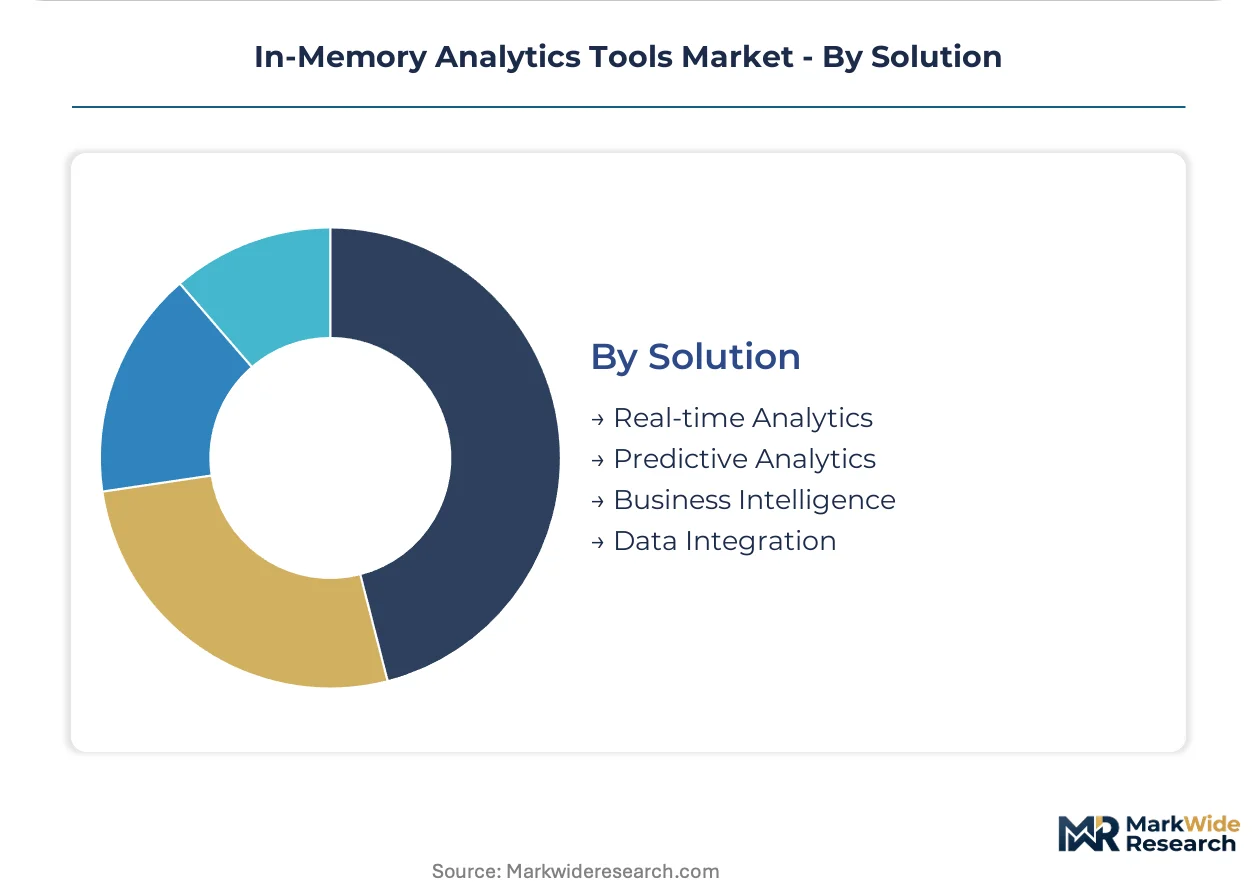
Solution:
Functional modules differentiate by whether they enable retrospective insight or forward-looking automation.
- Real-time Analytics:Sub-second query execution on streaming data. Banking networks require these for transaction scoring within payment processing windows.
- Predictive Analytics:Machine learning models trained and deployed in memory. EU AI Act mandates now require documented training data lineage for high-stakes deployments in Frankfurt and Paris.
- Business Intelligence:Dashboard and reporting layers atop memory-optimized engines. Standardizes executive consumption of operational metrics.
- Data Integration:ETL pipelines that land data in memory-optimized formats. Prepares multi-source inputs for downstream analytics consumption.
Business Intelligence commands the largest installed base. Predictive Analytics faces the tightest regulatory compliance burden as algorithmic transparency rules proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of in-memory analytics platforms concentrates in the United States and Germany, while consumption spreads across financial centers and manufacturing clusters demanding real-time decision infrastructure. Supply chain constraints on server-grade memory components create geographic friction between where platforms are engineered and where they are deployed.
United States
Financial services firms in New York and Chicago drive demand for sub-100 millisecond fraud detection systems that replace legacy disk-based warehouses. HIPAA audit trail requirements constrain healthcare deployments, forcing Cleveland Clinic and Mayo Clinic networks to engineer custom query provenance layers. The SEC's focus on real-time market surveillance pushes broker-dealers toward memory-optimized transaction monitoring.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg anchor European demand through SAP HANA deployments for supply chain optimization. GDPR Article 17 mandates accelerate migration to architectures enabling rapid data purging without batch delays. The KBA's connected vehicle regulations push edge-resident analytics for predictive maintenance on production lines.
Japan
Smart factory initiatives across Osaka and Nagoya industrial clusters mandate edge-resident analytics under METI's Society 5.0 framework. Semiconductor equipment manufacturers in Tokyo deploy memory-optimized quality control systems. The PMDA's digital therapeutics guidelines shape real-time clinical analytics requirements for Osaka-based medical device producers.
India
Mumbai and Bangalore fintech clusters create greenfield demand under the PLI scheme for domestic data center infrastructure. RBI's real-time payment settlement mandates push banks toward memory-optimized transaction processing. Hyderabad's pharmaceutical R&D hubs experiment with federated analytics for cross-border clinical data collaboration.
Brazil
São Paulo retail chains adopt serverless in-memory offerings for seasonal demand forecasting without capital commitment. ANVISA's track-and-trace regulations for pharmaceuticals drive real-time supply chain visibility investments. Rio de Janeiro-based telecom operators deploy memory-optimized network performance analytics for sub-millisecond customer churn prediction.
In-Memory Analytics Tools Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. SAP SE and Oracle anchor the integrated solutions segment through database-centric ecosystems that bundle visualization and governance layers. Microsoft and Amazon Web Services dominate cloud-based platforms through hyperscaler infrastructure advantages. The market structure rewards vertical integration into memory-optimized hardware partnerships and geographic expansion through localized data center deployments.
Within the enterprise software archetype, SAP SE exemplifies the integrated platform approach through its HANA-centric ecosystem. IBM occupies a hybrid cloud position extending mainframe-resident data into memory-optimized layers. Microsoft represents the mid-market cloud expansion vector through Azure Synapse integrations that embed in-memory engines inside broader data platform subscriptions. These three anchors illustrate how vendor strategy fragments across on-premise retention, cloud migration facilitation, and serverless consumption models.
| Leading Market Players |
|---|
| SAP SE |
| IBM |
| Oracle |
| Amazon Web Services |
| SAS Institute |
| Microsoft |
| TIBCO Software |
| Software AG |
| Teradata |
| Others |
Supply & Pricing Matrix
European enterprises migrating to SAP HANA environments under GDPR Article 17 mandates are compressing procurement timelines for server-grade memory components, forcing supply chains to absorb volatility in DDR5 spot pricing without passing full cost through to fixed-price enterprise contracts.
Pricing Analysis
Margin tightening in cloud-based platform tiers reflects hyperscaler serverless offerings that eliminate provisioning overhead and compress customer acquisition costs. Three-tier pricing structure across premium enterprise, standard mid-market, and economy developer levels differentiates by governance depth and SLA guarantees. Cost-down pressure on on-premises deployments accelerates because automotive manufacturers in Stuttgart demand fabric-attached memory scaling without hardware overprovisioning. Mid-market retailers in São Paulo exhibit highest price sensitivity, while German automotive OEMs prioritize performance parity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Taiwanese advanced memory fabrication facilities, exposing deployment timelines to geopolitical friction in semiconductor supply chains. Server-grade DRAM draws from concentrated wafer production in South Korea, Taiwan, and Japan. CXL interconnect controllers and battery-backed persistence layers rest on specialized component suppliers. Tariff exposure on memory module imports creates inventory positioning risk for European system integrators. Distribution runs through hyperscaler direct procurement channels and certified SAP implementation partners serving industrial manufacturing clusters.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DDR5 memory cost volatility and certified architect scarcity are forcing consolidation among standalone tool vendors unable to absorb margin compression or fund talent acquisition programs.
For Market Incumbents: Hedge against silicon supply concentration by securing long-term offtake agreements with South Korean memory fabricators before spot price swings destabilize fixed-price enterprise contracts. Deepen backward integration into CXL interconnect IP to differentiate fabric-attached memory offerings from commodity server configurations. The EU AI Act's algorithmic transparency mandates threaten margins for predictive analytics modules lacking embedded governance layers. For New Entrants and Emerging Players: India's PLI scheme for domestic data centers opens a window for localized in-memory processing offerings targeting Mumbai and Bangalore fintech clusters underserved by hyperscaler latency. Federated analytics convergence with differential privacy techniques represents the most penetrable white-space for pharmaceutical R&D use cases. Go-to-market through AWS and Azure marketplace listings lowers customer acquisition friction for serverless consumption models. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with SAP HANA migration expertise and established relationships with German automotive procurement committees. Mid-cap platform vendors with embedded governance layers and EU AI Act compliance documentation command premium positioning over pure-play engine providers. Watch for CXL interconnect standardization announcements as the signal indicating which memory-disaggregation architectures will dominate next-generation deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Synapse embeddings lock mid-market CFOs into broader data platform subscriptions. |
| Geographic Expansion | Localized data center deployments in India satisfy RBI real-time payment settlement mandates. |
| Strategic Partnership | CXL interconnect collaborations enable fabric-attached memory scaling independent from CPU roadmaps. |
| Acquisition of Specialist Firm | SAP HANA-certified architect teams command 12-18 month talent acquisition timelines in Germany. |
| Product Launch | Serverless pay-per-query offerings lower entry barriers for São Paulo seasonal demand forecasting. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, SAP HANA deployment certifications, and DDR5 spot price indices anchored the trend analysis, supplemented by interviews with CTOs at financial services firms, IT procurement officers in German automotive supply chains, platform engineers at cloud providers, and integration specialists serving healthcare networks. Secondary validation drew from SEC 10-K filings, EMA regulatory submission databases, METI Society 5.0 framework documentation, and customs records of server-grade memory imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped deployment model transitions, organization size adoption curves, vertical compliance exposure, and regional data sovereignty requirements to generate volume and value projections. CAGRs were derived from segment-level growth rate differentials weighted by base-year revenue contribution. Industry-specific forecast inputs included RBI real-time payment mandate timelines, EU AI Act implementation phases, and automotive OEM refresh cycle compression from five years to eighteen months.
Caveats apply where DDR5 memory cost volatility, geopolitical disruption in Taiwanese semiconductor fabrication, or accelerated EU AI Act enforcement could materially shift the outlook. Forecasts reflect documented assumptions about hyperscaler infrastructure expansion rates and SAP HANA migration completion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
TV Analytics Solutions Market
Analytics
Data Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Global Systems of Insight Market
Analytics
Complex Event Processing Market
Analytics
Global Telecom Analytics Market
Analytics
Speech Analytics Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Multi-Touch Attribution Market
Analytics
India Big Data Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Business Value Dashboard Market
Analytics
Global Talent Intelligence Software Market
Analytics
Personal Analytics Market