
 Application Delivery Network (ADN) Market | 2026-2036
Application Delivery Network (ADN) Market Size, Share, and Industry Trends Forecast 2026-2036
Application Delivery Network (ADN) Market Outlook
Premium application delivery controllers with integrated AI-driven traffic management is decoupling from commodity hardware load balancers on price and capability. F5 Networks leverages its hardware-software convergence to sustain margins in enterprise data centers. Akamai Technologies anchors its position through edge-computing density across 4,000 global locations. Cloudflare competes by extending serverless computing into its ADN fabric, blurring infrastructure and application layers.
An application delivery network constitutes a suite of Layer 4-7 services—encompassing global server load balancing, SSL/TLS offloading, TCP optimization, and WAN acceleration—that orchestrates traffic between users and distributed application instances. Cloud-based deployment now leads solution uptake as enterprises abandon capital-intensive appliance refresh cycles; managed services capture expanding margin pools as internal IT teams shrink. Security-integrated solutions within the solution dimension are outpacing standalone web acceleration, reflecting zero-trust architecture mandates.
FCC net-neutrality rulings in the United States, GDPR data-sovereignty requirements across Europe, and China's MIIT cybersecurity review standards collectively shape where ADN providers must localize inspection and encryption handling. ISO 27001 and SOC 2 Type II certifications have become non-negotiable for vendor shortlists in banking and healthcare end-user segments. Stakeholders must weigh sovereign cloud mandates against the latency economics of centralized global architectures when selecting deployment topology.
Market Dynamics
Cloud service providers are forcing a structural reconfiguration of ADN procurement as latency-sensitive workloads migrate from enterprise data centers to distributed edge infrastructure. This shift compresses refresh cycles and elevates managed service preferences over capital-intensive appliance deployments.
Growth Catalysts
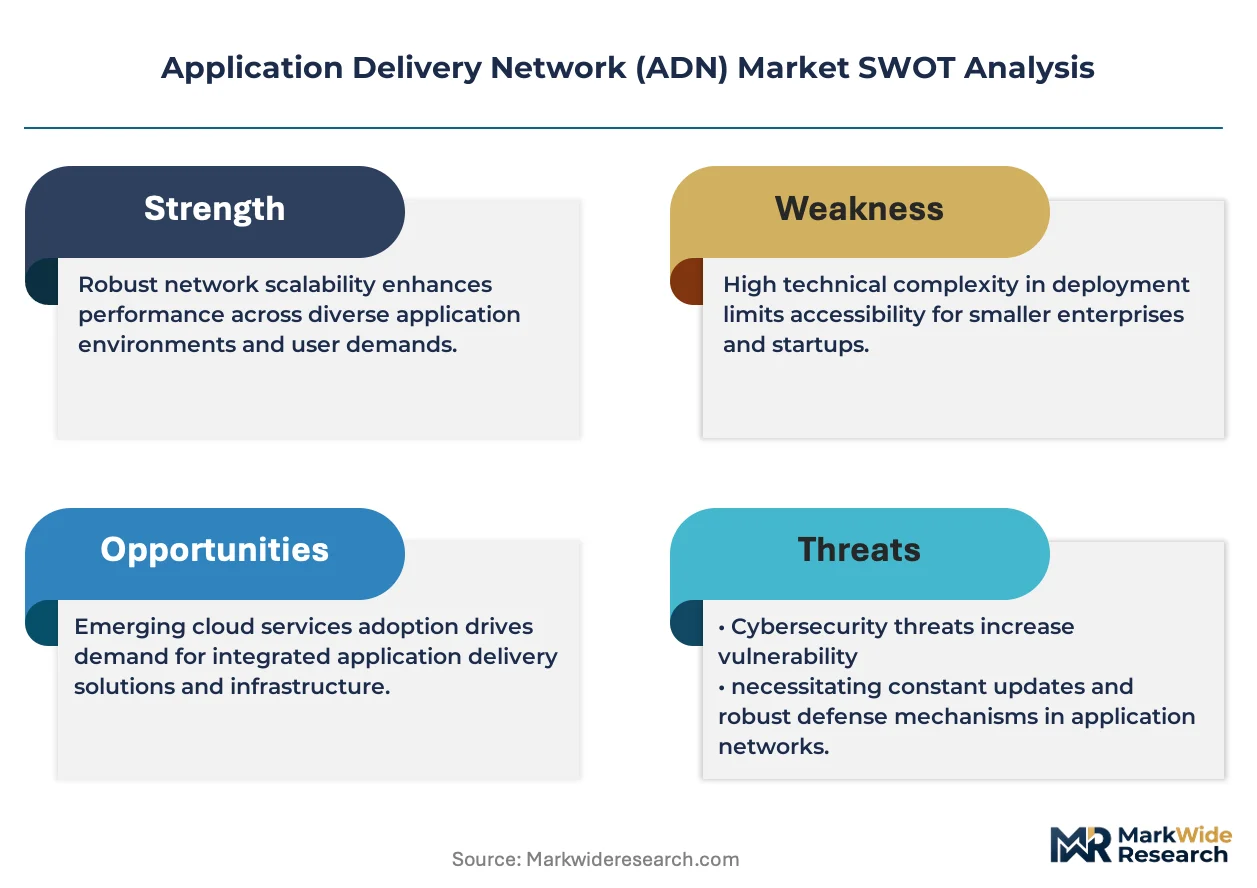
- Zero-trust architecture mandates:Banking and healthcare end-users now require ISO 27001-certified security-integrated solutions, displacing standalone web acceleration products from vendor shortlists.
- United States:FCC net-neutrality rulings compel providers to localize traffic inspection and encryption handling, creating procurement urgency for compliant ADN infrastructure.
- Multi-cloud orchestration:Enterprise consolidation of distributed application instances across heterogeneous cloud environments drives demand for unified Layer 4-7 traffic management.
Market Restraints
- GDPR data-sovereignty requirements:European localization mandates fragment global architectures and inflate operational complexity for centralized providers.
- Skilled traffic engineering talent:Scarce expertise in TCP optimization and WAN acceleration constrains enterprise self-managed deployment options.
- China's MIIT cybersecurity review standards:Foreign ADN providers face extended approval timelines and forced joint venture structures to access domestic demand.
Strategic Opportunities
- Serverless computing convergence:Integration of function-as-a-service into ADN fabrics blurs infrastructure and application layers, opening margin pools in developer-centric segments.
- Edge-computing density expansion:Underserved secondary cities in Germany and Japan present whitespace for localized point-of-presence investments.
- Managed service transition:Shrinking internal IT teams across United States enterprises accelerates outsourcing of SSL/TLS offloading and global server load balancing operations.
Industry Challenges
- Legacy appliance integration:Hybrid environments combining cloud-native ADN services with existing hardware load balancers create configuration complexity and performance inconsistencies.
- SOC 2 Type II certification timelines:Extended audit cycles delay vendor qualification for healthcare and financial services procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Delivery Network (ADN) Market |
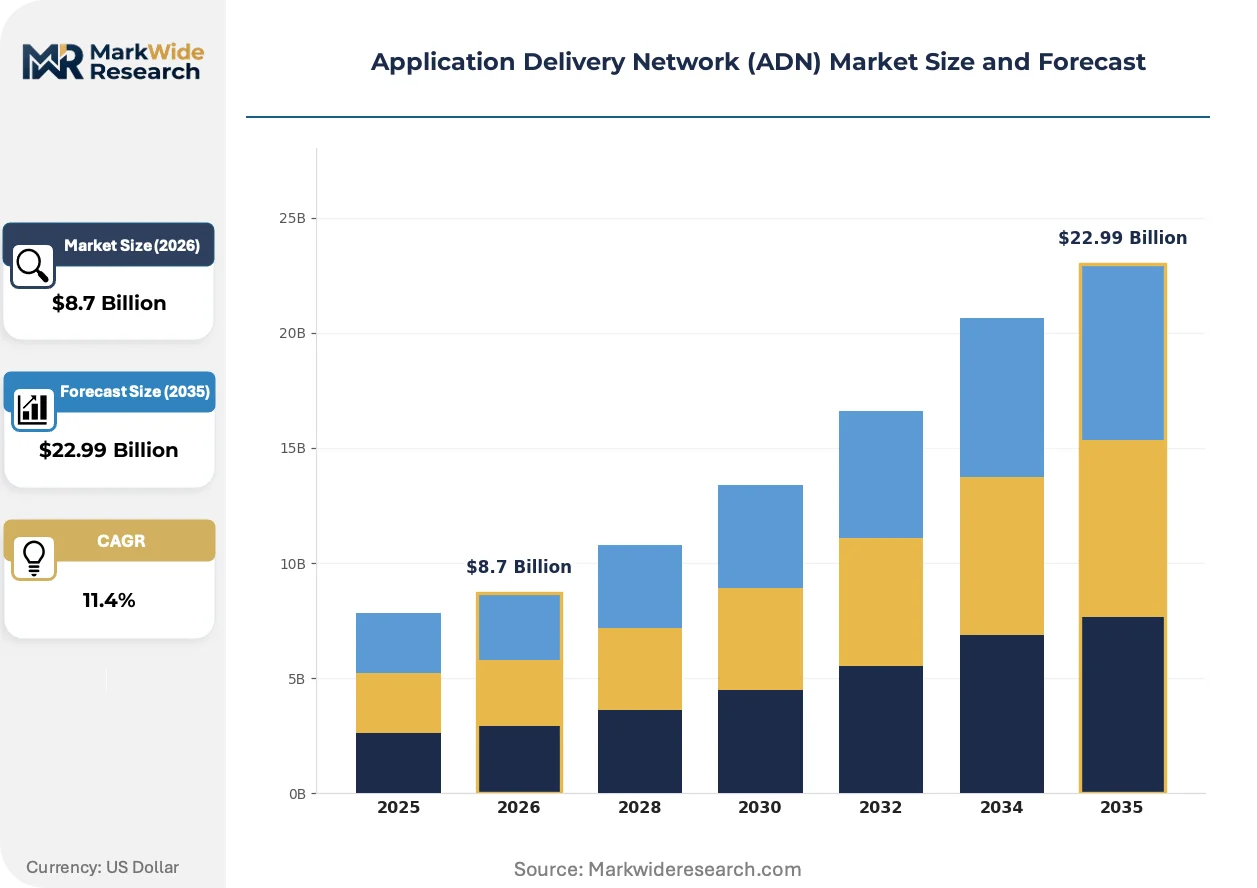
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Solution: Load Balancer, Web Acceleration, Security, Application Optimization End User: Retail, Banking, Telecom, Healthcare Service Type: Managed Services, Professional Services, Consulting, Support |
| Companies Covered | Cisco Systems, A10 Networks, F5 Networks, Radware, Array Networks, Citrix Systems, Fortinet, Cloudflare, Akamai Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Delivery Network (ADN) Market Strategic Shifts
AI-driven traffic management is compressing the traditional boundary between premium hardware controllers and software-defined alternatives. This convergence is redrawing competitive positioning across enterprise data center and cloud-native deployment modes.
Machine learning inference at the network edge is unifying real-time traffic prediction with automated SSL/TLS offloading decisions. Financial services institutions in the United States are deploying these capabilities within twelve-month procurement windows. The technology is unifying previously separate performance optimization and security enforcement budgets into single-platform evaluations.
GDPR's data-sovereignty enforcement is compelling providers to establish independent European encryption key management infrastructure. This regulatory pressure fragments previously centralized global architectures into region-isolated deployments. German automotive and industrial manufacturers are now prioritizing EU-only data residency certifications in ADN vendor selections.
Enterprise procurement teams are consolidating vendor relationships from multi-point solutions toward integrated platform contracts. Managed service providers capturing these consolidated engagements are displacing traditional value-added reseller channels. Japan's manufacturing sector exhibits this concentration most acutely, with trading houses bundling ADN services into broader digital transformation agreements.
Application Delivery Network (ADN) Market Segmentation
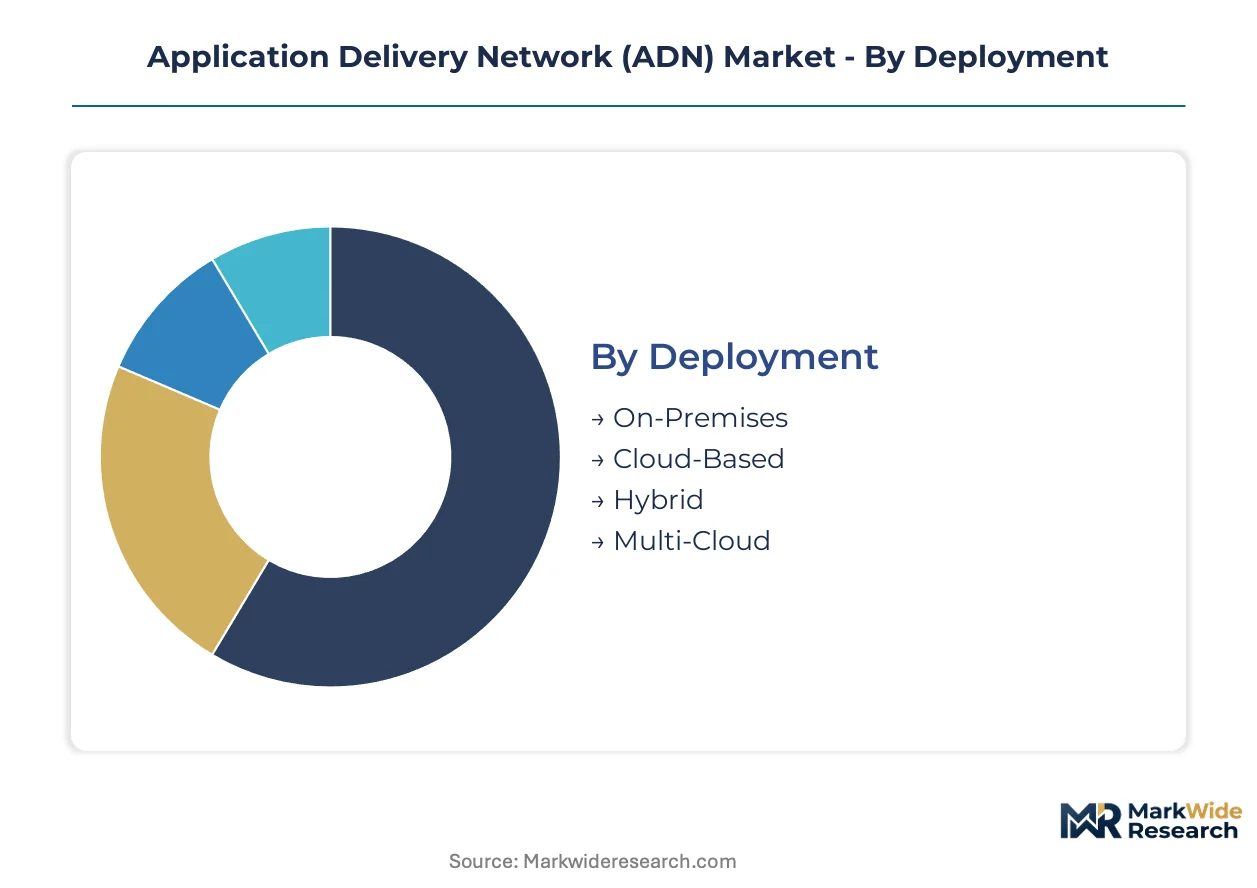
ADN procurement patterns diverge sharply across deployment topologies and buyer sophistication levels. Enterprise infrastructure teams prioritize integration depth while cloud-native adopters favor consumption flexibility and API-driven orchestration.
Deployment:
Cost tier separates capital-intensive buyers from operating-expense optimizers.
- Cloud-Based:Fully managed Layer 4-7 services delivered via subscription models eliminate appliance refresh cycles. United States enterprises shrinking internal IT teams favor this mode for SSL/TLS offloading and global server load balancing without data center footprint.
- Hybrid:Combines on-premises hardware controllers with cloud burst capacity for traffic spikes. German automotive manufacturers deploy this architecture to satisfy GDPR data-sovereignty requirements while maintaining latency-sensitive production floor connectivity.
- On-Premises:Dedicated appliance deployments in enterprise data centers retain control over encryption key management.
- Multi-Cloud:Orchestration across heterogeneous cloud environments unifies traffic management policies.
Cloud-Based leads volumes today; Multi-Cloud is gaining share fastest.
Solution:
Application maturity determines which capability buyers prioritize first.
- Security:Integrated zero-trust enforcement with ISO 27001-certified SSL/TLS inspection and DDoS mitigation. Banking and healthcare end-users in the United States now mandate this category as a procurement prerequisite, displacing standalone alternatives from vendor shortlists.
- Load Balancer:Traffic distribution across distributed application instances with health monitoring and failover automation. Japan's manufacturing sector concentrates demand here for ensuring continuous availability of supply chain management platforms.
- Web Acceleration:TCP optimization and content compression for static asset delivery.
- Application Optimization:WAN acceleration and protocol tuning for dynamic application performance.
Security leads volumes today; Application Optimization is expanding most quickly.
End User:
Regulatory exposure shapes procurement urgency and certification requirements.
- Banking:Financial institutions require SOC 2 Type II and ISO 27001 compliance for all ADN infrastructure. FCC net-neutrality rulings compel United States banks to localize traffic inspection, accelerating compliant solution procurement.
- Healthcare:HIPAA-covered entities demand encrypted data transmission with audit logging. Patient data sovereignty requirements drive preference for hybrid deployments with on-premises key custody.
- Retail:E-commerce platforms prioritize edge-computing density for seasonal traffic spikes.
- Telecom:Carriers leverage ADN infrastructure for content delivery network federation and subscriber experience management.
Banking leads volumes today; Healthcare shows the steepest expansion trajectory.
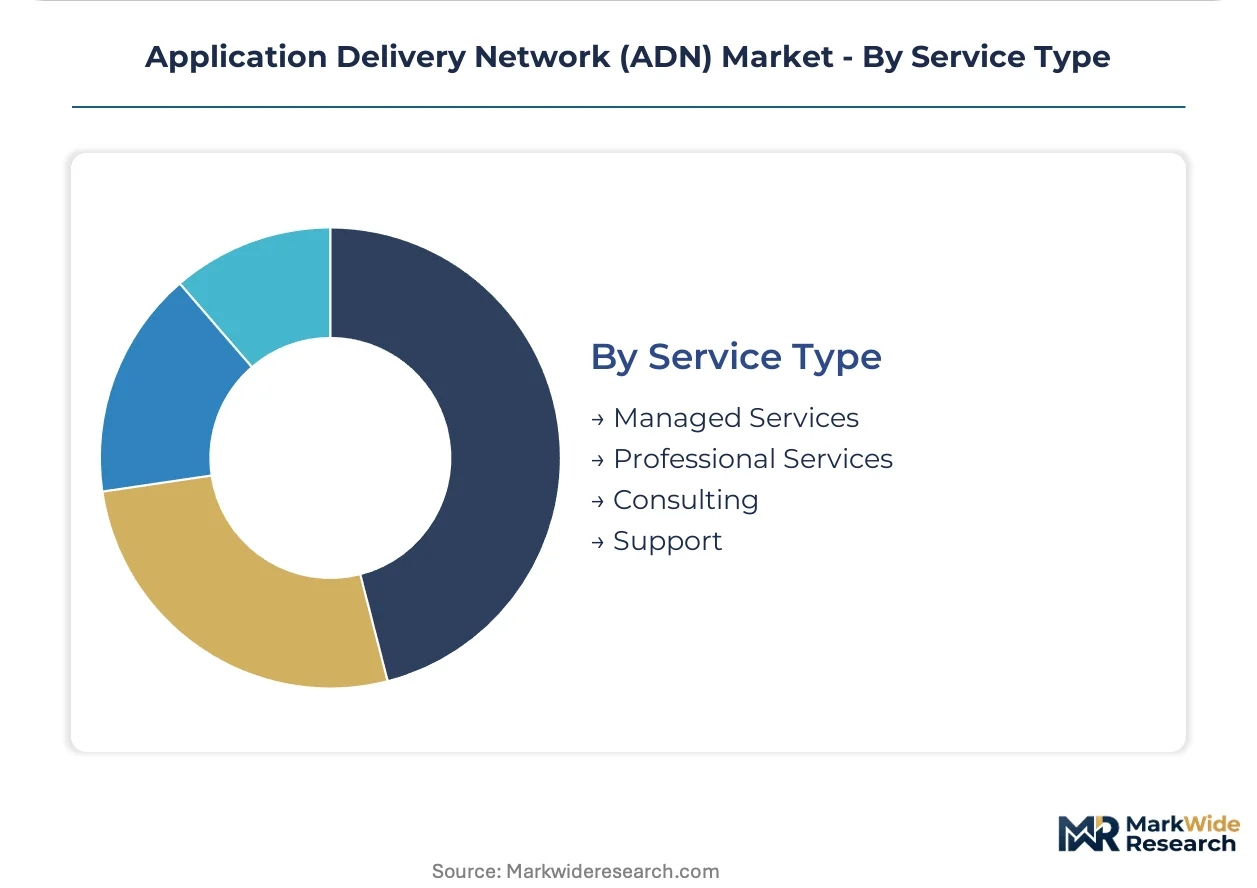
Service Type:
Internal capability gaps determine outsourcing depth versus co-managed arrangements.
- Managed Services:Fully outsourced operation of SSL/TLS offloading, global server load balancing, and security policy enforcement. United States enterprises with shrinking traffic engineering teams favor this model for 24/7 operational coverage without specialist hiring.
- Professional Services:Implementation and integration support for complex multi-cloud orchestration deployments. Germany's industrial manufacturers engage these services for GDPR-compliant architecture design.
- Consulting:Advisory engagements for zero-trust architecture planning and vendor selection.
- Support:Break-fix and maintenance contracts for existing appliance deployments.
Managed Services leads volumes today; Professional Services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized traffic engineering talent concentrates in the United States, Germany, and Japan, anchoring procurement intensity for enterprise-grade Layer 4-7 infrastructure. These markets exhibit divergent regulatory pressures and deployment preferences that fragment vendor go-to-market strategies.
United States
Financial services institutions and cloud-native enterprises drive demand for AI-driven traffic management and zero-trust security integration. FCC net-neutrality rulings compel providers to localize traffic inspection and encryption handling, creating procurement urgency for compliant infrastructure. New York and San Francisco Bay Area technology clusters concentrate managed service adoption as internal IT teams shrink.
Germany
Automotive and industrial manufacturers prioritize hybrid deployments balancing GDPR data-sovereignty requirements with production floor latency constraints. The country's national data protection regulator enforces strict EU-only data residency certifications, fragmenting previously centralized global architectures. Stuttgart and Munich industrial corridors anchor demand for ISO 27001-certified SSL/TLS offloading solutions.
Japan
Manufacturing trading houses bundle ADN services into broader digital transformation agreements, consolidating multi-point vendor relationships into integrated platform contracts. METI industrial standards shape procurement specifications for supply chain management platform availability. Nagoya and Osaka manufacturing clusters exhibit acute concentration in global server load balancing for continuous operations.
China
Domestic cloud service providers expand ADN adoption to manage latency-sensitive workloads across distributed edge infrastructure. MIIT cybersecurity review standards impose extended approval timelines and forced joint venture structures on foreign providers accessing domestic demand. Shanghai and Beijing technology corridors develop indigenous alternatives to Western appliance vendors.
United Kingdom
Financial services and healthcare institutions demand SOC 2 Type II and ISO 27001 compliance for outsourced SSL/TLS operations. GDPR alignment through the UK GDPR framework maintains data-sovereignty requirements post-Brexit. London's fintech concentration drives preference for cloud-based managed services over capital-intensive hardware refresh cycles.
Application Delivery Network (ADN) Market Competitive Environment
Top-tier vendors anchor enterprise data center and cloud-native segments, while mid-tier specialists occupy regional niches and vertical-specific deployments. The market exhibits tiered concentration with hardware-software convergence specialists commanding premium positioning against commodity load balancer providers. Two strategic archetypes dominate: edge-computing density builders pursuing geographic expansion, and security-integrated platform vendors capturing consolidated procurement budgets. Competitive moves center on managed service transitions and multi-cloud orchestration capability acquisition.
Within the security-integrated tier, F5 Networks and Fortinet exemplify hardware-software convergence strategies sustaining margin positions in enterprise infrastructure. Akamai Technologies anchors edge-computing density archetypes through distributed point-of-presence investments. Cloudflare occupies a position blurring infrastructure and application layers via serverless computing extensions. These three vendors represent divergent responses to cloud service provider procurement reconfiguration and zero-trust architecture mandates.
| Leading Market Players |
|---|
| Cisco Systems |
| A10 Networks |
| F5 Networks |
| Radware |
| Array Networks |
| Citrix Systems |
| Fortinet |
| Cloudflare |
| Akamai Technologies |
| Others |
Value Chain & Pricing Dynamics
AI-driven traffic management compression is simultaneously collapsing hardware-software cost boundaries and concentrating procurement leverage among cloud-native buyers with volume scale. This technological convergence fragments legacy appliance margins while elevating subscription-based pricing power for integrated platform vendors.
Pricing Analysis
Bundled security-integrated solutions command premium positioning against unbundled load-balancing commodities. Pricing stratifies across premium AI-enabled controllers, standard cloud-managed tiers, and economy appliance refreshes, with ISO 27001 certification tier and edge-computing density as primary price differentiation drivers. Cost compression in the hardware appliance tier is intensifying because cloud service providers are absorbing traffic engineering into managed service bundles. Banking and healthcare end-users in the United States exhibit lowest price sensitivity due to compliance mandates, while retail e-commerce platforms show highest sensitivity to per-GB bandwidth charges.
Supply Chain Analysis
Freight cost volatility for specialized networking hardware is elevating regional manufacturing preference across semiconductor-dependent controller production. Supply concentrates in Taiwan for advanced ASIC fabrication, China for commodity appliance assembly, and the United States for security-integrated software development. Raw material dependencies include high-performance memory modules, SSL/TLS acceleration chips, and specialized network processors. Single-source vulnerability for edge-computing point-of-presence real estate in tier-one markets constrains rapid geographic expansion. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between GDPR-constrained European deployments and latency-optimized United States infrastructure creates procurement cost differentials of 15-25% for equivalent capability tiers. Regulatory fragmentation rewards vendors with modular deployment architectures.
For Market Incumbents: To counter serverless computing convergence by Cloudflare and emerging edge-native challengers, deepen API-driven orchestration capabilities and acquire ISO 27001-certified managed service operations in Germany. Capacity addition in Stuttgart and Munich industrial corridors secures automotive manufacturer procurement pipelines against sovereign cloud mandates.
For New Entrants and Emerging Players: Managed service providers with 24/7 operational coverage represent the most penetrable channel partner type for bypassing established hardware-software incumbents. Target healthcare hybrid deployments in Japan's Nagoya manufacturing cluster where HIPAA-equivalent METI standards create compliance complexity incumbents underserve. Position through professional services-led GDPR architecture design for German automotive suppliers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional managed service specialists with ISO 27001 certification gaps and concentrated healthcare banking client bases. Long-term viability hinges on multi-cloud orchestration capability depth rather than point-of-presence count alone. Watch for FCC net-neutrality enforcement actions as signal for compliant infrastructure procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Density Expansion | Localized point-of-presence investments in Germany's secondary cities capture GDPR-constrained automotive demand. |
| Security-Integrated Platform Convergence | Zero-trust architecture bundling unifies previously separate performance optimization and security enforcement budgets. |
| Managed Service Transition | Outsourced SSL/TLS operations capture margin pools as United States enterprise IT teams shrink. |
| Multi-Cloud Orchestration Acquisition | Heterogeneous cloud traffic management capabilities address enterprise consolidation of distributed application instances. |
| Serverless Computing Extension | Function-as-a-service integration blurs infrastructure and application layers for developer-centric segments. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market's enterprise infrastructure decision-makers. The approach combines structured interviews with data center architects, cloud procurement officers, traffic engineering specialists, and managed service provider executives with secondary validation through SEC filings, hyperscaler capex disclosures, FCC regulatory dockets, and GDPR enforcement actions. Bottom-up deployment topology modeling triangulates against top-down cloud service provider revenue attribution.
Rate-of-change decomposition separates volume growth from value migration across deployment modes. The analytical framework segments by cloud-based, hybrid, on-premises, and multi-cloud topologies; security, load balancer, web acceleration, and application optimization solutions; and banking, healthcare, retail, and telecom end-users. CAGRs derive from elasticity-adjusted adoption curves and regulatory compliance deadline clustering. Edge-computing density investments and ISO 27001 certification penetration serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC net-neutrality enforcement intensity, GDPR data-sovereignty interpretation shifts, and MIIT cybersecurity review timeline extensions. Forecasts reflect documented assumptions about cloud migration velocity and zero-trust architecture mandate adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Global Software Defined Networking (SDN) Market