
 Global Software Defined Networking (SDN) Market | 2026-2036
Global Software Defined Networking (SDN) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software Defined Networking (SDN) Market Intelligence
Shortage of network engineers fluent in Python-based automation and YANG data modeling is collapsing deployment timelines for enterprise SDN rollouts. Cisco Systems dominates campus and branch SDN through its DNA Center platform and extensive channel footprint. Juniper Networks differentiates in service provider cores with its Contrail architecture and strong BGP-EVPN integration. Huawei Technologies anchors massive-scale deployments across Asia-Pacific through competitive pricing on its CloudEngine switches and iMaster NCE controller.
Software Defined Networking refers to an architecture that decouples network control logic from underlying forwarding hardware, using centralized controllers with southbound protocols such as OpenFlow or NETCONF to program data-plane behavior across multivendor infrastructure. Its primary purpose is enabling programmatic network management, automated provisioning, and policy-driven traffic engineering across distributed environments. Controller solutions currently command the largest share of solution-type revenue because every deployment requires this central brain for topology discovery and flow rule distribution. Hybrid cloud deployments are expanding fastest among deployment models as enterprises straddle on-premises VMware estates with AWS and Azure connectivity.
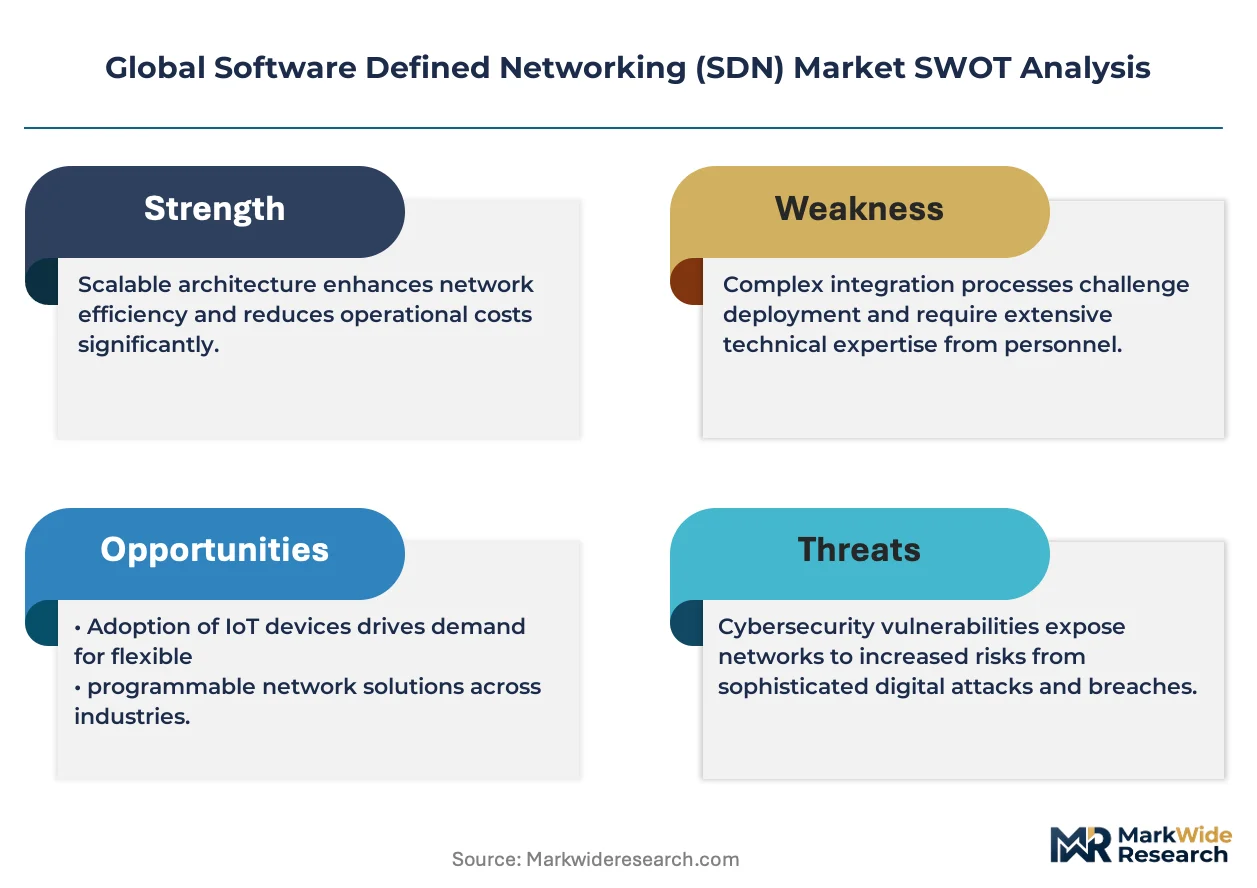
The Federal Communications Commission shapes US carrier SDN investment through spectrum auction conditions and network resilience mandates, while the European Telecommunications Standards Institute drives interoperability requirements that influence controller procurement across EU member states. China's Ministry of Industry and Information Technology accelerates domestic SDN adoption through its GB standards for cloud infrastructure and data center efficiency targets. Stakeholders must weigh whether to build in-house controller expertise or outsource to cloud-native network-as-a-service platforms as operational complexity outpaces available engineering talent pools.
Market Dynamics
Enterprise migration from hardware-centric to software-driven network architectures is redirecting procurement budgets toward programmable controllers and overlay platforms, compressing traditional switch-router upgrade cycles.
Growth Catalysts
- Federal cloud-first mandates:United States government agencies accelerate SDN controller deployment to satisfy zero-trust architecture requirements and modernize legacy infrastructure.
- Hyperscale data center buildouts:Amazon Web Services, Microsoft Azure, and Google Cloud expand physical footprints, driving demand for automated traffic engineering and east-west bandwidth optimization.
- NIST cybersecurity frameworks:Financial services institutions modernize under these guidelines, redirecting capital toward policy-driven segmentation and microsegmentation capabilities.
Market Restraints
- Silicon supply concentration:Advanced merchant silicon for programmable data planes concentrates among Taiwan Semiconductor Manufacturing and Broadcom, creating single-source vulnerability for white-box switch vendors.
- Legacy protocol inertia:Spanning Tree Protocol and proprietary vendor CLI dependencies persist in brownfield campuses, delaying controller-overlay adoption.
- Operational skill scarcity:Python-based automation and YANG data modeling expertise remains concentrated among cloud-native enterprises, collapsing deployment timelines for mid-market organizations.
Strategic Opportunities
- India data center expansion:The country's PLI scheme for electronics manufacturing and cloud infrastructure targets attracts hyperscale investment, creating greenfield SDN deployment pipelines.
- 5G transport network slicing:Convergence of SDN controllers with radio access network orchestrators enables guaranteed latency tiers for industrial automation and autonomous vehicle backhaul.
- Network-as-a-service channels:Managed service providers bundle controller expertise with subscription pricing, bypassing enterprise talent constraints and compressing sales cycles.
Industry Challenges
- Controller-to-device integration complexity:Multivendor environments require custom southbound protocol adapters, extending proof-of-concept phases and eroding project ROI.
- Intent-based networking certification gaps:Vendor-specific designations fail to transfer across Cisco DNA Center, Juniper Mist, and VMware NSX deployments, fragmenting labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software Defined Networking (SDN) Market |
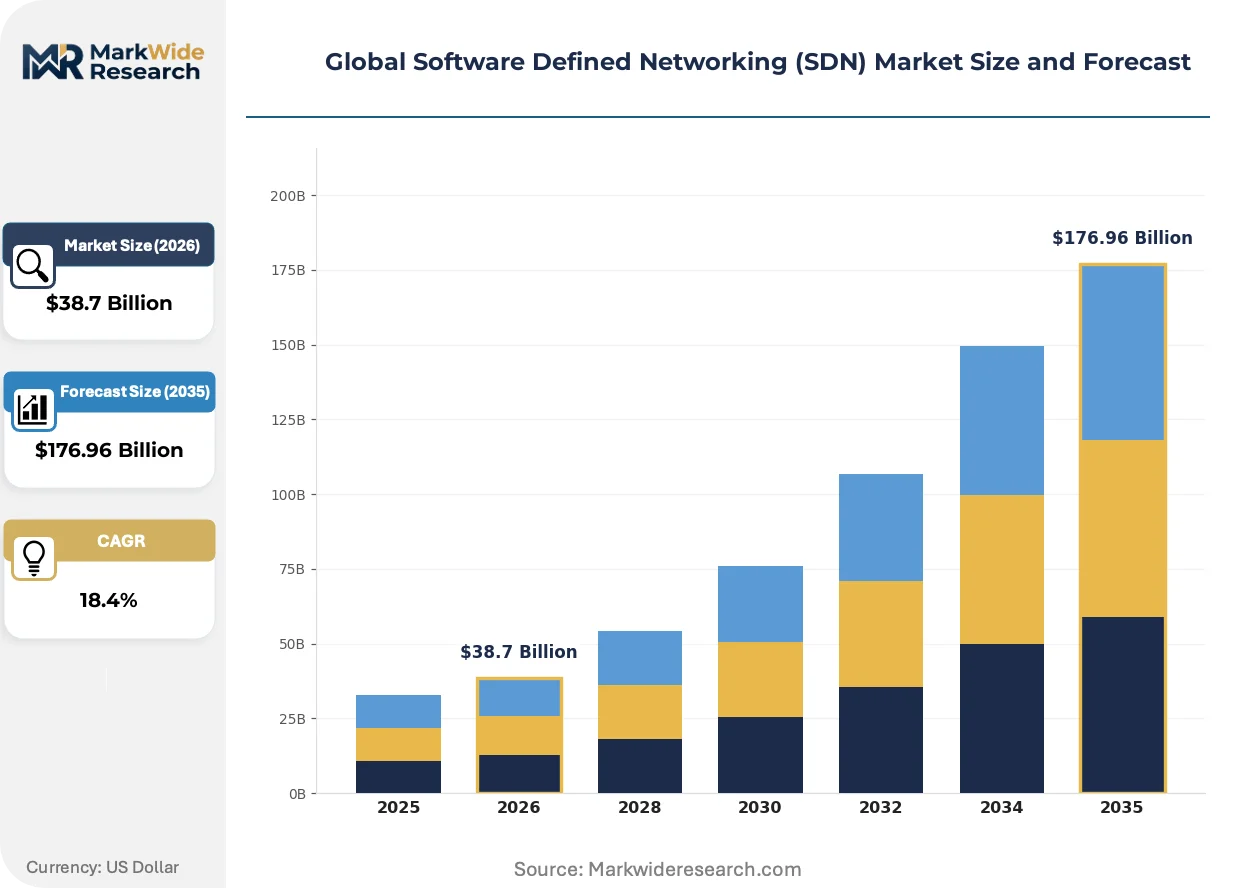
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution Type: Controller, Switch, Application, Security, Analytics Use Case: Data Center Optimization, Network Virtualization, Traffic Engineering, Policy Control, Cloud Orchestration End User Industry: Telecommunications, Financial Services, Government, Manufacturing, Education |
| Companies Covered | Hewlett Packard Enterprise, IBM Corporation, Cisco Systems, Dell Technologies, Arista Networks, Juniper Networks, Huawei Technologies, Nokia Corporation, VMware (Broadcom), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software Defined Networking (SDN) Market Strategic Shifts & Innovations
Intent-based networking interfaces and AI-driven anomaly detection are supplanting CLI-centric operations, compressing mean-time-to-resolution and flattening organizational hierarchies between architects and operators.
API-first controller architectures are supplanting traditional SNMP and CLI management planes in large enterprises. Financial services institutions in London and Singapore deploy these interfaces to automate compliance verification and policy propagation. The shift is compressing operational headcount ratios from one engineer per thousand ports toward one per ten thousand ports.
The European Telecommunications Standards Institute's multi-domain service orchestration specifications are forcing controller vendors to expose standardized northbound interfaces. European Union member state procurement guidelines now reference these requirements, disqualifying proprietary-only platforms. German and French carriers accelerate RFP processes that mandate ETSI-NFV alignment for transport SDN layers.
Consumption-based licensing for controller software is displacing perpetual entitlement models in mid-market enterprise accounts. Value-added distributors in the United States and United Kingdom now meter overlay node counts monthly, transferring capacity risk from buyer to vendor. This shift accelerates in healthcare verticals where capital budget volatility complicates three-year hardware refresh planning.
Global Software Defined Networking (SDN) Market Segmentation
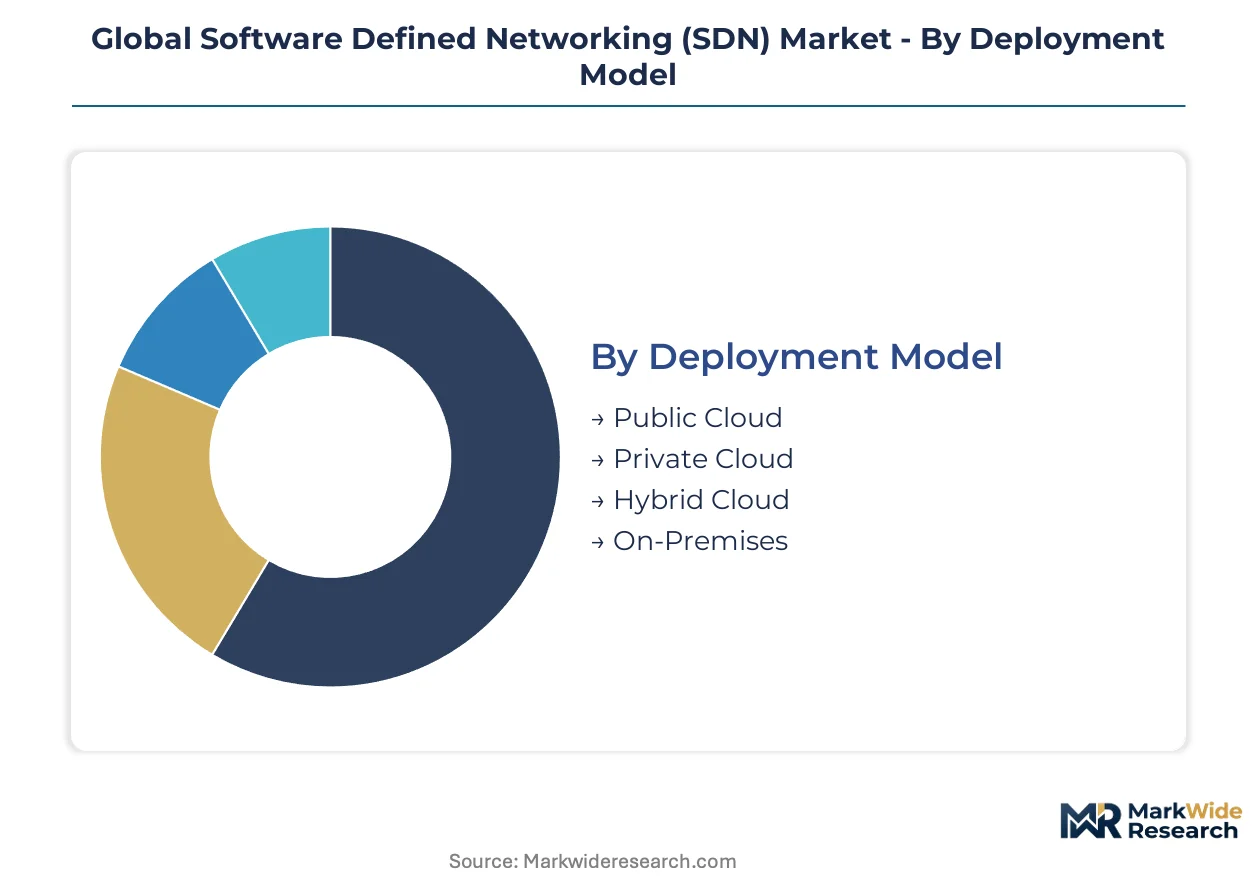
SDN procurement patterns diverge sharply across deployment models and verticals, with channel strategy determining which segments flow through direct enterprise sales versus systems integrators. Solution architecture choices cascade through controller selection, switch hardware, and professional services attach rates.
Deployment Model:
Channel economics vary dramatically: hyperscale deployments flow through direct OEM relationships, while mid-market hybrid clouds route through value-added distributors with metered licensing programs.
- Public Cloud:Native controller integration with AWS, Azure, and Google Cloud Platform delivers API-driven network provisioning without customer-managed infrastructure. Financial services institutions in Singapore and London deploy these configurations to automate compliance verification across multi-region footprints.
- Hybrid Cloud:Bridging on-premises VMware estates with public cloud connectivity demands overlay controllers capable of unified policy propagation. German automotive manufacturers and US healthcare systems drive expansion here as capital budget volatility complicates three-year hardware refresh planning.
- Private Cloud:Single-tenant controller deployments serve regulated industries requiring data sovereignty guarantees.
- On-Premises:Traditional appliance-based controllers persist in brownfield campuses with Spanning Tree Protocol dependencies.
On-Premises dominates installed base. Hybrid Cloud is where expansion concentrates.
Solution Type:
Margin profiles separate controller software with recurring revenue streams from commodity switch hardware facing pricing pressure from white-box alternatives.
- Controller:Centralized control planes with southbound OpenFlow or NETCONF interfaces program data-plane behavior across multivendor infrastructure. Every deployment requires this topology discovery and flow rule distribution engine, concentrating procurement budgets here.
- Security:Policy-driven segmentation and microsegmentation modules attach to controller cores, with NIST framework compliance driving financial services procurement. US federal cloud-first mandates accelerate zero-trust architecture deployments here.
- Switch:Programmable data-plane hardware from merchant silicon vendors.
- Application:Northbound network services consuming controller APIs.
- Analytics:AI-driven anomaly detection modules compressing mean-time-to-resolution.
Controller solutions anchor vendor profitability. Security modules are climbing the fastest as compliance requirements tighten.
Use Case:
Technical complexity and professional services intensity escalate from traffic engineering through full cloud orchestration.
- Data Center Optimization:East-west bandwidth automation and workload-aware traffic engineering reduce oversubscription in hyperscale facilities. Amazon Web Services, Microsoft Azure, and Google Cloud physical expansions concentrate demand here.
- Cloud Orchestration:Multi-domain service orchestration spanning compute, storage, and network resources requires ETSI-NFV-aligned controllers. European Union procurement guidelines now mandate these standardized northbound interfaces, disqualifying proprietary-only platforms.
- Network Virtualization:Overlay abstraction of physical infrastructure.
- Traffic Engineering:Programmable path selection for bandwidth optimization.
- Policy Control:Centralized enforcement of segmentation and quality-of-service rules.
Data Center Optimization commands current spending. Cloud Orchestration shows the steepest expansion trajectory as Kubernetes adoption deepens.
End User Industry:
Procurement sophistication separates telecommunications carriers with internal engineering teams from manufacturing enterprises outsourcing to managed service providers.
- Telecommunications:Service provider cores demand BGP-EVPN integration and 5G transport network slicing capabilities. India's PLI scheme for electronics manufacturing attracts hyperscale investment, creating greenfield deployment pipelines for domestic carriers.
- Financial Services:Policy-driven microsegmentation and automated compliance verification dominate procurement criteria. NIST cybersecurity frameworks redirect capital toward programmable segmentation in London, Singapore, and New York institutions.
- Government:Federal cloud-first mandates and zero-trust architecture requirements accelerate US agency modernization.
- Manufacturing:Industrial automation latency requirements drive 5G transport SDN deployments.
- Education:Capital-constrained institutions favor consumption-based licensing through managed service channels.
Telecommunications retains the largest installed base. Financial Services is gaining share fastest as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum auction conditions and federal cloud-first mandates anchor United States demand, while ETSI interoperability requirements redirect procurement across European Union member states. China's MIIT accelerates domestic adoption through GB standards for data center efficiency.
United States
Hyperscale data center buildouts by Amazon Web Services, Microsoft Azure, and Google Cloud concentrate controller deployment in Northern Virginia, Dallas-Fort Worth, and Phoenix. FCC network resilience mandates shape carrier SDN investment timelines. Financial services institutions in New York and Chicago modernize legacy infrastructure under NIST cybersecurity frameworks.
Germany
Automotive manufacturers in Stuttgart and Munich drive hybrid cloud SDN adoption bridging on-premises VMware estates with cloud connectivity. ETSI multi-domain service orchestration specifications force controller vendors to expose standardized northbound interfaces. Frankfurt's financial services cluster deploys policy-driven microsegmentation for automated compliance verification.
China
MIIT's GB standards for cloud infrastructure and data center efficiency targets accelerate domestic SDN controller deployment. Huawei Technologies anchors massive-scale implementations across Beijing, Shanghai, and Shenzhen through competitive pricing on programmable switches. State-owned carriers expand transport network slicing capabilities for industrial automation backhaul.
India
The PLI scheme for electronics manufacturing and cloud infrastructure targets attracts hyperscale investment to Mumbai, Bangalore, and Hyderabad. Domestic carriers deploy greenfield SDN pipelines for 5G transport networks. Data center operators automate east-west bandwidth optimization as capacity expands.
United Kingdom
Financial services institutions in London deploy API-first controller architectures to automate compliance verification across multi-region footprints. ETSI-NFV alignment requirements accelerate RFP processes for transport SDN layers. Manchester and Edinburgh emerge as secondary data center clusters demanding overlay controllers for unified policy propagation.
Global Software Defined Networking (SDN) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the SDN market. The vendor base separates into three tiers: incumbent networking equipment suppliers with channel dominance, cloud-native software specialists with API-first architectures, and white-box hardware vendors with merchant silicon strategies. Consolidation pressures favor players with controller software recurring revenue over commodity switch vendors facing pricing pressure. Dominant competitive moves include strategic partnerships between controller vendors and hyperscale cloud providers, plus geographic expansion into India's data center buildout pipeline.
Within the incumbent networking tier, Cisco Systems and Juniper Networks occupy positions defined by campus-to-core coverage and service provider specialization respectively. Cisco's DNA Center platform exemplifies channel-anchored deployment models, while Juniper's Contrail architecture represents BGP-EVPN integration depth for carrier cores. Arista Networks sits within the cloud-native tier, its presence concentrated among hyperscale data center operators demanding API-driven provisioning without legacy protocol dependencies.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| IBM Corporation |
| Cisco Systems |
| Dell Technologies |
| Arista Networks |
| Juniper Networks |
| Huawei Technologies |
| Nokia Corporation |
| VMware (Broadcom) |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with Taiwan Semiconductor Manufacturing and Broadcom lock in merchant silicon access while freezing controller software pricing for hyperscale data center operators across Northern Virginia and Dallas-Fort Worth. These contractual structures transfer inventory risk to buyers while insulating white-box switch vendors from spot-market volatility in programmable data-plane components.
Pricing Analysis
Controller licensing spreads 40-60% between US East Coast financial services deployments and Asia-Pacific education verticals. Consumption-based SaaS tiers for overlay platforms dominate mid-market procurement, with metered node counts replacing perpetual entitlements. Pricing pressure stems from white-box switch commoditization eroding hardware margins. Healthcare systems show highest price sensitivity due to capital budget volatility, while telecommunications carriers absorb premium positioning for 5G transport slicing capabilities.
Supply Chain Analysis
Strategic stockpiling of merchant silicon concentrates among Taiwan, South Korea, and USA fabrication facilities, with just-in-time controller software delivery preferred for cloud-native deployments. Advanced programmable chips draw from TSMC 7nm/5nm nodes, Broadcom Tomahawk silicon, and Intel Tofino pipelines. Single-source vulnerability runs through Taiwan Strait logistics chokepoints. Distribution runs through value-added distributors with metered licensing programs for mid-market hybrid cloud accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SDN market is recovering from cyclical infrastructure compression as hyperscale capital expenditure cycles turn upward following federal cloud-first mandate acceleration.
For Market Incumbents: Consolidate controller software recurring revenue streams through channel-anchored DNA Center deployments while divesting commodity switch hardware facing white-box pricing erosion. Acquire Python-based automation talent pools to collapse deployment timelines for enterprise rollouts. Prioritize ETSI-NFV certification alignment to maintain European Union carrier RFP eligibility. For New Entrants and Emerging Players: Fast-track ETSI multi-domain service orchestration certification to bypass proprietary platform lock-in across German automotive and French carrier procurement channels. Target India's PLI-scheme data center greenfield deployments where domestic carrier engineering teams lack legacy protocol dependencies. Lead with API-first architectures bypassing CLI-centric brownfield constraints. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native controller specialists with recurring SaaS revenue and hyperscale cloud provider partnerships. Long-term viability hinges on intent-based networking interface differentiation compressing operational headcount ratios. Watch for inflection when federal zero-trust architecture mandates accelerate beyond current NIST framework compliance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies VMware estates with AWS and Azure connectivity for German automotive manufacturers. |
| Strategic Partnership | Links controller vendors to hyperscale cloud providers in Northern Virginia data center clusters. |
| Acquisition of Specialist Firm | Captures Python automation talent pools collapsing mid-market deployment timelines. |
| Geographic Expansion | Targets India's PLI-scheme data center buildouts in Mumbai and Hyderabad corridors. |
| Product Launch | Introduces AI-driven anomaly detection modules compressing mean-time-to-resolution metrics. |
Research Approach
The analysis maps controller software, switch hardware, security modules, and overlay platforms, each validated through network architects, IT procurement officers, and channel partner technical directors. Primary fieldwork combined CTO interviews at financial services institutions with integration specialist discussions at value-added distributors. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, and ETSI specification documents. Bottom-up deployment modeling triangulated against top-down infrastructure spending forecasts.
Consistency checks validated volume and value outputs against carrier RFP timelines and federal procurement databases across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from compound growth trajectory analysis against infrastructure replacement cycle data. Forecast inputs incorporated NIST cybersecurity framework compliance deadlines and spectrum auction condition timelines.
Decision-makers should treat outputs as directional under sustained hyperscale data center expansion and federal cloud-first mandate continuity; material deviation would warrant model refresh. Forecasts reflect these base assumptions with acknowledged sensitivity to silicon supply concentration and operational skill scarcity constraints. Revision becomes warranted when merchant silicon lead times or Python automation talent availability crosses critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Graph Database Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Global DNS Service Market