
 United Kingdom Data Center Networking Market | 2026-2036
United Kingdom Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Networking Market Insights
400G/800G port density is redrawing procurement priorities across UK facility operators. Cisco Systems leverages its merchant silicon partnerships to sustain switching portfolio breadth. Arista Networks specializes in ultra-low-latency spine architectures for financial services colocation.
Data center networking encompasses the switching, routing, and interconnect hardware that moves traffic between servers, storage arrays, and external networks within a facility, typically operating at line rates from 25G to 800G per port with sub-microsecond latency budgets. Its primary purpose is to maintain throughput and reliability for cloud, enterprise, and AI training workloads. Ethernet switches occupy the largest revenue pool given their ubiquity across every rack, while SDN deployments are expanding fastest as operators automate fabric management across hybrid estates. Colocation providers represent a concentrated demand channel where multi-tenant density requirements drive premium port configurations.
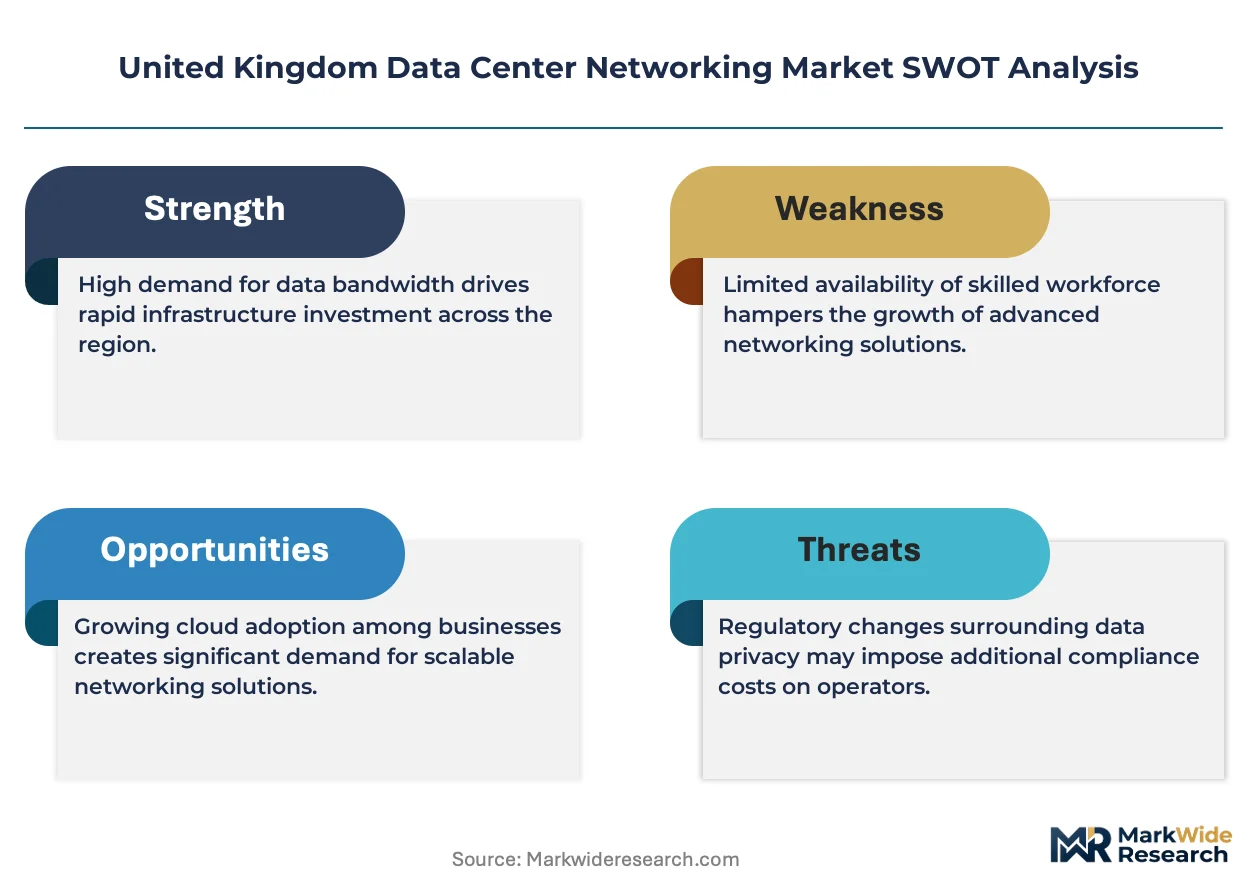
Ofcom's wholesale fixed telecoms market reviews and the UK government's Product Security and Telecommunications Infrastructure regime shape equipment certification timelines and cybersecurity baselines for network hardware procurement. BSI standards for electromagnetic compatibility and energy efficiency add compliance layers to product qualification cycles. Stakeholders must weigh capex timing against anticipated shifts in AI workload patterns and regulatory refresh schedules.
Market Dynamics
AI training clusters and inference nodes are forcing UK operators to re-architect spine-leaf topologies around 800G port densities and liquid-cooled rack configurations, compressing refresh cycles from five years to eighteen months.
Growth Catalysts
- Ofcom's Wholesale Fixed Telecoms Market Review:Mandated open-access fiber pricing accelerates dark fiber deployment between Greater London and Manchester facilities.
- Hyperscale AI workload concentration:Cloud providers are procuring 51.2Tbps switching fabrics for large language model training clusters in Slough and Docklands.
- Edge computing node proliferation:5G standalone rollouts require micro data centers in Birmingham, Leeds, and Glasgow with sub-5ms latency backhaul.
Market Restraints
- Merchant silicon supply concentration:Broadcom and Marvell dominate 51.2Tbps switching ASICs, creating single-source vulnerability for UK system integrators.
- BSI electromagnetic compatibility certification:Extended test cycles for 800G transceivers delay product launches by four to six months versus CE-marked equivalents.
- Copper and rare earth price volatility:Palladium and gallium arsenide cost swings compress gross margins on optical interconnect modules.
Strategic Opportunities
- Wales and Northern England greenfield sites:Renewable energy access and lower land costs attract hyperscale builds outside the Thames Valley corridor.
- Converged IP-optical transport:Co-packaged optics and silicon photonics integration reduce power-per-bit by forty percent in high-density fabrics.
- UK Product Security and Telecommunications Infrastructure regime:Mandatory vulnerability disclosure creates first-mover advantage for vendors with pre-certified secure boot architectures.
Industry Challenges
- Silicon photonics packaging expertise:Co-packaged optics assembly requires precision alignment skills scarce in UK workforce pipelines.
- Multi-vendor SONiC integration:Disaggregated network operating system deployments demand software engineering capabilities most colocation providers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Networking Market |
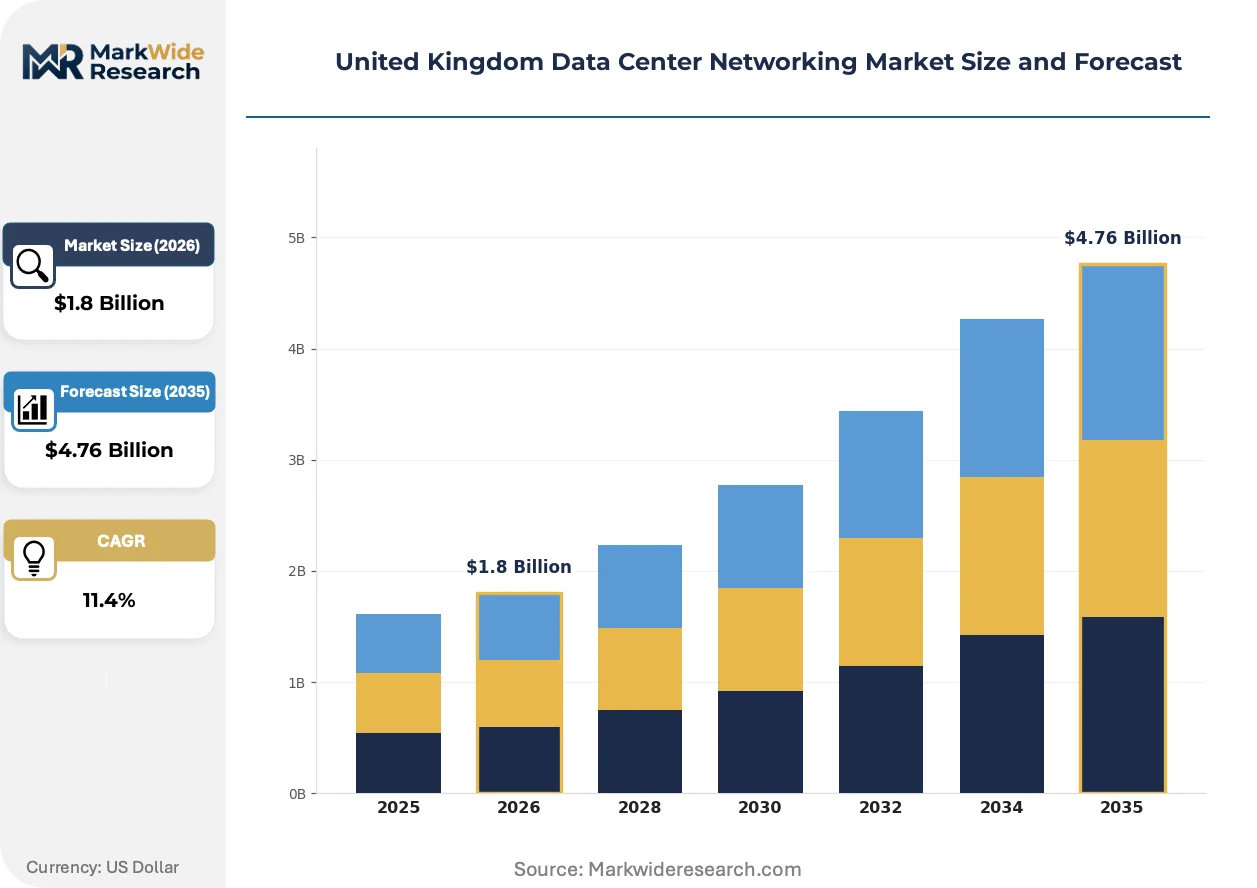
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Network Adapters Deployment Model: On-Premises, Hybrid, Colocation, Managed Services Customer Type: Enterprises, Service Providers, Government, SMEs Technology: SDN, MPLS, Ethernet, Fiber Optics |
| Companies Covered | Cisco Systems, Arista Networks, Juniper Networks, Hewlett Packard Enterprise, Broadcom, Huawei Technologies, Dell Technologies, Extreme Networks, VMware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Networking Market Trends and Innovations
Switching architectures are splitting between ultra-low-latency fabrics for financial trading and throughput-optimized designs for AI training, with each path demanding incompatible hardware roadmaps.
Co-packaged optics is bifurcating the transceiver market between pluggable modules for legacy refresh cycles and embedded photonics for greenfield hyperscale builds. Cloud operators in Slough and Docklands are deploying 51.2Tbps switches with co-packaged optics for training clusters, while enterprise colocation tenants retain QSFP-DD pluggables to preserve interoperability. The technology is bifurcating procurement teams into separate hardware evaluation tracks with divergent qualification timelines.
Ofcom's 2024 Business Connectivity Market Review imposes regulated pricing on dark fiber leases between data center zones. The framework compresses backhaul costs for multi-site operators while forcing incumbent carriers to unbundle infrastructure. Wholesale bandwidth buyers in Greater Manchester and West London are renegotiating long-term contracts to capture regulated rate ceilings.
Financial services colocation clients are consolidating switching procurement under direct vendor relationships, bypassing systems integrators who previously managed multi-site deployments. Tier-one banks in Canary Wharf and the City of London are negotiating enterprise license agreements with Arista and Cisco for spine architectures. This concentration shifts margin from channel partners to manufacturers while reducing deployment flexibility for smaller hedge funds and trading venues.
United Kingdom Data Center Networking Market Segmentation
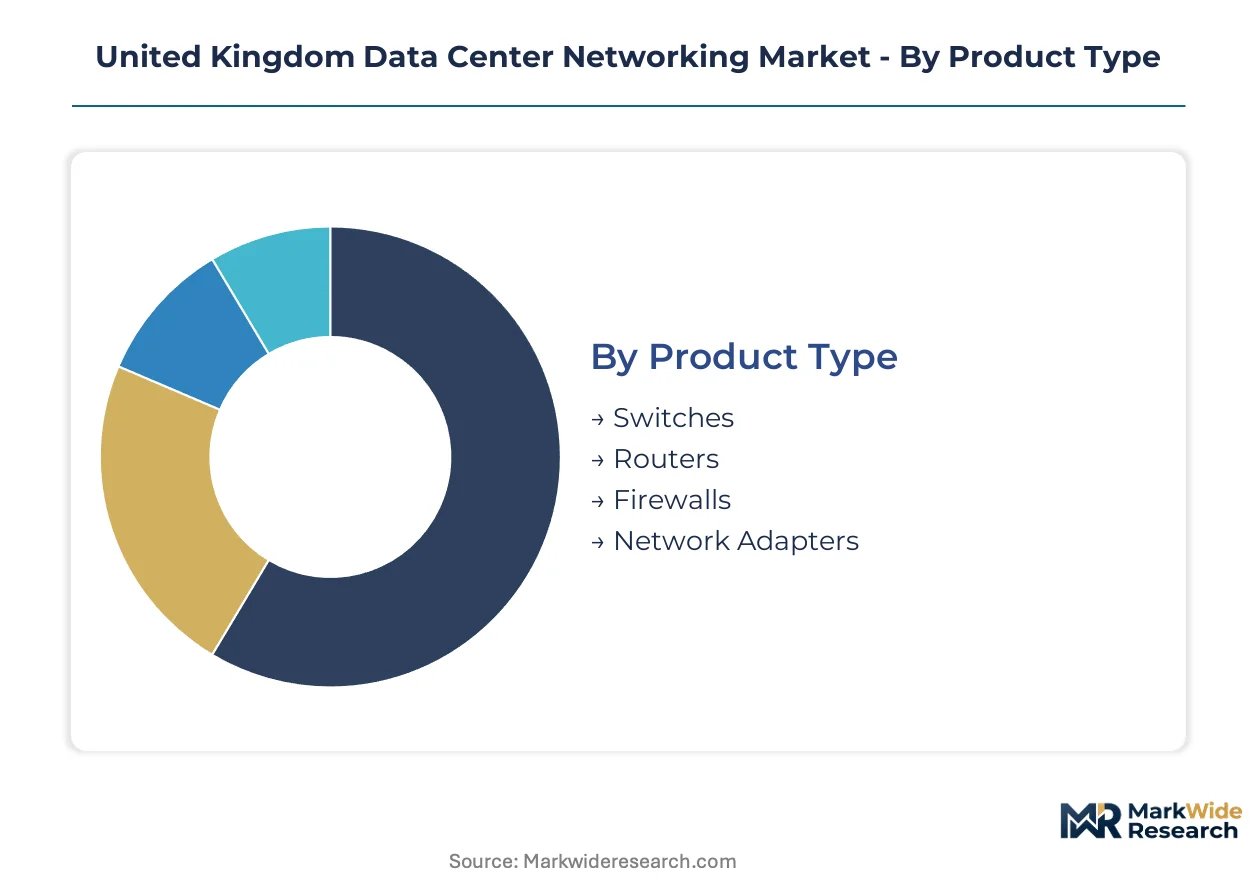
UK data center networking procurement flows through distinct channel configurations that reshape how vendors position hardware portfolios. Understanding segment boundaries clarifies where 400G/800G upgrade cycles concentrate versus legacy refresh patterns.
Product Type:
Channel mix varies sharply by product category, with switches dominating direct OEM relationships while firewalls route through security-focused systems integrators.
- Switches:Ethernet switching platforms operate at 25G to 800G line rates with sub-microsecond latency budgets, forming the backbone of spine-leaf fabrics. Demand clusters in Greater London hyperscale facilities where AI training clusters require 51.2Tbps switching capacity. Refresh cycles compress from five years to eighteen months under AI workload pressure.
- Routers:Layer 3 platforms handle inter-facility traffic and external connectivity with deep buffer architectures for WAN optimization. Manchester and Slough edge deployments drive demand for disaggregated routing stacks compatible with SONiC operating systems. Procurement flows through carrier-neutral colocation providers negotiating wholesale bandwidth agreements.
- Firewalls:Next-generation platforms integrate threat inspection with 100G+ throughput for east-west traffic segmentation in multi-tenant environments.
- Network Adapters:SmartNICs and DPUs offload virtualization overhead from host CPUs in high-density compute racks.
Switches dominate installed base. Routers is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capex-intensive on-premises builds from opex-driven managed service arrangements with divergent vendor engagement models.
- On-Premises:Enterprise-owned facilities in Canary Wharf and the City of London deploy custom spine architectures with direct vendor relationships bypassing integrators. Financial services colocation clients consolidate procurement under enterprise license agreements with Arista and Cisco for ultra-low-latency trading infrastructure.
- Colocation:Multi-tenant facilities in Slough and Docklands require premium port configurations supporting 800G densities and liquid-cooled rack layouts for AI training clusters. Operators procure 51.2Tbps fabrics with co-packaged optics to minimize power-per-bit.
- Hybrid:Split workload placement across owned and leased infrastructure demands consistent SDN policy orchestration.
- Managed Services:Third-party network operations offload fabric management for SMEs lacking in-house SONiC engineering capabilities.
On-Premises retains the largest revenue pool. Colocation is climbing the fastest.
Customer Type:
Application requirements fragment procurement priorities, with service providers optimizing for throughput density while enterprises prioritize operational simplicity.
- Service Providers:Cloud operators and telcos scale 800G spine fabrics across Greater London, Manchester, and emerging Wales greenfield sites. BSI electromagnetic compatibility certification extends product launch timelines by four to six months versus CE-marked equivalents.
- Enterprises:Tier-one banks and hedge funds in financial services clusters demand sub-microsecond latency with direct vendor support contracts. Trading venues bypass systems integrators to negotiate spine architecture licenses directly with switching vendors.
- Government:Public sector deployments align with the UK Product Security and Telecommunications Infrastructure regime mandating secure boot architectures and vulnerability disclosure.
- SMEs:Mid-market operators rely on channel partners for multi-vendor integration lacking in-house software engineering depth.
Service Providers command the highest port densities. Government is gaining share fastest.
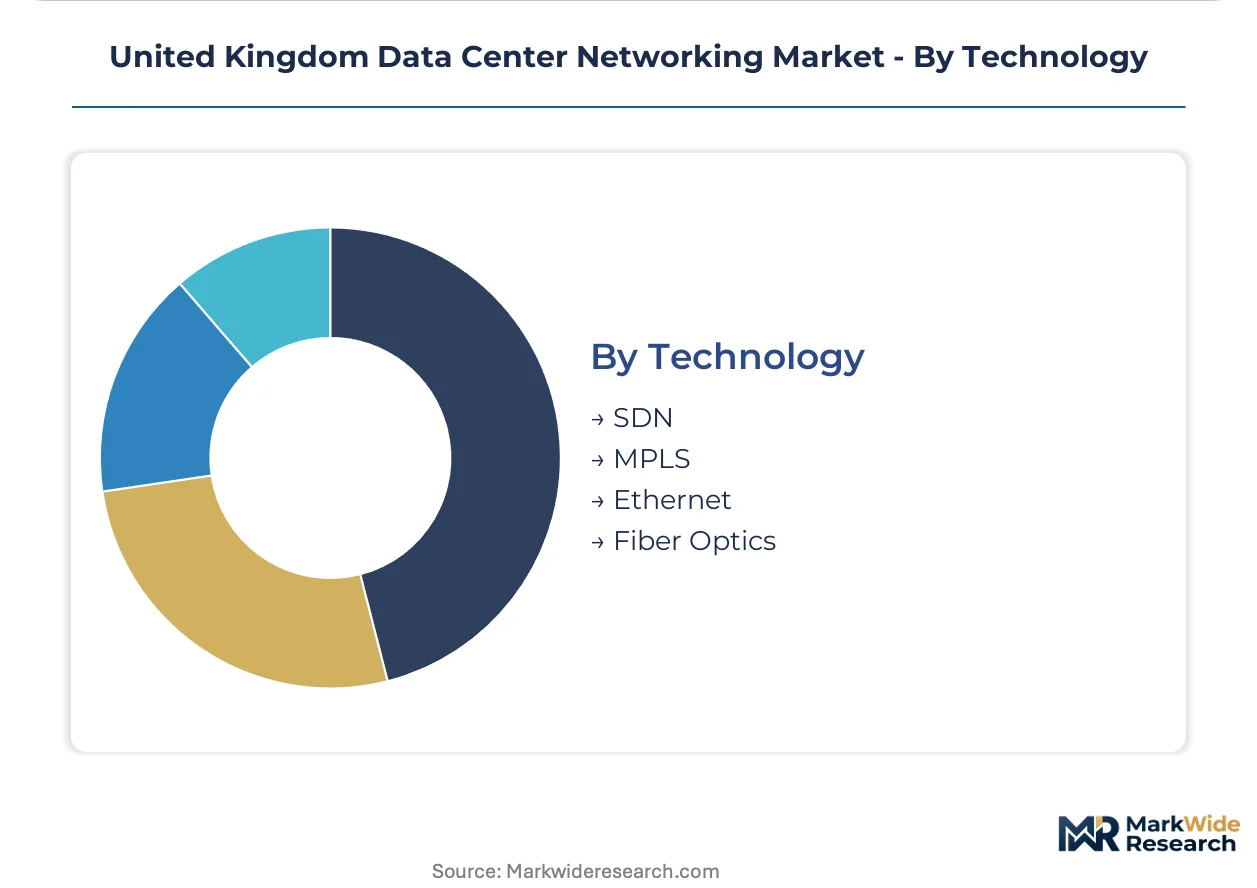
Technology:
Maturity curves separate established Ethernet deployments from emerging SDN automation layers with incompatible qualification timelines.
- Ethernet:IEEE 802.3 standards-based switching at 100G/400G/800G dominates physical layer connectivity across every rack. Pluggable QSFP-DD modules preserve interoperability for enterprise colocation tenants in legacy refresh cycles.
- SDN:Disaggregated network operating systems automate fabric management across hybrid estates. Multi-vendor SONiC integration demands software engineering capabilities scarce in UK workforce pipelines, constraining adoption at smaller colocation providers.
- Fiber Optics:Single-mode and multimode cabling infrastructure supports reach requirements from intra-rack to inter-facility connections.
- MPLS:Traffic-engineered WAN connectivity persists in financial services for deterministic latency guarantees.
Ethernet anchors installed base. SDN is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom runs a structural deficit in high-end switching ASICs and optical transceivers, importing merchant silicon from Broadcom and Marvell while exporting specialized colocation services to continental European financial institutions. This trade pattern concentrates procurement leverage in Greater London's hyperscale corridor.
London and Southeast England
Docklands and Slough facilities absorb 800G spine fabric deployments for AI training clusters, with cloud operators procuring 51.2Tbps switching capacity. Ofcom's wholesale fixed telecoms market review mandates open-access fiber pricing between these zones. The Thames Valley corridor hosts the densest concentration of liquid-cooled rack configurations in Europe.
North England
Manchester data centers drive demand for disaggregated routing stacks compatible with SONiC operating systems. The city's carrier-neutral colocation providers negotiate wholesale bandwidth agreements under BSI electromagnetic compatibility certification timelines. Edge computing nodes in Leeds and Sheffield extend sub-5ms latency backhaul for 5G standalone rollouts.
Midlands
Birmingham micro data centers serve financial services disaster recovery requirements with sub-microsecond latency budgets. The region benefits from lower land costs and improved renewable energy access compared to the Southeast. West Midlands 5G testbeds accelerate network function virtualization procurement for enterprise tenants.
Scotland
Edinburgh and Glasgow facilities target carbon-neutral operations through North Sea wind power interconnects. Scottish colocation operators emphasize BSI energy efficiency standards in procurement specifications. The Central Belt attracts hyperscale satellite offices seeking alternative locations to England's saturated power grid.
Wales
Greenfield sites in Newport and Cardiff exploit renewable energy access and streamlined planning permissions for hyperscale builds. Welsh facilities compete on power-per-bit metrics against Thames Valley incumbents. The region's emergence challenges Greater London's historical dominance in UK data center networking demand.
United Kingdom Data Center Networking Market Competitive Landscape
Listed leaders compete with private specialists across switching silicon and systems integration. The vendor base splits between merchant ASIC suppliers controlling upstream component supply and systems houses assembling differentiated hardware portfolios. Three archetypes dominate: merchant silicon licensors, disaggregated switching specialists, and vertically integrated incumbents. Competitive moves concentrate on co-packaged optics integration and SONiC certification partnerships.
Within the merchant silicon tier, Broadcom exemplifies upstream control over 51.2Tbps switching ASICs. Among systems-focused vendors, Cisco Systems occupies a position representing vertically integrated incumbency, while Arista Networks sits within the disaggregated specialist archetype emphasizing ultra-low-latency spine architectures. Juniper Networks anchors the routing-centric segment with carrier-grade credentials. These three represent distinct competitive vectors rather than direct substitution.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Broadcom |
| Huawei Technologies |
| Dell Technologies |
| Extreme Networks |
| VMware |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month refresh cycles for 800G spine fabrics concentrate procurement leverage among hyperscale operators in Greater London and Slough, compressing supplier margins while amplifying volume-based pricing power for cloud providers with direct ASIC partnerships.
Pricing Analysis
Cloud service providers anchor contract-based long-term offtake structures for merchant silicon switching platforms. Price differentiation hinges on port density tiers and BSI electromagnetic compatibility certification status, with uncertified modules trading at discounts against compliant equivalents. Cost compression in optical interconnects is intensifying because palladium and gallium arsenide price volatility feeds through to transceiver margins. SMEs relying on channel partners exhibit highest price sensitivity; hyperscale operators with direct vendor relationships demonstrate lowest sensitivity due to enterprise license agreement scale.
Supply Chain Analysis
The United States and Taiwan anchor wafer fabrication for 51.2Tbps switching ASICs, while Malaysia and Thailand concentrate optical transceiver assembly operations. UK system integrators draw from Broadcom and Marvell for merchant silicon, from Chinese and Japanese suppliers for rare earth substrates, and from German precision optics houses for co-packaged alignment equipment. Single-source vulnerability around 51.2Tbps ASICs creates structural risk for domestic spine fabric deployments. Distribution runs through carrier-neutral colocation providers negotiating wholesale bandwidth agreements with direct OEM relationships bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White-box switching platforms built on SONiC and merchant silicon threaten to commoditize spine-layer margins, forcing incumbents to defend through architectural differentiation and captive silicon roadmaps.
For Market Incumbents: Compound switching portfolio stickiness through co-packaged optics integration and secure boot architecture pre-certification under the UK Product Security and Telecommunications Infrastructure regime. Deepen backward integration into silicon photonics packaging capabilities to offset merchant ASIC supply concentration. Channel control through direct enterprise license agreements with financial services colocation clients protects margin against disaggregated SONiC alternatives. For New Entrants and Emerging Players: Differentiate on SONiC-native automation stacks targeting mid-market colocation providers lacking in-house software engineering depth. Wales and Northern England greenfield hyperscale sites represent the most penetrable geography given streamlined planning permissions and renewable energy access. A managed services wrapper around multi-vendor fabric orchestration offers the strongest go-to-market angle against entrenched incumbent relationships. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because AI workload concentration compresses refresh cycles and concentrates procurement among fewer hyperscale buyers. Acquisition target archetype: disaggregated switching specialists with proven SONiC certification partnerships and established relationships with carrier-neutral colocation operators. Watch hyperscaler capex disclosure inflections as the priority signal for 800G spine fabric demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership Expansion | Broadcom and Marvell ASIC access secures 51.2Tbps roadmap positioning for UK hyperscale deployments. |
| Co-Packaged Optics Integration | Silicon photonics embedding reduces power-per-bit forty percent in Slough and Docklands training clusters. |
| SONiC Certification Investment | Disaggregated network operating system validation opens mid-market colocation provider procurement channels. |
| Secure Boot Architecture Pre-Certification | UK Product Security and Telecommunications Infrastructure compliance creates first-mover advantage in government tenders. |
| Wales Greenfield Site Establishment | Renewable energy access and lower land costs challenge Thames Valley corridor dominance for hyperscale builds. |
Research Methodology
The analysis maps Ethernet switching, routing platforms, optical interconnects, and SDN automation layers, each validated through primary interviews with data center network architects, colocation procurement directors, cloud infrastructure engineers, and carrier-neutral facility operators. Secondary sources include Ofcom wholesale market review documentation, BSI electromagnetic compatibility certification records, hyperscaler capital expenditure disclosures, and carrier-neutral colocation provider financial filings. Bottom-up port shipment estimates and top-down infrastructure investment flows undergo cross-validation through triangulation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, deployment model, customer archetype, and technology maturity tier, with additional granularity on AI workload density classifications. CAGRs derive from fitted growth curves applied to infrastructure capex patterns and regulatory refresh cycle timing. Forecast inputs incorporate merchant silicon availability timelines and BSI certification pipeline durations.
Material uncertainties — merchant silicon supply disruptions, rare earth price shocks, and regulatory refresh schedule shifts — sit outside the modeled envelope. Forecasts reflect assumptions on hyperscaler AI cluster deployment pacing and Ofcom wholesale pricing regime stability. Recalibration cycles align with material shifts in hyperscaler capex guidance and BSI standards revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Data Center Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Indonesia Data Center Networking Market