
 Australia Data Center Networking Market | 2026-2036
Australia Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Networking Market Insights
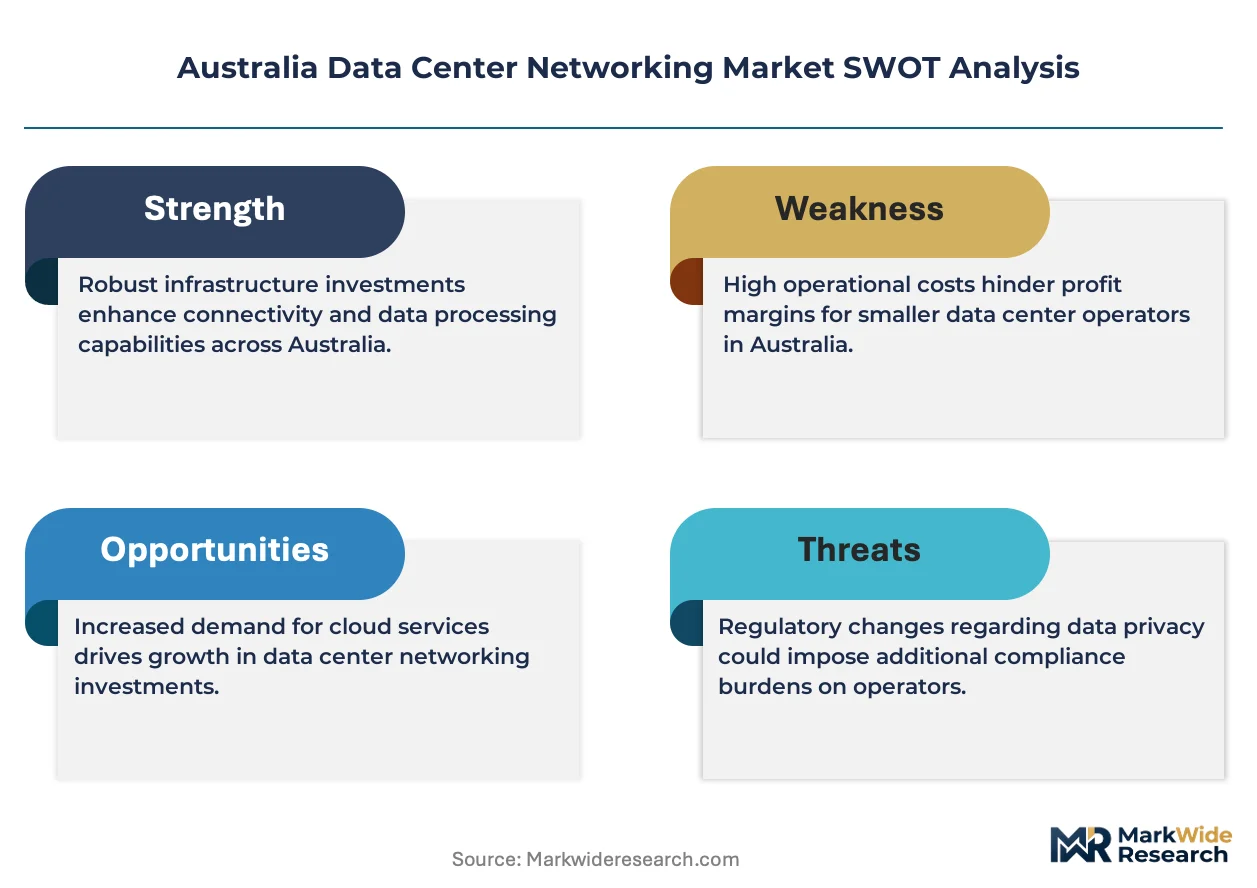
Wholesale procurement channels between hyperscale cloud tenants and original equipment manufacturers is reconfiguring how networking hardware flows into Australian facilities. Cisco Systems Inc. leverages its established partner ecosystem to sustain turnkey deployment capabilities across Sydney and Melbourne metro zones. Arista Networks Inc. specializes in low-latency Ethernet fabrics that anchor high-performance computing workloads for local cloud service providers. Juniper Networks Inc. competes through programmable silicon architectures that reduce operational complexity for enterprise data center operators.
Australia data center networking encompasses the switching, routing, and security infrastructure that interconnects compute and storage resources within facilities, typically operating at speeds from 10 Gbps to 400 Gbps with sub-microsecond latency requirements for AI training clusters. Ethernet switches command the largest product type position due to their ubiquity in spine-leaf architectures, while InfiniBand technology is capturing the fastest expansion as NVIDIA's accelerated computing platforms penetrate local AI deployments. Cloud service providers represent the dominant end-user segment by capital commitment, though colocation providers are diversifying their networking service layers to capture recurring revenue from enterprises seeking hybrid connectivity.
ACMA's telecommunications licensing framework and the Australian government's Critical Infrastructure Act shape operator obligations for network resilience and supply chain security. TGA-equivalent data governance expectations and state-level planning regulations in New South Wales and Victoria constrain facility expansion timelines and equipment certification requirements. Stakeholders must monitor how sovereign cloud mandates and energy efficiency standards will redefine procurement specifications for core networking gear.
Market Dynamics
Hyperscale cloud tenants are consolidating procurement authority and bypassing traditional distribution channels to source 400G Ethernet switches and InfiniBand fabrics directly from original equipment manufacturers, compressing reseller margins while accelerating deployment timelines for Sydney and Melbourne facilities.
Growth Catalysts
- AI Training Cluster Deployment:Cloud service providers are procuring high-bandwidth, low-latency networking infrastructure to support NVIDIA accelerated computing platforms for generative AI workloads.
- Critical Infrastructure Act Compliance:Australia's data sovereignty mandates and network resilience obligations are forcing facility operators to upgrade security architectures and redundancy specifications.
- Hyperscale Facility Construction:Concentrated demand in New South Wales and Victoria is pulling fiber optic interconnect and spine-leaf switching equipment into accelerated procurement cycles.
Market Restraints
- Semiconductor Supply Concentration:Advanced switching ASICs and optical transceivers depend on concentrated fabrication capacity in East Asia, creating vulnerability to geopolitical disruption.
- State-Level Planning Friction:New South Wales and Victoria environmental and zoning approvals extend facility commissioning timelines, delaying networking equipment installation schedules.
- Copper and Rare Earth Input Volatility:Ethernet cable assemblies and magnetics face raw material cost swings that compress hardware margins for local integrators.
Strategic Opportunities
- Edge Computing Interconnect:Regional Queensland and Western Australia facilities present underpenetrated demand for distributed networking infrastructure outside Sydney-Melbourne concentration.
- Sovereign Cloud Mandates:Australian government cloud-first policies and classified workload requirements are creating procurement preference for domestically certified networking equipment.
- Silicon Photonics Convergence:Co-packaged optics and electronic-photonic integration promise power efficiency gains for high-density AI clusters in tropical climate conditions.
Industry Challenges
- Specialized Engineering Talent Scarcity:Optical networking design and InfiniBand fabric optimization skills remain concentrated among a small cohort of Sydney-based specialists.
- Multi-Vendor Integration Complexity:Enterprise operators struggle to harmonize Cisco, Arista, and Juniper equipment under unified software-defined networking orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Networking Market |
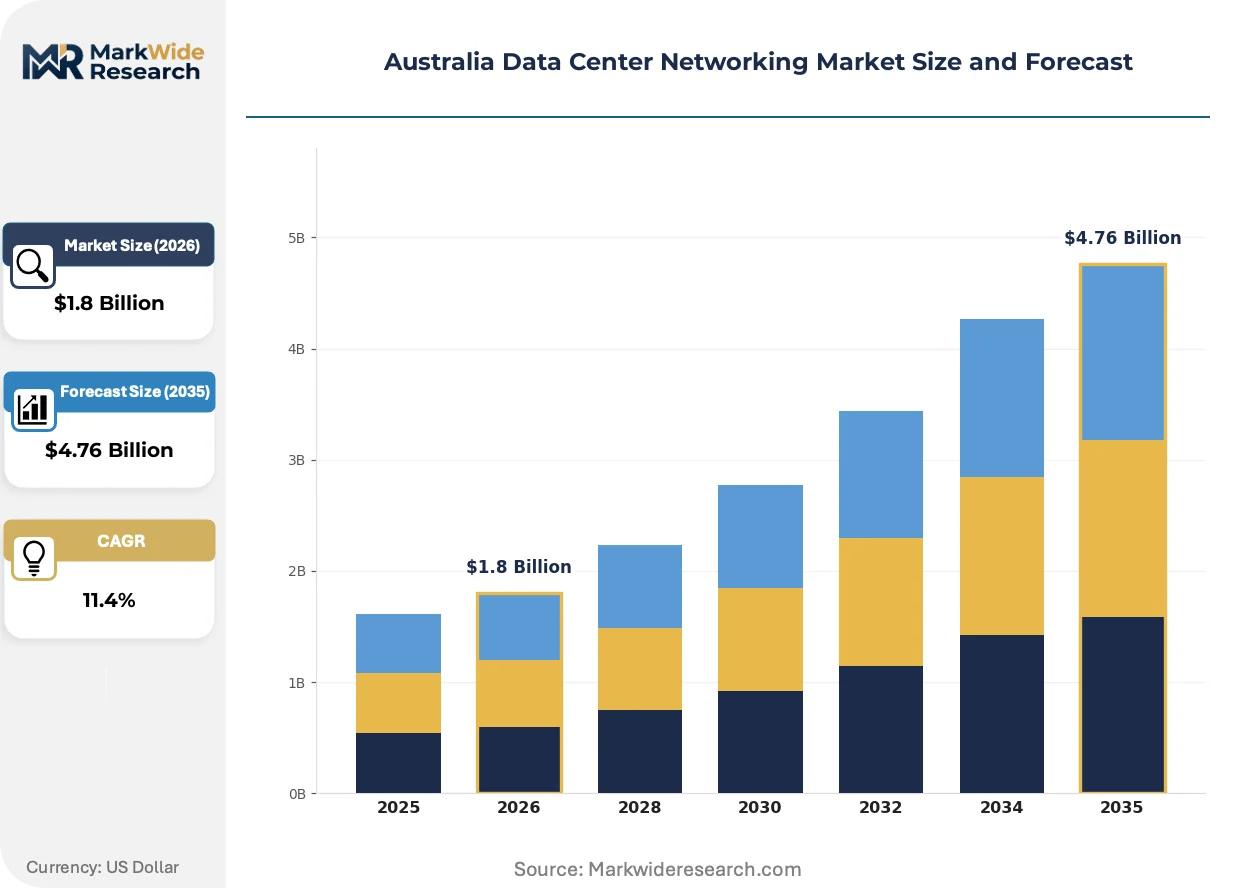
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Fiber Channel, InfiniBand, MPLS End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Providers Application: Data Storage, Disaster Recovery, Virtualization, Network Security |
| Companies Covered | Cisco Systems Inc., Broadcom Corporation, Arista Networks Inc., Juniper Networks Inc., Dell Technologies Inc., Hewlett Packard Enterprise Company, NVIDIA, F5 Networks Australia, Extreme Networks Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Networking Market Trends and Innovations
Networking architecture is undergoing fundamental restructuring as AI workload requirements force bandwidth and latency specifications upward while power constraints demand integration efficiency gains.
Co-packaged optics is collapsing the physical separation between switch ASICs and optical engines, eliminating retimer components and reducing power consumption per bit by half. Hyperscale operators in Sydney are piloting 51.2Tbps silicon switches with embedded photonics for 2025 AI cluster deployments. This compression of the optical-electrical boundary is collapsing traditional transceiver supplier business models and shifting value capture toward semiconductor foundries.
Australia's Critical Infrastructure Act and accompanying Security of Critical Infrastructure Rules impose mandatory reporting and risk management obligations on data center network operators. The Australian Cyber Security Centre now mandates supply chain visibility down to component origin for facilities hosting government workloads. Colocation providers are responding by segmenting certified and non-certified network zones within the same physical footprint.
Wholesale procurement patterns are concentrating buying power among three hyperscale cloud tenants who now account for the majority of 400G port shipments. Traditional value-added distributors are retrenching toward professional services and sparing contracts as direct OEM relationships capture hardware margin. This channel restructuring is most visible in Melbourne, where Amazon Web Services and Microsoft have established dedicated supply agreements bypassing local reseller networks.
Australia Data Center Networking Market Segmentation
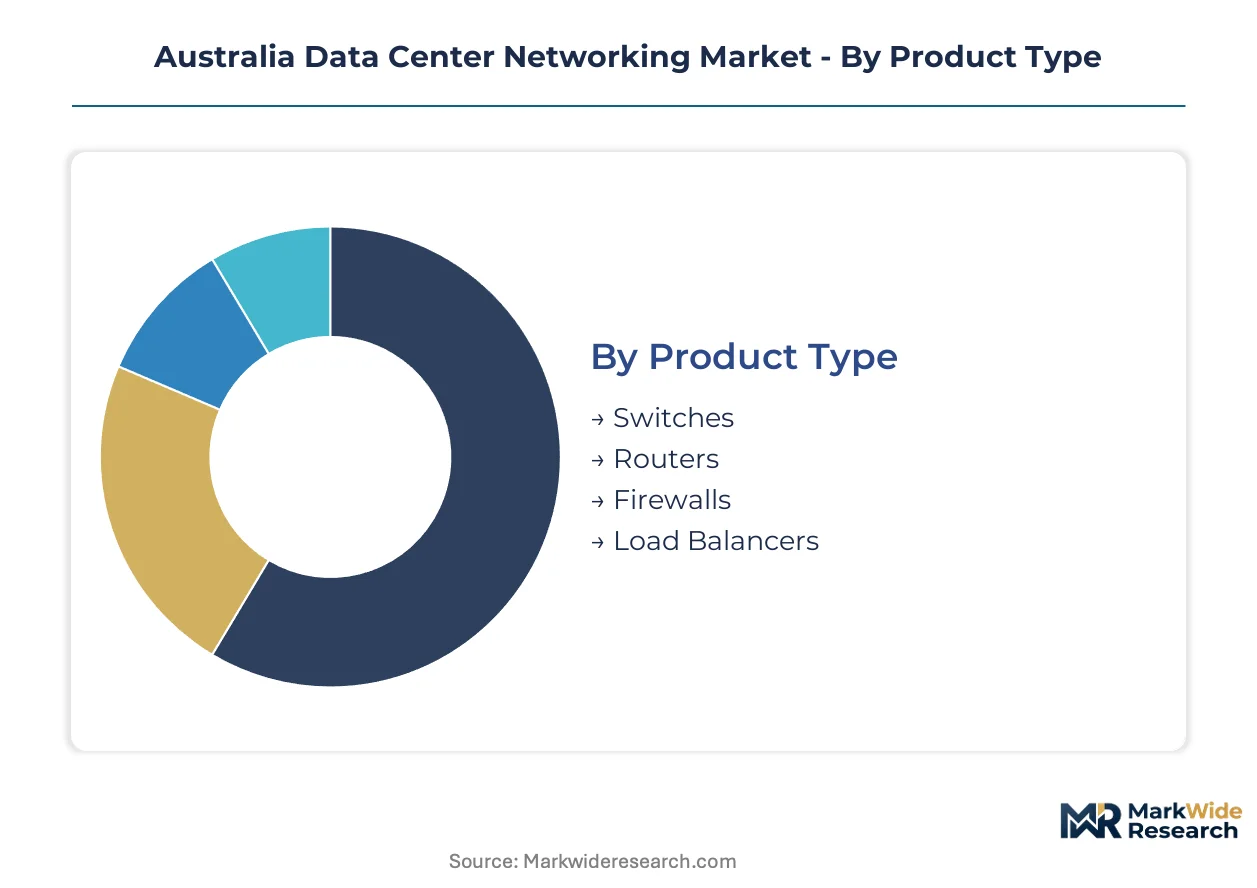
Segmentation in the Australia data center networking market reveals how procurement authority, workload requirements, and compliance obligations reshape equipment specifications across facility types. Understanding these divides exposes where capital concentrates and which technologies face displacement pressure.
Product Type:
Mature switching platforms anchor spine-leaf architectures while emerging security appliances capture premium pricing from Critical Infrastructure Act compliance mandates.
- Switches:Ethernet switches operating at 10G to 400G speeds form the backbone of hyperscale fabric deployments. Sydney and Melbourne hyperscale facilities pull the majority of spine-leaf switch volumes as cloud service providers expand AI training clusters. These platforms face relentless bandwidth escalation from NVIDIA accelerated computing platforms.
- Routers:Border and core routers manage inter-facility traffic flows across metropolitan fiber networks. New South Wales and Victoria operators prioritize programmable silicon architectures to reduce operational complexity under sovereign cloud certification requirements. Edge routing demand is climbing in Queensland and Western Australia regional facilities.
- Firewalls:Next-generation firewalls with deep packet inspection capabilities address ACMA telecommunications licensing and Australian Cyber Security Centre supply chain visibility mandates. Hardware appliances command preference over virtualized instances for classified workload zones.
- Load Balancers:Application delivery controllers distribute traffic across distributed compute pools in hybrid cloud configurations. Colocation providers deploy these to differentiate managed networking service offerings from commodity cross-connects.
Switches retain volume leadership; InfiniBand-capable switching fabrics hold the steepest expansion curve as AI workload penetration accelerates.
Technology:
Cost tier stratification separates commodity Ethernet from premium InfiniBand deployments, with fiber channel persisting in legacy enterprise storage environments.
- Ethernet:Dominant interconnect protocol spanning 1G to 400G port speeds with standardized interoperability. Cloud service providers in Sydney drive 400G Ethernet procurement volumes as hyperscale facility construction accelerates. Power efficiency concerns are pushing adoption of co-packaged optics variants.
- InfiniBand:Low-latency high-bandwidth fabric technology purpose-built for GPU clustering and AI training workloads. Melbourne facilities hosting NVIDIA accelerated computing platforms represent the fastest-expanding demand pocket. Supply concentration in specialized switch ASICs creates procurement vulnerability.
- Fiber Channel:Storage area networking protocol maintaining presence in enterprise data centers with legacy SAN investments. Financial services and government agencies in New South Wales sustain residual demand despite Ethernet convergence pressure.
- MPLS:Traffic engineering protocol for metropolitan and wide-area connectivity between distributed facilities. Telecommunications operators leverage MPLS for managed service differentiation in multi-tenant colocation environments.
Ethernet retains volume leadership; InfiniBand gains share fastest as generative AI training clusters proliferate across Australian facilities.
End User:
Customer type determines procurement scale and channel structure, with hyperscale cloud tenants consolidating direct OEM relationships while enterprises rely on systems integrators.
- Cloud Service Providers:Hyperscale operators including Amazon Web Services and Microsoft account for the majority of 400G port shipments through direct OEM supply agreements. These tenants bypass traditional distribution channels, compressing reseller margins while accelerating Melbourne and Sydney deployment timelines. Sovereign cloud mandates are segmenting certified and non-certified network zones within facilities.
- Telecommunications:Carrier-neutral operators and national telcos deploy networking infrastructure for inter-facility connectivity and managed service layers. ACMA licensing frameworks impose network resilience obligations that shape redundancy specifications and equipment certification requirements.
- Enterprises:Corporate data center operators face multi-vendor integration complexity when harmonizing Cisco, Arista, and Juniper equipment under unified orchestration layers. Financial services and mining sector enterprises in New South Wales and Western Australia sustain mid-market switch procurement.
- Colocation Providers:Multi-tenant facility operators diversify into managed networking services to capture recurring revenue from hybrid cloud connectivity demand. These providers segment physical network zones to accommodate government workload certification requirements under the Critical Infrastructure Act.
Cloud service providers retain volume leadership; colocation providers are climbing fastest as managed networking service penetration deepens.
Application:
Application priority reshapes latency and redundancy specifications, with AI training clusters demanding sub-microsecond performance while disaster recovery emphasizes geographic diversity.
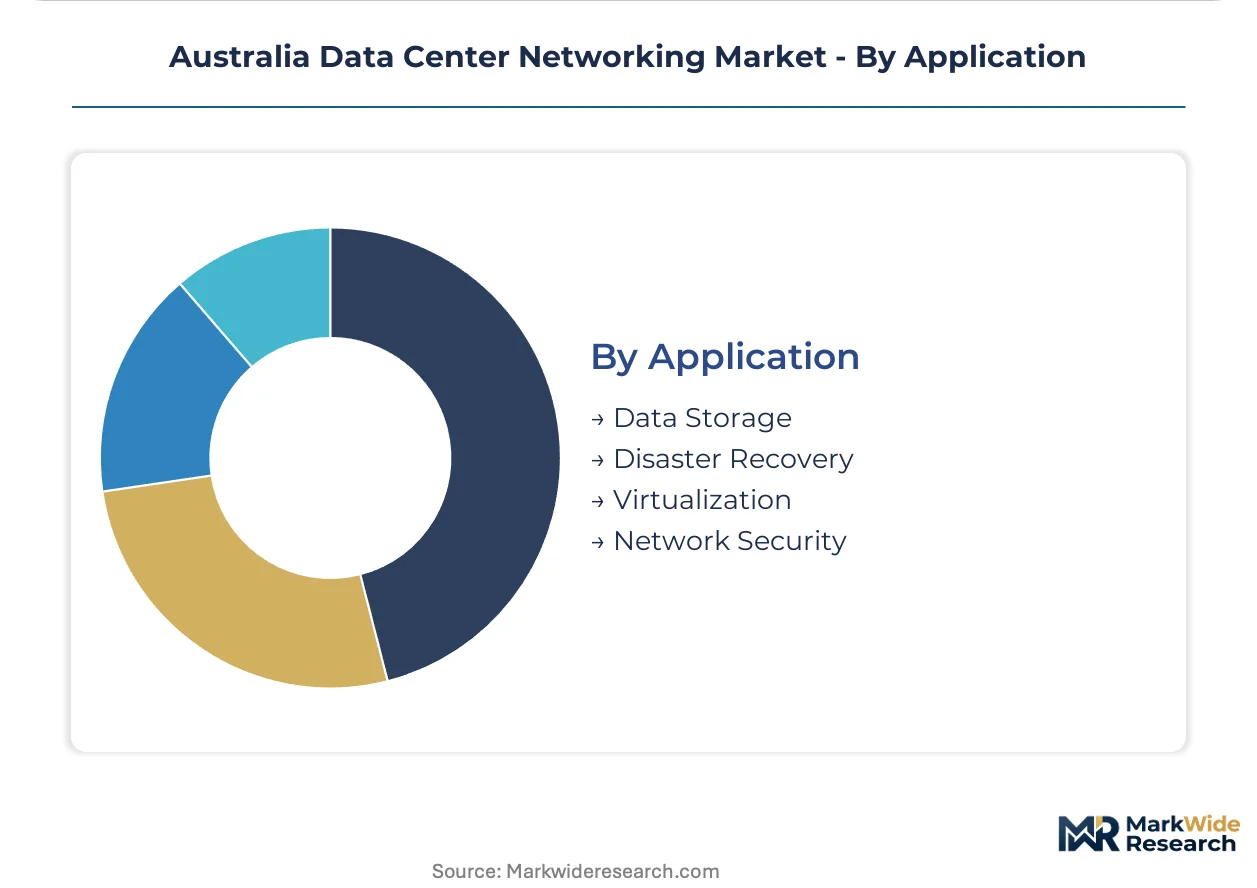
- Data Storage:Storage networking infrastructure connects all-flash and object storage pools to compute resources. Hyperscale facilities in Sydney prioritize NVMe-over-fabric connectivity for AI training data pipelines. Ethernet convergence is displacing legacy fiber channel attachments in new builds.
- Disaster Recovery:Replication and backup networking requires metropolitan and interstate fiber diversity to meet recovery point objectives. State-level planning friction in New South Wales and Victoria extends secondary site commissioning timelines, delaying networking equipment installation schedules.
- Virtualization:Software-defined networking overlays abstract physical switch hardware for multi-tenant resource allocation. Colocation providers leverage virtualization to offer differentiated service tiers without physical network segmentation.
- Network Security:Segmentation, microsegmentation, and zero-trust enforcement drive firewall and policy controller deployment. Australian Cyber Security Centre supply chain visibility mandates down to component origin reshape procurement specifications for facilities hosting government workloads.
Data storage retains volume leadership; network security is expanding most quickly under Critical Infrastructure Act compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing for 400G Ethernet switches while Western Australia trades at discount spreads due to sparse hyperscale tenancy and elevated logistics costs for remote facility construction.
New South Wales
Sydney's hyperscale corridor drives concentrated procurement of spine-leaf switching fabrics and InfiniBand clusters for AI training workloads. The state's Critical Infrastructure Act enforcement and data sovereignty mandates force operators into certified equipment upgrade cycles. Macquarie Park and Eastern Creek industrial zones host the majority of cloud service provider facility construction, pulling optical interconnect demand into accelerated deployment timelines.
Victoria
Melbourne's enterprise colocation market sustains mid-tier Ethernet switch volumes for hybrid cloud connectivity deployments. Victoria's planning regulations and environmental approval processes extend facility commissioning timelines, compressing networking equipment installation windows. Truganina and Derrimut industrial precincts concentrate hyperscale construction activity, with direct OEM procurement bypassing traditional distribution channels.
Queensland
Brisbane and regional Queensland facilities present underpenetrated demand for distributed edge networking infrastructure outside the Sydney-Melbourne concentration. The state's planning framework offers faster approval pathways for data center zoning, attracting secondary market entrants. Sunshine Coast and Gold Coast metro zones are emerging as disaster recovery and latency-sensitive application nodes, pulling MPLS and SD-WAN equipment procurement northward.
Western Australia
Perth's isolation creates captive demand for self-sufficient network architectures with redundant fiber paths to eastern seaboard facilities. The state's mining sector enterprises sustain mid-market router and firewall procurement for private data center operations. Jandakot and Forrestdale industrial areas host limited hyperscale presence, with equipment costs inflated by interstate logistics and specialized engineering talent scarcity.
South Australia
Adelaide's government and defense sector concentration drives certified networking equipment demand under sovereign cloud mandates and Australian Cyber Security Centre supply chain visibility requirements. The state's renewable energy profile attracts carbon-conscious facility operators seeking power-efficient silicon photonics switching platforms. Edinburgh Parks and Mawson Lakes technology precincts anchor modest but growing colocation networking service layers.
Australia Data Center Networking Market Competitive Landscape
Incumbent network equipment vendors and cloud-native fabric specialists split the market along procurement-channel lines, with direct OEM relationships capturing hyperscale volume while systems integrators retain enterprise and mid-market access. The vendor base concentrates around three strategic archetypes: full-stack infrastructure incumbents with established partner ecosystems, programmable silicon specialists optimizing for AI workload latency, and security-integrated platform vendors addressing Critical Infrastructure Act compliance mandates. Competitive dynamics center on backward integration into switch ASIC design and geographic expansion of certified deployment capabilities across Australian metro zones.
Among the full-stack infrastructure tier, Cisco Systems Inc. and Dell Technologies Inc. occupy positions defined by turnkey deployment scale and established channel relationships across Sydney and Melbourne metro zones. Arista Networks Inc. exemplifies the programmable silicon specialist archetype, with its market presence tied to low-latency fabric optimization for cloud service provider AI clusters. These three companies represent distinct competitive vectors—incumbent ecosystem depth, workload-specific performance optimization, and hyperscale direct procurement alignment—that structure vendor selection criteria across facility operator segments.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Broadcom Corporation |
| Arista Networks Inc. |
| Juniper Networks Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise Company |
| NVIDIA |
| F5 Networks Australia |
| Extreme Networks Inc. |
| Others |
Pricing and Supply Chain Analysis
East Asian foundry concentration for advanced switch ASICs and optical transceivers funnels margin capture toward semiconductor fabricators, compressing hardware integrator profitability while hyperscale direct procurement bypasses traditional distributor markups entirely.
Pricing Analysis
Configured-to-order spine-leaf fabrics command substantial premiums over standard 10G-100G Ethernet switches in Australian facilities. Three-tier pricing structure across premium InfiniBand clusters, certified sovereign-cloud hardware, and commodity Ethernet gear reflects compliance-grade differentiation and volume scale. Cost compression in mid-tier switching is intensifying because hyperscale cloud tenants consolidate procurement authority through direct OEM agreements. Enterprise operators exhibit highest price sensitivity, while cloud service providers prioritize latency specifications over unit economics.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and Samsung Foundry anchor production of 400G switch ASICs and coherent optical DSPs feeding Australian data center builds. The supply chain draws from Taiwanese wafer fabrication, Malaysian optical component assembly, and Chinese copper cable and magnetics production. Single-source vulnerability in specialized InfiniBand switch silicon creates procurement risk for Melbourne AI cluster deployments. Distribution runs through direct OEM-hyper scale relationships for high-volume ports, with systems integrators retaining enterprise and colocation channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethernet switching incumbents face substitution pressure from InfiniBand fabrics as NVIDIA accelerated computing platforms capture AI training workloads, forcing defensive repositioning across product portfolios and partnership structures.
For Market Incumbents: Entrench certified supply chain visibility capabilities to satisfy Australian Cyber Security Centre component-origin mandates for government workload hosting. Deepen backward integration into switch ASIC design to reduce dependency on Taiwanese foundry allocation cycles. Prioritize Melbourne and Sydney deployment engineering teams to counter Arista Networks' low-latency fabric specialization. For New Entrants and Emerging Players: Establish a beachhead in Queensland edge computing interconnect, where underpenetrated regional facility demand escapes hyperscale procurement consolidation. Target Western Australia mining-sector private data centers with ruggedized routing and security appliances suited to remote operational conditions. Lead with professional services and sparing contracts rather than hardware margin capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed colocation providers diversifying into managed networking service layers. Five-to-ten year viability hinges on sovereign cloud certification penetration and AI workload hosting mix evolution. Monitor hyperscale capex disclosure patterns for 400G and 800G port procurement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Acquisition | Captive switch silicon development reduces foundry allocation dependency for Cisco and Juniper. |
| Sovereign Cloud Certification | ACMA and Australian Cyber Security Centre compliance unlocks government workload hosting premiums. |
| Co-Packaged Optics Pilot | Silicon photonics integration halves power consumption for tropical-climate Sydney AI clusters. |
| Queensland Edge Expansion | Brisbane and Gold Coast facilities capture disaster recovery demand outside Sydney-Melbourne concentration. |
| InfiniBand Fabric Partnership | NVIDIA integration agreements secure positioning in Melbourne generative AI training cluster builds. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center facility operators, network engineering directors, and hyperscale cloud procurement leads; and secondary validation through SEC 10-K filings, hyperscaler capex disclosures, ACMA telecommunications licensing registers, and Australian state planning authority approval databases. Bottom-up equipment shipment estimates and top-down infrastructure investment flows were triangulated to constrain forecast variance.
Forecast inputs span product type segmentation across switches, routers, firewalls, and load balancers; technology tiers from 10G Ethernet through 400G and InfiniBand; end-user categories including cloud service providers, telecommunications carriers, enterprises, and colocation operators; and application areas spanning data storage, disaster recovery, virtualization, and network security. CAGRs were derived from regression against historical hyperscale facility commissioning timelines and projected AI workload penetration curves across the analysis window. Supply chain risk modeling incorporated semiconductor fabrication capacity allocation and Critical Infrastructure Act compliance cost trajectories.
Stress conditions across Taiwanese foundry output disruption, Australian dollar commodity currency volatility, and New South Wales planning approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale tenant expansion schedules and sovereign cloud mandate enforcement intensity. Quarterly review of hyperscale direct procurement disclosure patterns and state-level data center zoning approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Nigeria Data Center Networking Market