
 Global DNS Service Market | 2026-2036
Global DNS Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNS Service Market Foresight
Asset-light subscription billing and usage-based leasing for DNS infrastructure is rewriting competitive entry barriers for mid-tier providers. Cloudflare leverages anycast network density to compete against hyperscaler incumbents. Amazon Web Services anchors enterprise trust through tight integration with cloud compute and storage portfolios. Google LLC differentiates via AI-driven threat detection layered into recursive resolution services.
Domain Name System services translate human-readable domain names into IP addresses through hierarchical, distributed database queries, typically resolving within 20-200 milliseconds depending on caching hierarchy and geographic proximity. The technology underpins virtually all internet commerce, communications, and cloud application access. Managed DNS offerings command premium positioning due to guaranteed uptime SLAs and DDoS mitigation commitments, while edge DNS deployments grow fastest as latency-sensitive applications proliferate. Cybersecurity applications within the application segment absorb disproportionate R&D investment as DNS-layer threat interception becomes a standard enterprise control.
The FCC enforces DNS security expectations for US telecommunications carriers under broadband infrastructure rules, while the EU AI Act imposes transparency requirements on automated DNS threat classification systems. China's MIIT mandates domestic DNS resolution logging for critical information infrastructure operators, shaping vendor localization strategies. Stakeholders must monitor divergence between sovereign data routing requirements and the technical feasibility of fragmented DNS root governance models.
Market Dynamics
The Global DNS Service Market contends with a fundamental architectural shift as sovereign data routing mandates collide with the technical requirements of unified root governance, forcing infrastructure providers to engineer jurisdictional segmentation capabilities.
Growth Catalysts
- Zero-trust security mandates:Federal agencies in the United States now require DNS-layer traffic inspection as a core pillar of network segmentation, accelerating procurement of managed resolution services with integrated threat intelligence.
- Edge computing proliferation:Latency-sensitive applications in autonomous vehicle coordination and industrial IoT command resolution times below 10 milliseconds, driving investment in geographically dense anycast networks.
- NIS2 Directive compliance:The European Union's expanded critical infrastructure framework imposes binding DNS security obligations on energy, transport, and digital providers, creating mandatory upgrade cycles.
Market Restraints
- Root server concentration:Thirteen logical root server operators maintain global coordination authority, creating systemic resilience risk that no single vendor can independently mitigate.
- IPv4 address scarcity:Exhaustion of unallocated IPv4 blocks forces complex carrier-grade NAT deployments that degrade DNS query path transparency and troubleshooting reliability.
- Cross-border data friction:China's MIIT domestic resolution logging requirements for critical information infrastructure operators fragment global traffic engineering optimization.
Strategic Opportunities
- India's digital infrastructure buildout:The country's PLI scheme for data center localization creates demand for sovereign DNS resolution stacks that comply with data localization mandates.
- AI-driven threat classification:Machine learning models trained on query pattern anomalies enable predictive DNS firewalling, opening premium service tiers for financial services and healthcare.
- Serverless edge deployment:Convergence of DNS resolution with edge compute containers allows application logic to execute at the resolution point, collapsing architectural latency.
Industry Challenges
- DNSSEC key management complexity:Zone signing key ceremonies require specialized cryptographic expertise that exceeds typical network operations team capabilities, delaying deployment.
- Legacy resolver integration:Embedded DNS clients in industrial control systems and medical devices resist firmware updates, creating persistent security exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNS Service Market |
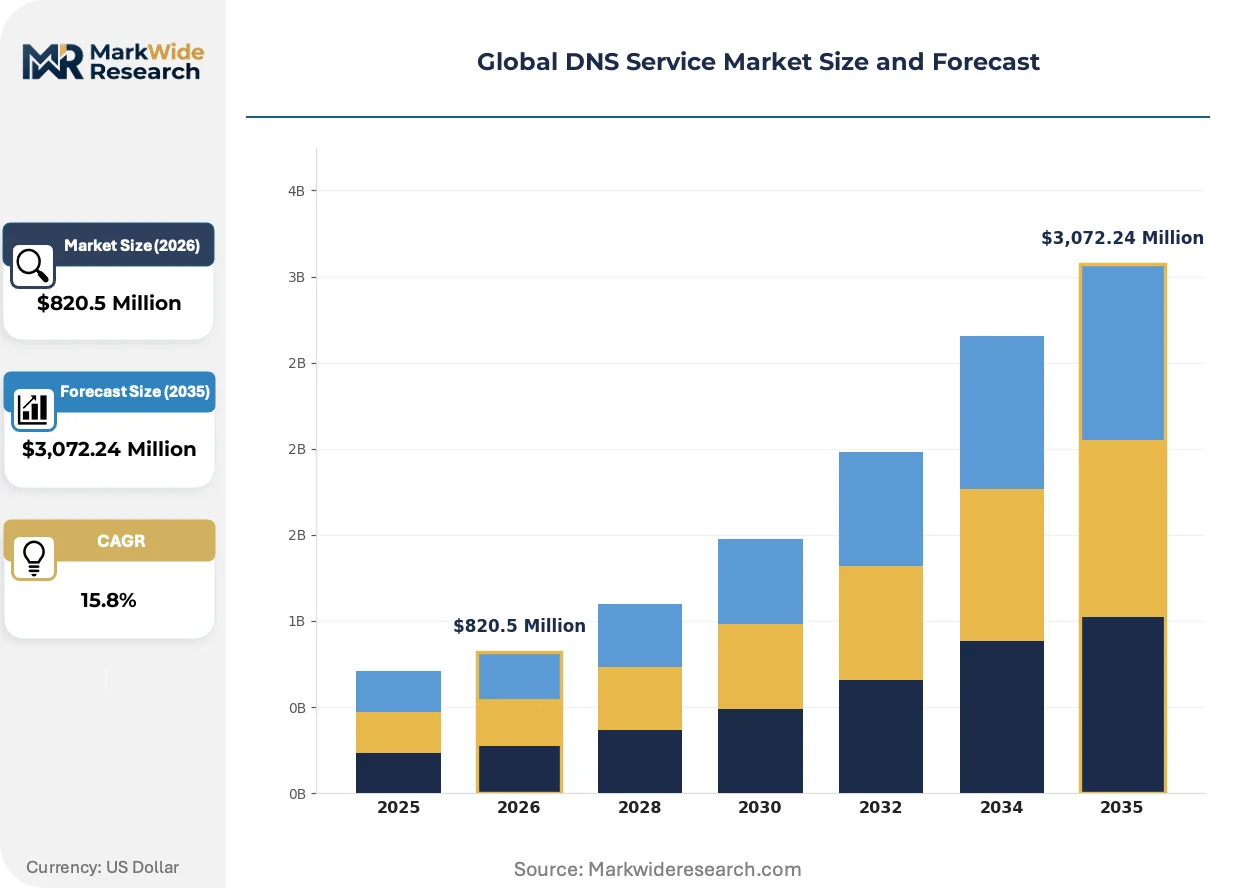
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,072.24 Million |
| CAGR (2026 – 2036) | 15.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Authoritative DNS, Recursive DNS, Forward DNS, Dynamic DNS, Managed DNS Deployment Model: Cloud-Based, On-Premises, Hybrid, Hosted, Edge DNS Application: Cybersecurity, Content Delivery, Load Balancing, Network Optimization, IoT Connectivity End User: Telecommunication Providers, Internet Service Providers, Content Delivery Networks, Managed Service Providers, Web Hosting Companies |
| Companies Covered | Cloudflare, Inc., Amazon Web Services, Inc., Microsoft Corporation, Google LLC, Akamai Technologies, Inc., Oracle Corporation, IBM Corporation, Cisco Systems, Inc., NS1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNS Service Market Shifts & Advancements
Resolution infrastructure is fragmenting into specialized stacks as latency requirements diverge across consumer, enterprise, and machine-to-machine traffic classes, each demanding distinct architectural trade-offs.
Encrypted DNS protocols are migrating from experimental deployment to default configuration. Mozilla Firefox and Apple iOS now ship with DNS-over-HTTPS enabled, forcing enterprise network administrators to deploy inspection proxies or accept blind encrypted tunnels. This protocol shift is compressing visibility for security teams and creating demand for resolver-based filtering services that operate inside the encrypted channel.
The EU AI Act imposes transparency requirements on automated DNS threat classification systems that use machine learning for domain reputation scoring. DNS security vendors serving European enterprises must now document training data provenance and decision logic for regulatory audit. Financial services firms in Frankfurt and Amsterdam are responding by demanding vendor-provided algorithmic impact assessments as contractual prerequisites.
Consumption patterns among hyperscale cloud buyers are consolidating procurement around bundled infrastructure stacks rather than standalone DNS contracts. Platform engineering teams at SaaS providers now expect resolution services to integrate natively with identity federation and workload orchestration layers. This bundling dynamic is most visible in North American enterprise accounts where cloud migration timelines compress vendor evaluation cycles.
Global DNS Service Market Segmentation
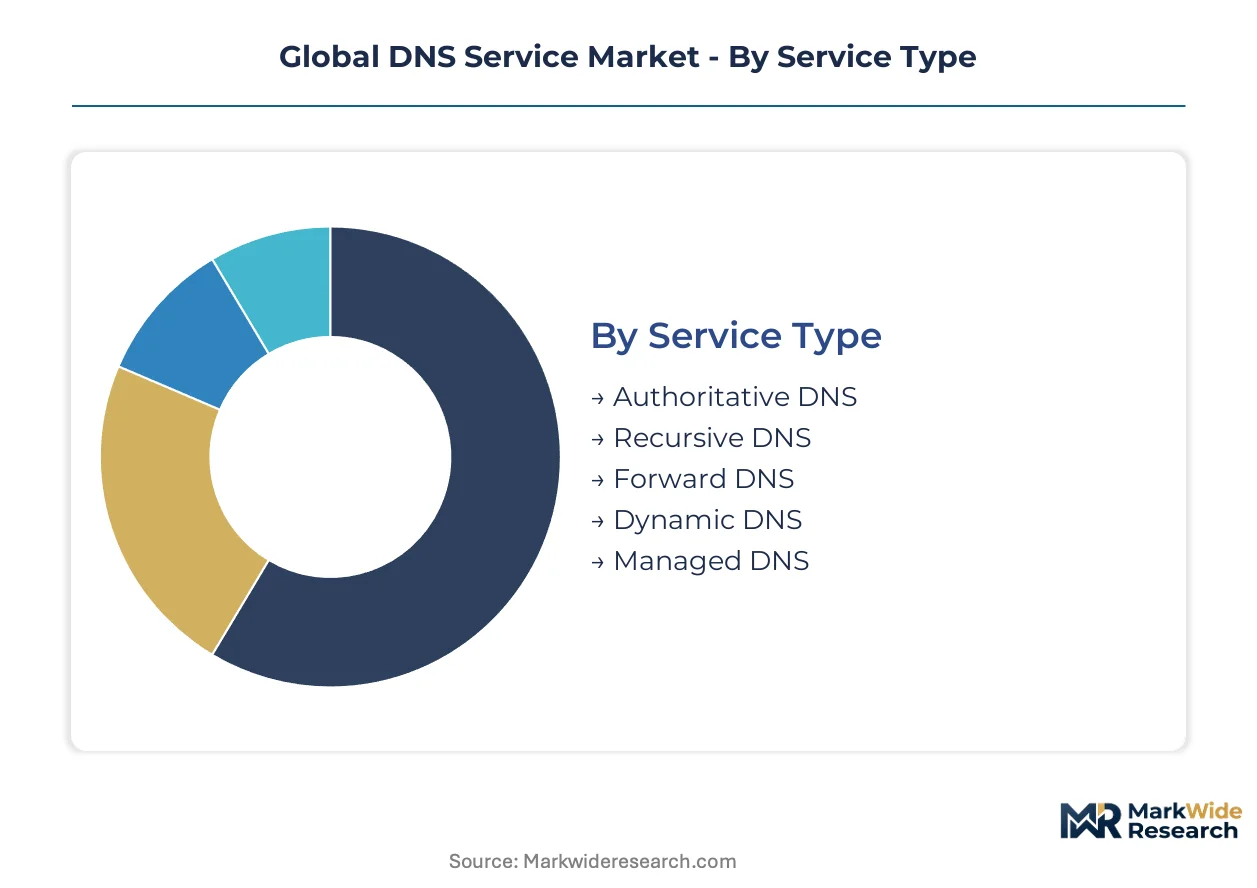
Segmentation in the DNS service market reveals how infrastructure specialization creates divergent margin structures across resolution architectures. Each category reflects distinct operational intensity profiles that reshape vendor competitive positioning and customer procurement criteria.
Service Type:
After-sales service intensity varies dramatically across resolution service types, with managed offerings demanding 24/7 incident response capabilities while recursive services operate with lighter ongoing touch requirements.
- Managed DNS:Comprehensive outsourcing of zone management, traffic steering, and DDoS mitigation backed by contractual uptime guarantees. Financial services firms in Frankfurt and Singapore drive premium-tier procurement as regulatory scrutiny intensifies.
- Authoritative DNS:Stores definitive domain records and responds to queries about specific zones. Cloud-native SaaS providers in San Francisco and Bangalore represent the core demand concentration as application architectures fragment across multi-cloud footprints.
- Recursive DNS:Resolves queries by traversing the DNS hierarchy on behalf of end clients. Enterprise IT departments prioritize resolver-based filtering to maintain visibility despite encrypted DNS protocol adoption.
- Dynamic DNS:Automatically updates DNS records as IP addresses change. Residential IoT deployments and remote workforce connectivity solutions absorb volume in this segment.
- Forward DNS:Translates domain names to IP addresses in standard query flows. Embedded in virtually every network stack, this segment competes primarily on latency performance rather than feature differentiation.
By volume, Recursive DNS leads due to universal endpoint dependency. By growth pace, Managed DNS is ahead as enterprise security postures mature.
Deployment Model:
Cost tier stratification separates hyperscaler-integrated deployments from sovereign infrastructure mandates, with hybrid architectures commanding middle-tier pricing as complexity premiums.
- Cloud-Based:Fully managed resolution infrastructure delivered via subscription without capital expenditure. North American SaaS providers and European fintechs drive procurement as zero-trust mandates eliminate on-premises resolver dependencies.
- Edge DNS:Distributed resolution nodes positioned within 50 kilometers of end users to guarantee sub-10 millisecond response times. Autonomous vehicle networks and industrial control systems in Stuttgart and Detroit require this architecture.
- Hybrid:Combines cloud scalability with on-premises control for sensitive zone data. Healthcare systems subject to HIPAA and German healthcare data regulations favor this model for patient-facing applications.
- On-Premises:Dedicated resolver hardware operated within customer data centers. Defense contractors and classified government facilities maintain this deployment despite higher total cost of ownership.
- Hosted:Single-tenant resolution infrastructure managed by third-party providers. Mid-market enterprises without internal DNS expertise select this option for predictable operational expenditure.
Cloud-Based deployments dominate current procurement volumes. Edge DNS exhibits the steepest expansion trajectory as latency-sensitive machine-to-machine traffic proliferates.
Application:
Customer type differentiation separates enterprise security buyers seeking threat interception from infrastructure teams optimizing delivery performance, with procurement authority often split across CISO and platform engineering functions.
- Cybersecurity:DNS-layer threat detection, domain reputation filtering, and tunneling prevention. Banking regulators in London and New York now mandate this capability as a core network segmentation control.
- Content Delivery:Geographic traffic steering and latency optimization for media streaming. Video platforms and gaming services in Seoul and Los Angeles drive specialized anycast network requirements.
- Load Balancing:Intelligent request distribution across server pools based on health and proximity. E-commerce platforms deploy this during high-traffic events to maintain checkout flow reliability.
- Network Optimization:Route selection and congestion avoidance through DNS-based traffic engineering. Telecommunication carriers leverage this to reduce transit costs and improve quality of experience metrics.
- IoT Connectivity:Lightweight resolution protocols for resource-constrained devices. Smart city deployments in Barcelona and Singapore require this for sensor network scalability.
Cybersecurity applications command the highest per-query revenue. IoT Connectivity is gaining share fastest as connected device populations multiply.
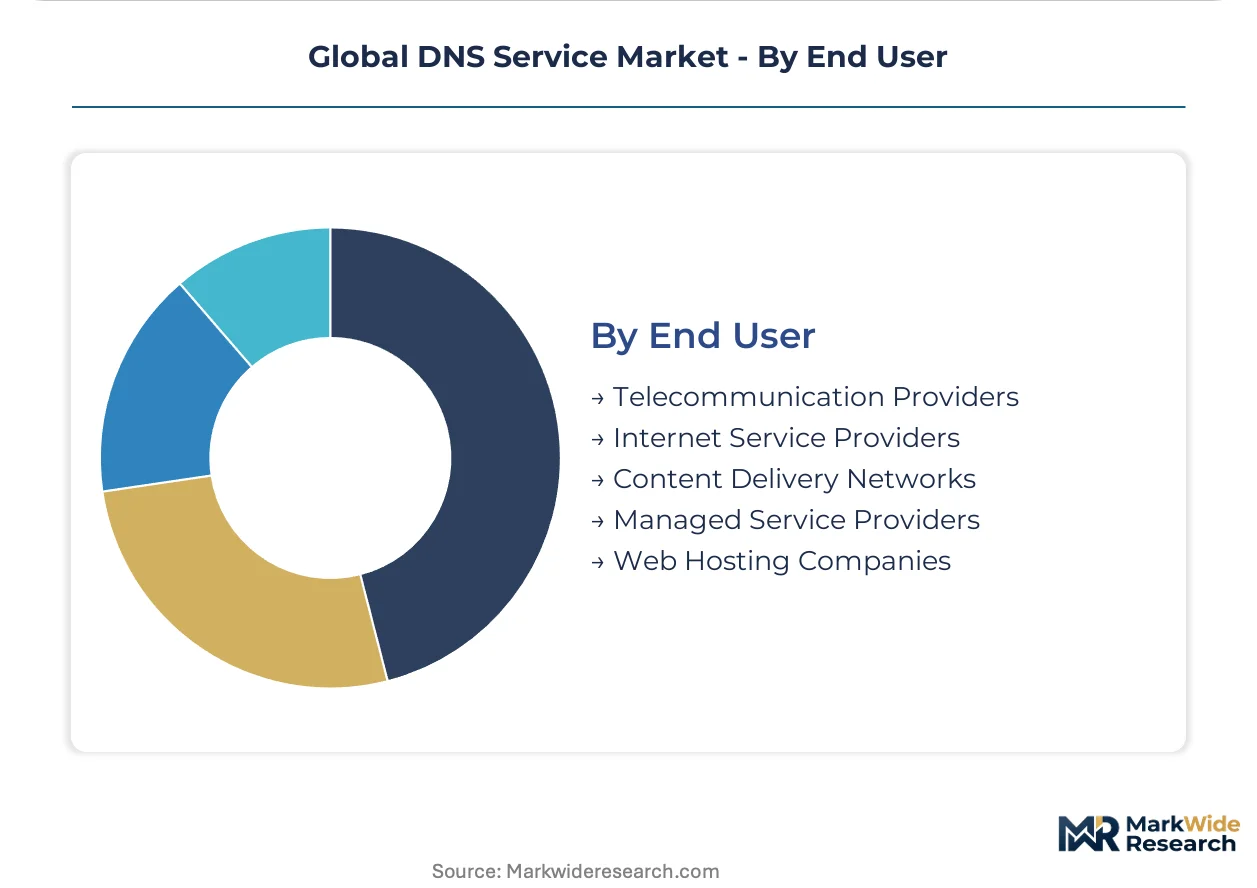
End User:
Supply concentration among hyperscale infrastructure operators creates tiered procurement dynamics, with telecommunications carriers negotiating enterprise terms while web hosting companies compete on reseller margin compression.
- Telecommunication Providers:National carriers operating DNS infrastructure for subscriber resolver services. FCC broadband infrastructure rules and EU NIS2 Directive compliance obligations reshape capital allocation toward security-hardened resolution stacks.
- Content Delivery Networks:Global edge platforms requiring recursive and authoritative resolution at every point of presence. These buyers demand API-native integration with caching and compute layers.
- Internet Service Providers:Regional and municipal broadband operators providing default resolver services. Regulatory logging requirements in Beijing and data minimization mandates in Amsterdam create divergent procurement specifications.
- Managed Service Providers:IT outsourcing firms bundling DNS into broader infrastructure management contracts. These intermediaries prioritize multi-tenant control planes and white-label reporting capabilities.
- Web Hosting Companies:Domain registration and hosting platforms offering basic resolution as a commodity attachment. Price sensitivity dominates procurement, with feature differentiation limited to control panel integration.
Telecommunication Providers represent the largest absolute spending category. Content Delivery Networks are expanding most quickly as edge computing architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in DNS services concentrates in the United States while European operators absorb compliance premiums from NIS2 Directive obligations. German and French enterprises pay 15-25% above North American benchmarks for equivalent managed resolution tiers. Indian and Chinese markets fragment into sovereign infrastructure stacks that resist standardization.
United States
Federal zero-trust mandates and hyperscaler concentration drive procurement of DNS-layer traffic inspection tools. FCC broadband infrastructure rules enforce security expectations for telecommunications carriers operating subscriber resolver services. San Francisco and Seattle anchor cloud-native SaaS demand as application architectures fragment across multi-cloud footprints.
Germany
Industrial IoT deployments in automotive and manufacturing command sub-10 millisecond resolution guarantees. EU NIS2 Directive imposes binding DNS security obligations on energy and transport operators, forcing mandatory upgrade cycles. Stuttgart's autonomous vehicle networks require edge DNS architectures for real-time coordination protocols.
China
Critical information infrastructure operators face MIIT-mandated domestic resolution logging requirements that fragment global traffic engineering. Sovereign data routing mandates collide with unified root governance, forcing jurisdictional segmentation capabilities. Beijing and Shanghai clusters concentrate state-aligned cloud providers building compliant resolution stacks.
India
PLI scheme incentives for data center localization create demand for sovereign DNS resolution stacks. Mid-tier enterprises seek asset-light subscription billing models that rewrite competitive entry barriers. Bangalore and Hyderabad absorb disproportionate investment as SaaS providers localize infrastructure for regulatory compliance.
Singapore
Financial services firms in the ASEAN hub procure premium managed DNS tiers with guaranteed uptime SLAs. Cross-border data friction from neighboring jurisdictions positions the city-state as a neutral resolution intermediary. Maritime and logistics operators deploy edge DNS for port automation and supply chain visibility systems.
Global DNS Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical control. The DNS service market structures around three tiers: hyperscale cloud providers bundling resolution with compute portfolios, pure-play DNS specialists competing on anycast network density, and telecommunications carriers defending subscriber resolver relationships. Strategic moves concentrate on API-native integration with identity federation layers and geographic expansion of edge node presence to satisfy latency-sensitive machine-to-machine traffic.
Among hyperscale platform operators, Amazon Web Services, Google LLC, and Cloudflare occupy distinct positioning archetypes. AWS anchors enterprise trust through tight integration with cloud compute and storage portfolios. Google exemplifies AI-driven threat detection layered into recursive resolution services. Cloudflare represents anycast network density as a competitive wedge against incumbent infrastructure providers. These three entities collectively shape procurement expectations for bundled infrastructure stacks across North American and European enterprise accounts.
| Leading Market Players |
|---|
| Cloudflare, Inc. |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| Akamai Technologies, Inc. |
| Oracle Corporation |
| IBM Corporation |
| Cisco Systems, Inc. |
| NS1 |
| Others |
Supply & Pricing Matrix
Single-source dependency on anycast network infrastructure determines both tier spreads and supply chain configuration across the DNS service landscape. Hyperscaler bundling and sovereign data mandates compress margins at the mid-market while premium managed tiers capture compliance premiums.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS-tiered pricing across cloud-based, edge, and hybrid deployment models. Pricing stratifies across premium managed tiers with guaranteed SLAs, standard bundled infrastructure stacks, and economy recursive resolver services. Cost compression in standard tiers is intensifying because hyperscalers absorb DNS into compute-storage portfolios at near-zero marginal pricing. Web hosting companies exhibit the highest price sensitivity, while financial services firms in Frankfurt and Singapore demonstrate the lowest.
Supply Chain Analysis
Extended payment terms from hyperscaler buyers strain pure-play DNS specialists operating at the infrastructure layer. Geographic supply concentrates in the United States, Germany, and China, with edge node deployment resting on fiber backbone density and data center localization. Raw material dependencies include submarine cable capacity, server-grade silicon, and renewable energy contracts for facility power. Single-source vulnerability persists in root server coordination authority. Distribution runs through direct enterprise sales, cloud marketplace integrations, and telecommunications carrier reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encrypted DNS protocols threaten to displace traditional resolver-based security visibility, forcing incumbents to engineer inspection capabilities inside encrypted tunnels or cede control to endpoint-native solutions.
For Market Incumbents: Entrench API-native integration with identity federation and workload orchestration layers to deepen platform stickiness. Expand anycast node density in Stuttgart, Detroit, and Singapore to capture autonomous vehicle and industrial IoT latency requirements. Counter Cloudflare's network density advantage through tighter vertical integration with cloud compute portfolios.
For New Entrants and Emerging Players: Mid-market healthcare systems in India seeking HIPAA-compliant hybrid deployments represent the most penetrable entry point. Sovereign DNS resolution stacks for PLI-scheme data centers in Bangalore and Hyderabad offer a second white-space target. Lead with algorithmic impact assessments as contractual prerequisites to exploit EU AI Act transparency requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors anycast network specialists with proven sub-10 millisecond latency capabilities. Long-term viability hinges on jurisdictional segmentation engineering for sovereign data routing mandates. Monitor divergence between China's MIIT logging requirements and unified root governance feasibility as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Expansion | Sub-10 millisecond guarantees capture autonomous vehicle coordination protocols in Stuttgart and Detroit. |
| AI-Driven Threat Classification | Machine learning models trained on query anomalies open premium tiers for Frankfurt banking regulators. |
| Jurisdictional Segmentation Engineering | Compliance with China's MIIT mandates and EU NIS2 Directive enables sovereign market access. |
| Encrypted DNS Inspection Proxy Development | Mozilla Firefox and Apple iOS defaults force enterprise visibility solutions inside encrypted channels. |
| Platform Integration with Hyperscaler Marketplaces | Native AWS, Azure, and GCP bundling captures compressed procurement cycles among SaaS providers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with DNS infrastructure architects, CISOs at financial services firms, platform engineering leads at SaaS providers, and telecommunications carrier network operations directors; and secondary validation through SEC filings from hyperscaler cloud operators, FCC broadband infrastructure rulemakings, EU NIS2 Directive implementation guidance, and China MIIT critical information infrastructure circulars. Bottom-up triangulation across service type, deployment model, and application segmentation intersected with top-down macroeconomic and regulatory scenario analysis.
Forecast inputs considered zero-trust mandate adoption curves, encrypted DNS protocol penetration rates, edge computing investment cycles, and sovereign data localization policy trajectories across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, application use case, end-user category, and regional regulatory cluster. CAGRs derived from historical infrastructure spending patterns, hyperscaler capex disclosures, and compliance-driven upgrade cycle timing.
Practitioners should monitor encrypted DNS default adoption rates, NIS2 Directive enforcement severity, and root server governance fragmentation for early signals of trajectory revision. Macroeconomic contraction in cloud infrastructure spending, regulatory deviation from current sovereign data routing frameworks, or breakthroughs in quantum-resistant DNSSEC would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Belgium Data Center Networking Market