
 Computer Network Design Services Market | 2026-2036
Computer Network Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Network Design Services Market Analysis
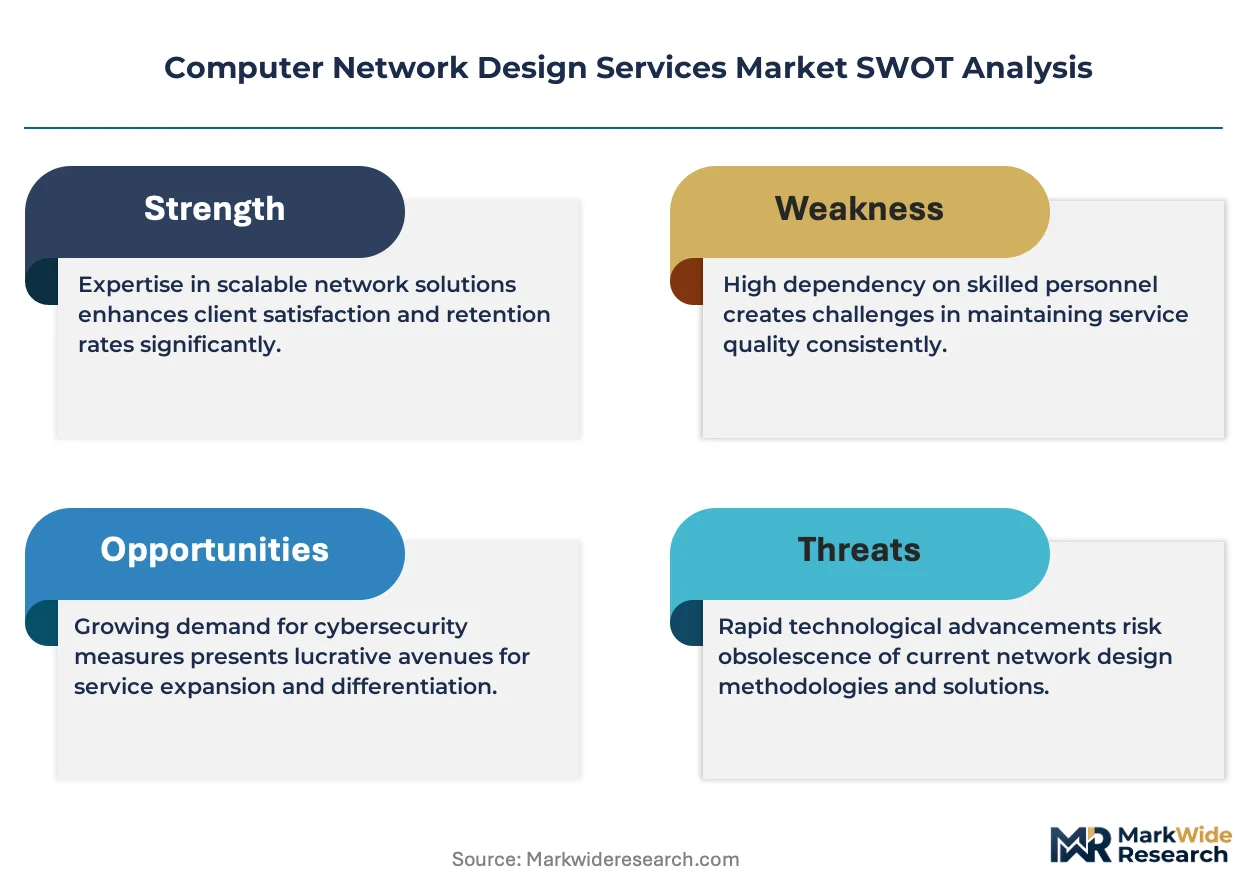
India is rewriting competitive dynamics in computer network design services as domestic cloud infrastructure investments surge. Cisco Systems leverages its routing and switching portfolio to anchor enterprise campus redesigns across South Asia. Juniper Networks competes through automation-first architectures that reduce operational overhead for service providers. Huawei Technologies extends its presence in emerging markets through cost-optimized 5G transport and core network design capabilities.
Computer network design services encompass the architectural planning, topology engineering, and performance modeling of data transmission systems using protocols such as BGP, OSPF, and SDN controllers with sub-50ms failover requirements. These services enable organizations to build resilient, scalable infrastructure that supports real-time applications across distributed locations. Cloud-based deployment models are capturing accelerated demand as enterprises migrate workloads away from legacy on-premises data centers. Implementation services command premium margins where multi-vendor integration complexity rises. Large enterprises dominate customer-type revenue pools, though SME uptake is rising through managed network-as-a-service offerings.
The US FCC mandates universal broadband coverage, while the EU AI Act imposes data governance requirements that reshape network segmentation strategies for cross-border traffic. India's TRAI spectrum allocation rules and China's MIIT 5G infrastructure directives create divergent compliance environments for multinational design engagements. Stakeholders must monitor how zero-trust security mandates from ISO 27001 and NIST frameworks will recast access-layer architecture specifications before committing to multi-year infrastructure roadmaps.
Market Dynamics
Zero-trust security mandates from NIST and ISO 27001 are forcing enterprises to rebuild access-layer architectures from the ground up, creating cascading demand for specialized network redesign services across every vertical.
Growth Catalysts
- FCC Broadband Mandates:Universal coverage requirements in the United States are accelerating fiber and fixed wireless deployment timelines, requiring extensive outside plant engineering and core network redesign.
- Healthcare Infrastructure:Telemedicine expansion and electronic health record interoperability under HIPAA security rules are driving hospital network segmentation projects.
- Industrial Automation:Smart factory investments in Germany are concentrating demand for time-sensitive networking architectures that integrate operational technology with enterprise IT.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers certified in BGP, OSPF, and SDN controller deployment creates project bottlenecks and wage inflation.
- Component Lead Times:Optical transport and high-speed switching hardware from concentrated Asian manufacturing bases extend deployment schedules.
- Regulatory Fragmentation:Divergent data localization rules across EU GDPR, China's MIIT directives, and India's TRAI spectrum policies complicate cross-border network architecture.
Strategic Opportunities
- Edge Computing Convergence:Integration of 5G transport with distributed cloud infrastructure creates new design service categories for ultra-low latency applications.
- SME Managed Services:Network-as-a-service offerings are penetrating mid-market segments previously excluded by capex barriers.
- EU AI Act Compliance:Data governance requirements for cross-border AI traffic are reshaping segmentation strategies and creating advisory revenue streams.
Industry Challenges
- Legacy System Integration:Enterprises maintaining decades-old MPLS and TDM infrastructure face complex migration paths to SD-WAN and SASE architectures.
- Certification Velocity:Rapid evolution of vendor-specific cloud networking credentials outpaces workforce development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Network Design Services Market |
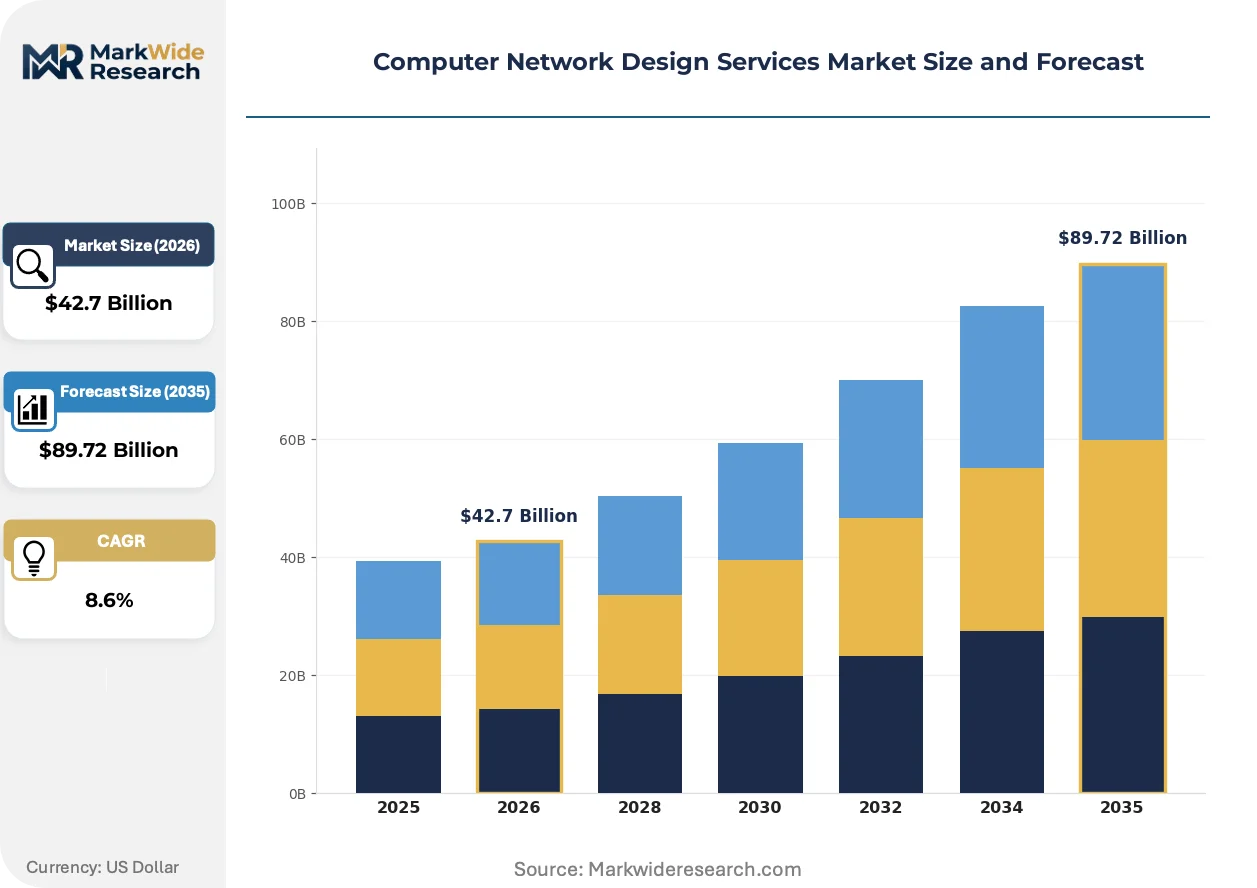
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Implementation, Management, Monitoring Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote Industry Vertical: Healthcare, Education, Financial Services, Retail Customer Type: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | Cisco Systems, Juniper Networks, Hewlett Packard Enterprise, Huawei Technologies, International Business Machines Corporation, Accenture, Telefonaktiebolaget LM Ericsson, Arista Networks, FUJITSU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Network Design Services Market Emerging Trajectories
Intent-based networking systems are automating configuration management at scale, compressing design-to-deployment cycles and redefining how engineering firms structure service delivery models.
Artificial intelligence for IT operations is rendering obsolete manual topology mapping and capacity planning workflows. Large enterprises with distributed campuses are deploying AIOps platforms at accelerating velocity. This automation is compressing margins on traditional assessment and documentation services.
The EU AI Act imposes data governance requirements that reshape network segmentation strategies for cross-border traffic. Financial services and healthcare providers must implement enhanced monitoring and logging architectures. German and French enterprises are investing most heavily in compliance-ready designs.
Consumption-based procurement models are displacing perpetual licensing for network design engagements. Mid-market buyers favor subscription arrangements that bundle ongoing optimization with initial architecture. This shift is most visible in India's cloud-first enterprise segment.
Computer Network Design Services Market Segmentation
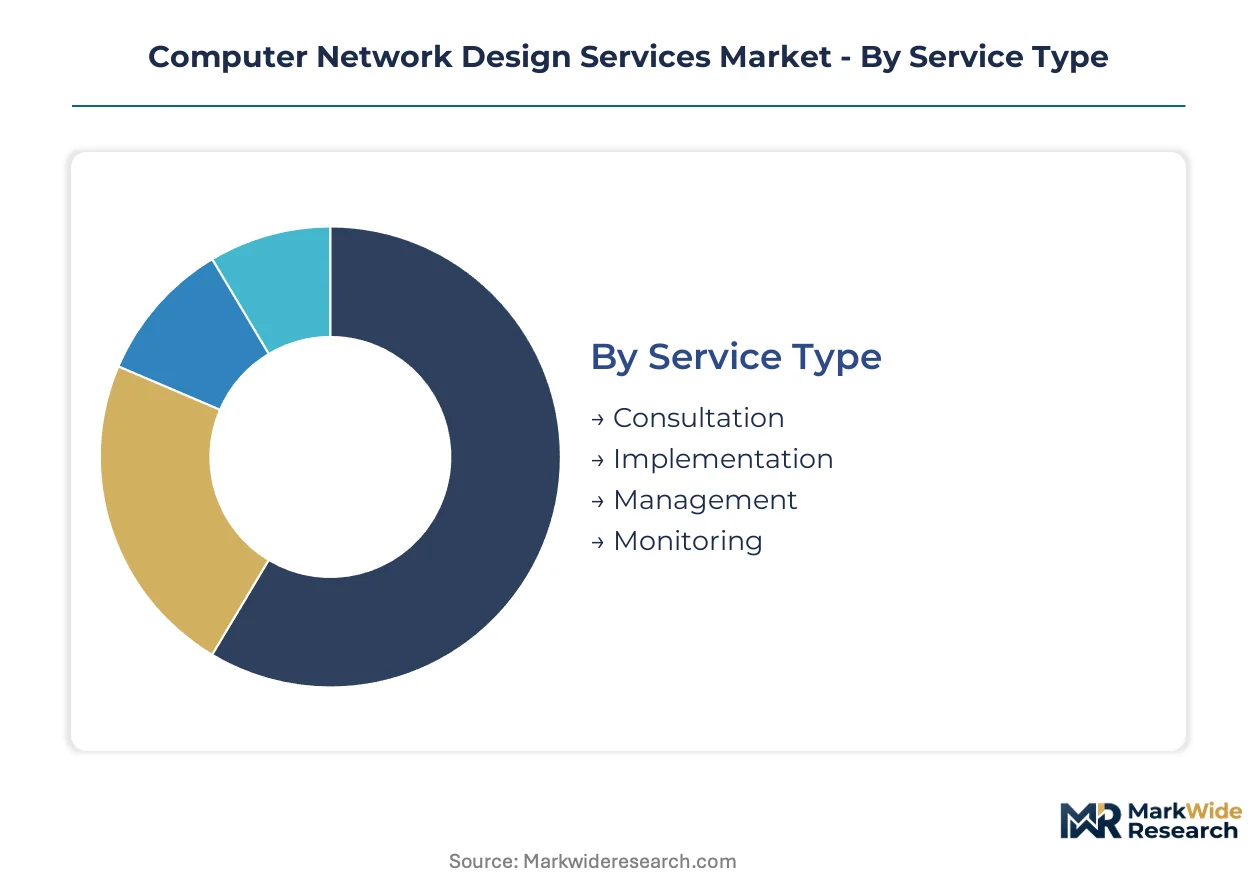
Computer network design services fragment across service delivery modes, infrastructure locations, sector-specific compliance requirements, and organizational scale. Each dimension carries distinct procurement patterns and margin structures that reshape vendor positioning.
Service Type:
Use-case spectrum spans advisory engagements through operational handoff, with complexity and duration varying dramatically across the workflow chain.
- Consultation:Architectural planning and topology engineering services establish baseline requirements for protocol selection and failover specifications. Healthcare providers in the United States commission consultation services to align network segmentation with HIPAA security rules before capital commitment.
- Implementation:Physical deployment and multi-vendor integration commands premium pricing where optical transport hardware and SDN controller configuration intersect. German smart factory investments drive concentrated implementation demand for time-sensitive networking that bridges operational technology with enterprise IT.
- Management:Ongoing operational support for configured infrastructure.
- Monitoring:Continuous performance surveillance and alerting services.
Established volume favors Implementation; emerging adoption favors Consultation.
Deployment Model:
Cost tier differentiation separates capital-intensive builds from operational expenditure models, with procurement authority shifting accordingly.
- Cloud-Based:Subscription-provisioned network infrastructure eliminates data center capital requirements while introducing latency and sovereignty trade-offs. India's cloud-first enterprise segment shows steepest expansion trajectory for this model as domestic infrastructure investments mature.
- Hybrid:Split architectures preserve sensitive workloads on-premises while bursting elastic demand to cloud. Financial services firms in Germany and France commission hybrid designs to satisfy EU AI Act data governance requirements for cross-border AI traffic.
- On-Premises:Fully captive infrastructure maintained within organizational facilities.
- Remote:Distributed access architectures supporting geographically dispersed endpoints.
Legacy concentration sits with On-Premises; procurement momentum favors Cloud-Based.
Industry Vertical:
Application-specific compliance mandates and performance thresholds create divergent design specifications across sectors.
- Healthcare:Telemedicine expansion and electronic health record interoperability drive hospital network segmentation projects with sub-50ms failover requirements. US providers rebuild access-layer architectures to satisfy zero-trust security mandates from NIST frameworks.
- Financial Services:Real-time transaction processing and fraud detection systems demand ultra-low latency transport with enhanced monitoring architectures. EU AI Act compliance investments concentrate heaviest among German and French enterprises in this vertical.
- Education:Campus-wide connectivity and research network integration.
- Retail:Distributed point-of-sale and inventory management connectivity.
Regulatory intensity peaks in Healthcare; margin expansion favors Financial Services.
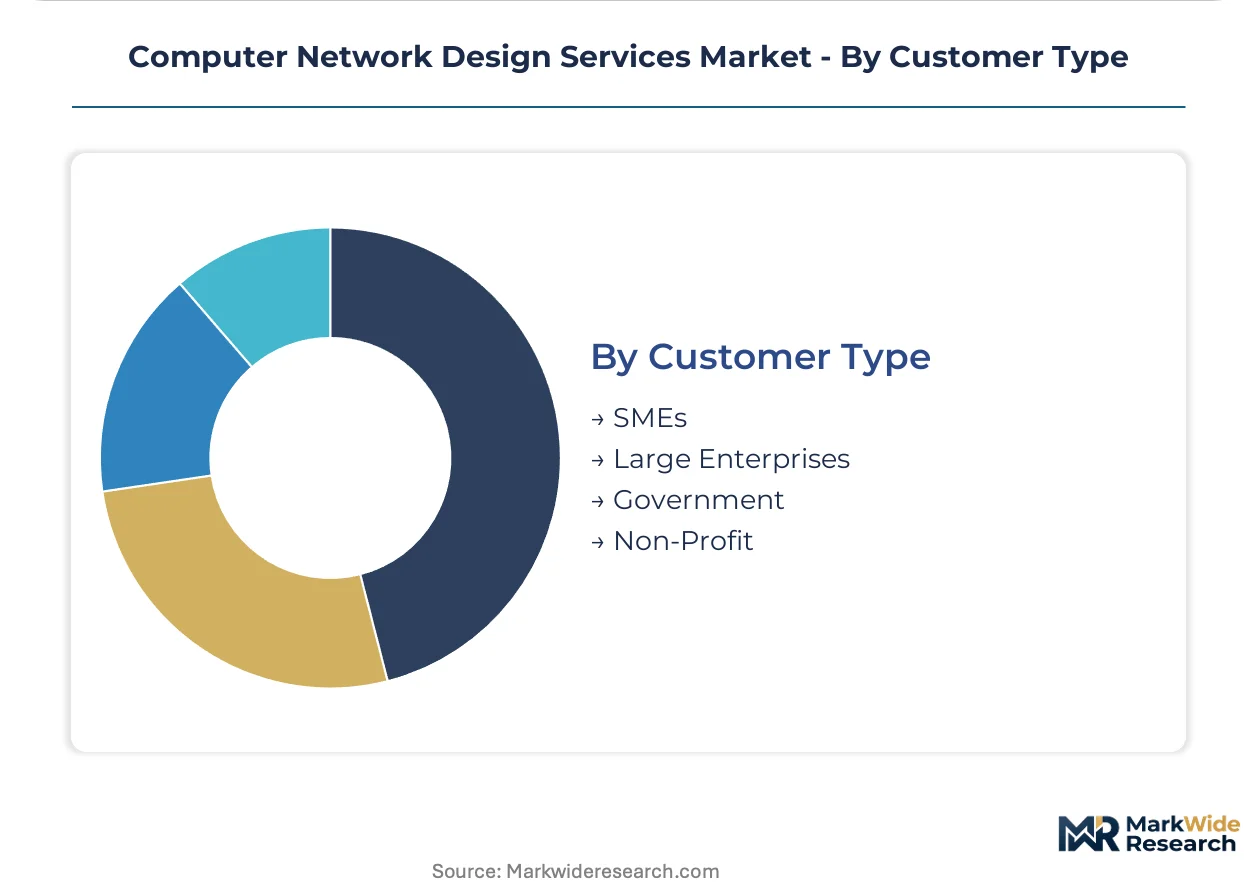
Customer Type:
Organizational scale determines procurement modality, with capital availability and internal technical capacity as decisive factors.
- Large Enterprises:Distributed campus environments with dedicated network engineering teams commission complex multi-site architectures. Intent-based networking and AIOps platforms compress traditional assessment service margins while accelerating design-to-deployment cycles.
- SMEs:Mid-market segments previously excluded by capex barriers access network capabilities through managed network-as-a-service offerings. Subscription procurement models displace perpetual licensing most visibly in India's domestic market.
- Government:Public sector infrastructure with specific procurement and security requirements.
- Non-Profit:Cost-constrained organizations prioritizing mission-critical connectivity.
Revenue concentration remains with Large Enterprises; penetration gains favor SMEs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US enterprises prioritize zero-trust security rebuilds. German manufacturers invest in time-sensitive networking. Indian cloud-first buyers favor subscription procurement over capital builds.
United States
FCC broadband mandates accelerate fiber and fixed wireless deployment across rural and underserved markets. HIPAA security rules compel healthcare providers to segment networks for telemedicine and electronic health record systems. Dallas-Fort Worth and Northern Virginia data center corridors concentrate demand for core network redesign and edge computing integration.
Germany
Smart factory investments in automotive and industrial machinery drive time-sensitive networking architectures bridging operational technology with enterprise IT. EU AI Act data governance requirements reshape segmentation strategies for cross-border AI traffic. Bavaria's manufacturing belt leads procurement of specialized network design services for Industry 4.0 implementations.
India
Domestic cloud infrastructure investments surge as enterprises migrate workloads from legacy data centers. TRAI spectrum allocation rules create compliance complexity for multinational design engagements. Bangalore and Hyderabad technology corridors anchor demand for managed network-as-a-service offerings among mid-market buyers.
China
MIIT 5G infrastructure directives accelerate transport and core network buildouts across industrial zones. Data localization requirements complicate cross-border architecture for foreign-invested enterprises. Yangtze River Delta manufacturing clusters concentrate procurement of private 5G network designs for smart factory applications.
United Kingdom
Financial services firms commission ultra-low latency transport for real-time transaction processing and fraud detection systems. GDPR cross-border data flow rules influence network segmentation for international banking operations. London's fintech corridor drives advisory demand for compliance-ready designs under evolving regulatory frameworks.
Computer Network Design Services Market Vendor Landscape
Capability concentration sits with full-stack infrastructure vendors; scale advantage sits with systems integrators and managed service providers. The market structures around three tiers: hardware-anchored design firms, automation-first specialists, and advisory-led consultancies. Dominant competitive moves include strategic partnerships between equipment vendors and cloud platforms, plus geographic expansion through local certification acquisitions.
Within the hardware-anchored tier, Cisco Systems and Juniper Networks exemplify contrasting approaches to enterprise campus and service provider engagements. Cisco's routing and switching portfolio anchors redesign projects across distributed environments. Juniper occupies a position emphasizing automation-first architectures that reduce operational overhead. Huawei Technologies represents the emerging-market vector through cost-optimized transport and core capabilities. International Business Machines Corporation and Accenture sit within the advisory-led tier, translating compliance mandates into implementation roadmaps for regulated verticals.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| International Business Machines Corporation |
| Accenture |
| Telefonaktiebolaget LM Ericsson |
| Arista Networks |
| FUJITSU |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber-optic cable routes carry escalating freight premiums that compress margins on optical transport hardware while amplifying price differentiation between turnkey implementation services and standalone design consulting. Procurement officers at German automotive manufacturers now negotiate extended payment terms that shift working capital burdens upstream to specialized network engineering firms.
Pricing Analysis
Long-term managed service contracts dominate enterprise procurement, displacing project-based engagements as cloud migration accelerates. Price differentiation rests on certification density—engineers holding Cisco CCIE or Juniper JNCIP credentials command 40-60% premiums over uncertified peers—and vertical specialization in HIPAA-compliant healthcare or EU AI Act-ready financial architectures. Cost compression in mid-market segments intensifies as Indian cloud-first buyers favor subscription bundling over capital-intensive builds. SMEs exhibit highest price sensitivity; large enterprises with captive engineering teams prioritize outcome guarantees over rate negotiation.
Supply Chain Analysis
Supply-chain finance facilities from concentrated Asian manufacturing bases extend payment cycles to 90-120 days for optical transceivers and high-speed switching ASICs. Component sourcing draws from Taiwan, China, and South Korea for advanced silicon photonics and merchant silicon. Single-source vulnerability concentrates in 400G/800G optical module suppliers, with logistics chokepoints at Shanghai and Shenzhen port complexes. Distribution runs through authorized value-added distributors and direct OEM channels to systems integrators, bypassing traditional IT resellers for complex multi-vendor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in SME network-as-a-service penetration, where capex-to-opex conversion creates niche openings for specialized automation-first providers outside incumbent hardware ecosystems.
For Market Incumbents: Harden certification pipelines against automation-driven margin erosion by embedding intent-based networking expertise into managed service offerings. Acquire boutique compliance consultancies in Germany and France to capture EU AI Act advisory revenue. Vertical integration into captive optical transport manufacturing mitigates lead-time volatility from Asian supply bases. For New Entrants and Emerging Players: India's tier-2 technology corridors—Pune, Chennai, Kochi—offer underpenetrated mid-market density with limited incumbent presence. Target healthcare providers in secondary US metropolitan areas lacking specialized HIPAA segmentation expertise. Lead with consumption-based procurement platforms that bundle ongoing optimization with initial architecture, mirroring cloud-native buyer preferences. For Investors and Strategic Acquirers: Automation-first engineering boutiques with proven AIOps deployment track records represent compelling acquisition targets as enterprise buyers prioritize operational overhead reduction. Monitor certification velocity gaps—where vendor-specific cloud networking credentials outpace workforce development—as inflection indicators for talent arbitrage opportunities. Long-term viability favors firms with recurring revenue concentration above 60% of total engagement value.| Strategic Initiative | Industry Significance |
|---|---|
| Intent-Based Networking Deployment | Automated configuration management compresses design-to-deployment cycles for Cisco and Juniper enterprise clients. |
| Zero-Trust Architecture Certification | NIST SP 800-207 compliance specialization unlocks federal and healthcare vertical procurement channels. |
| Edge Computing Infrastructure Partnership | 5G transport integration with distributed cloud creates ultra-low latency service categories for smart factory implementations. |
| Managed Network-as-a-Service Launch | Subscription bundling penetrates Indian SME segments previously excluded by capital expenditure barriers. |
| EU AI Act Compliance Advisory | Data governance roadmaps for cross-border AI traffic generate recurring revenue from German and French financial services firms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network architects at Cisco and Juniper, service provider engineering directors, healthcare IT security officers, and German automotive OT-IT integration leads. Secondary validation drew from FCC broadband deployment filings, EU AI Act regulatory texts, TRAI spectrum allocation orders, SEC 10-K infrastructure vendor disclosures, and hyperscaler capex announcements. Bottom-up triangulation across project-level procurement data and top-down reconciliation against vendor-reported service revenue established dimensional integrity.
Calibration against historical deployment velocity and regulatory implementation timelines anchored projections across the analysis window. Segmentation modeling incorporated service type, deployment model, industry vertical, customer scale, and geographic regulatory cluster. CAGRs derived from compound annual trajectory fitting to disclosed vendor growth rates and infrastructure investment forecasts. Specific inputs included fiber deployment timelines under FCC mandates, smart factory capital commitment schedules from German automotive OEMs, and cloud infrastructure investment trajectories from Indian domestic hyperscalers.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting infrastructure financing costs or trade policy shifts impacting optical component tariffs would shift the trajectory. Forecasts reflect documented assumptions around regulatory implementation pacing and vendor certification program expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Global Managed SD-WAN Service Market