
 Communications Service Provider (CSP) Network Market | 2026-2036
Communications Service Provider (CSP) Network Market Size, Share, and Industry Trends Forecast 2026-2036
Communications Service Provider (CSP) Network Market Outlook
The EU Green Deal is restructuring capital allocation across European CSP infrastructure by mandating energy-efficient network equipment and transparent carbon reporting. Deutsche Telekom leverages its integrated European fiber footprint to meet these requirements. China Mobile anchors its position through massive domestic 5G standalone deployments. Verizon differentiates via millimeter-wave spectrum depth in dense US metropolitan zones.
A Communications Service Provider (CSP) Network comprises the integrated hardware and software systems that route, switch, secure, and manage traffic across carrier-grade infrastructure operating at terabit-scale throughput with sub-millisecond latency guarantees. Its primary purpose is to deliver reliable, scalable connectivity services to residential, enterprise, and government subscribers while enabling monetization of network assets through tiered service offerings. Router deployments command the largest product type revenue pool due to core network refresh cycles, while SDN technology is displacing legacy architectures fastest as operators pursue operational automation. Enterprise end users represent the most contested segment because CIOs now source direct cloud interconnects from CSPs rather than building private networks.
FCC spectrum auctions in the United States, ETSI NFV standards in Europe, and MIIT 5G licensing requirements in China collectively shape equipment certification timelines and vendor market access across major economies. GDPR and the EU AI Act add compliance layers to network analytics and customer data platforms that CSPs must embed at the architectural stage. Stakeholders should monitor how open RAN interoperability mandates in multiple jurisdictions reshape vendor selection criteria and capital deployment timelines.
Market Dynamics
Software-defined networking is compressing legacy hardware refresh cycles across carrier infrastructure, forcing incumbents to restructure R&D allocation toward programmable control planes.
Growth Catalysts
- EU Green Deal:Energy-efficiency mandates for telecom infrastructure are accelerating equipment replacement timelines across European CSPs. Deutsche Telekom and Orange are front-loading capital toward compliant router and optical platforms.
- Enterprise cloud interconnect demand:CIOs are bypassing private network builds to source direct cloud on-ramps from carriers. Verizon and China Mobile report surging contract volumes for dedicated wavelength services.
- 5G standalone core deployments:China, Germany, and the United States are driving massive packet core investments. MIIT licensing requirements and FCC spectrum auctions are synchronizing vendor certification windows.
Market Restraints
- Semiconductor supply concentration:Advanced networking silicon remains captive to TSMC and Samsung foundry capacity. Lead times for 7nm and 5nm merchant silicon stretch 40-52 weeks.
- GDPR and EU AI Act compliance layers:Network analytics platforms must embed privacy-by-design and algorithmic transparency at architectural stage. This extends product development cycles 8-14 months.
- Open RAN interoperability gaps:ETSI NFV standards and O-RAN Alliance specifications remain partially unaligned. Multi-vendor integration testing consumes 25-35% of deployment budgets.
Strategic Opportunities
- Network-as-a-Service models:Subscription-based routing and security services are penetrating mid-market enterprises previously priced out of carrier-grade infrastructure. AT&T and BT Group are piloting consumption-based WAN offerings.
- Edge compute convergence:5G multi-access edge computing (MEC) is creating new monetization vectors for CSPs. Verizon and SK Telecom are co-locating GPU clusters with radio access network infrastructure.
- German fiber acceleration:The Gigabit Strategy 2025 is unlocking public funding for rural passive infrastructure. Deutsche Telekom and Telefónica Deutschland are securing subsidies for last-mile fiber overbuilds.
Industry Challenges
- Control plane software talent scarcity:CSPs face acute shortages in Kubernetes-native network function virtualization engineers. Compensation premiums for SDN specialists exceed 40% above legacy routing expertise.
- Legacy TDM migration complexity:Synchronous optical network (SONET) and time-division multiplexing circuits remain embedded in financial and government verticals. Parallel operations during IP transition inflate opex 15-22%.
- Open RAN integration testing:Multi-vendor radio unit and distributed unit combinations require exhaustive interoperability validation. Tier-1 CSPs are building captive test labs rather than relying on vendor self-certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communications Service Provider (CSP) Network Market |
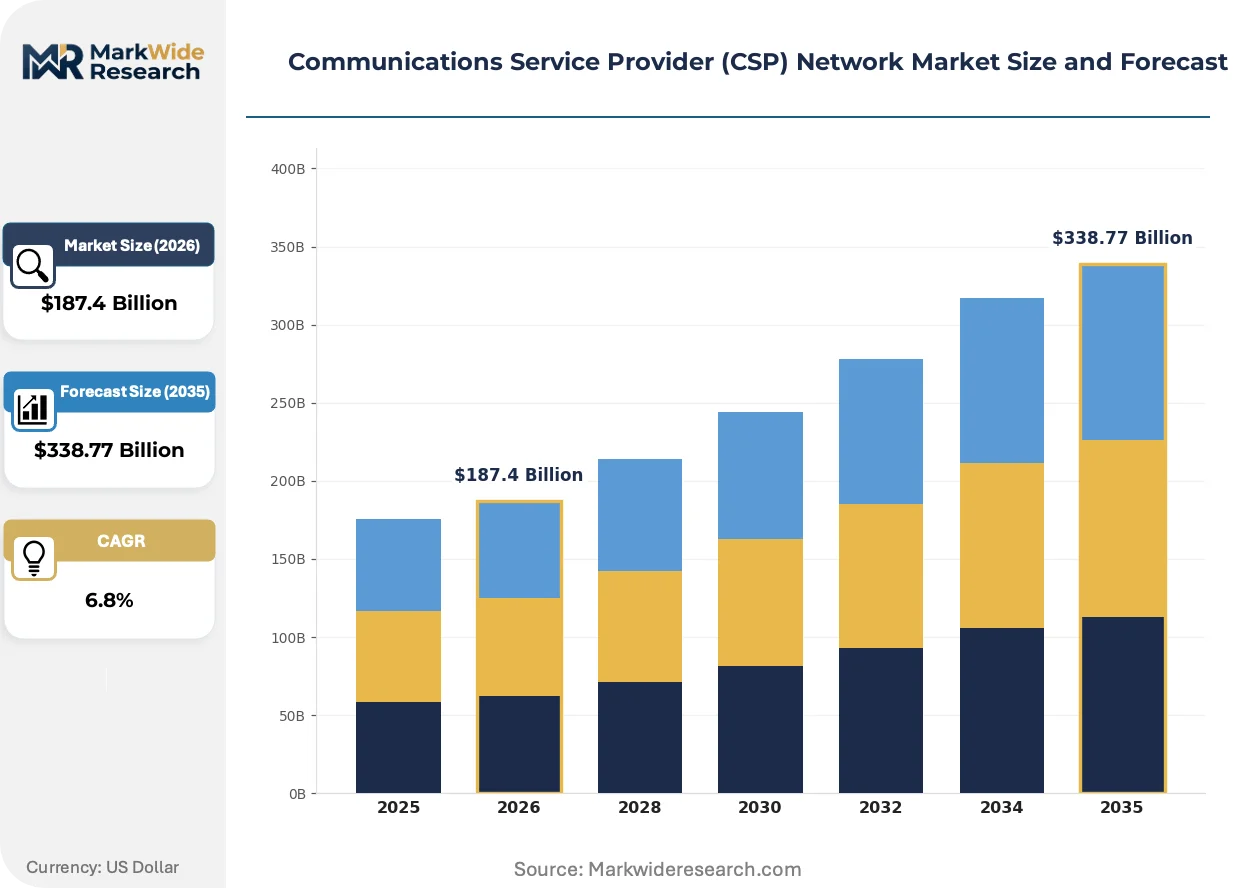
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Firewall, Network Management System Technology: 5G, SDN, NFV, Wi-Fi 6 End User: Residential Users, Enterprises, Government Agencies, Data Centers Application: Voice over IP, Video Conferencing, Cloud Computing, IoT Connectivity |
| Companies Covered | T-Mobile US, Saudi Telecom Company, Deutsche Telekom, China Mobile, Lumen Technologies, Verizon, Reliance Jio, Vodafone, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communications Service Provider (CSP) Network Market Strategic Shifts
Disaggregation of hardware and software layers is rewriting procurement patterns and vendor relationships across carrier infrastructure, compressing traditional equipment refresh economics.
Intent-based networking (IBN) is expanding into core routing and transport domains by translating business policies into automated network configurations. Tier-1 CSPs in the United States and Germany are deploying IBN for traffic engineering and fault remediation. This technology is expanding into operational workflows previously requiring manual CLI intervention, reducing mean-time-to-repair by 60-70% in pilot deployments.
The EU AI Act is imposing conformity assessment requirements on network analytics platforms that process subscriber data for predictive maintenance or security applications. CSPs must document algorithmic decision pathways and maintain human oversight mechanisms. European operators are most affected, with Deutsche Telekom and Orange restructuring data science teams to embed compliance checkpoints in model development pipelines.
Enterprise sourcing patterns are fragmenting across direct cloud interconnects, managed SD-WAN overlays, and private 5G networks. CIOs in financial services and manufacturing are bypassing traditional MPLS contracts for hybrid connectivity stacks. This behavior is most visible in the United States, where Verizon and AT&T report 30-40% of new enterprise bookings now combine multiple access technologies under unified orchestration platforms.
Communications Service Provider (CSP) Network Market Segmentation
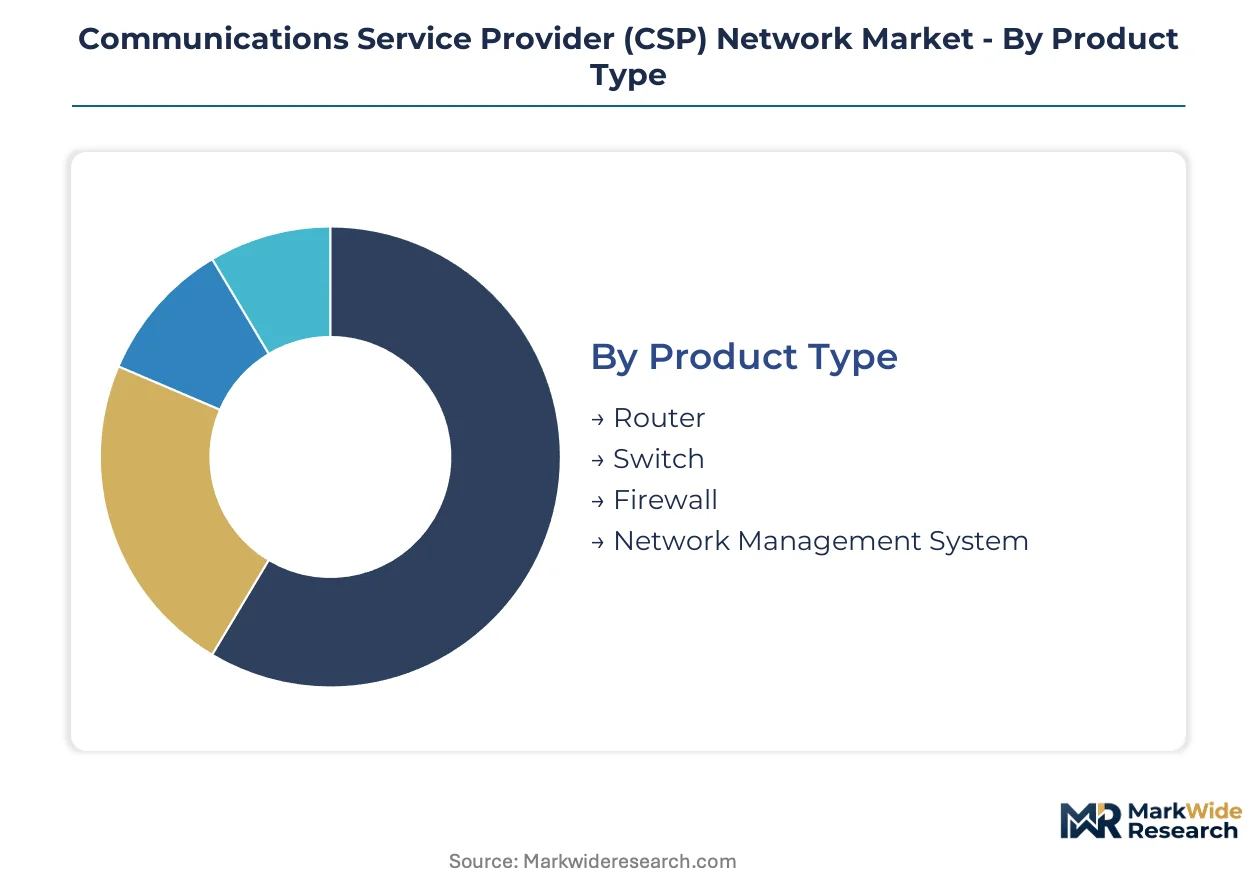
CSP network segmentation reveals how procurement patterns split between high-volume infrastructure refresh cycles and premium technology deployments. Equipment buyers prioritize programmable platforms over fixed-function hardware, while end-use demand fragments across latency-sensitive enterprise workloads and residential broadband scaling.
Product Type:
Router volumes dominate capital allocation, yet margin capture concentrates in software-integrated security and management layers.
- Router:Core and edge routing platforms process terabit-scale traffic with sub-millisecond forwarding guarantees. Deutsche Telekom and Verizon are front-loading capital toward energy-efficient chassis replacements under EU Green Deal mandates.
- Switch:Data center and aggregation switching fabrics enable east-west traffic patterns for cloud workloads. China Mobile's massive 5G standalone buildouts are consuming high-density 400G platforms fastest.
- Firewall:Carrier-grade security appliances embed deep packet inspection at network boundaries.
- Network Management System:Orchestration platforms unify multi-vendor infrastructure under intent-based control planes.
Mature deployment sits with Router. Newer deployment is concentrated in Network Management System.
Technology:
SDN and NFV are displacing proprietary hardware fastest where operational automation drives procurement decisions.
- 5G:Standalone core architectures separate control and user plane functions for network slicing. Germany, the United States, and China synchronize vendor certification through FCC spectrum auctions and MIIT licensing requirements.
- SDN:Software-defined networking compresses legacy refresh cycles by centralizing control plane intelligence. AT&T and BT Group are restructuring R&D allocation toward programmable infrastructure.
- NFV:Virtualized network functions run on commodity compute, reducing proprietary hardware dependency.
- Wi-Fi 6:Dense indoor connectivity complements macro cellular coverage for enterprise campuses.
Established deployment centers on 5G. Steepest expansion trajectory belongs to SDN.
End User:
Enterprise contracts command premium pricing, while residential volumes anchor equipment amortization models.
- Enterprises:CIOs source direct cloud interconnects and managed SD-WAN overlays rather than building private networks. Financial services and manufacturing verticals in the United States now combine multiple access technologies under unified orchestration.
- Data Centers:Hyperscale facilities demand high-throughput, low-latency interconnects for distributed computing workloads.
- Residential Users:Broadband access aggregation scales through PON and DOCSIS infrastructure upgrades.
- Government Agencies:Secure communications mandates drive certified encryption and sovereign cloud connectivity requirements.
Legacy concentration persists with Residential Users. Emerging demand clusters around Data Centers.
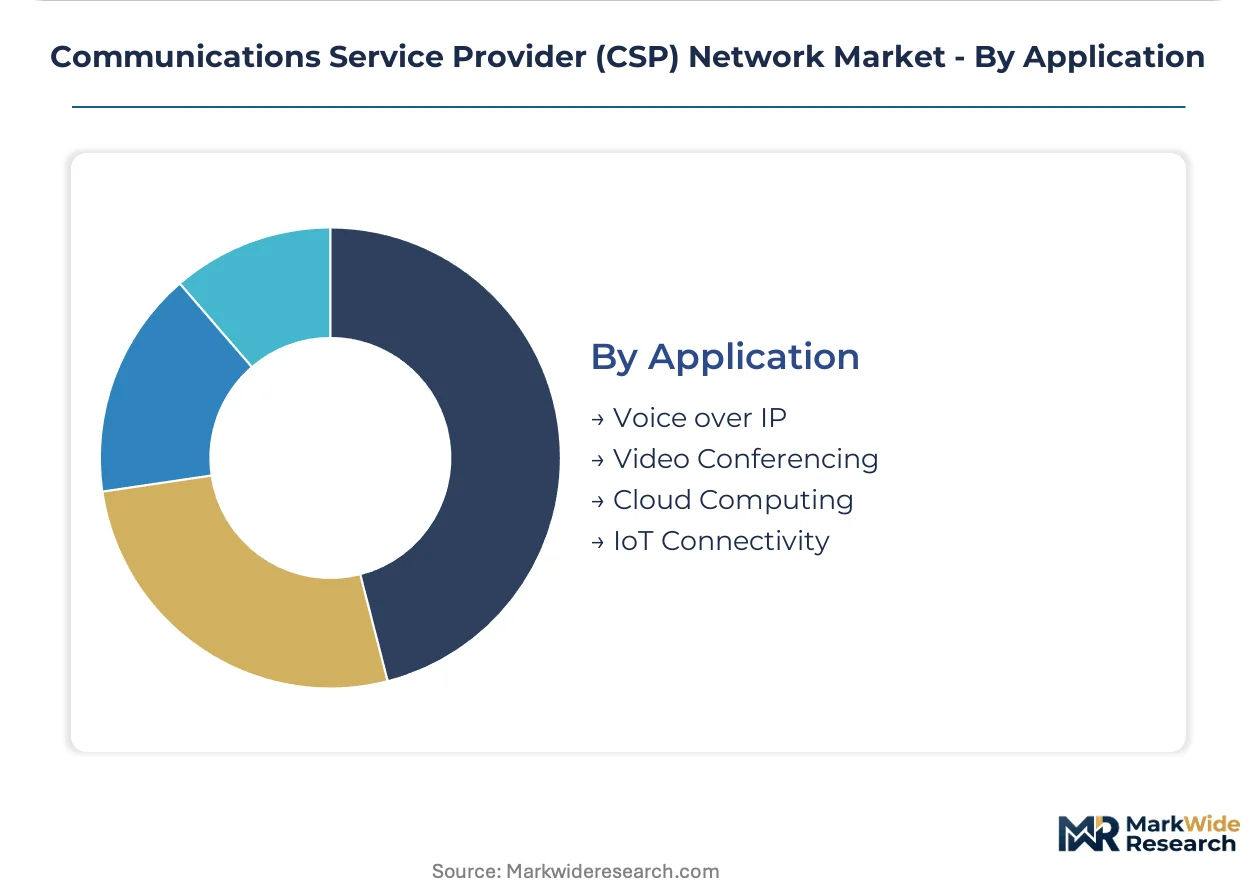
Application:
Cloud computing workloads generate the highest throughput requirements, while IoT connectivity expands endpoint density fastest.
- Cloud Computing:Distributed storage and compute workloads traverse CSP backbones between hyperscale regions and enterprise premises. SK Telecom and Verizon are co-locating GPU clusters with radio access infrastructure for edge convergence.
- IoT Connectivity:Massive machine-type communications require optimized signaling overhead for sensor networks.
- Voice over IP:Session border controllers manage real-time media streams with quality-of-service guarantees.
- Video Conferencing:Synchronous video demands symmetric bandwidth and jitter-controlled transport.
Traditional dominance holds with Voice over IP. Fastest share gains are occurring in Cloud Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Taiwan and South Korea, while consumption concentrates in Germany, the United States, and China where 5G standalone cores and fiber overbuilds absorb the highest capital volumes.
United States
Millimeter-wave spectrum depth and enterprise cloud interconnect contracts drive carrier infrastructure investment. FCC spectrum auctions synchronize vendor certification windows with deployment timelines. Dense metropolitan zones in New York, Los Angeles, and Chicago anchor the fastest 5G core buildouts.
Germany
EU Green Deal mandates compress equipment replacement cycles toward energy-efficient platforms. The Gigabit Strategy 2025 unlocks public funding for rural passive infrastructure. Deutsche Telekom and Telefónica Deutschland concentrate last-mile fiber deployment in Bavaria and North Rhine-Westphalia.
China
Massive domestic 5G standalone deployments consume high-density 400G switching platforms fastest. MIIT licensing requirements shape vendor access and equipment certification timelines. The Yangtze River Delta and Pearl River Delta regions concentrate both manufacturing capacity and consumption.
Saudi Arabia
NEOM and giga-project developments generate demand for greenfield carrier infrastructure at scale. The national telecom regulator imposes localization requirements on equipment procurement. Riyadh and the Eastern Province anchor concentration for smart city and industrial zone connectivity.
India
Rural broadband mandates and enterprise digitalization expand addressable infrastructure spend. TRAI spectrum policy and right-of-way regulations shape deployment economics. Maharashtra and Karnataka host the densest fiber and data center interconnect activity.
Communications Service Provider (CSP) Network Market Competitive Environment
The competitive structure tilts toward integrated national champions with captive spectrum and fiber assets. Tier-1 operators command pricing power through direct enterprise relationships and cloud interconnect franchises. Three archetypes dominate: vertically integrated telecom groups, wholesale infrastructure specialists, and mobile-first challengers with spectrum depth. Consolidation through fiber asset acquisitions and strategic partnerships for edge compute co-location represent the primary competitive vectors.
Among integrated telecom groups, Deutsche Telekom and Verizon exemplify carriers leveraging continental fiber footprints and millimeter-wave spectrum positions to capture enterprise cloud interconnect contracts. China Mobile occupies a distinct scale-driven tier through massive domestic 5G standalone deployment volumes. T-Mobile US represents the mobile-first challenger archetype, consolidating subscriber scale to negotiate equipment procurement terms and accelerate network densification timelines.
| Leading Market Players |
|---|
| T-Mobile US |
| Saudi Telecom Company |
| Deutsche Telekom |
| China Mobile |
| Lumen Technologies |
| Verizon |
| Reliance Jio |
| Vodafone |
| AT&T |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed network equipment producers in China and South Korea anchor supply concentration, while private-equity-rolled-up software specialists discipline pricing through recurring revenue models. This ownership-financing duality shapes how carrier procurement teams negotiate multi-year router and optical platform contracts.
Pricing Analysis
Margin tightening in carrier-grade hardware reflects 7nm and 5nm silicon foundry premiums at TSMC and Samsung. Three-tier pricing structure across premium chassis, standard modular systems, and economy fixed-configuration units separates vendors. Cost-down pressure on mid-range platforms accelerates because enterprise CIOs now bundle cloud interconnect with managed SD-WAN under unified orchestration. Government agencies exhibit lowest price sensitivity due to sovereign encryption mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for multi-vendor network equipment. Manufacturing concentrates in Taiwan, South Korea, and China. Advanced networking silicon draws from merchant foundry output, specialized optical components, and rare-earth magnet substrates. Single-source vulnerability at TSMC for 5nm merchant silicon creates procurement risk. Distribution runs through carrier-direct fulfillment with systems integrator overlay for complex multi-site deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act and GDPR compliance layers function as a cost-of-compliance moat, elevating capital requirements for network analytics platforms and advantaging incumbent operators with embedded legal-engineering teams.
For Market Incumbents: To counter open RAN interoperability gaps that inflate multi-vendor integration testing budgets, Deutsche Telekom and Verizon should deepen backward integration into captive test labs for radio unit validation. Certification investment in EU AI Act algorithmic transparency documentation protects enterprise cloud interconnect pricing power.
For New Entrants and Emerging Players: Mid-market enterprises previously priced out of carrier-grade infrastructure represent the most penetrable buyer archetype. Subscription-based network-as-a-service models bypass heavy capex requirements. Target German rural broadband subsidies under Gigabit Strategy 2025 for fiber overbuild partnerships with regional utilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Kubernetes-native NFV engineering boutiques in Germany and the United States with proven MIIT or FCC certification pathways. Long-term viability hinges on 5G standalone core deployment momentum across China, Germany, and the United States. Watch for MIIT licensing requirement accelerations as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | ETSI NFV alignment reduces multi-vendor integration testing from 35% to 15% of deployment budgets. |
| Edge Compute Co-location Partnership | Verizon and SK Telecom GPU cluster deployments create new monetization vectors for 5G MEC. |
| Energy-Efficient Chassis Replacement | Deutsche Telekom front-loads capital toward EU Green Deal compliant router platforms. |
| Cloud Interconnect Franchise Buildout | AT&T and BT Group consumption-based WAN offerings penetrate mid-market enterprise segments. |
| Intent-Based Networking Deployment | Tier-1 CSPs in the United States reduce mean-time-to-repair by 60-70% in pilot routing domains. |
Study Parameters
Document review covered FCC spectrum auction filings, ETSI NFV standards documentation, MIIT 5G licensing requirements, and hyperscaler capex disclosures, complemented by interviews with carrier network planning executives, vendor product managers, enterprise CIOs sourcing cloud interconnects, and systems integrators deploying multi-vendor infrastructure. Secondary validation drew from SEC 10-K equipment revenue breakdowns, customs trade data for networking silicon, and O-RAN Alliance specification releases. Bottom-up equipment shipment models and top-down carrier capex aggregation were cross-referenced for triangulation.
Historical deployment trajectories were cross-referenced against panel input from carrier procurement leaders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and application workload. CAGRs were derived from equipment refresh cycle compression rates and enterprise cloud interconnect contract velocity. Industry-specific forecast inputs incorporated EU Green Deal replacement timelines and open RAN interoperability maturity curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation and sovereign spectrum policy shifts. Forecasts reflect assumptions about MIIT licensing synchronization, ETSI NFV standard finalization, and enterprise SD-WAN adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Denmark Data Center Networking Market