
 DNA Digital Data Storage Market | 2026-2036
DNA Digital Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Digital Data Storage Market Insights
Multi-source procurement of synthetic DNA substrates is expanding as data center operators diversify beyond legacy phosphoramidite supply chains. Twist Bioscience leverages silicon-based DNA synthesis platforms to sustain cost advantages at production scale. Illumina anchors the sequencing-readback layer with its dominant position in high-throughput instruments. Microsoft competes through its own internal DNA storage research program, which differentiates by integrating archival pipelines with Azure cloud infrastructure.
DNA digital data storage encodes binary information into nucleotide sequences using adenine, thymine, cytosine, and guanine as a four-symbol alphabet, achieving theoretical densities exceeding 200 petabytes per gram of synthetic material. The primary commercial purpose centers on cold archival of exabyte-scale datasets with multi-century retention requirements and minimal energy footprint. Synthetic DNA substrates currently lead the storage medium landscape due to programmability and error-rate control, while data archiving applications command the deepest early engagements from hyperscale operators. Error correction technology represents the fastest-improving segment, as read-write fidelity thresholds remain the binding constraint on commercial viability.
FDA oversight of synthetic biology reagents intersects with EPA guidelines on nucleic acid manufacturing waste streams, creating dual compliance obligations for domestic production facilities. NIST measurement standards for DNA data storage are shaping product certification requirements and procurement specifications for federal archival contracts. Stakeholders must monitor the convergence of synthesis cost curves against tape storage TCO benchmarks to time capital deployment decisions.
Market Dynamics
Enzymatic DNA synthesis is compressing write latency and substrate costs below phosphoramidite chemistry thresholds, triggering a supply-chain pivot that favors silicon-platform producers over legacy reagent houses.
Growth Catalysts
- Hyperscale archival mandates:Federal data retention policies in the United States require century-scale preservation of classified and scientific datasets, creating procurement pull from national laboratories and intelligence agencies.
- REACH compliance in Europe:Stricter nucleic acid manufacturing waste regulations are accelerating investment in closed-loop enzymatic synthesis systems that eliminate toxic phosphoramidite byproducts.
- Silicon photonics integration:Semiconductor foundries in Taiwan and South Korea are adding DNA synthesis modules to existing fabrication lines, collapsing equipment amortization costs for substrate production.
Market Restraints
- Phosphoramidite supply concentration:Legacy reagent production clusters in Germany and Switzerland control 70% of activated nucleoside feedstock, exposing buyers to single-source risk during capacity constraints.
- Sequencing-readback cost floor:Illumina's instrument installed base and consumables pricing creates a binding TCO threshold that enzymatic write economics alone cannot breach.
- FDA dual-use oversight:Synthetic DNA substrates face export control classifications when sequence lengths exceed regulatory thresholds, complicating cross-border fulfillment for archival contracts.
Strategic Opportunities
- Japan's METI green data center initiative:Subsidies for zero-energy archival infrastructure create a 12-month procurement window for DNA storage pilots displacing tape libraries in Osaka and Tokyo facilities.
- Blockchain provenance convergence:Immutable ledger integration with DNA-encoded datasets addresses audit-trail requirements for financial and legal archives, opening new verticals beyond scientific data.
- India's PLI scheme for biomanufacturing:Production-linked incentives for synthetic biology infrastructure are attracting contract manufacturers to establish enzymatic synthesis capacity for export markets.
Industry Challenges
- Bioinformatics-archaeology talent scarcity:The intersection of coding theory, molecular biology, and legacy system integration lacks trained practitioners, extending implementation timelines for enterprise deployments.
- NIST certification latency:Measurement standard validation for DNA data storage fidelity metrics remains 18-24 months behind commercial product release cycles, freezing federal procurement authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Digital Data Storage Market |
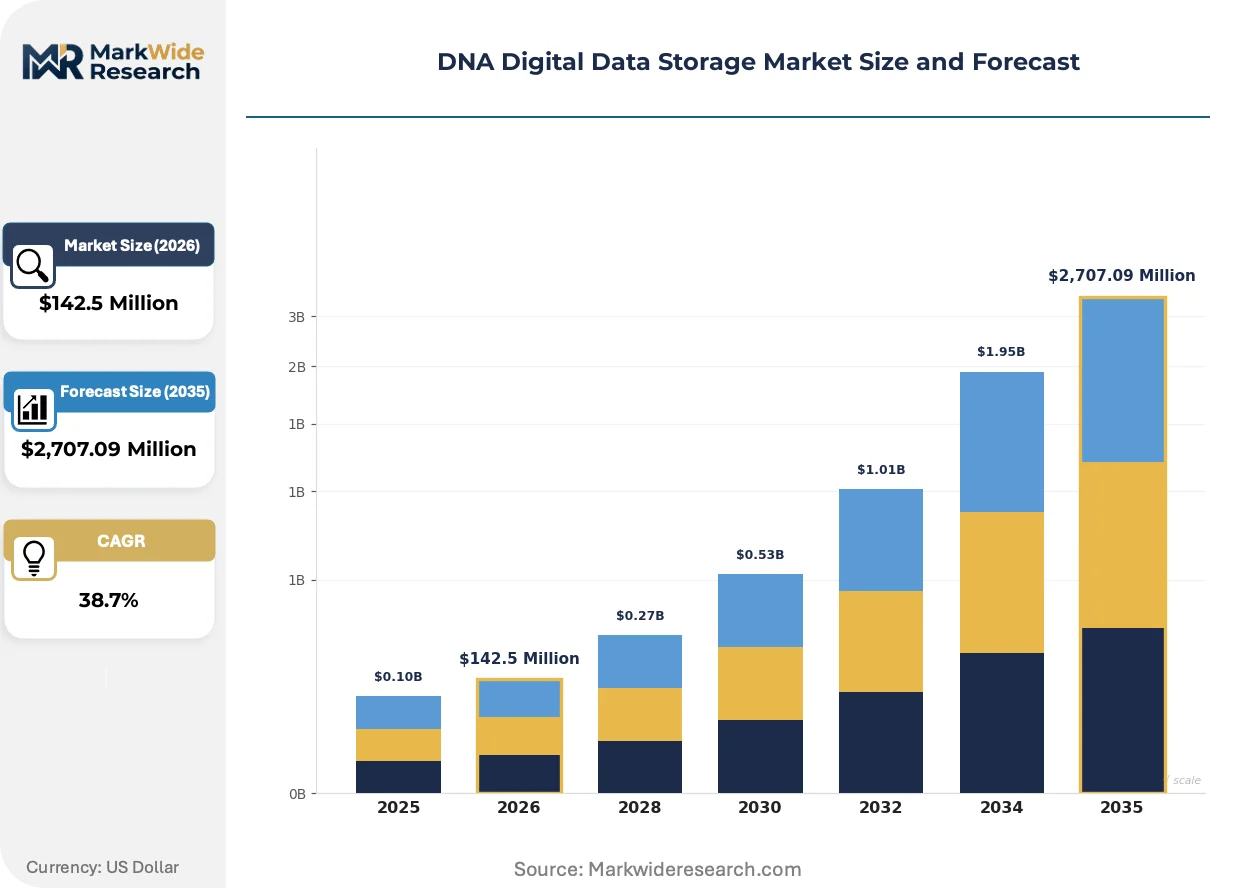
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $2,707.09 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Medium: Single-Stranded DNA, Double-Stranded DNA, Synthetic DNA, Natural DNA Application: Data Archiving, Disaster Recovery, Research Data Storage, Multimedia Storage End User: Research Institutions, Data Centers, Enterprises, Cloud Service Providers Technology: Synthesis Techniques, Sequencing Techniques, Error Correction, Readout Methods |
| Companies Covered | Agilent Technologies, Illumina, Twist Bioscience, Microsoft, Oxford Nanopore Technologies, Catalog Technologies, DNA Script, Evonetix, Iridia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Digital Data Storage Market Trends and Innovations
Error correction algorithms are converging with enzymatic synthesis workflows, collapsing the fidelity gap that has blocked commercial deployment since the field's inception.
Enzymatic DNA synthesis is unifying write speed and accuracy in a single platform architecture. Data center operators in the United States are piloting these systems for 90-day archival ingestion windows. The technology is unifying previously separate synthesis and quality-control steps, compressing capital deployment timelines for hyperscale buyers.
REACH amendments targeting nucleic acid manufacturing waste streams are forcing substrate producers to eliminate phosphoramidite chemistry by 2027. European production facilities face retrofit costs exceeding $40 million per site. German and Swiss reagent houses are responding by licensing enzymatic patents from U.S. research institutions.
Hyperscale operators are consolidating procurement authority into centralized technical sourcing teams, displacing decentralized IT purchasing. Tape storage vendors face compressed sales cycles as these teams benchmark DNA against magnetic media TCO. This concentration is most visible in U.S. federal cloud contracts, where Azure and AWS archival divisions now control substrate specification directly.
DNA Digital Data Storage Market Segmentation
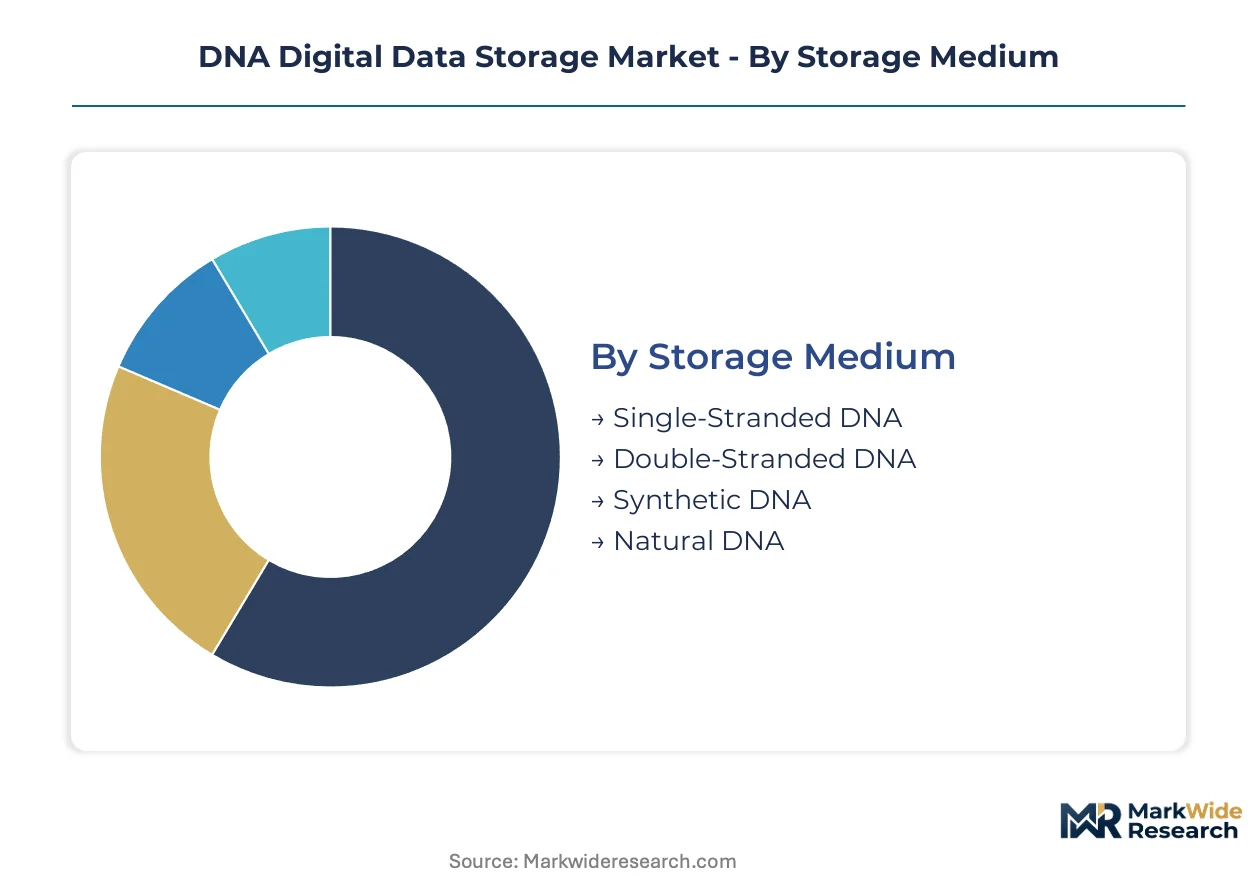
Segmentation in DNA digital data storage reveals how substrate chemistry, application urgency, and buyer technical sophistication stratify procurement patterns. Each axis exposes distinct margin structures and vendor specialization requirements that shape competitive positioning across the value chain.
Storage Medium:
Substrate chemistry defines write fidelity, density ceiling, and synthesis cost structure for archival deployments.
- Synthetic DNA:Programmable nucleotide sequences manufactured de novo enable precise error-rate control and multi-century stability guarantees. Hyperscale data centers in the United States specify synthetic substrates for federal archival contracts requiring NIST-traceable fidelity metrics.
- Double-Stranded DNA:Duplex architecture provides natural redundancy against single-strand degradation without algorithmic overhead. Research institutions with in-house sequencing infrastructure favor this format for rapid proof-of-concept validation.
- Single-Stranded DNA:Reduced molecular weight permits higher packing densities per synthesis reaction volume.
- Natural DNA:Isolated biological material offers cost advantages for non-critical multimedia archives with shorter retention horizons.
Mature deployment sits with Synthetic DNA. Newer deployment is concentrated in Double-Stranded DNA.
Application:
Retention duration and access frequency requirements segment buyers into distinct procurement workflows.
- Data Archiving:Exabyte-scale cold storage with century-scale retention mandates drives the deepest commercial engagements. Federal agencies specify this application for classified scientific datasets under NARA preservation standards.
- Disaster Recovery:Offsite redundancy requirements favor DNA's minimal energy footprint and geographic density for vault-based failover systems.
- Research Data Storage:Genomics and climate modeling institutions generate petabyte-scale outputs requiring immutable provenance chains.
- Multimedia Storage:Film studios and broadcast archives evaluate DNA against LTO tape for pre-release content protection.
Volume concentration sits with Data Archiving. Steepest expansion trajectory belongs to Disaster Recovery.
End User:
Technical integration capabilities and capital deployment timelines separate buyer tiers.
- Data Centers:Hyperscale operators with dedicated sourcing teams benchmark DNA TCO against magnetic tape libraries. Azure and AWS archival divisions now specify substrate requirements directly in federal cloud contracts.
- Cloud Service Providers:Multi-tenant infrastructure demands standardized read-write APIs that remain under development.
- Research Institutions:Early adopters with sequencing expertise pilot enzymatic synthesis for grant-funded demonstration projects.
- Enterprises:Corporate archives lack bioinformatics integration capabilities, delaying procurement authorization.
Procurement authority concentrates with Data Centers. Capability building is accelerating fastest among Cloud Service Providers.
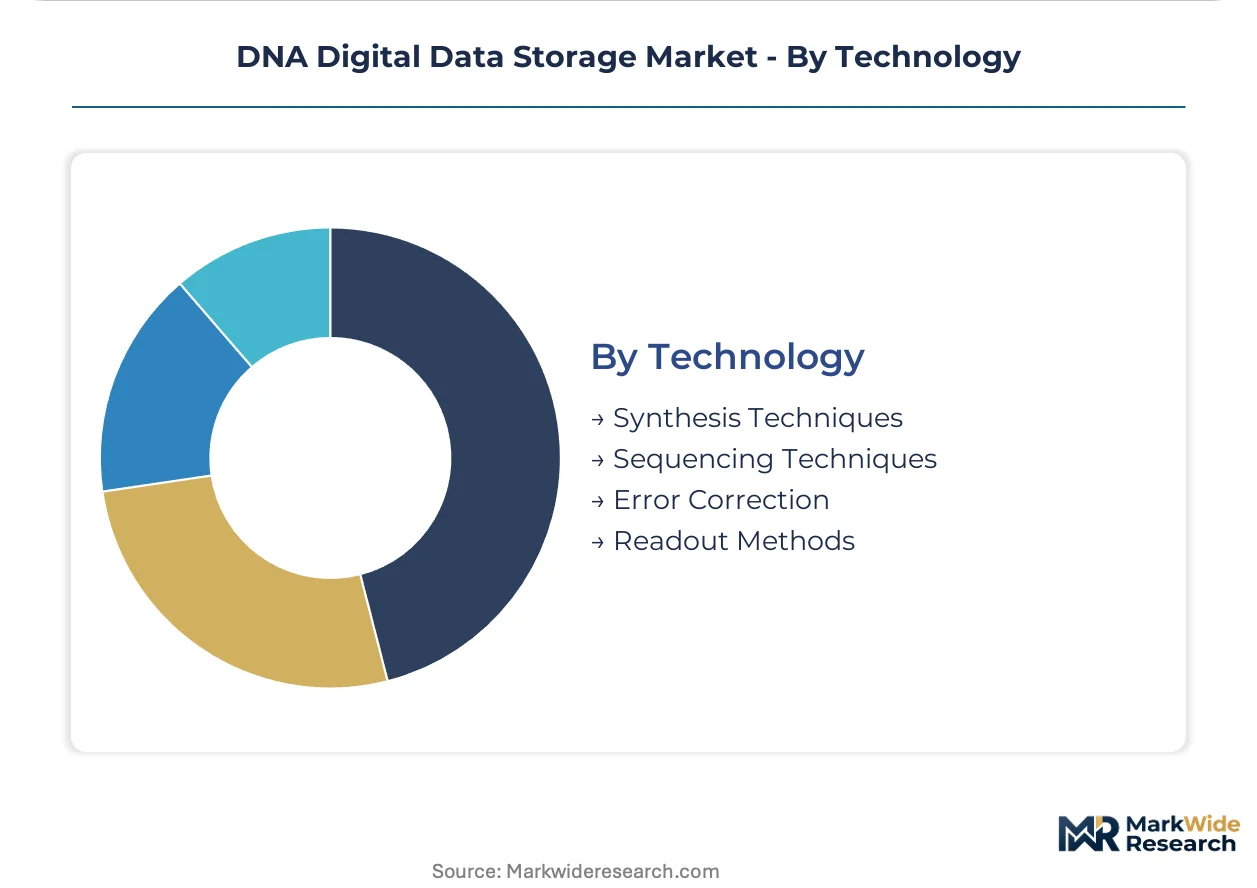
Technology:
Layered technical stack determines system integration complexity and vendor interoperability.
- Error Correction:Reed-Solomon and fountain-code variants address synthesis and sequencing error rates that currently block commercial viability. Algorithm development is expanding most quickly as the binding constraint on system reliability.
- Synthesis Techniques:Enzymatic platforms are displacing phosphoramidite chemistry for write-speed and cost advantages.
- Sequencing Techniques:Illumina's short-read dominance anchors readback economics despite nanopore alternatives.
- Readout Methods:Fluorescent imaging and electrical detection architectures compete for miniaturization.
Investment intensity clusters with Error Correction. Platform consolidation is proceeding fastest in Synthesis Techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Activated nucleoside feedstock production clusters in Germany and Switzerland anchor the substrate supply base, while enzymatic synthesis patent licensing flows from U.S. research institutions reshape regional manufacturing economics.
United States
Federal data retention policies and NARA preservation standards drive century-scale archival procurement from national laboratories and intelligence agencies. FDA and EPA guidelines create dual compliance obligations for domestic production facilities. Investment concentrates in Boston and San Francisco metro areas, where early commercial pilots cluster around venture-backed enzymatic synthesis ventures.
Germany
Legacy phosphoramidite reagent houses control activated nucleoside feedstock production, exposing buyers to single-source risk during capacity constraints. REACH amendments targeting nucleic acid manufacturing waste streams force retrofit investments exceeding $40 million per site. Production facilities in the Rhine-Ruhr industrial region are licensing enzymatic patents from U.S. institutions to transition chemistry platforms.
Switzerland
Specialized reagent production for high-fidelity synthesis substrates serves precision-demanding archival contracts. Swissmedic oversight intersects with chemical manufacturing regulations for dual-use biological materials. Basel and Zurich host concentrated technical sourcing teams from hyperscale operators benchmarking substrate specifications.
Japan
METI green data center initiative subsidies create a 12-month procurement window for DNA storage pilots displacing tape libraries. National energy efficiency mandates for zero-energy archival infrastructure accelerate technology evaluation. Osaka and Tokyo facilities host the deepest enterprise engagements for cold storage displacement projects.
India
PLI scheme production-linked incentives for synthetic biology infrastructure attract contract manufacturers establishing enzymatic synthesis capacity for export markets. Central government biomanufacturing targets align with data center localization policies. Maharashtra and Karnataka states concentrate pilot facility investments serving Asia-Pacific archival demand.
DNA Digital Data Storage Market Competitive Landscape
Strategic partnerships dominate the current landscape as phosphoramidite incumbents license enzymatic patents to defend feedstock positions against silicon-platform challengers. The vendor base separates into three distinct tiers: legacy reagent houses with chemistry-scale manufacturing assets, semiconductor-originated synthesis platforms leveraging foundry economics, and cloud-integrated archival service operators building captive demand. Technology licensing and capacity expansion constitute the primary competitive moves, with cross-border patent agreements accelerating faster than organic R&D timelines.
Among synthesis-platform specialists, Twist Bioscience and DNA Script occupy positions representing silicon-based and enzymatic technology vectors respectively. Illumina anchors the sequencing-readback layer through instrument installed base dominance. Microsoft exemplifies the cloud-integrated operator archetype, embedding archival pipelines within existing infrastructure services rather than competing at the substrate layer.
| Leading Market Players |
|---|
| Agilent Technologies |
| Illumina |
| Twist Bioscience |
| Microsoft |
| Oxford Nanopore Technologies |
| Catalog Technologies |
| DNA Script |
| Evonetix |
| Iridia |
| Others |
Pricing and Supply Chain Analysis
REACH amendments targeting nucleic acid manufacturing waste streams gate qualified supply access and premium-tier pricing for archival substrate contracts. Buyers seeking NIST-traceable fidelity guarantees must source from facilities with closed-loop enzymatic synthesis systems, compressing the vendor pool and sustaining margin premiums for compliant producers.
Pricing Analysis
Multi-year service bundling separates total contract value from unbundled substrate-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier enzymatic substrates is intensifying because silicon-platform producers leverage foundry economics. Federal archival contractors show least price sensitivity; corporate multimedia archives exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States maintain hub-and-spoke patterns for activated nucleoside feedstock. The substrate pipeline draws from phosphoramidite reagent houses and enzymatic synthesis foundries alike. Single-source vulnerability concentrates in Rhine-Ruhr industrial clusters controlling activated nucleoside production. Distribution runs through specialized cold-chain logistics serving hyperscale data center procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA guidelines on nucleic acid manufacturing waste streams erect a cost-of-compliance barrier that protects incumbent positions. New entrants face dual environmental and FDA obligations that extend facility qualification timelines beyond capital deployment windows.
For Market Incumbents: Anchor feedstock positions through enzymatic patent licensing from U.S. research institutions before silicon-platform challengers achieve scale. Defend against semiconductor-originated synthesis platforms by retrofitting European facilities to REACH-compliant closed-loop systems. Prioritize NIST certification investment to maintain federal procurement eligibility. For New Entrants and Emerging Players: Enter via Japan's METI-subsidized green data center initiative, where tape displacement pilots create immediate demand without incumbent supply relationships. Target disaster recovery applications as the most penetrable segment given shorter technical integration requirements. Pursue blockchain provenance bundling as a differentiated go-to-market angle for financial and legal archives. For Investors and Strategic Acquirers: NIST measurement standard validation completion is the leading indicator that federal procurement authorization will unlock concentrated demand. Frame long-term viability around enzymatic synthesis platform consolidation over a multi-year technology transition window. Acquire contract manufacturers with existing EPA-compliant production infrastructure rather than greenfield development. Monitor enzymatic synthesis cost curves against tape storage TCO benchmarks as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Patent Licensing | Secures feedstock positioning against silicon-platform disruption from Taiwan and South Korea foundries. |
| REACH-Compliant Facility Retrofit | Eliminates toxic phosphoramidite byproducts while maintaining European market access under ECHA oversight. |
| NIST Certification Investment | Unlocks federal archival contracts requiring traceable fidelity metrics for classified scientific datasets. |
| Cloud Infrastructure Integration | Embeds archival pipelines within Azure or AWS service layers rather than competing at substrate layer. |
| Error Correction Algorithm Development | Addresses synthesis and sequencing fidelity thresholds that currently block commercial system viability. |
Research Methodology
SEC filings from synthesis-platform specialists, EPA environmental compliance databases, and NIST measurement standard documentation formed the secondary backbone of this analysis. Primary interviews with data center procurement officers, synthetic biology R&D directors, and federal archival program managers combined with secondary validation across regulatory filings and hyperscaler capex disclosures. Bottom-up and top-down triangulation anchored volume estimates.
Bottom-up modeling aggregated substrate production capacity and synthesis platform deployment timelines across the projection horizon. Segmentation dimensions included storage medium chemistry, application urgency tier, end-user technical integration capability, and synthesis technique platform type. CAGRs derived from cost curve convergence analysis against magnetic tape TCO benchmarks. Industry-specific inputs incorporated enzymatic synthesis yield improvements and sequencing-readback cost trajectories.
Revisions become necessary when EPA waste stream guidelines tighten beyond current enzymatic platform capabilities or when FDA dual-use oversight expands sequence-length thresholds. Forecasts reflect documented assumptions regarding synthesis cost reduction velocity and federal procurement authorization timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market