
 SDN Orchestration Market | 2026-2036
SDN Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
SDN Orchestration Market Analysis
Subscription-based software-defined orchestration is consolidating as the dominant commercial model, displacing perpetual licensing in carrier procurement cycles. Cisco Systems leverages its installed base of routing hardware to bundle orchestration subscriptions at contract renewal points. Juniper Networks competes through cloud-native Contrail architecture positioned for multi-vendor environments. Nokia Corporation anchors its market presence via deep integration with telco network operations centers across European markets.
SDN orchestration denotes the automated provisioning, configuration, and lifecycle management of software-defined network resources through centralized controllers and northbound APIs, typically operating across OpenFlow, NETCONF, or REST-based protocols to enable policy-driven traffic engineering. The technology serves primarily to reduce operational expenditure in multi-tenant and multi-vendor network environments by replacing manual CLI-based administration with programmable workflows. Cloud-based deployment models now capture the fastest expansion as hyperscale data center operators and telecom providers pursue elastic capacity scaling without capital-intensive infrastructure builds. Managed services within the service type dimension concentrate margin pools where providers assume full operational responsibility for customer network orchestration stacks.
The Federal Communications Commission in the United States and the European Telecommunications Standards Institute both mandate interoperability benchmarks that directly shape vendor qualification requirements for carrier procurement. India's Telecom Regulatory Authority and the Department of Telecommunications enforce domestic security certification for orchestration platforms deployed in government and strategic networks, creating localized compliance barriers. Stakeholders must monitor evolving open-source foundation governance models and their influence on proprietary feature differentiation strategies.
Market Dynamics
Telecom operators are consolidating multi-vendor network stacks under unified orchestration layers to reduce CLI-dependent operations and enable closed-loop automation across 5G transport domains.
Growth Catalysts
- 5G Network Slicing Mandates:Mobile operators in South Korea and Germany deploy orchestration platforms to instantiate virtualized network slices for enterprise IoT and industrial automation use cases.
- Open RAN Interface Standardization:O-RAN Alliance specifications are creating procurement pull for orchestration systems capable of managing disaggregated radio access network components from multiple suppliers.
- Containerized Network Functions:Kubernetes-based CNF architectures are displacing virtual machine-based VNFs, requiring orchestration platforms with cloud-native lifecycle management capabilities.
Market Restraints
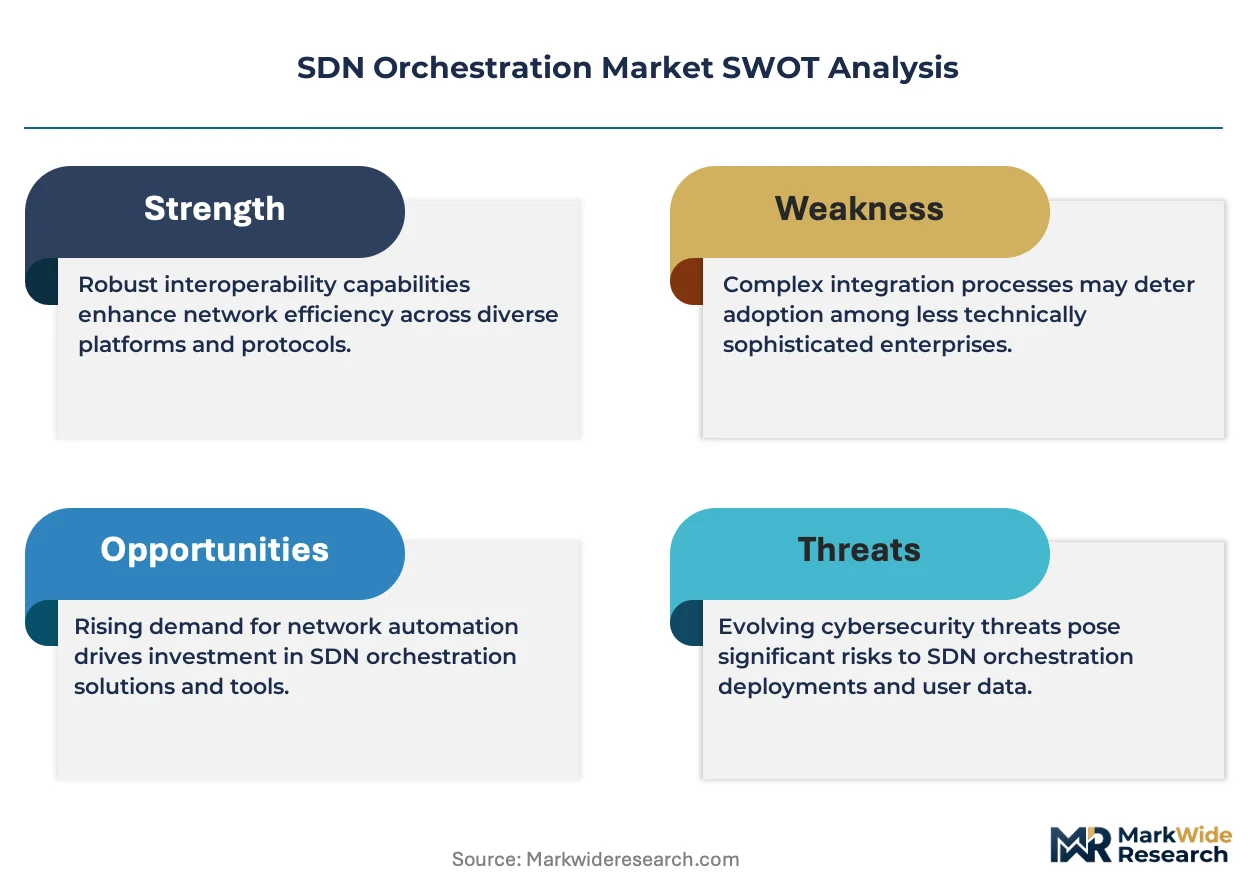
- Specialized Engineering Talent Scarcity:Shortage of engineers proficient in both telecommunications protocols and cloud-native development stacks limits deployment velocity at tier-2 operators.
- Legacy Infrastructure Lock-In:Existing MPLS and SONET/SDH transport investments at incumbent carriers create technical debt that slows software-defined migration timelines.
- Domestic Security Certification Requirements:India's TRAI and Department of Telecommunications impose localized compliance barriers that fragment vendor addressable markets.
Strategic Opportunities
- Edge Computing Orchestration:Multi-access edge computing deployments in manufacturing zones and smart city corridors require distributed orchestration with sub-10ms latency guarantees.
- Private 5G Network Management:Industrial campuses in Germany and South Korea are procuring dedicated orchestration stacks for captive network deployments outside public carrier infrastructure.
- AI-Driven Closed-Loop Automation:Integration of machine learning inference engines with orchestration controllers enables predictive traffic engineering and autonomous fault remediation.
Industry Challenges
- Multi-Vendor Integration Complexity:Southbound API inconsistencies between equipment suppliers force custom adapter development, extending deployment cycles.
- Operational Skill Transition:Carrier network operations centers require retraining from hardware-centric to software-centric troubleshooting methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SDN Orchestration Market |
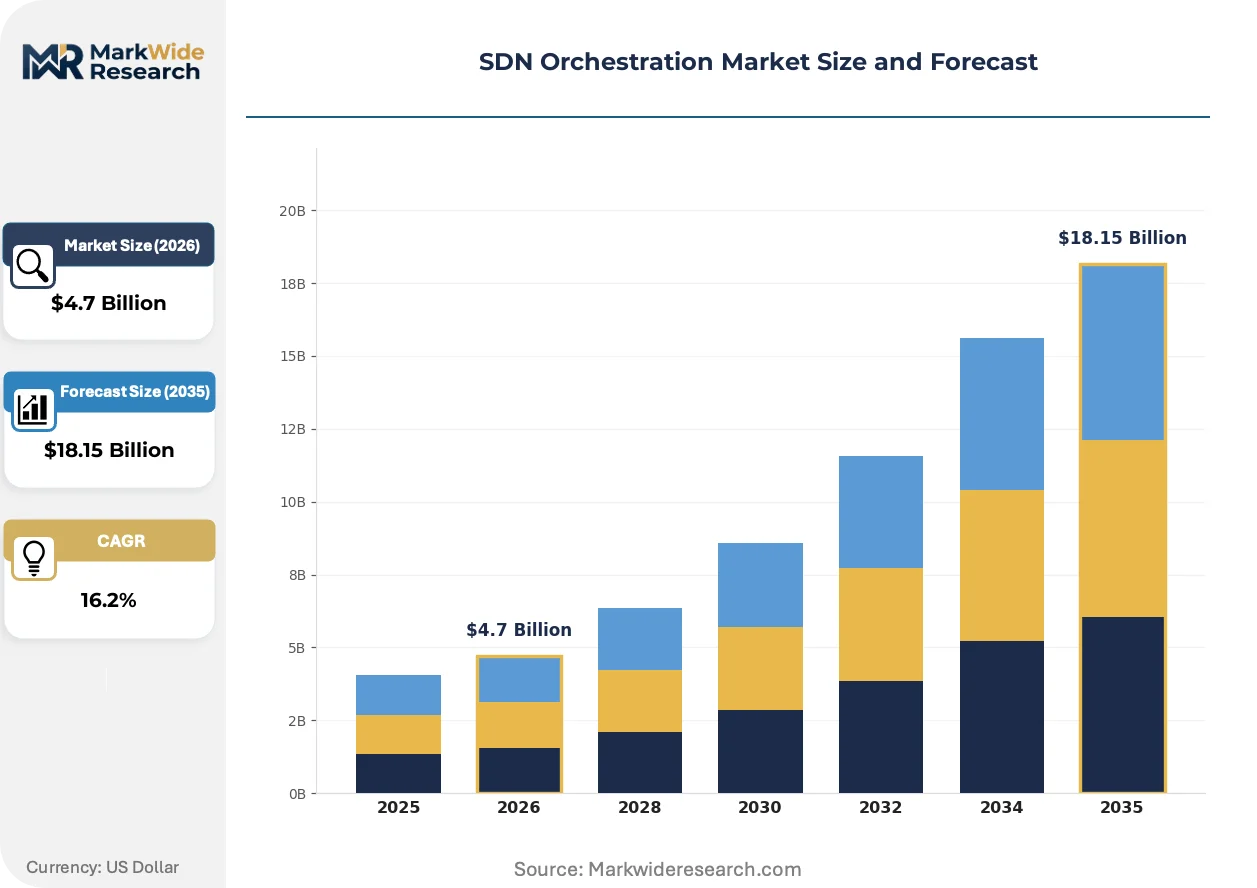
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $18.15 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed End User: Telecom Providers, Enterprises, Service Providers, Government Agencies Solution Type: Traffic Management, Network Monitoring, Automation, Security Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Cisco Systems, Juniper Networks, Nokia Corporation, Huawei Technologies, Hewlett Packard Enterprise, Ciena Corporation, VMware, NEC Corporation, Anuta Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SDN Orchestration Market Emerging Trajectories
Intent-based networking is compressing the abstraction layer between business policy statements and network configuration execution, reducing manual translation errors in carrier provisioning workflows.
Cloud-native orchestration platforms built on microservices architectures are unifying control plane functions previously distributed across element management systems, network management systems, and service orchestrators. Tier-1 operators in the United States and Germany are deploying these platforms at scale for 5G core management. This unification is compressing vendor consolidation timelines as carriers reduce supplier counts to simplify integration testing.
The European Telecommunications Standards Institute's zero-touch orchestration frameworks are mandating automated service lifecycle management without human intervention for standard provisioning requests. Equipment vendors must certify compliance with these frameworks to qualify for carrier procurement shortlists. European operators are responding by restructuring internal organizations to separate policy design from execution functions.
Enterprise buyers are compressing evaluation cycles for orchestration platforms, demanding proof-of-concept deployments in production network segments before full-scale commitments. This behavior is displacing traditional request-for-proposal processes with outcome-based trial frameworks. The pattern is most visible in South Korea's manufacturing vertical, where smart factory deployments require rapid validation of deterministic latency guarantees.
SDN Orchestration Market Segmentation
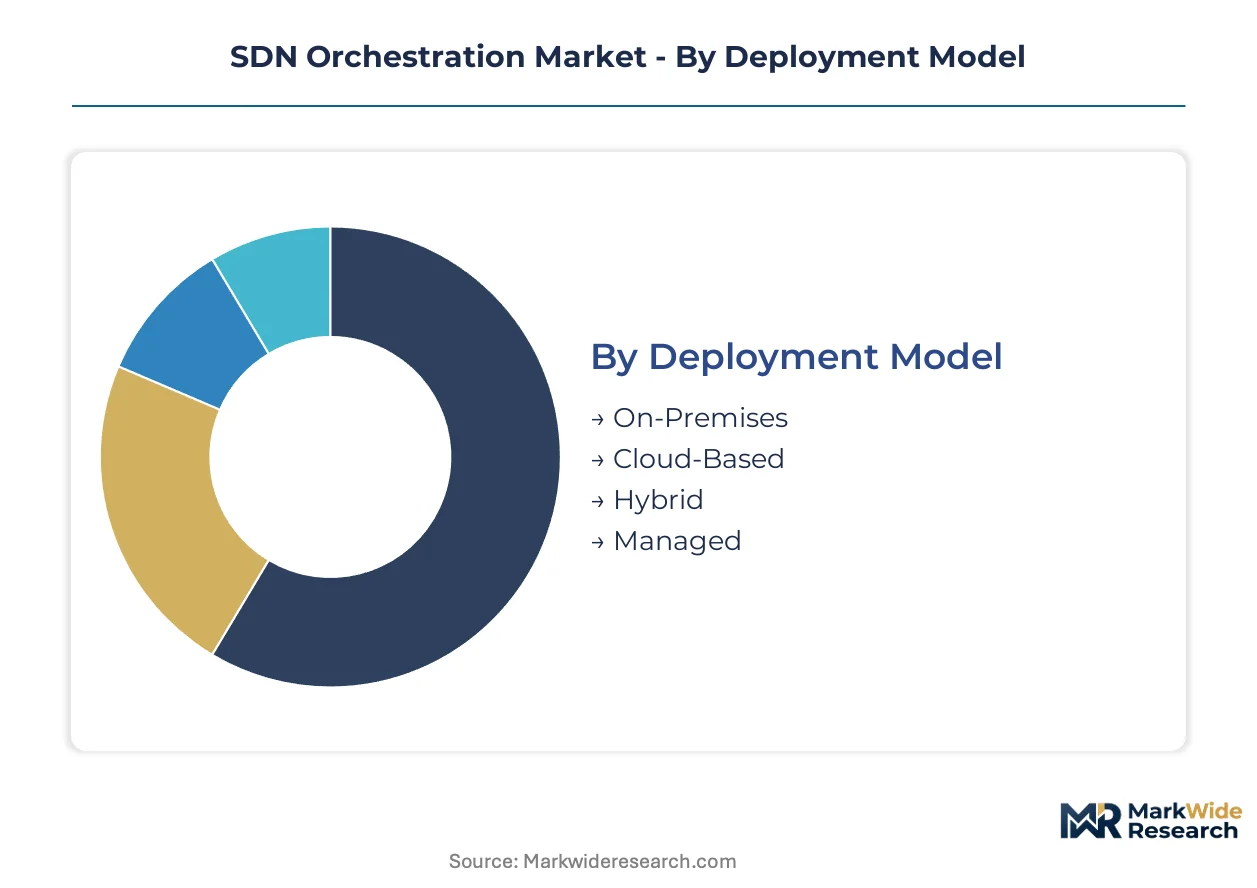
Segmentation in SDN orchestration reveals how procurement patterns split between capital-intensive on-premises deployments and elastic cloud subscriptions. Certification requirements from the FCC, ETSI, and India's TRAI apply unevenly across deployment models and end-user categories, shaping vendor qualification pathways.
Deployment Model:
Cloud-based deployments face streamlined certification through ETSI zero-touch frameworks, while on-premises installations trigger deeper security audits under India's TRAI mandates and US federal procurement standards.
- On-Premises:Hardware-anchored orchestration controllers deployed within carrier data centers and enterprise facilities. German telecom providers favor this model for 5G core management to satisfy domestic data sovereignty requirements under GDPR and BSI standards.
- Cloud-Based:SaaS-delivered orchestration platforms enabling elastic capacity scaling without infrastructure ownership. South Korean mobile operators deploy these for rapid network slice instantiation in smart factory corridors, bypassing capital approval cycles.
- Hybrid:Split-control architectures combining on-premises policy engines with cloud analytics layers.
- Managed:Full operational outsourcing where vendors assume lifecycle responsibility for customer orchestration stacks.
Leading the category by volume: On-Premises. Growing fastest: Cloud-Based.
End User:
Cost tiers diverge sharply between telecom providers running billion-dollar infrastructure and government agencies bound by public procurement ceilings.
- Telecom Providers:Tier-1 carriers in the United States, Germany, and South Korea dominate procurement volumes. These buyers mandate ETSI zero-touch compliance and O-RAN Alliance interoperability, consolidating supplier counts to reduce integration testing overhead.
- Enterprises:Manufacturing campuses and financial institutions procuring private orchestration stacks. German automotive firms and South Korean electronics conglomerates drive demand for deterministic latency guarantees in smart factory deployments.
- Service Providers:Neutral host operators and cloud communications platforms.
- Government Agencies:Defense and critical infrastructure networks subject to localized security certification.
Highest absolute spend: Telecom Providers. Steepest expansion trajectory: Enterprises.
Solution Type:
Application maturity separates traffic management tools with decade-long deployment histories from emerging AI-driven automation modules.
- Traffic Management:Policy-driven flow engineering across OpenFlow and NETCONF protocols. South Korean carriers deploy these solutions for 5G transport optimization, integrating with Samsung and NEC radio units through standardized southbound interfaces.
- Automation:Closed-loop provisioning and intent-based configuration translation. United States-based hyperscale operators adopt these platforms to compress provisioning intervals from weeks to minutes across multi-vendor environments.
- Network Monitoring:Real-time telemetry aggregation and fault correlation engines.
- Security:Microsegmentation and threat response orchestration for zero-trust architectures.
Widest installed base: Traffic Management. Climbing the fastest: Automation.
Service Type:
Margin concentration pools in managed services where providers assume operational risk, while consulting engagements face pricing pressure from standardized deployment playbooks.
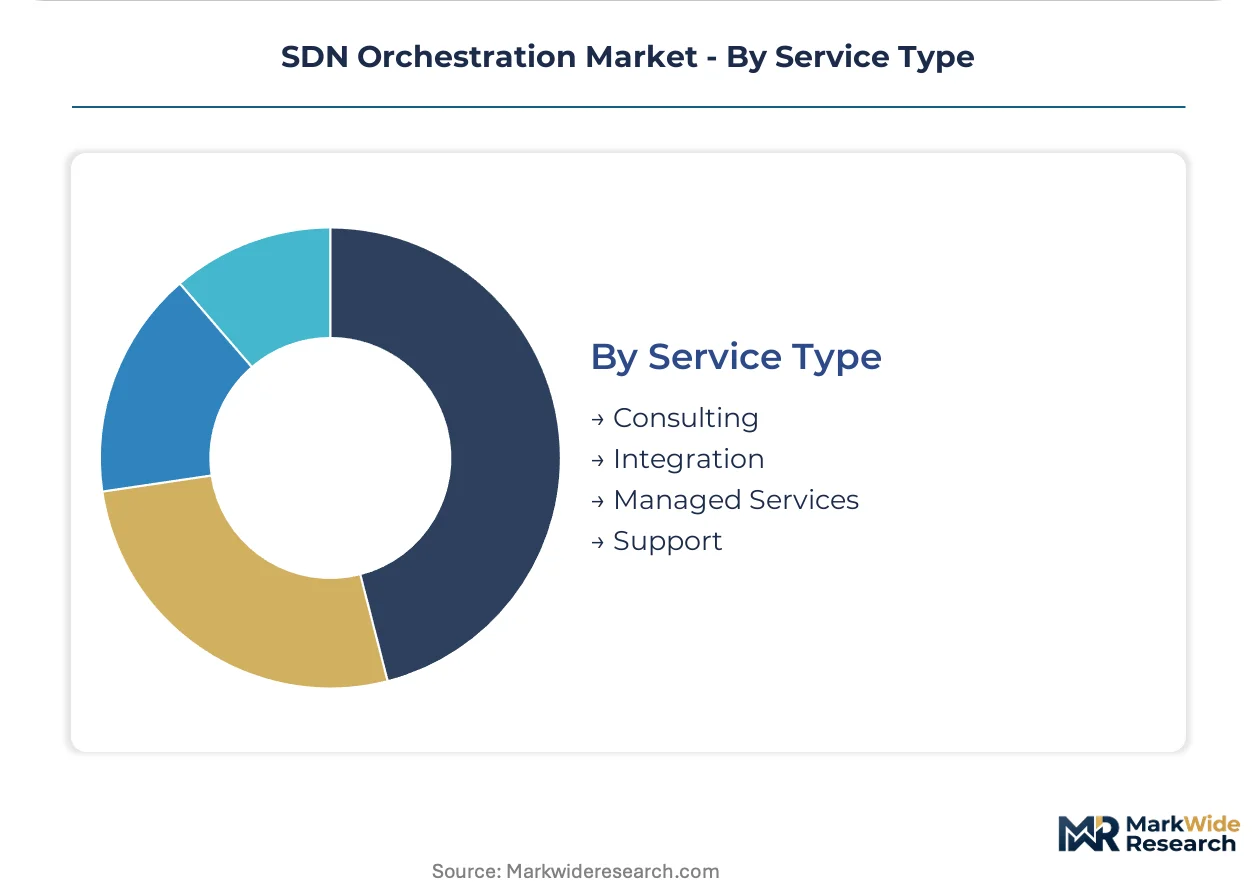
- Managed Services:Full-stack operational responsibility including 24/7 controller management and incident response. European operators in Germany and France outsource these functions to compress internal headcount and accelerate skill transitions from hardware to software-centric methodologies.
- Integration:Multi-vendor adapter development and legacy MPLS migration services. United States carriers require extensive customization to bridge Cisco, Juniper, and Nokia equipment through inconsistent southbound APIs.
- Consulting:Architecture design and procurement advisory engagements.
- Support:Break-fix maintenance and software update management.
Largest revenue pool: Managed Services. Gaining share fastest: Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States vendors dominate orchestration software development, while South Korea and Germany concentrate deployment demand for 5G network slicing. India's certification requirements fragment procurement patterns. Production of orchestration controllers clusters in Silicon Valley and Shenzhen, but consumption concentrates where telecom operators modernize transport networks.
United States
Hyperscale cloud operators and tier-1 carriers drive cloud-native orchestration procurement for multi-vendor data center fabrics. FCC interoperability benchmarks shape vendor qualification requirements for federal and carrier procurement cycles. Seattle and Northern Virginia data center corridors deploy these platforms for elastic capacity scaling across distributed infrastructure footprints.
Germany
Industrial automation and automotive manufacturing campuses demand private 5G orchestration with deterministic latency guarantees for smart factory deployments. ETSI zero-touch orchestration frameworks mandate automated service lifecycle management for carrier procurement shortlists. Bavaria's manufacturing belt and North Rhine-Westphalia's logistics corridors anchor enterprise adoption of edge computing orchestration stacks.
South Korea
Electronics conglomerates and mobile operators instantiate network slices for industrial IoT and connected vehicle use cases with sub-10ms latency requirements. National smart city infrastructure programs accelerate procurement of distributed orchestration controllers. Seoul Capital Area and Busan-Ulsan manufacturing zones validate orchestration platforms through outcome-based trial frameworks before full-scale commitments.
India
Domestic telecom operators modernize transport networks amid spectrum auctions and 5G rollout mandates, though procurement velocity faces engineering talent constraints. TRAI and Department of Telecommunications enforce localized security certification for government and strategic network deployments. Karnataka's technology corridor and Maharashtra's financial centers concentrate enterprise demand for cloud-based orchestration subscriptions.
Japan
Telecom incumbents integrate orchestration layers with existing network operations centers while transitioning from hardware-centric to software-centric methodologies. METI industrial digitization programs subsidize private 5G deployments for manufacturing verticals. Tokyo-Osaka industrial corridors and Kyushu's semiconductor fabrication zones deploy orchestration for multi-access edge computing in precision manufacturing environments.
SDN Orchestration Market Vendor Landscape
Top-tier vendors anchor carrier procurement shortlists through ETSI certification and O-RAN Alliance compliance, while mid-tier specialists compete on multi-vendor integration agility and cloud-native architecture differentiation. The market structure reflects consolidation pressure as carriers reduce supplier counts to simplify integration testing overhead. Three archetypes dominate: routing hardware incumbents bundling orchestration subscriptions, cloud-native challengers positioning for disaggregated environments, and telecom-integrated specialists with deep network operations center relationships. Competitive dynamics center on strategic partnerships for southbound API standardization and portfolio diversification into edge computing orchestration.
Within the routing hardware incumbent tier, Cisco Systems exemplifies subscription bundling strategies leveraging installed base renewal cycles, while Juniper Networks occupies a position emphasizing cloud-native multi-vendor positioning. Nokia Corporation anchors the telecom-integrated specialist archetype through European network operations center relationships. These three entities represent distinct competitive vectors: hardware-anchored bundling, cloud-native openness, and operational integration depth.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Nokia Corporation |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Ciena Corporation |
| VMware |
| NEC Corporation |
| Anuta Networks |
| Others |
Supply Flow & Price Mechanics
Tier-1 telecom carriers in the United States, Germany, and South Korea command substantial pricing leverage through consolidated procurement volumes, compressing vendor margins while favoring subscription-based SaaS models over perpetual licensing arrangements.
Pricing Analysis
Margin tightening in cloud-native orchestration tiers reflects carrier demands for elastic capacity scaling without infrastructure ownership premiums. Three-tier pricing structure across enterprise-grade, carrier-standard, and managed-economy levels differentiates by support responsiveness and API customization depth. Pricing pressure intensifies in on-premises deployments as legacy hardware incumbents bundle orchestration subscriptions at renewal points to defend installed bases. Tier-2 operators exhibit highest price sensitivity, while hyperscale cloud providers prioritize integration agility over unit cost.
Supply Chain Analysis
Direct-to-carrier channels handle tier-1 operator procurement, with systems integrators and managed service providers serving mid-market enterprise demand. Controller hardware production concentrates in the United States, Taiwan, and South Korea, while software development clusters in Silicon Valley and Bangalore engineering corridors. Supply chains draw from specialized semiconductor foundries for programmable data plane silicon and cloud infrastructure providers for SaaS delivery substrates. Single-source vulnerability in merchant silicon supply creates exposure to foundry capacity constraints. Distribution runs through certified systems integrators for complex multi-vendor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier procurement consolidation is accelerating vendor attrition as tier-1 operators reduce supplier counts to compress integration testing overhead and simplify ETSI certification pathways.
For Market Incumbents: Anticipate margin compression in hardware-anchored orchestration bundles as cloud-native challengers displace CLI-dependent administration tools with Kubernetes-based alternatives. Defend position through backward integration into programmable silicon and captive supply of zero-touch automation modules certified under ETSI frameworks. Prioritize certification investment in India's TRAI security mandates to preempt compliance barriers that fragment addressable markets. For New Entrants and Emerging Players: Tier-2 telecom operators in India and Southeast Asia represent the most penetrable buyer archetype, underserved by incumbent complexity and pricing structures. Target private 5G network deployments in German automotive campuses and South Korean electronics manufacturing zones where deterministic latency requirements outstrip incumbent solution agility. Pursue outcome-based trial frameworks that displace traditional RFP processes through rapid production-network validation. For Investors and Strategic Acquirers: The window for entry favors cloud-native orchestration specialists with proven multi-vendor southbound API adapters and Kubernetes-native controller architectures. Long-term viability hinges on positioning for edge computing orchestration as manufacturing verticals deploy distributed controllers with sub-10ms latency guarantees. Watch for inflection signals in O-RAN Alliance procurement pull as disaggregated radio access network specifications mature.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies control plane functions previously distributed across element management systems at tier-1 carriers. |
| Strategic Partnership | Accelerates southbound API standardization with Samsung and NEC radio units for South Korean 5G deployments. |
| Acquisition of Specialist Firm | Addresses engineering talent scarcity in cloud-native development stacks through targeted capability consolidation. |
| Geographic Expansion | Captures private 5G orchestration demand in Bavaria's manufacturing belt and Busan-Ulsan industrial zones. |
| Product Launch | Introduces AI-driven closed-loop automation modules for predictive traffic engineering at hyperscale operators. |
Methodological Framework
Multi-period observation of carrier procurement volumes, ETSI certification timelines, and O-RAN Alliance specification adoption anchored the trend analysis, supplemented by interviews with network operations center directors, cloud infrastructure procurement officers, systems integration specialists, and telecom regulatory affairs leads. Secondary validation drew from FCC interoperability filings, ETSI framework documentation, TRAI security certification records, and hyperscale operator capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment models and end-user categories.
Segment-weighting approaches applied differential growth coefficients to cloud-based versus on-premises deployment trajectories, with additional stratification by solution type maturity and service type margin concentration. CAGRs were derived from fitted growth curves across the projection horizon, incorporating 5G network slicing deployment schedules, Open RAN procurement pull timelines, and containerized network function migration patterns as industry-specific forecast inputs.
Revisions become necessary when carrier consolidation timelines accelerate, ETSI zero-touch mandates expand scope, or India's TRAI certification requirements fragment vendor qualification pathways beyond current modeling assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
GPU Database Market