
 Anastrozole Tablets Market | 2026-2036
Anastrozole Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Anastrozole Tablets Market Outlook
Continuous manufacturing technology is narrowing the cost gap between branded and generic anastrozole production, compressing batch-to-batch variability while accelerating scale-up timelines. Teva Pharmaceutical Industries Ltd leverages its vertically integrated API-to-tablet infrastructure to sustain margin resilience across pricing cycles. AstraZeneca Plc anchors the originator segment through brand loyalty in oncology protocols where physician familiarity drives prescribing habits. Sun Pharmaceutical Industries Ltd competes aggressively in emerging markets through localized manufacturing and distribution networks.
Anastrozole tablets contain the non-steroidal aromatase inhibitor C17H19N5, formulated as 1 mg oral tablets that suppress estrogen biosynthesis by inhibiting aromatase enzyme conversion of androgens to estrogens in peripheral tissues. The generic product type dominates volume throughput as patent expiration enabled multi-source competition, while extended-release formulations represent a narrower but higher-margin development frontier. Oncology clinics and hospitals anchor end-user demand, though outpatient facilities are capturing share as oral chemotherapy administration shifts away from infusion centers. Blister packs remain the standard packaging format due to unit-dose compliance requirements in institutional settings.
FDA oversight through the Center for Drug Evaluation and Research governs bioequivalence standards for generic anastrozole approvals, while EMA's Committee for Medicinal Products for Human Use maintains parallel quality benchmarks in Europe. The WHO's prequalification program shapes access in low-income markets where procurement agencies require international certification. Stakeholders must monitor how tightening environmental regulations on pharmaceutical manufacturing effluents reshape production location decisions and capital allocation across the supplier base.
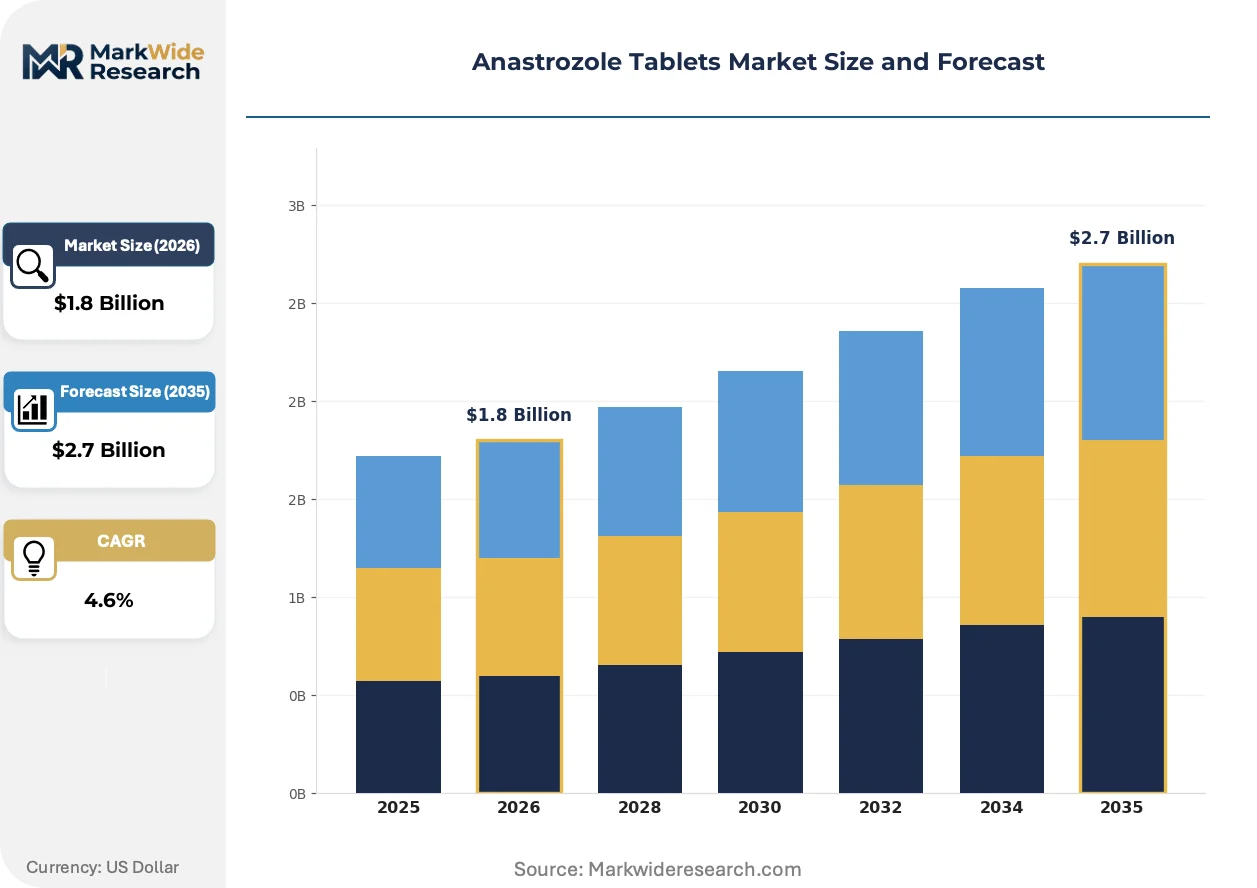
Market Dynamics
Continuous manufacturing technology is compressing production timelines for generic anastrozole while FDA's abbreviated new drug application pathway accelerates multi-source competition, fundamentally restructuring margin distribution between originators and contract manufacturers.
Growth Catalysts
- Postmenopausal breast cancer incidence:Sustained prescription volumes in the United States drive oncology clinic throughput as aromatase inhibitor protocols expand in adjuvant therapy settings.
- FDA abbreviated approval pathway:Streamlined bioequivalence standards enable faster generic entry, intensifying price competition and expanding patient access.
- Continuous manufacturing adoption:Pharmaceutical producers deploy advanced process control to reduce batch-to-batch variability and accelerate scale-up timelines.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing clusters in select Asian manufacturing hubs, exposing finished dose producers to geopolitical and logistics disruptions.
- Environmental compliance costs:Tightening effluent regulations from the EPA and EMA force capital-intensive wastewater treatment upgrades at production facilities.
- Substitution pressure from letrozole:Alternative aromatase inhibitors compete for hormone receptor-positive breast cancer protocol share, pressuring anastrozole volume retention.
Strategic Opportunities
- Extended-release formulation development:Modified-release anastrozole tablets command premium positioning in oncology protocols seeking dosing convenience improvements.
- Outpatient administration shift:Oral chemotherapy delivery moves from hospital infusion centers to retail pharmacy and specialty pharmacy channels.
- EMA centralized procedure leverage:European market access through the Committee for Medicinal Products for Human Use enables simultaneous multi-country commercialization.
Industry Challenges
- Continuous manufacturing talent scarcity:Process analytical technology and real-time release testing expertise remains concentrated among specialized engineering consultancies.
- Blister packaging compliance complexity:Unit-dose serialization requirements for institutional settings demand specialized packaging line investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anastrozole Tablets Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic, Brand, Combination, Extended Release End User: Oncology Clinics, Hospitals, Outpatient Facilities, Pharmacies Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Packaging Type: Blister Packs, Bottles, Vials, Sachets |
| Companies Covered | AstraZeneca Plc, Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Dr. Reddy’s Laboratories Ltd, Cipla Ltd, Zydus Pharmaceuticals, Hikma Pharmaceuticals, Natco Pharma, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anastrozole Tablets Market Strategic Shifts
Formulation science and regulatory science are converging to reshape how anastrozole reaches patients, with manufacturing technology and distribution channels undergoing simultaneous transformation.
Hot-melt extrusion technology is hybridizing solid dispersion production for anastrozole, enabling improved bioavailability in generic formulations. Contract development and manufacturing organizations in India and the United States are adopting this platform to differentiate commodity tablet offerings. The structural consequence is compression of development timelines for complex generic equivalents while raising technical barriers for conventional wet-granulation competitors.
EMA's Falsified Medicines Directive serialization mandates are forcing track-and-trace infrastructure investments across European supply chains. Secondary packaging lines now require aggregation capabilities linking individual blister packs to case-level identifiers. Oncology clinics and hospital pharmacies in Germany, France, and Italy are prioritizing suppliers with verified authentication systems, creating procurement preference hierarchies.
Specialty pharmacy distribution is displacing traditional wholesale channels for oral oncology products in the United States. Payers and pharmacy benefit managers are consolidating volume through limited network arrangements that favor vertically integrated dispensers. This concentration is most pronounced in Medicare Part D and commercial oncology benefit designs, where prior authorization workflows increasingly route prescriptions to preferred specialty pharmacy partners.
Anastrozole Tablets Market Segmentation
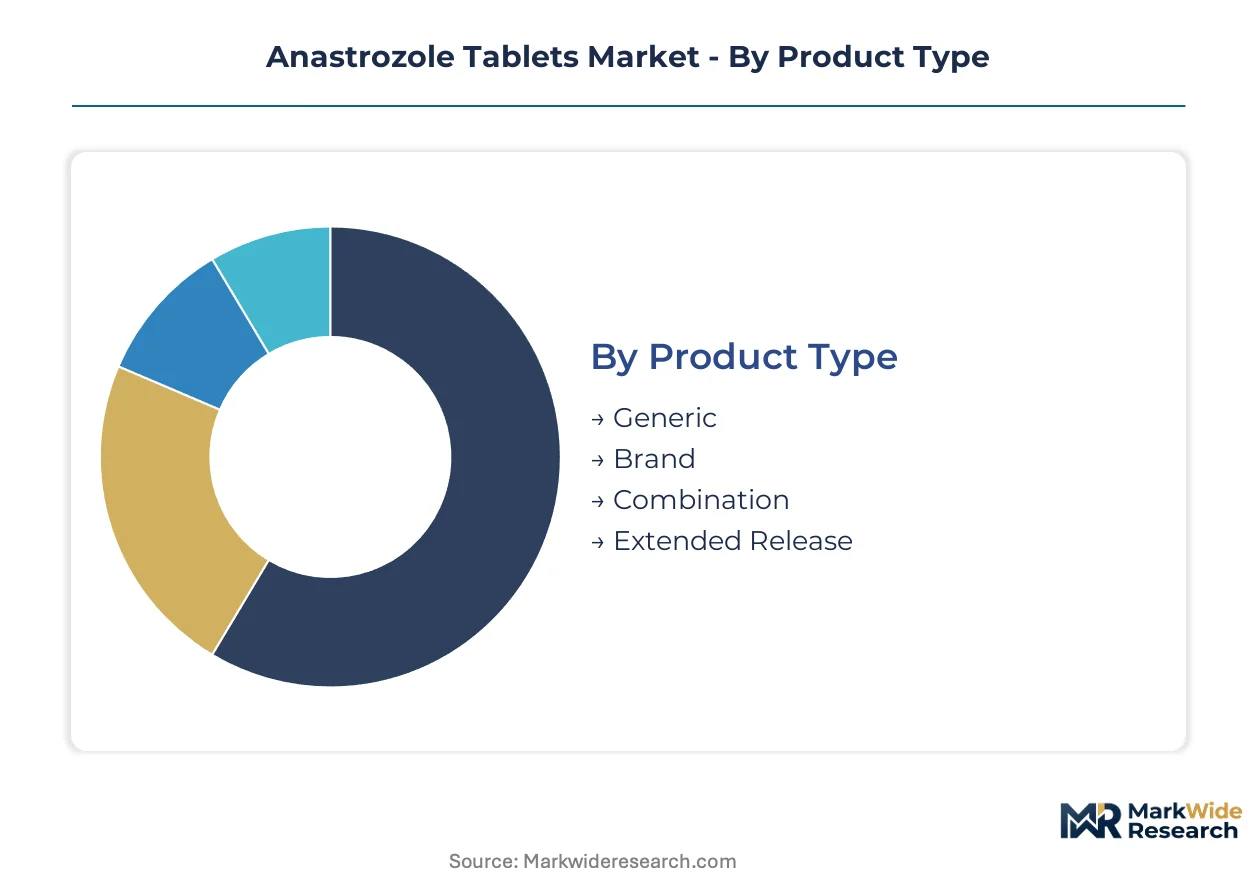
Segmentation in the anastrozole tablets market reveals how formulation choices, distribution channels, and packaging specifications align with distinct clinical workflows and regulatory requirements across oncology care settings. Understanding these divisions illuminates where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Generic formulations turn inventory fastest through high-volume dispensing channels, while extended-release variants cycle slowly through specialty oncology protocols requiring prior authorization.
- Generic:Multi-source competition following patent expiration has compressed margins while expanding patient access through FDA's abbreviated new drug application pathway. Oncology clinics in the United States drive volume throughput as aromatase inhibitor protocols standardize on cost-effective options.
- Brand:Originators maintain protocol loyalty in academic medical centers where physician familiarity and clinical data heritage support continued prescribing. AstraZeneca's Arimidex anchors this tier through established adjuvant therapy guidelines and oncology nursing education programs.
- Combination:Fixed-dose pairings with other hormonal agents address specific patient subpopulations in breast cancer treatment protocols.
- Extended Release:Modified-release formulations target dosing convenience improvements in long-term adjuvant therapy settings.
Generic formulations anchor the volume base while extended-release variants gain share at the steepest rate through premium positioning in convenience-focused protocols.
End User:
Cost tier differentiation separates institutional purchasers with formulary control from retail channels where patient cost-sharing influences selection.
- Oncology Clinics:Specialized infusion centers and cancer treatment facilities manage complex oral chemotherapy regimens with pharmacist oversight. United States-based community oncology practices drive prescription volumes as aromatase inhibitor adoption expands in postmenopausal hormone receptor-positive protocols.
- Hospitals:Inpatient and outpatient departments within integrated health systems leverage group purchasing organization contracts for standardized procurement.
- Outpatient Facilities:Ambulatory care centers capture share as oral chemotherapy administration shifts away from traditional infusion settings.
- Pharmacies:Retail and specialty pharmacy dispensers handle patient-facing fulfillment with insurance navigation support.
Oncology clinics concentrate the highest prescription volumes while outpatient facilities expand most quickly through care setting migration.
Administration Route:
Application logic governs this category, with oral delivery dominating breast cancer adjuvant therapy while alternative routes serve niche indications.
- Oral:The 1 mg tablet formulation enables self-administered daily dosing in long-term adjuvant therapy protocols. FDA bioequivalence standards ensure therapeutic consistency across generic and brand suppliers in United States markets.
- Intravenous:Parenteral delivery serves patients with compromised gastrointestinal absorption or acute care requirements.
- Subcutaneous:Depot formulations provide extended duration coverage for selected patient populations.
- Transdermal:Patch-based delivery remains experimental for aromatase inhibitor compounds.
Oral administration commands absolute volume dominance while intravenous routes retain critical role in acute care settings.
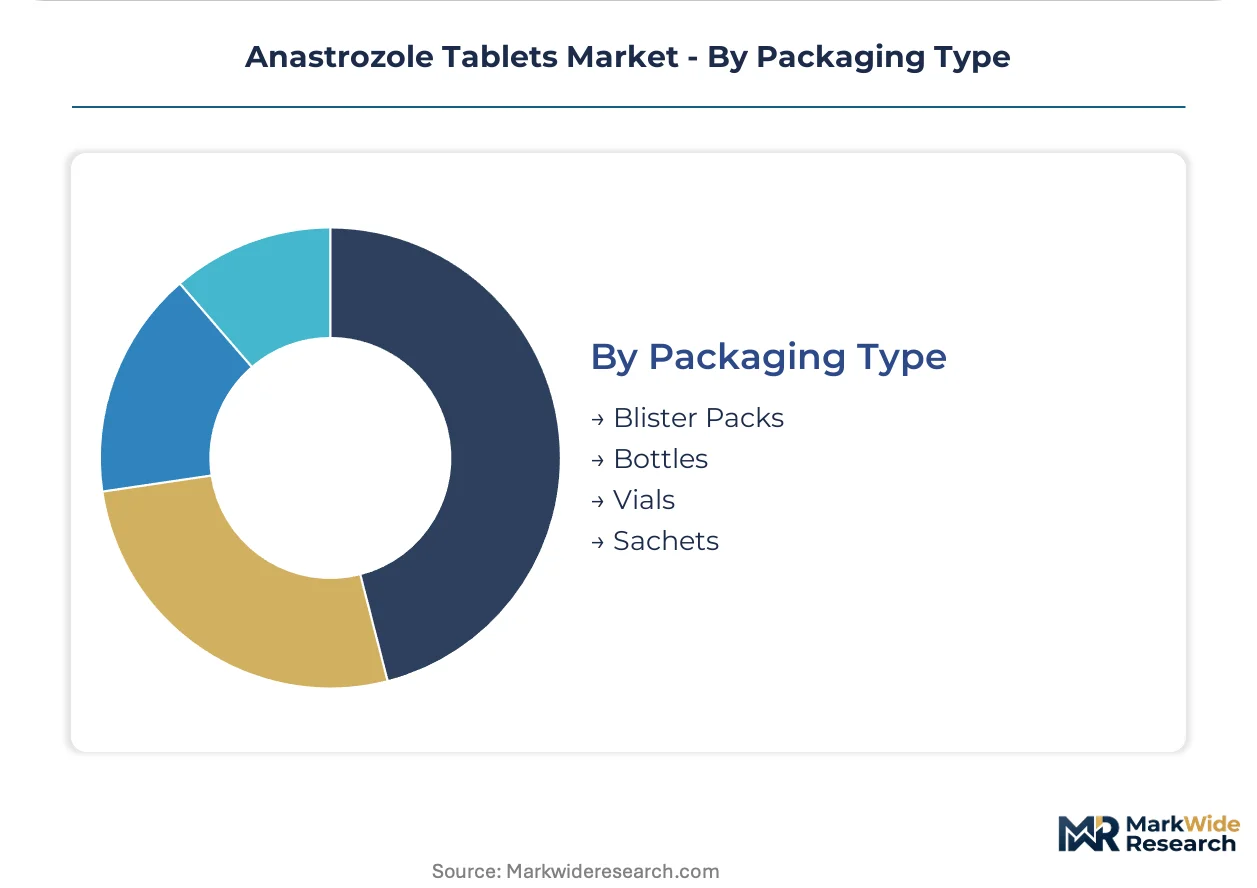
Packaging Type:
Supply concentration in blister pack manufacturing reflects institutional compliance requirements rather than patient preference.
- Blister Packs:Unit-dose aluminum-plastic configurations satisfy serialization mandates under EMA's Falsified Medicines Directive and institutional pharmacy requirements. German and French hospital pharmacies prioritize suppliers with verified track-and-trace aggregation capabilities.
- Bottles:Multi-count containers serve cost-sensitive retail pharmacy dispensing with child-resistant closure requirements.
- Vials:Parenteral packaging supports compounding pharmacy and clinical trial supply chains.
- Sachets:Single-unit flexible packaging addresses emerging market access and sample distribution needs.
Blister packs maintain institutional procurement preference while bottle formats retain retail pharmacy cost efficiency advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in active pharmaceutical ingredients reshape finished dose availability across major oncology markets, with API sourcing concentration in Asian manufacturing hubs creating supply chain vulnerabilities for Western formulators.
United States
Postmenopausal hormone receptor-positive breast cancer incidence sustains prescription volumes through community oncology practices and academic medical centers. FDA's abbreviated new drug application pathway accelerates generic entry, intensifying price competition while expanding patient access. The New Jersey and Pennsylvania pharmaceutical corridor hosts major finished dose operations serving domestic distribution networks.
Germany
Oncology clinics in Bavaria and North Rhine-Westphalia drive aromatase inhibitor protocol standardization through hospital purchasing consortiums. EMA's Falsified Medicines Directive serialization mandates force track-and-trace infrastructure investments across secondary packaging lines. The Rhine-Main industrial cluster concentrates pharmaceutical manufacturing with verified authentication systems for institutional procurement.
India
Domestic breast cancer burden and export-oriented generic production create dual demand channels for API and finished dose manufacturers. CDSCO oversight governs bioequivalence standards for local market approvals while WHO prequalification shapes access in low-income export destinations. The Hyderabad-Visakhapatnam pharmaceutical belt anchors contract manufacturing for global supply chains.
China
NMPA regulatory harmonization with ICH standards accelerates domestic innovation while maintaining cost advantages in API production. The Yangtze River Delta pharmaceutical zone clusters fermentation-based aromatase inhibitor precursor manufacturing with integrated downstream processing. Environmental compliance upgrades under MEE effluent regulations reshape capital allocation across production facilities.
United Kingdom
NHS England cancer drug fund mechanisms influence prescribing patterns through value-based procurement frameworks for oral oncology agents. MHRA post-Brexit regulatory autonomy maintains alignment with EMA quality benchmarks while streamlining national approval timelines. The Golden Triangle research corridor between London, Cambridge, and Oxford anchors clinical trial networks for extended-release formulation development.
Anastrozole Tablets Market Competitive Environment
On the supply side, the industry is bifurcated between originator brand maintenance and multi-source generic competition, with manufacturing technology differentiation creating a middle tier of specialized contract producers. Three strategic archetypes dominate: vertically integrated API-to-tablet operators, pure-play finished dose formulators, and research-intensive originators defending protocol loyalty. Capacity expansion and continuous manufacturing technology licensing represent the dominant competitive moves reshaping cost structures.
Among originator and large generic manufacturers, AstraZeneca Plc occupies a position exemplifying brand-anchored protocol loyalty in academic medical centers, while Teva Pharmaceutical Industries Ltd represents the vertically integrated archetype with captive API supply. Sun Pharmaceutical Industries Ltd sits within the emerging market specialist tier, leveraging localized production networks for geographic expansion.
| Leading Market Players |
|---|
| AstraZeneca Plc |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| Cipla Ltd |
| Zydus Pharmaceuticals |
| Hikma Pharmaceuticals |
| Natco Pharma |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta pharmaceutical zone anchors API production capacity for aromatase inhibitor precursors, with fermentation-based manufacturing scale directly translating into downstream pricing leverage for finished dose formulators in Europe and North America. Capacity utilization swings in this cluster transmit immediately into spot pricing volatility for contract manufacturers lacking captive supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in anastrozole procurement. Price differentiation rests on FDA bioequivalence certification tier and volume scale commitments from oncology clinic networks. Cost compression in the generic tier is intensifying because continuous manufacturing technology licenses are spreading among Indian and Chinese producers. Retail pharmacy dispensers exhibit the highest price sensitivity due to patient cost-sharing exposure, while academic medical centers maintain lower sensitivity through formulary lock-in.
Supply Chain Analysis
Geopolitical friction between India and China dominates supply chain risk assessment for Western formulators dependent on Asian API sourcing. Active pharmaceutical ingredient production concentrates in China, India, and select Eastern European facilities. Finished dose manufacturing draws from anastrozole base compound, lactose excipients, and aluminum blister foil. Single-source vulnerability persists for fermentation-derived precursors. Distribution runs through specialty pharmacy networks consolidating oral oncology volume in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
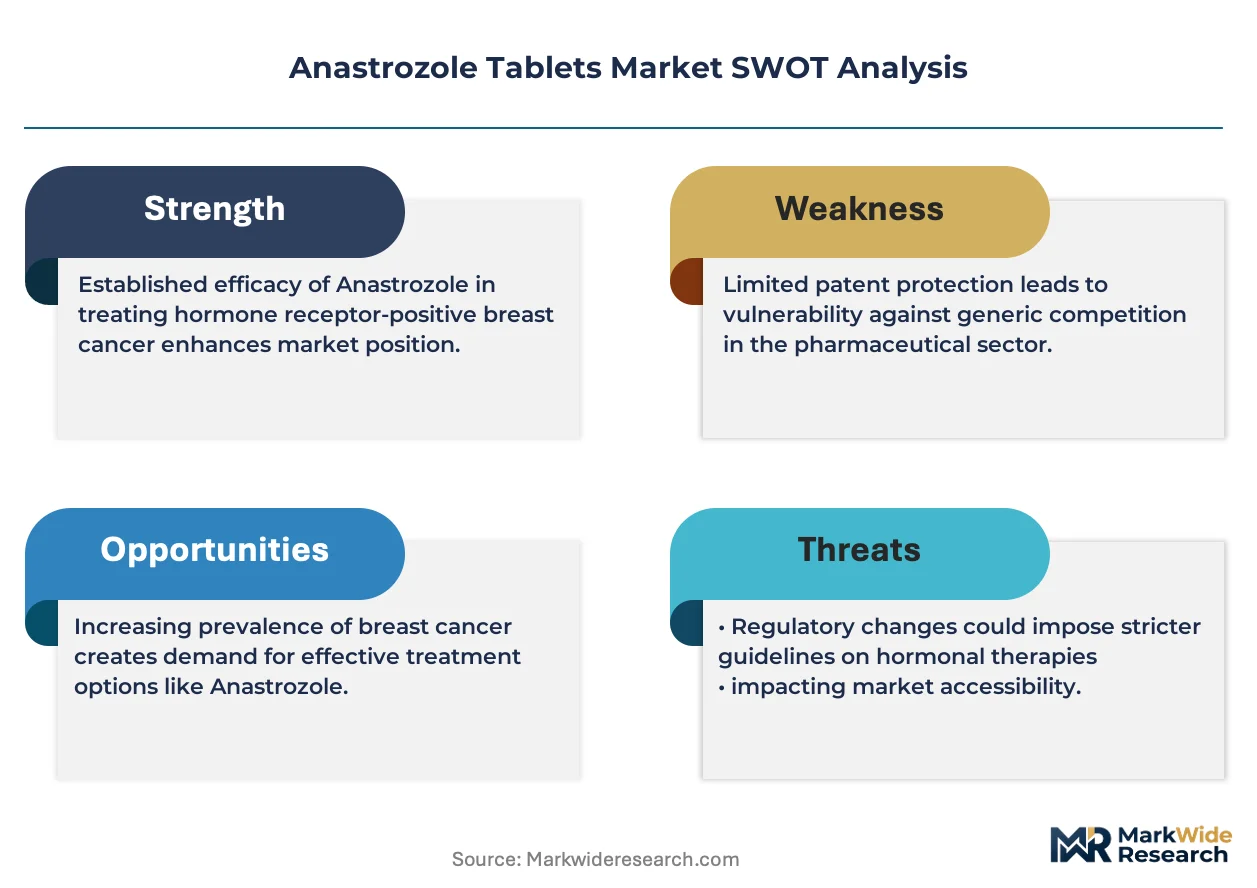
The anastrozole tablets market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. FDA bioequivalence standards and EMA serialization mandates create switching costs that new entrants cannot easily replicate.
For Market Incumbents: Harden protocol loyalty in academic medical centers through extended-release formulation pipelines and oncology nursing education investments. Deepen backward integration into API production to offset margin pressure from letrozole substitution. Continuous manufacturing technology licensing represents the critical lever for cost structure defense against emerging Indian producers.
For New Entrants and Emerging Players: Pursue outpatient facility channels as oral chemotherapy administration migrates from infusion centers. The most penetrable segment lies in extended-release development partnerships with European CDMOs lacking hot-melt extrusion capabilities. A go-to-market angle through EMA centralized procedure filings enables simultaneous multi-country commercialization without country-by-country registration.
For Investors and Strategic Acquirers: Long-term, this sits as a cash-flow compounder play because postmenopausal breast cancer incidence sustains prescription volumes with limited therapeutic substitution risk. Acquisition targets should display vertically integrated API-to-tablet infrastructure with WHO prequalification status. The signal to watch is EPA effluent enforcement intensity reshaping production location economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Licensing | Hot-melt extrusion technology adoption compresses batch variability for generic producers. |
| EMA Centralized Procedure Filing | Simultaneous multi-country approval reduces registration timelines across European markets. |
| Extended-Release Formulation Development | Modified-release tablets command premium positioning in convenience-focused oncology protocols. |
| Specialty Pharmacy Network Partnership | Medicare Part D prior authorization workflows favor vertically integrated dispensers. |
| API Backward Integration | Captive supply of C17H19N5 precursors insulates margin from Asian sourcing disruptions. |
Study Parameters
Cross-validation between primary interviews with oncology clinic pharmacists and secondary FDA ANDA filings anchors the qualitative findings. Conversations with formulary directors, contract manufacturing executives, and GPO procurement managers informed supply-side dynamics. Regulatory affairs specialists at EMA and CDSCO provided compliance pathway intelligence. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure data from CMS and NHS England.
Calibration against historical generic entry patterns and patent cliff dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, administration route, and regional regulatory cluster. CAGRs derived from patent expiration timelines, biosimilar competition intensity, and aromatase inhibitor protocol adoption curves. Forecast inputs incorporated continuous manufacturing penetration rates and specialty pharmacy channel concentration.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy and API trade flows would shift the trajectory. Forecasts reflect assumptions on regulatory harmonization and environmental compliance cost pass-through. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Antihelminthics Market