
 Sterile Dosage Form Market | 2026-2036
Sterile Dosage Form Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Dosage Form Market Insights
Hospital procurement channels is reconfiguring as integrated delivery networks consolidate supplier contracts for sterile dosage forms. Gerresheimer AG leverages its European fill-finish footprint to anchor long-term agreements with institutional buyers. Schott AG specializes in borosilicate glass containment solutions that sustain premium positioning across oncology and anesthesia applications. Nipro Corporation competes through Asian manufacturing scale that controls cost structures for standard vial and ampoule segments.
A sterile dosage form is a pharmaceutical preparation manufactured and packaged under aseptic conditions to eliminate microbial contamination, typically involving terminal sterilization or aseptic processing with particulate filtration and validated cleanroom environments. These formulations serve critical therapeutic functions where even minor bioburden risks threaten patient safety, particularly in parenteral administration of biologics and cytotoxic agents. Pre-filled syringes command expanding share as delivery mode convenience reduces medication errors and nursing labor in hospital and home care settings. Intravenous administration dominates value pools across oncology and infectious disease therapy areas, while subcutaneous formats gain traction in biologic self-administration protocols that shift site of care toward outpatient and home environments.
The FDA enforces current Good Manufacturing Practice standards for sterile drug products under 21 CFR Parts 210 and 211, with particular scrutiny of aseptic processing validation and environmental monitoring protocols that directly shape capital expenditure requirements for manufacturers. The EMA and national competent authorities apply Annex 1 of the EU GMP guide, mandating barrier isolation technology and continuous particulate monitoring that filter market access toward facilities with advanced containment infrastructure. Stakeholders must monitor regulatory divergence between FDA and EMA expectations for contamination control strategy documentation, as harmonization gaps will determine which manufacturing sites qualify for dual-territory supply without redundant qualification runs.
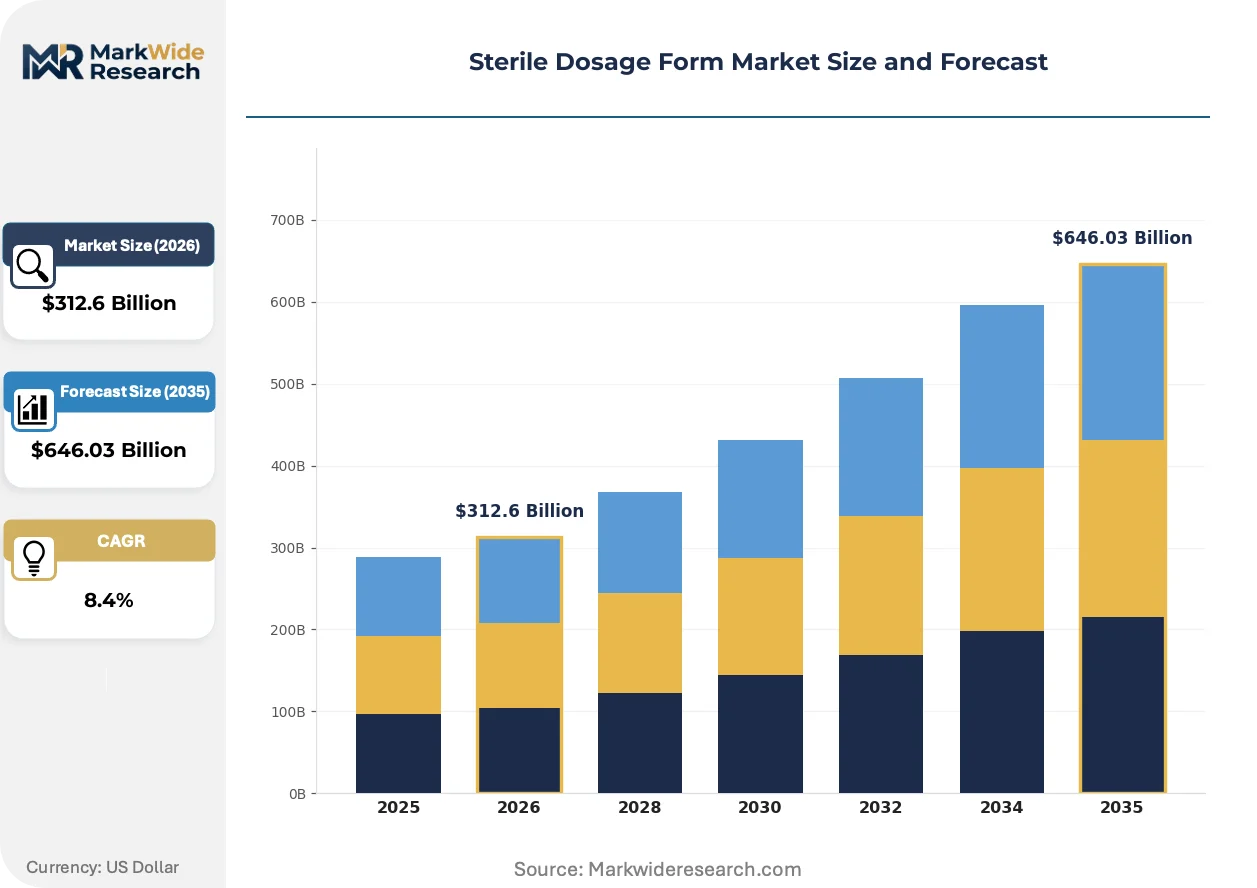
Market Dynamics
Barrier isolation technology is forcing wholesale facility redesigns as FDA and EMA contamination control standards tighten simultaneously, concentrating fill-finish capacity among operators capable of ISO 5 environment validation.
Growth Catalysts
- Biologics pipeline expansion:Oncology monoclonal antibodies require aseptic processing for heat-sensitive molecules, pulling investment toward specialized containment infrastructure.
- Annex 1 EU GMP revision:Mandatory barrier technology upgrades filter market access toward advanced manufacturing sites, accelerating consolidation among compliant operators.
- Home care administration shift:Pre-filled syringes reduce nursing labor and medication errors in outpatient oncology protocols, expanding addressable volume beyond hospital settings.
Market Restraints
- Borosilicate glass supply concentration:Schott AG and Nipro Corporation control premium tubular glass supply, creating single-source vulnerability for vial-dependent formulations.
- Isolator qualification timelines:EMA barrier validation protocols extend facility approval cycles to 18-24 months, compressing effective capacity expansion windows.
- Lyophilization equipment scarcity:Freeze-dryer manufacturing backlogs limit biologics fill-finish throughput regardless of cleanroom availability.
Strategic Opportunities
- Indian contract manufacturing:CDSCO regulatory alignment with ICH standards opens sterile injectable outsourcing from Western sponsors seeking cost arbitrage.
- Cell therapy aseptic processing:Autologous CAR-T manufacturing requires closed-system fill-finish innovation absent from legacy small-molecule infrastructure.
- Pre-filled syringe self-administration:Rheumatology and endocrinology biologics shift site of care, creating demand for combination product expertise.
Industry Challenges
- Contamination control strategy documentation:FDA and EMA divergence in quality risk assessment formats forces dual-track qualification for multi-territory supply.
- Aseptic processing technician scarcity:ISO 5 environment behavior training programs lag facility expansion timelines, constraining operational readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Dosage Form Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Vials, Ampoules, Pre-filled Syringes Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Oncology, Anesthesia, Infectious Diseases, Cardiovascular |
| Companies Covered | Schott AG, Corning Incorporated, Bormioli Pharma S.p.A., Piramal Glass, Gerresheimer AG, DWK Life Sciences GmbH, Nipro Corporation, Adelphi Healthcare Packaging, APG Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Dosage Form Market Trends and Innovations
Digital twin technology is compressing facility qualification timelines while regulatory data integrity requirements reshape validation protocols across sterile manufacturing operations.
Isolator-integrated filling lines are virtualizing cleanroom architecture by replacing open Grade A environments with closed robotic processing chambers. Contract manufacturers in Germany and the United States are adopting these systems at replacement cycle points to reduce personnel gowning requirements and particulate generation sources. This virtualization is compressing environmental monitoring costs while extending batch run durations for high-value oncology biologics.
EMA Annex 1 2022 revision mandates continuous viable and non-viable particle monitoring with alarm-triggered batch disposition protocols. Pharmaceutical manufacturers must install redundant detection systems and real-time data acquisition infrastructure to satisfy inspector expectations for proactive contamination response. Small-volume parenteral facilities in Ireland and Belgium face disproportionate retrofit burdens relative to greenfield sites designed under the revised standard.
Integrated delivery networks are consolidating sterile dosage form procurement under single-source agreements with fill-finish operators capable of multi-product flexibility. Hospital systems in the United States are displacing fragmented distributor relationships with direct manufacturer contracts that bundle vial, syringe, and cartridge formats under unified quality agreements. This concentration is most visible in Texas and California health systems where oncology infusion center networks drive volume commitments.
Sterile Dosage Form Market Segmentation
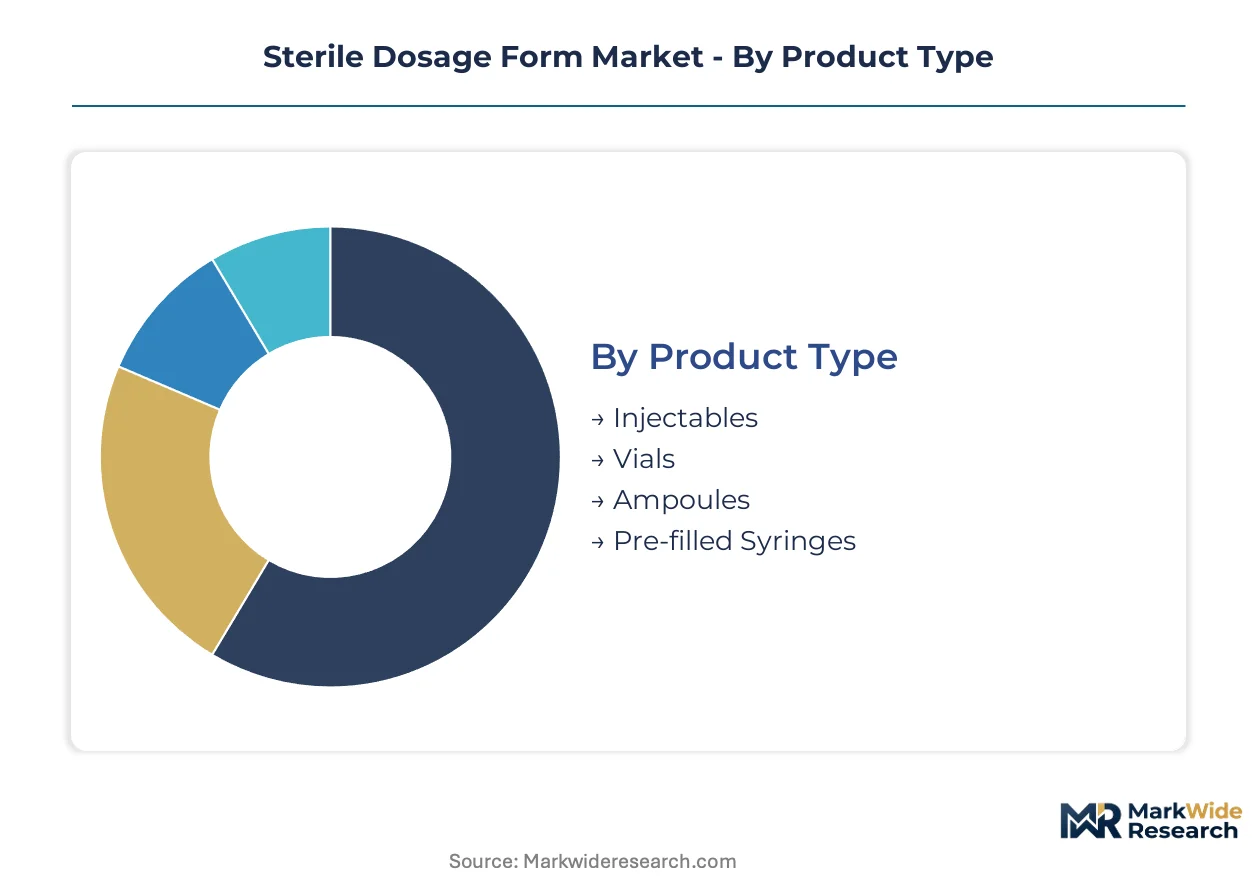
Sterile dosage form manufacturers configure production lines around specific containment formats and administration routes. Each segment imposes distinct cleanroom validation requirements and barrier technology investments that shape facility economics.
Product Type:
Mature formats dominate current throughput while advanced delivery systems capture growth from biologics expansion and site-of-care shifts.
- Injectables:Liquid and lyophilized formulations in bulk containers requiring aseptic filling into final presentation formats. Hospital infusion centers in the United States and Germany concentrate demand for oncology monoclonal antibodies, though lyophilization equipment scarcity constrains throughput expansion regardless of cleanroom availability.
- Pre-filled Syringes:Single-unit presentations combining drug product with integrated needle systems that eliminate vial-to-syringe transfer steps. Home care administration protocols for rheumatology and endocrinology biologics in North American and European markets pull capacity toward combination product expertise and self-injection training infrastructure.
- Vials:Borosilicate glass or polymeric containers for multi-dose or single-use parenteral administration, standardized across institutional procurement.
- Ampoules:Sealed glass units for single-dose immediate use, concentrated in anesthesia and emergency medicine applications with cost-sensitive manufacturing.
Injectables handle the majority of throughput; Pre-filled Syringes is expanding most quickly on share as biologics self-administration protocols proliferate.
Delivery Mode:
Volume concentration aligns with acute care settings while margin expansion tracks outpatient and home administration capabilities.
- Intravenous:Direct vascular administration requiring infusion infrastructure and nursing supervision. Oncology therapy areas in hospital and ambulatory infusion centers across the United States drive absolute volume, with EMA Annex 1 contamination control mandates extending batch validation timelines for high-value cytotoxic formulations.
- Subcutaneous:Tissue-layer injection enabling patient self-administration without vascular access. Biologics developers targeting rheumatology and diabetes markets in Germany and Switzerland prioritize this route to reduce site-of-care costs and expand addressable patient populations beyond infusion center capacity.
- Intramuscular:Deep tissue deposition for vaccine and long-acting antipsychotic formulations with established immunization infrastructure.
- Inhalation:Pulmonary delivery of sterile solutions for respiratory therapy, requiring specialized particle engineering and device integration.
Intravenous retains the largest volume footprint; Subcutaneous is gaining share fastest as pharmaceutical sponsors redesign molecules for self-administration compatibility.
End User:
Procurement consolidation is restructuring channel economics across institutional and direct-to-patient distribution pathways.
- Hospitals:Integrated delivery networks consolidating supplier contracts under single-source agreements with fill-finish operators capable of multi-product flexibility. Texas and California health systems bundle vial, syringe, and cartridge formats under unified quality agreements that displace fragmented distributor relationships.
- Home Care:Outpatient and residential administration settings requiring patient training infrastructure and cold-chain logistics. Pre-filled syringe formats reduce nursing labor and medication error liability as oncology and immunology protocols shift site of care beyond traditional facilities.
- Clinics:Ambulatory infusion and injection centers with specialized nursing staff and shorter patient stays than hospital settings.
- Pharmacies:Retail and specialty dispensing channels with compounding capabilities for patient-specific dosing adjustments.
Hospitals command the dominant procurement volume; Home Care shows the steepest expansion trajectory as reimbursement models incentivize site-of-care migration.
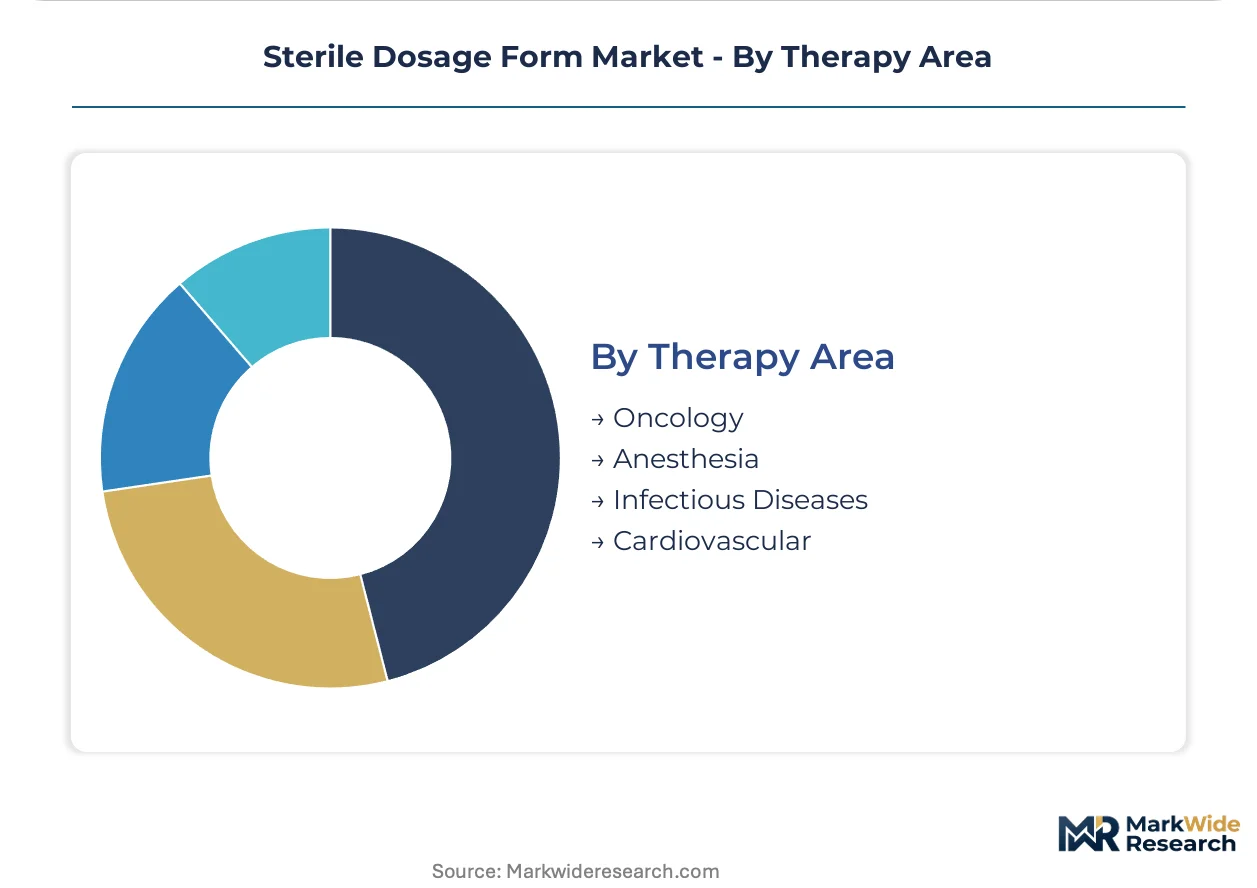
Therapy Area:
Clinical application segments align manufacturing priorities with disease-specific regulatory and handling requirements.
- Oncology:Cytotoxic and biologic formulations requiring containment infrastructure for operator protection and product integrity. FDA and EMA aseptic processing standards for heat-sensitive monoclonal antibodies concentrate investment in barrier isolation technology and continuous environmental monitoring systems.
- Infectious Diseases:Antibiotic and antiviral sterile presentations with high-volume demand and cost-sensitive procurement. Pandemic preparedness stockpiling in the United States and European Union shapes capacity planning for injectable broad-spectrum agents.
- Anesthesia:Rapid-onset intravenous agents for surgical settings with standardized dosing and established generic competition.
- Cardiovascular:Emergency and chronic administration of anticoagulants and antiarrhythmics with acute care concentration.
Oncology generates the highest value per unit; Infectious Diseases is climbing the fastest on volume as antimicrobial resistance drives novel formulation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain terminals anchor European sterile injectable distribution into Germany and the Benelux, while direct rail links from Frankfurt Airport's cargo hub feed fill-finish facilities across the Rhine-Main manufacturing corridor.
United States
Oncology infusion center networks in Texas and California drive concentrated demand for pre-filled syringe and vial formats. FDA 21 CFR Parts 210 and 211 enforcement tightens aseptic processing validation requirements, extending facility approval timelines. The Boston-Cambridge biotech cluster anchors cell therapy aseptic processing innovation, with specialized CDMOs retrofitting legacy small-molecule infrastructure for autologous manufacturing.
Germany
Rheumatology and diabetes biologics developers prioritize subcutaneous administration formats to reduce site-of-care costs. EMA Annex 1 2022 revision mandates barrier isolation technology and continuous particulate monitoring, filtering market access toward advanced manufacturing sites. The Frankfurt-Rhine-Main corridor concentrates fill-finish capacity serving global biopharma supply chains, with Gerresheimer AG leveraging its European footprint for institutional procurement agreements.
Switzerland
Swissmedic oversight of biologics manufacturing maintains premium positioning for high-value oncology and immunology formulations. The Basel region hosts specialized containment infrastructure for cytotoxic drug processing, with Roche and Novartis supply chains demanding ISO 5 environment validation. Swiss facilities face disproportionate retrofit burdens for EMA Annex 1 compliance relative to greenfield sites designed under revised standards.
India
CDSCO regulatory alignment with ICH standards opens sterile injectable outsourcing from Western sponsors seeking cost arbitrage. Maharashtra and Gujarat host contract manufacturing clusters serving global fill-finish demand, with Bormioli Pharma and Piramal Glass expanding borosilicate glass conversion capacity. The country's national pharmaceutical regulator accelerates facility inspections for export-oriented sterile dosage form production.
Japan
PMDA oversight of combination products shapes pre-filled syringe development for rheumatology and endocrinology self-administration protocols. The Kanto region around Tokyo concentrates aseptic processing expertise for biologics requiring heat-sensitive molecule handling. Japanese manufacturers face lyophilization equipment scarcity that constrains biologics throughput regardless of cleanroom availability.
Sterile Dosage Form Market Competitive Landscape
On the supply side, the industry is consolidating around operators capable of ISO 5 environment validation and barrier isolation technology deployment. Three strategic archetypes dominate: European glass containment specialists with premium borosilicate positioning, Asian manufacturers competing on cost structure for standard vial segments, and integrated packaging providers bundling fill-finish with delivery system expertise. Competitive moves concentrate on facility retrofit cycles for EMA Annex 1 compliance and long-term procurement agreements with consolidating hospital systems.
Within the European glass containment tier, Schott AG and Gerresheimer AG exemplify premium positioning strategies, while Nipro Corporation occupies a scale-driven position in Asian manufacturing. DWK Life Sciences GmbH represents mid-cap specialists navigating retrofit timelines for barrier technology adoption. These anchors illustrate how regulatory compliance capacity increasingly separates market access tiers across oncology and anesthesia applications.
| Leading Market Players |
|---|
| Schott AG |
| Corning Incorporated |
| Bormioli Pharma S.p.A. |
| Piramal Glass |
| Gerresheimer AG |
| DWK Life Sciences GmbH |
| Nipro Corporation |
| Adelphi Healthcare Packaging |
| APG Europe |
| Others |
Pricing and Supply Chain Analysis
German borosilicate glass manufacturing clusters anchor upstream supply for premium vial and syringe containment, concentrating margin capture with Schott AG and Gerresheimer AG while downstream fill-finish operators absorb cost pass-through pressure. This upstream concentration shapes tiered pricing structures across oncology and anesthesia applications where ISO 5 validation requirements filter market access.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement as integrated delivery networks consolidate supplier contracts across Texas and California health systems. Three-tier pricing stratifies across premium barrier-isolation validated formats, standard aseptic vial presentations, and economy ampoule segments for cost-sensitive anesthesia applications. Pricing pressure stems from EMA Annex 1 retrofit capital requirements compressing margin pools for mid-cap operators without greenfield advantages. Hospital procurement committees exhibit highest price sensitivity for standard infectious disease antibiotics, while oncology biologics buyers prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes for advanced barrier isolation technology limit equipment flows from Germany and Switzerland into Indian and Southeast Asian manufacturing expansions, constraining capacity buildout timelines. Supply concentrates in Germany for precision glass containment, India for contract fill-finish scale, and Japan for lyophilization equipment manufacturing. Raw material dependencies include borosilicate glass tubing, pharmaceutical-grade elastomeric closures, and WFI-grade stainless steel. Single-source vulnerability runs through Schott AG's premium tubular glass position. Distribution runs through direct manufacturer agreements with consolidating hospital systems displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile dosage form manufacturing represents a service-attach opportunity where validation documentation and continuous environmental monitoring contracts expand faster than hardware sales. After-sales contamination control strategy consulting and batch disposition advisory services capture recurring revenue from facilities facing EMA Annex 1 compliance deadlines.
For Market Incumbents: Insulate market position through backward integration into borosilicate glass conversion capacity and captive barrier technology manufacturing to neutralize supply concentration risk. Prioritize certification investment for dual FDA-EMA qualification to capture multi-territory supply contracts without redundant validation runs. Defend against emerging Indian CDMO cost arbitrage by anchoring long-term agreements with consolidating Texas and California integrated delivery networks. For New Entrants and Emerging Players: Establish a beachhead in cell therapy aseptic processing where autologous CAR-T manufacturing demands closed-system fill-finish innovation absent from legacy infrastructure. Target the Indian contract manufacturing segment where CDSCO regulatory alignment with ICH standards opens Western sponsor outsourcing. Pursue a go-to-market angle bundling barrier technology deployment with technician training programs to address ISO 5 environment behavior scarcity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barrier isolation technology deployment as EMA Annex 1 mandates filter market access toward advanced manufacturing sites. Long-term viability across the analysis window favors operators with validated ISO 5 environments and established institutional procurement relationships. Acquisition targets should emphasize mid-cap specialists with retrofit timelines accelerating toward compliance deadlines. The signal to watch is FDA-EMA harmonization gaps in contamination control strategy documentation formats.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolation Technology Deployment | EMA Annex 1 compliance mandates filter market access toward advanced containment infrastructure operators. |
| Backward Integration into Glass Containment | Captive borosilicate supply neutralizes Schott AG and Nipro Corporation single-source vulnerability. |
| Cell Therapy Aseptic Processing Capability | Autologous CAR-T manufacturing requires closed-system fill-finish absent from legacy small-molecule sites. |
| Integrated Delivery Network Direct Contracting | Texas and California health systems displace fragmented distributor relationships with unified quality agreements. |
| Dual FDA-EMA Qualification Investment | Harmonization gaps in contamination control documentation determine multi-territory supply eligibility. |
Research Methodology
Operator-level perspectives from fill-finish facility directors, regulatory affairs leads, hospital procurement managers, and aseptic processing technicians anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA 483 inspection observations, EMA GMP inspection reports, and hospital GPO contract databases. Bottom-up capacity modeling and top-down therapy-area demand projections were triangulated to cross-check volume estimates across the sterile dosage form value chain.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, delivery mode, end user, and therapy area. CAGRs were derived from fitted growth curves applied to base-year sizing, with cross-validation against biologics pipeline data and institutional procurement volume trends. Forecast inputs incorporated lyophilization equipment manufacturing backlogs, barrier technology deployment timelines, and Annex 1 compliance retrofit schedules.
Sensitivities concentrate around EMA-FDA regulatory divergence, borosilicate glass supply disruption, and aseptic processing technician availability constraints. Forecasts reflect documented assumptions regarding biologics pipeline advancement and hospital procurement consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Global Diphenhydramine Market