
 Global Viral Vaccines Market | 2026-2036
Global Viral Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Viral Vaccines Market Foresight
Direct procurement channels between national immunization programs and manufacturers is reconfiguring how doses flow from production facilities to end users. Pfizer Inc. leverages its cold-chain logistics network to sustain delivery contracts across multiple continents. Moderna Inc. anchors its position through mRNA platform specialization that extends into emerging infectious disease preparedness. GSK plc competes via differentiated adjuvant technologies that occupy a distinct tier in combination vaccine formulations.
Viral vaccines comprise biologically active preparations containing attenuated, inactivated, or recombinant antigenic components derived from pathogenic viruses, formulated to elicit protective immune responses through the stimulation of neutralizing antibodies and memory T-cell populations. These products serve the primary commercial purpose of preventing morbidity and mortality from communicable diseases in mass immunization campaigns and targeted risk-group interventions. mRNA vaccines represent the fastest-expanding product type as manufacturing scalability and speed-to-clinic advantages attract procurement preference during outbreak response scenarios. Live attenuated vaccines retain mature, stable margin pools in pediatric combination products where long-standing safety profiles support premium pricing in private-pay segments.
The FDA's breakthrough therapy designation and EMA's PRIME scheme are compressing development timelines and reshaping how sponsors prioritize pipeline candidates for regulatory investment. WHO prequalification standards govern access to procurement by Gavi and UNICEF, creating a dual-track compliance burden for manufacturers serving both donor-funded and commercial markets. Stakeholders must monitor how the EU AI Act and emerging computational validation requirements will reshape predictive modeling for vaccine immunogenicity assessments.
Market Dynamics
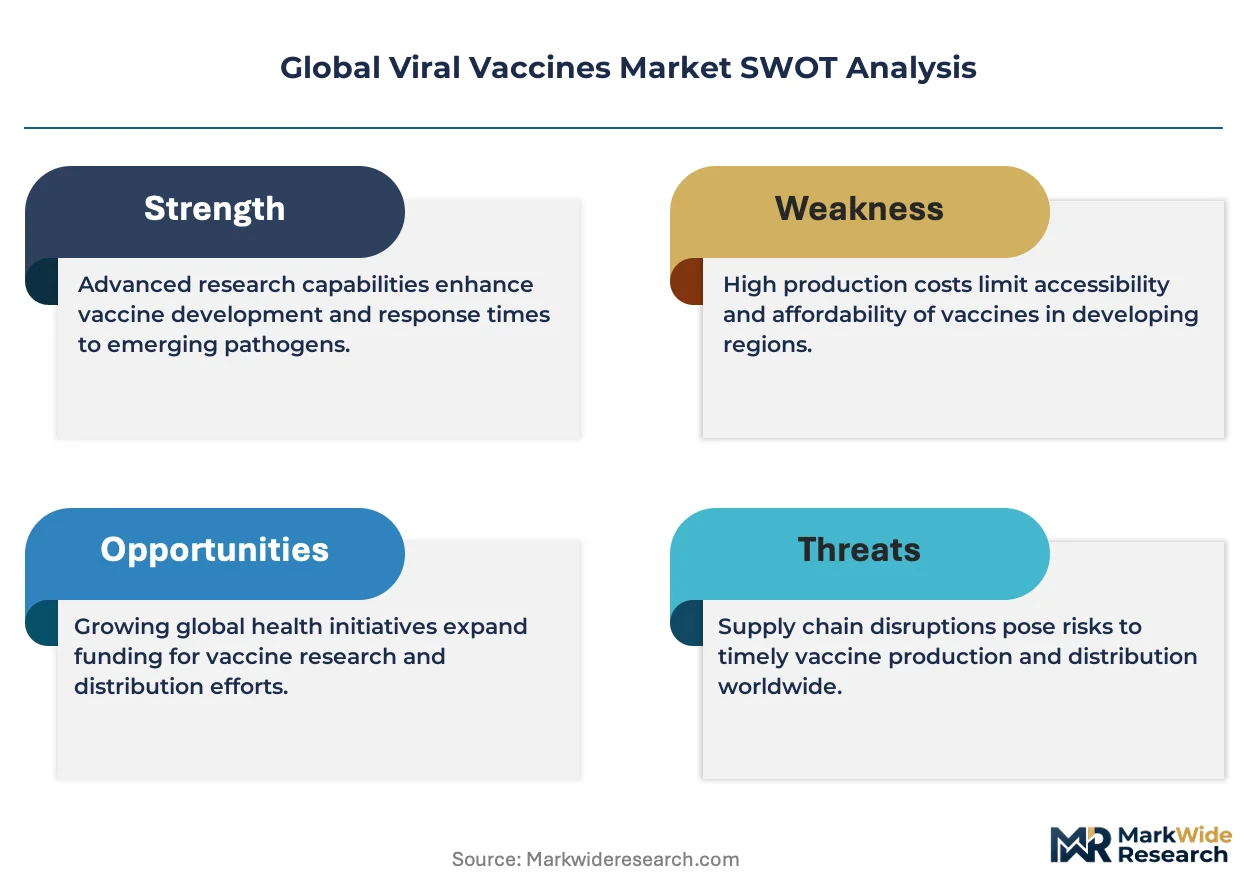
mRNA platform standardization is collapsing traditional development timelines while WHO prequalification requirements and Gavi procurement frameworks reshape competitive entry barriers for manufacturers serving low-income country immunization programs.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses Phase II-to-III transitions for novel viral vaccine candidates, reducing sponsor capital at risk during pivotal trials.
- Fill-Finish Capacity Expansion:Indian domestic manufacturers are scaling aseptic filling lines to capture UNICEF tender volumes, redirecting dose flows from Western European contract manufacturing organizations.
- mRNA Manufacturing Modularity:Platform-based production cell lines enable rapid antigen switching for outbreak response, attracting BARDA and CEPI funding commitments for pandemic preparedness stockpiles.
Market Restraints
- Lipid Nanoparticle Input Concentration:Four suppliers control 90% of ionizable lipid production for mRNA formulations, creating single-source vulnerability for dose scale-up campaigns.
- Cold-Chain Infrastructure Gaps:Ultra-low temperature storage requirements for mRNA products exclude last-mile distribution in rural Indonesia, Nigeria, and Democratic Republic of Congo health posts.
- EMA Regulatory Friction:The EU AI Act's computational validation requirements for predictive immunogenicity modeling impose documentation burdens that delay marketing authorization submissions by 8-14 months.
Strategic Opportunities
- Combination Pediatric Formulations:Hexavalent and heptavalent products addressing measles-mumps-rubella-varicella plus emerging pathogens command premium positioning in Brazil's expanded immunization schedule.
- Self-Amplifying RNA Convergence:The fusion of saRNA platforms with microneedle patch delivery systems enables room-temperature-stable products for decentralized administration in Kenyan and Vietnamese community health worker programs.
- Direct National Procurement Channels:Brazil's Ministry of Health and Indonesia's Bio Farma are bypassing UNICEF intermediaries to negotiate volume commitments directly with manufacturers, compressing margin leakage.
Industry Challenges
- Computational Biology Talent Scarcity:Vaccine developers compete with tech sector employers for machine learning specialists capable of training epitope prediction models, inflating compensation costs in Boston and Basel clusters.
- Legacy Adjuvant Facility Retooling:Aluminum salt manufacturing lines require $40-80 million conversion investments to produce next-generation saponin and emulsion adjuvants, straining mid-cap balance sheets.
- WHO Prequalification Timeline Compression:Manufacturers face 18-24 month inspection queues for new facility approvals, delaying Gavi-eligible market entry despite clinical trial completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Viral Vaccines Market |
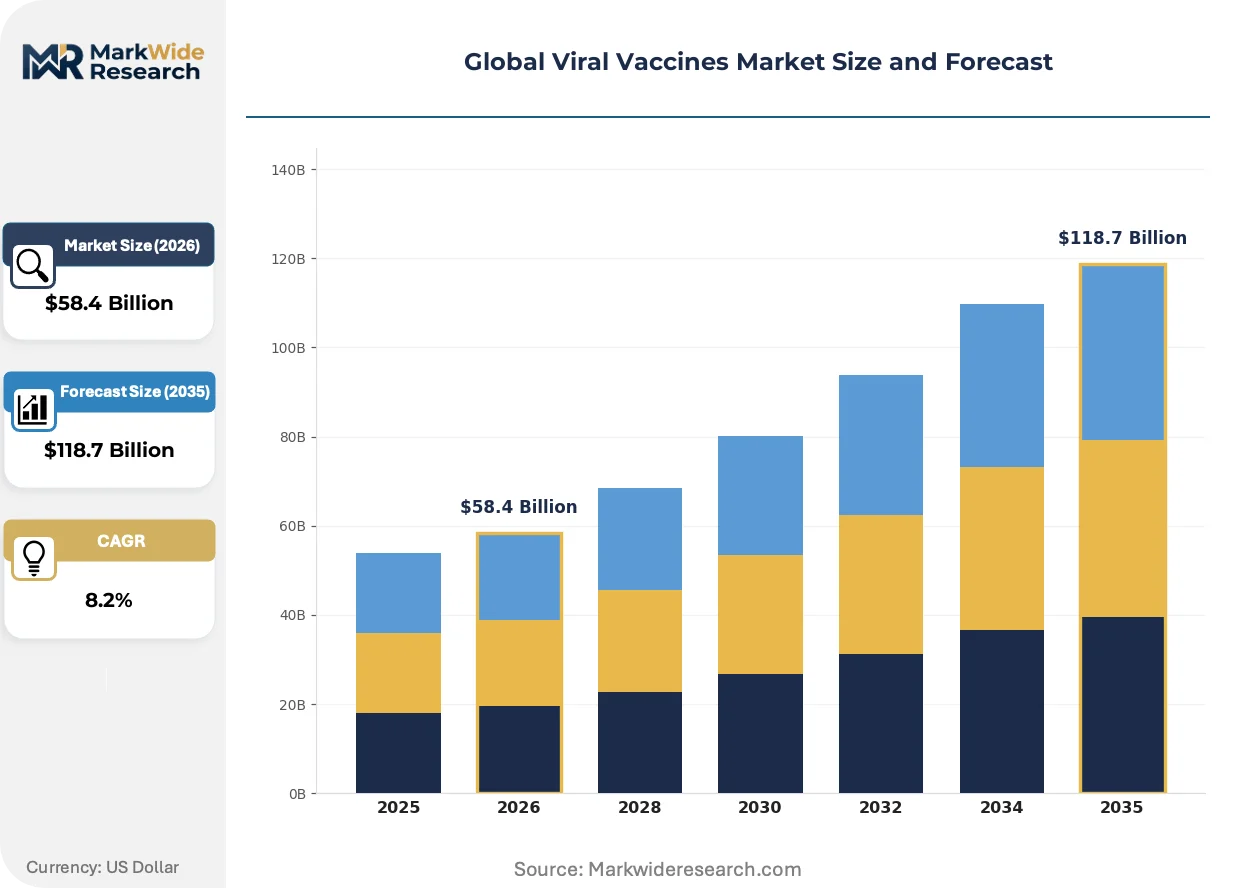
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $118.7 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Subunit Vaccines, mRNA Vaccines End User: Hospitals, Clinics, Research Laboratories, Pharmacies Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Target Virus: Influenza Virus, Measles Virus, Hepatitis Virus, Zika Virus |
| Companies Covered | Pfizer Inc., Moderna Inc., Merck & Co., Inc., GSK plc, Sanofi, AstraZeneca, Johnson & Johnson, CSL Seqirus, Novavax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Viral Vaccines Market Shifts & Advancements
Platform convergence and regulatory science advances are compressing the traditional 10-15 year vaccine development arc while procurement centralization reshapes commercial access pathways.
Self-amplifying RNA technology is collapsing the dose-sparing economics of conventional mRNA platforms. saRNA constructs encode replicase enzymes that amplify antigen expression from minimal input material, enabling 10-fold dose reduction per vial. National immunization programs in Thailand and Mexico are prioritizing saRNA candidates in tender evaluations, pressuring first-generation mRNA sponsors to license replication technology or cede cost-sensitive procurement segments.
The EU AI Act's risk-based classification system for predictive immunogenicity algorithms imposes validation documentation requirements that diverge from FDA computational modeling guidance. Sponsors developing universal influenza or HIV mosaic candidates must maintain dual-track evidence packages, increasing regulatory affairs headcount by 30-40% for pipeline assets employing machine learning-driven epitope selection. EMA's draft qualification opinion process for AI-based biomarker discovery remains unresolved, creating submission timing uncertainty for 2027-2028 filing waves.
National immunization programs are consolidating procurement authority into centralized tendering agencies that negotiate multi-year supply commitments with price escalation caps. Brazil's Ministry of Health now manages all pediatric vaccine purchasing through its own contracting office rather than PAHO's Revolving Fund, enabling direct manufacturer relationships that bypass traditional distribution intermediaries. This channel compression is most visible in pneumococcal and rotavirus product categories where single-tender volumes exceed 15 million annual doses.
Global Viral Vaccines Market Segmentation
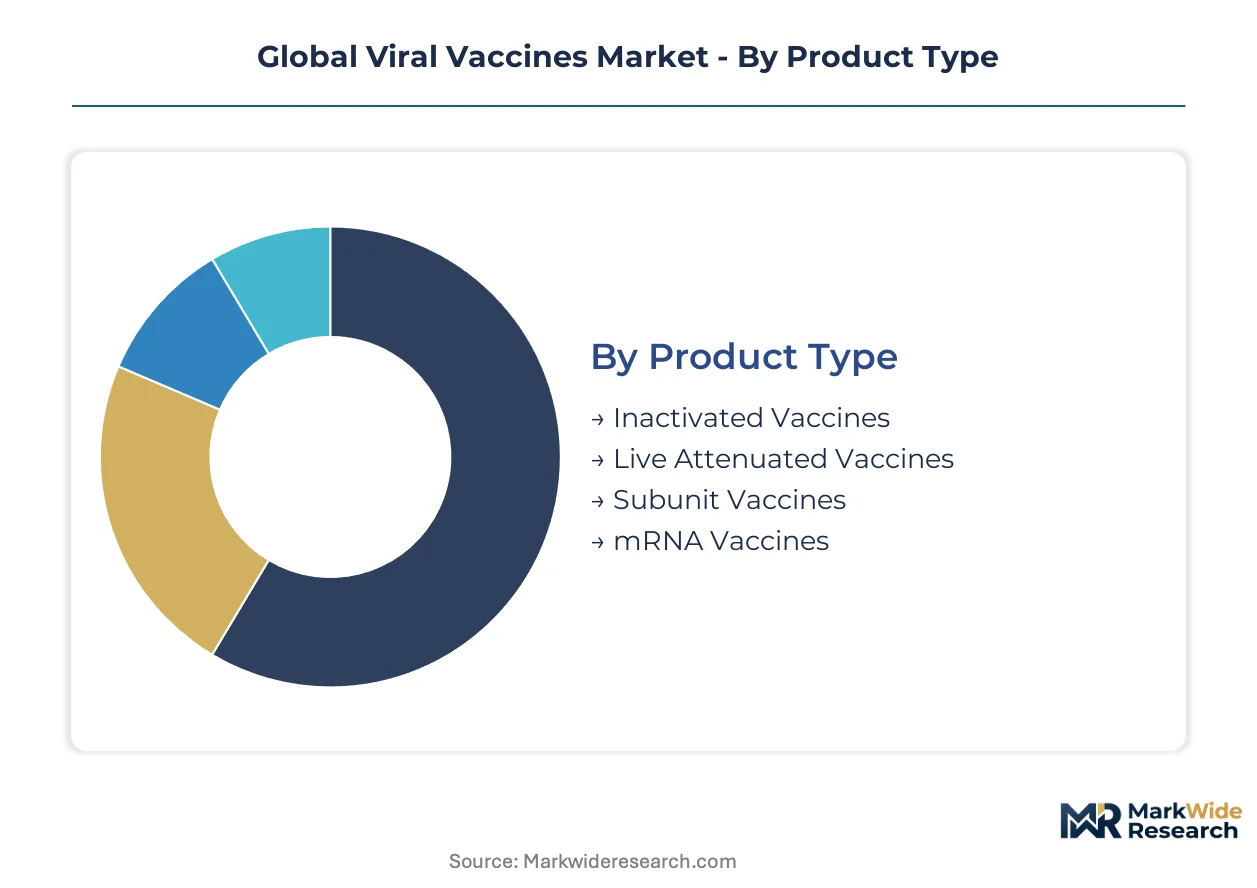
Vaccine platform diversity creates distinct commercial zones where manufacturing complexity, cold-chain requirements, and regulatory pathways fragment procurement patterns. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Mature platforms with established fill-finish infrastructure coexist alongside emerging modalities that collapse development timelines but impose novel supply constraints.
- Inactivated Vaccines:Viral particles chemically or physically rendered non-replicative while preserving immunogenic surface epitopes. Demand concentrates in India's domestic immunization program as Serum Institute of India scales alum-adjuvanted hepatitis B and rabies formulations for WHO prequalification.
- mRNA Vaccines:Lipid nanoparticle-encapsulated nucleic acid constructs encoding viral antigens synthesized through cell-free enzymatic transcription. Procurement preference in the United States and Germany favors platform standardization for pandemic stockpile replenishment, though ionizable lipid supply concentration creates dose-scale vulnerability.
- Live Attenuated Vaccines:Cold-adapted or serially passaged viral strains with reduced pathogenicity retained in pediatric combination schedules.
- Subunit Vaccines:Purified recombinant proteins or virus-like particles produced in yeast or insect cell culture systems.
Inactivated vaccines retain volume leadership; mRNA vaccines hold the steepest expansion curve.
End User:
Procurement authority concentration and reimbursement pathways segment the customer base into volume-driven national programs versus margin-preserving private channels.
- Hospitals:Integrated health systems managing inpatient and emergency department immunization for high-risk populations. Brazil's SUS network and Thailand's Ministry of Public Health hospitals negotiate direct procurement contracts, bypassing distributor markups for influenza and pneumococcal doses.
- Clinics:Outpatient facilities delivering routine pediatric and adult immunization. Demand concentrates in Vietnam's commune health stations and Mexico's IMSS clinics where cold-chain infrastructure gaps favor thermostable live attenuated products over mRNA alternatives.
- Research Laboratories:Academic and government institutions conducting Phase I/II clinical trials.
- Pharmacies:Retail channels capturing private-pay seasonal influenza and travel vaccine demand.
Hospitals command the largest procurement volumes; clinics show the most rapid channel expansion.
Administration Route:
Delivery technology differentiation determines last-mile distribution economics and health worker training requirements across immunization programs.
- Intramuscular:Deep deltoid or vastus lateralis injection requiring sterile needle-syringe units. Demand concentrates in Gavi-eligible countries where auto-disable syringe bundling with multi-dose vials reduces waste and improves safety profiles.
- Oral:Live attenuated viral formulations delivered through enteric-coated capsules or liquid suspensions. India's Universal Immunization Program prioritizes oral polio and rotavirus delivery for community health worker deployment in Bihar and Uttar Pradesh.
- Subcutaneous:Shallow injection into adipose tissue for certain live viral vaccines.
- Intranasal:Mucosal spray delivery inducing local IgA responses.
Intramuscular delivery dominates dose volumes; oral administration gains share fastest in resource-limited settings.
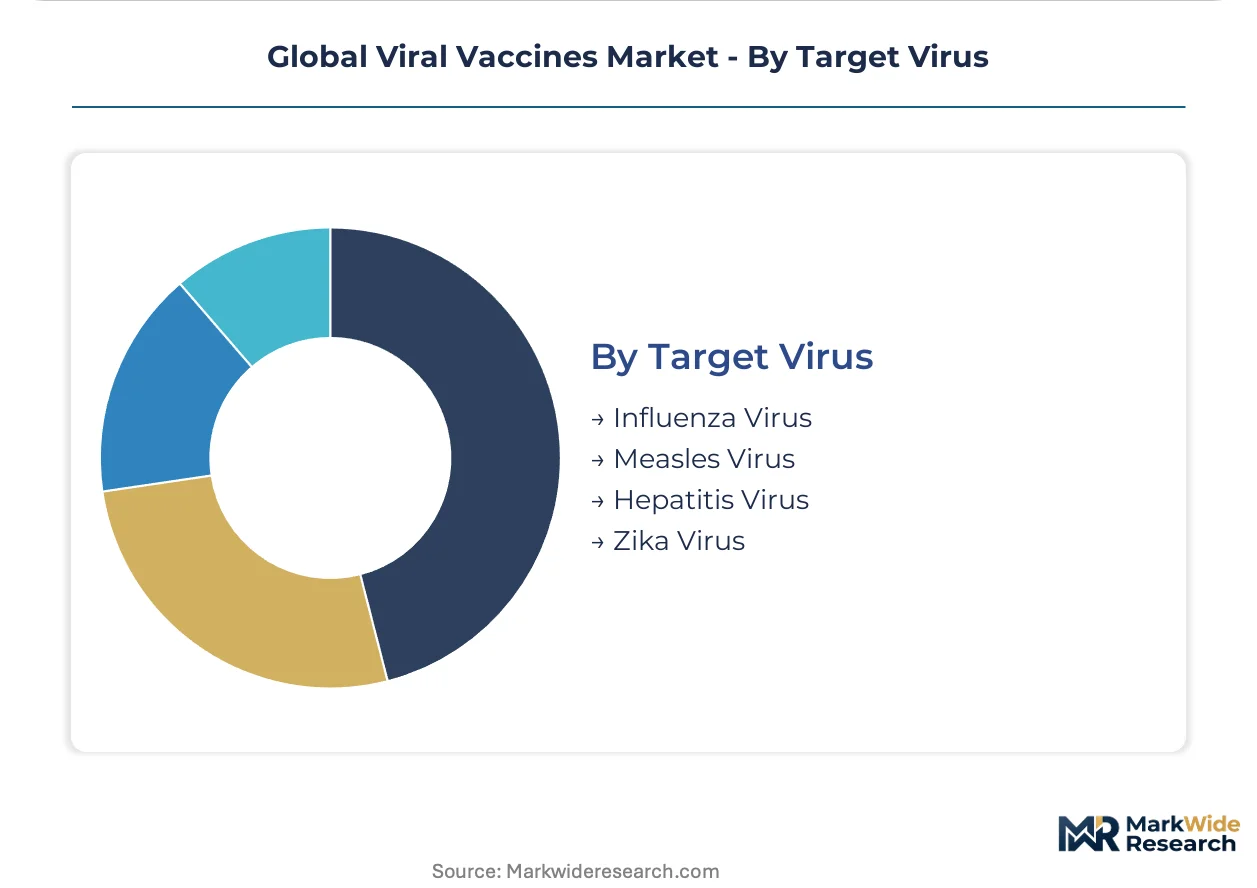
Target Virus:
Disease burden variation and eradication campaign status create divergent market maturity profiles across pathogen-specific indications.
- Influenza Virus:Seasonal trivalent and quadrivalent formulations requiring annual strain selection and manufacturing campaign restart. Demand concentrates in the United States where CDC contract volumes and pharmacy channel expansion sustain manufacturer commitment despite antigenic drift uncertainty.
- Hepatitis Virus:Recombinant surface antigen vaccines with mature, stable procurement through UNICEF and PAHO for birth-dose administration. Brazil's expanded immunization schedule added hepatitis A to hepatitis B combination products, extending manufacturer commitment to Latin American fill-finish capacity.
- Measles Virus:Live attenuated component of combination pediatric schedules with elimination campaign targets.
- Zika Virus:Emerging indication with suspended Phase II trials and uncertain commercialization pathway.
Hepatitis vaccines anchor procurement stability; influenza platforms face the most volatile demand fluctuations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridor underwrites Europe's vaccine distribution hub status, connecting North Sea shipping lanes to continental rail networks that reach immunization programs across 40 countries within 72 hours.
United States
BARDA stockpile replenishment contracts and CDC pediatric purchasing programs drive procurement volumes. The FDA's breakthrough therapy designation compresses Phase II-to-III timelines for pandemic preparedness candidates. Greater Boston's biotech cluster concentrates mRNA platform development, with Cambridge-based developers attracting talent from pharmaceutical incumbents.
Germany
Federal Ministry of Health pandemic preparedness funding and BioNTech's manufacturing expansion anchor domestic demand. The EMA's PRIME scheme accelerates assessment timelines for emerging infectious disease vaccines. The Rhine-Main region's fill-finish infrastructure scales to serve UNICEF tender volumes, redirecting dose flows from Western European contract manufacturers.
India
Universal Immunization Program expansion and Serum Institute of India's WHO prequalification pursuit drive volume growth. CDSCO's streamlined approval pathways for vaccines manufactured in pre-qualified facilities reduce time-to-market for export-bound products. Pune's vaccine manufacturing corridor scales aseptic filling capacity to capture Gavi-eligible market share.
Brazil
Ministry of Health direct procurement centralization and expanded hexavalent pediatric schedules reshape purchasing patterns. ANVISA's accelerated review pathways for WHO-prequalified products compress registration timelines. São Paulo's Butantan Institute anchors domestic manufacturing partnerships that bypass PAHO Revolving Fund intermediaries.
China
National Immunization Program expansion into second-tier cities and domestic mRNA platform development investments concentrate procurement authority. NMPA's conditional approval pathways for urgently needed vaccines compress clinical data requirements. Suzhou's biotech park attracts fill-finish joint ventures that target Southeast Asian export markets.
Global Viral Vaccines Market Competitive Landscape
On the supply side, the industry is consolidating around platform-specialized developers with differentiated manufacturing capabilities and regulatory expertise. Large-cap pharmaceutical incumbents leverage cold-chain infrastructure and pre-qualified facility networks to sustain tender relationships across multiple continents. Mid-cap biotech specialists anchor positions through modality-specific expertise in mRNA or adjuvant technologies. The dominant competitive moves involve strategic partnerships for lipid nanoparticle supply security and capacity expansion into Indian and Southeast Asian fill-finish corridors.
Among US-based platform developers, Pfizer Inc. and Moderna Inc. exemplify the mRNA specialization archetype that has displaced traditional inactivated vaccine procurement preferences in high-income country pandemic stockpiles. GSK plc represents the adjuvant-differentiated incumbent tier, occupying a distinct position in combination pediatric formulations through proprietary immunostimulant technologies. These three anchors illustrate how competitive positioning now depends on manufacturing modularity and regulatory pathway expertise rather than legacy commercial infrastructure alone.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Moderna Inc. |
| Merck & Co., Inc. |
| GSK plc |
| Sanofi |
| AstraZeneca |
| Johnson & Johnson |
| CSL Seqirus |
| Novavax |
| Others |
Supply & Pricing Matrix
Pune's vaccine manufacturing corridor anchors global fill-finish capacity expansion, with Serum Institute of India and Bharat Biotech scaling aseptic lines that compress per-dose costs for Gavi-eligible procurement. This supply concentration grants Indian manufacturers pricing leverage in UNICEF tenders while Western European contract manufacturers face margin compression from redirected volume flows.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with national immunization programs negotiating multi-year supply commitments that embed price escalation caps. Pricing stratifies across WHO-prequalified, domestically registered, and investigational tiers, with certification grade commanding premium positioning. Cost compression in economy-tier pediatric combinations intensifies as Indian manufacturers capture tender volumes. Private-pay clinics in São Paulo and Bangkok show lowest price sensitivity, while Gavi-eligible programs in sub-Saharan Africa prioritize cost minimization above formulation sophistication.
Supply Chain Analysis
Lonza, Samsung Biologics, and Catalent hold dominant contract manufacturing capacity for lipid nanoparticle encapsulation and viral vector production. Supply concentrates in Switzerland, South Korea, and Singapore, with ionizable lipid production drawing from four specialized chemical suppliers. Single-source vulnerability for mRNA formulation inputs creates dose-scale risk during pandemic surge campaigns. Distribution runs through Rotterdam's cold-chain logistics corridor connecting North Sea shipping to continental rail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent scarcity in computational biology and regulatory affairs constrains pipeline velocity, with machine learning specialists commanding compensation premiums that strain mid-cap development budgets.
For Market Incumbents: Entrench platform specialization through captive ionizable lipid supply agreements and accelerated WHO prequalification timelines for Indian fill-finish joint ventures. Defend against saRNA platform displacement by licensing replication technology or acquiring microneedle patch delivery specialists. Prioritize regulatory affairs headcount expansion to manage dual-track FDA-EMA submission packages. For New Entrants and Emerging Players: Pursue combination pediatric formulation gaps in Brazil's expanded hexavalent schedule and Indonesia's direct procurement channel openings. Kenya and Vietnam community health worker programs represent most penetrable segments for room-temperature-stable delivery innovations. Anchor go-to-market strategy through Bio Farma and Butantan Institute domestic manufacturing partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adjuvant-differentiated incumbents with proven pediatric combination portfolios over first-generation mRNA platforms facing saRNA cost displacement. Long-term viability hinges on pandemic preparedness stockpile renewal cycles and emerging infectious disease platform adaptability. Monitor BARDA and CEPI funding commitment announcements as inflection indicators for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Nanoparticle Supply Security Agreement | Captive ionizable lipid sourcing insulates mRNA scale-up campaigns from single-supplier vulnerability. |
| WHO Prequalification Fast-Track | Compressed 18-24 month inspection queues unlock Gavi-eligible procurement volumes for Indian manufacturers. |
| saRNA Platform Licensing | Dose-sparing economics from replicase amplification technology defend against cost-sensitive tender loss. |
| Microneedle Patch Delivery Partnership | Room-temperature stability enables decentralized administration in Kenyan and Vietnamese community health programs. |
| Direct National Procurement Channel | Brazil Ministry of Health and Indonesia Bio Farma relationships bypass UNICEF margin leakage. |
Research Methodology
Cross-validation between regulatory submission databases and procurement tender records anchors the qualitative findings in this study. Primary interviews with vaccine development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and WHO prequalification listings. Bottom-up dose-volume modeling and top-down market sizing triangulate across analysis approaches.
Calibration against historical procurement data and announced capacity expansion timelines shapes the projection framework. Segmentation dimensions include vaccine platform type, administration route, target virus indication, and regional regulatory cluster. CAGRs derive from dose-demand modeling across pediatric expansion schedules and pandemic preparedness stockpile replenishment cycles. Immunization program budget trajectories and fill-finish capacity commissioning timelines serve as industry-specific forecast inputs.
Sensitivities concentrate around regulatory timeline delays, ionizable lipid supply disruptions, and emerging platform technology transitions. Forecasts reflect documented assumptions regarding procurement centralization trends and cold-chain infrastructure buildout rates. Quarterly review of WHO prequalification queue lengths, BARDA funding announcements, and Gavi tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Propofol Market