
 Global Chick Embryo Cell Rabies Vaccine Market | 2026-2036
Global Chick Embryo Cell Rabies Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chick Embryo Cell Rabies Vaccine Market Foresight
Purified Vero cell substrate is consolidating share against nerve tissue formulations in cost-sensitive procurement channels. Sanofi Pasteur leverages decades of chick embryo cell process mastery to sustain premium positioning in regulated markets. Serum Institute of India anchors volume supply for WHO-prequalified tenders across South Asia and Africa. GlaxoSmithKline competes through differentiated cold-chain logistics networks that extend reach into last-mile distribution.
Chick embryo cell rabies vaccine constitutes a beta-propiolactone-inactivated, purified suspension of rabies virus propagated in primary cultures of chick fibroblasts, with potency standardized at ≥2.5 IU per intramuscular dose per WHO requirements. The product serves human post-exposure prophylaxis following category II and III exposures under WHO guidelines, replacing historical nerve tissue vaccines due to superior safety profiles. Purified Chick Embryo Cell product type occupies the mature core of revenue, while Post Exposure Prophylaxis application leads volume as bite-incident reporting improves in endemic regions. Veterinary Immunization application represents the fastest-growing margin pool as companion animal vaccination mandates expand in middle-income markets.
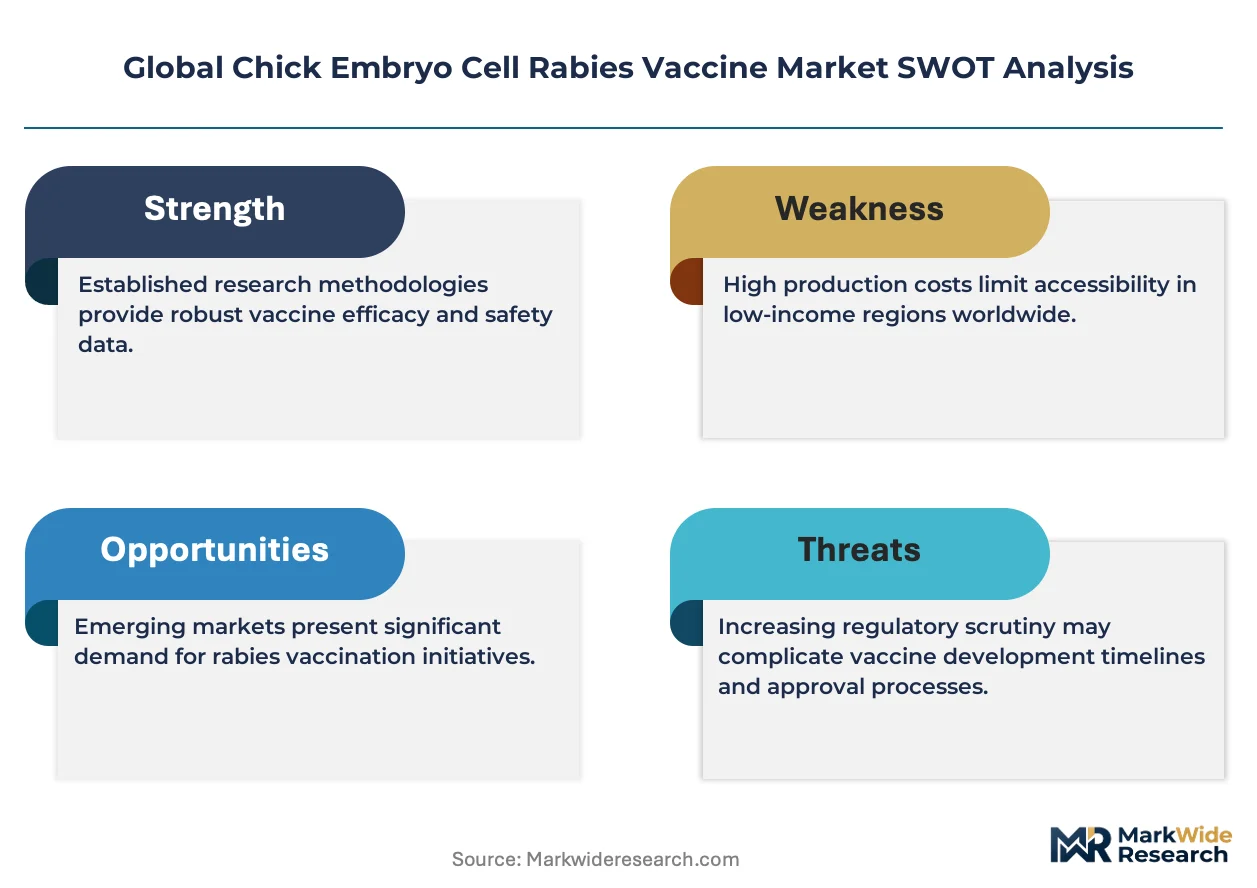
FDA biologics licensing and EMA centralized marketing authorization govern product standards for export-oriented manufacturers, while WHO prequalification shapes access to Gavi and UNICEF procurement channels. India's CDSCO and China's NMPA operate parallel national regulatory pathways that condition market entry for domestic versus imported supply. Stakeholders must monitor evolving WHO rabies elimination roadmaps and national transitions from nerve tissue to cell-culture vaccines to anticipate procurement volume shifts.
Market Dynamics
WHO prequalification standards are compressing the competitive field toward purified cell-culture vaccines, eliminating nerve tissue alternatives from public procurement channels and forcing manufacturers to absorb validation costs or exit tender participation.
Growth Catalysts
- Post-exposure prophylaxis expansion:Category II and III bite reporting protocols in endemic regions are widening the addressable patient base for chick embryo cell-derived immunization beyond traditional urban clinic networks.
- WHO prequalification pathway:Alignment with WHO standards unlocks Gavi and UNICEF procurement channels, creating volume anchors for manufacturers that complete the multi-year validation process.
- Veterinary mandate proliferation:Companion animal vaccination requirements in middle-income markets are opening parallel margin pools for human vaccine producers with transferable cell-culture platforms.
Market Restraints
- Primary chick fibroblast supply concentration:Specific pathogen-free egg sourcing depends on concentrated poultry breeding networks in the United States and Europe, exposing production to avian disease outbreak disruptions.
- Cold-chain infrastructure gaps:Last-mile distribution in tropical climates requires validated 2-8°C maintenance that exceeds regional logistics capabilities in sub-Saharan Africa and parts of South Asia.
- Vero cell substrate competition:Purified Vero cell rabies vaccines offer comparable safety profiles with established manufacturing scale, creating substitution pressure in cost-sensitive procurement evaluations.
Strategic Opportunities
- Heat-stable formulation development:Thermotolerant vaccine platforms that withstand 25°C exposure would eliminate cold-chain dependency and unlock rural distribution in India, Nigeria, and Indonesia.
- Pre-exposure prophylaxis penetration:Veterinary workers and laboratory personnel in Southeast Asia represent underpenetrated cohorts for scheduled immunization programs using chick embryo cell products.
- CDSCO accelerated approval pathway:India's streamlined review for vaccines addressing neglected tropical diseases offers faster market entry for manufacturers with existing WHO prequalification dossiers.
Industry Challenges
- Cell bank characterization complexity:Primary chick fibroblast master cell banks require extensive adventitious agent testing that extends development timelines and strains analytical capabilities.
- Multinational harmonization friction:Divergent potency testing standards between FDA biologics licensing and EMA centralized marketing authorization force redundant clinical bridging studies.
- Skilled bioprocess engineering scarcity:Aseptic primary cell culture expertise concentrates at legacy vaccine manufacturers, constraining workforce expansion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chick Embryo Cell Rabies Vaccine Market |
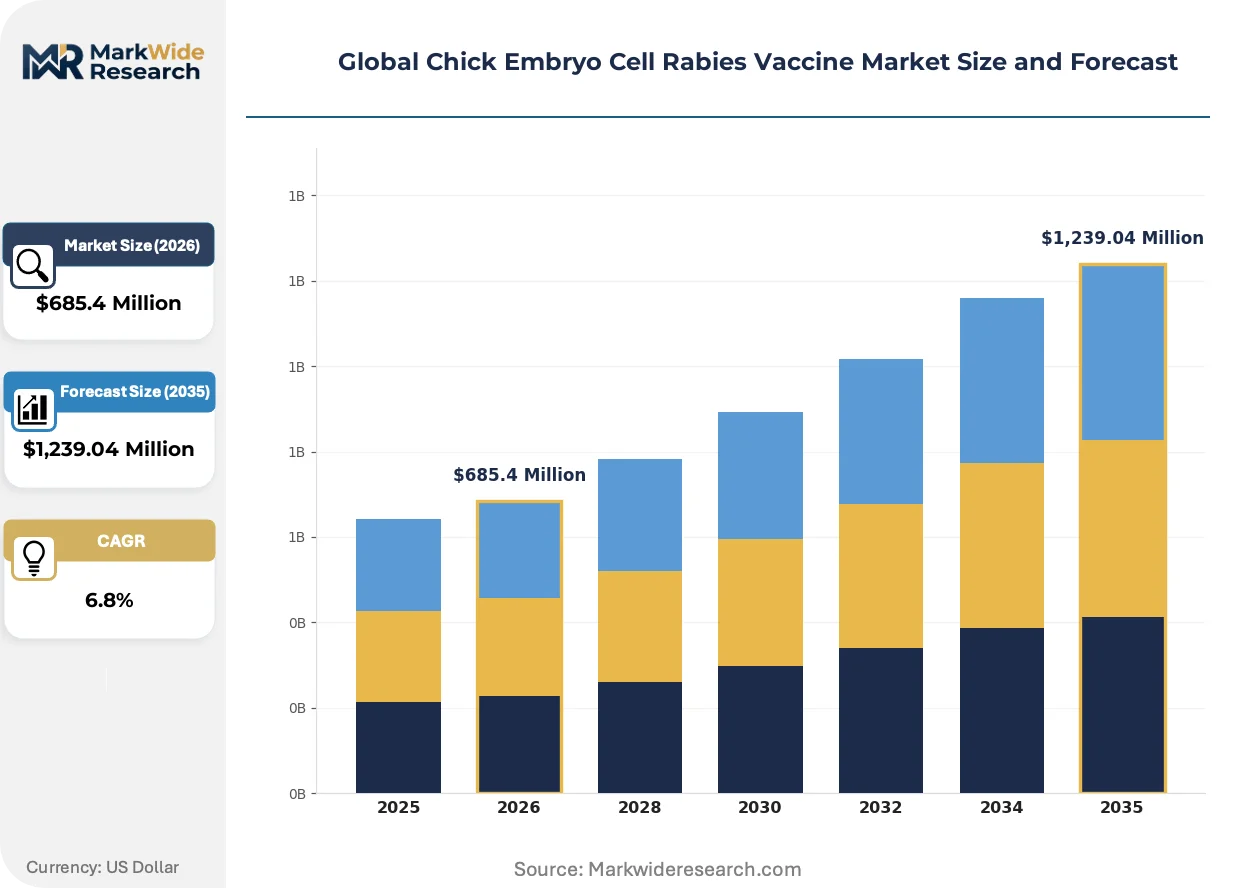
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Chick Embryo Cell, Purified Vero Cell, Human Diploid Cell, Nerve Tissue Vaccine Application: Post Exposure Prophylaxis, Pre Exposure Prophylaxis, Veterinary Immunization, Research End User: Vaccination Clinics, Veterinary Hospitals, Pharmaceutical Companies, Research Laboratories Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Government Health Centers |
| Companies Covered | Sanofi Pasteur, GlaxoSmithKline, Merck & Co., Inc., Novartis AG, Serum Institute of India, Cadila Pharmaceuticals, Berna Biotech, Chiron Behring Vaccines, IDT Biologika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chick Embryo Cell Rabies Vaccine Market Shifts & Advancements
Continuous bioprocessing and single-use technologies are compressing batch-to-batch variability while regulatory convergence around WHO standards is harmonizing quality expectations across formerly fragmented national approval pathways.
Single-use bioreactor systems are replacing stainless steel infrastructure in chick embryo cell propagation. Mid-tier manufacturers in India and Brazil are adopting this technology to reduce cross-contamination risks and accelerate facility changeover. Modular deployment is unifying quality standards across greenfield and legacy production sites, enabling faster scale-up without capital-intensive fixed-asset investment.
WHO rabies elimination roadmaps are mandating transitions from nerve tissue to cell-culture vaccines in national immunization schedules. This regulatory pressure is disqualifying historical suppliers and concentrating procurement authority at centralized tender bodies. African and Southeast Asian public health programs are responding by consolidating volume commitments to secure preferential pricing from prequalified manufacturers.
Bite-case reporting through digital surveillance platforms is compressing the window between exposure and prophylaxis initiation. Community health worker networks in India and the Philippines are replacing passive clinic-based presentation with active case detection. This behavioral shift is elevating demand for single-dose vial presentations that minimize wastage in remote dispensing settings.
Global Chick Embryo Cell Rabies Vaccine Market Segmentation
Segmentation in chick embryo cell rabies vaccines reveals how manufacturing substrate choices, prophylaxis timing, and procurement channel structures determine margin capture. Each dimension exposes different competitive bottlenecks, from primary cell sourcing constraints to cold-chain distribution economics.
Product Type:
Supply concentration in primary chick fibroblast sourcing shapes competitive positioning across substrate technologies, with specific pathogen-free egg networks creating geographic lock-in for manufacturers.
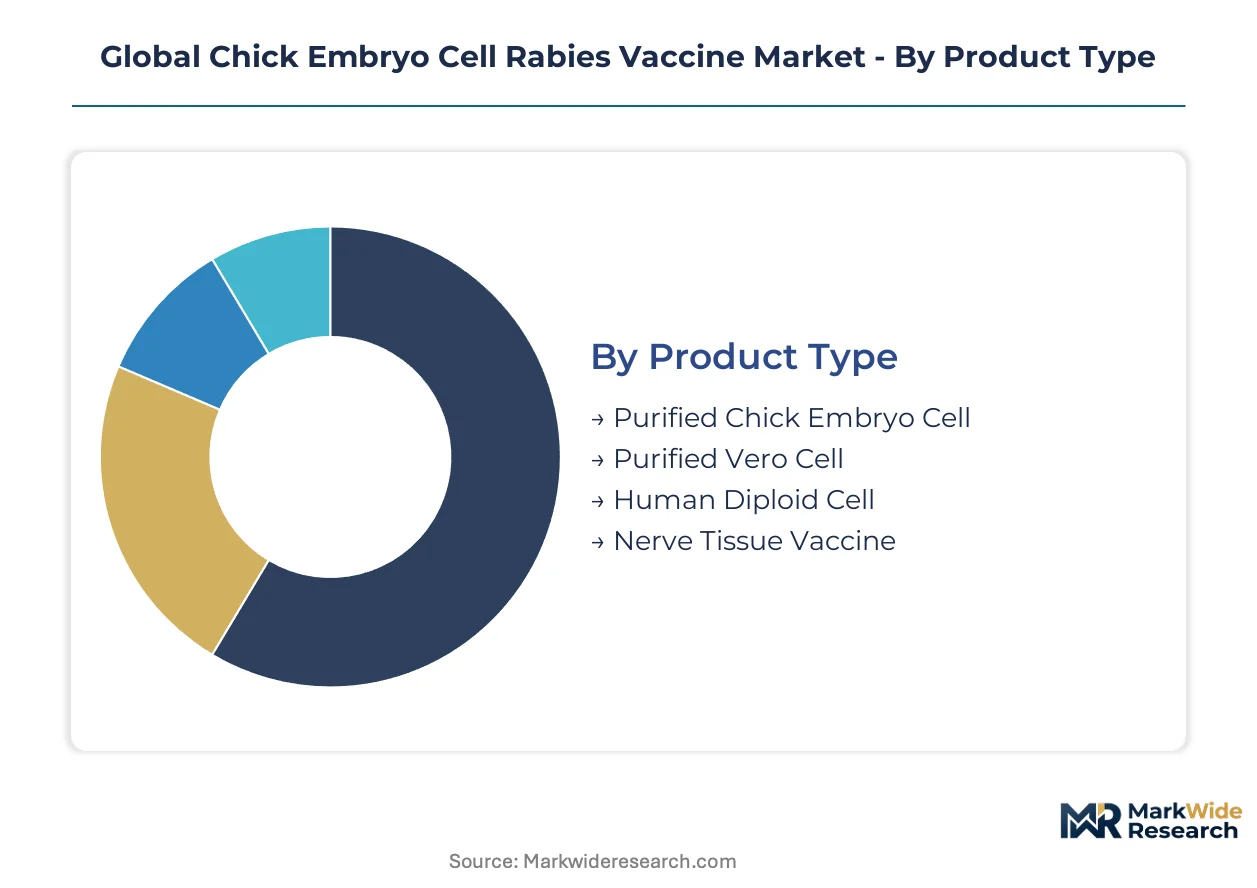
- Purified Chick Embryo Cell:Beta-propiolactone-inactivated suspension propagated in primary chick fibroblast cultures, standardized at ≥2.5 IU per intramuscular dose per WHO requirements. Public-sector tenders in India absorb the majority of global volume, driven by national transitions from nerve tissue alternatives and Serum Institute of India's WHO-prequalified supply dominance.
- Purified Vero Cell:Continuous African green monkey kidney cell substrate offering comparable safety with established manufacturing scale at legacy facilities. Procurement evaluations in cost-sensitive African markets are consolidating share toward this technology as manufacturers leverage existing Vero cell infrastructure originally built for other viral vaccines.
- Human Diploid Cell:WI-38 or MRC-5 fibroblast substrates delivering premium safety profiles for pre-exposure prophylaxis in laboratory personnel. Limited production slots and high media costs restrict availability to regulated markets with reimbursement depth.
- Nerve Tissue Vaccine:Historical sheep brain-derived formulation now eliminated from WHO-prequalified procurement channels. Remaining production serves isolated national programs with incomplete immunization schedule transitions.
Purified Chick Embryo Cell absorbs the bulk of installed capacity; Purified Vero Cell is expanding most quickly.
Application:
Cost tier differentiation separates acute post-bite intervention from scheduled pre-exposure programs, with veterinary mandates creating a parallel margin architecture.
- Post Exposure Prophylaxis:Category II and III bite-case management following WHO protocol ESSEN or Zagreb regimens. Digital surveillance platforms in India and the Philippines are compressing exposure-to-prophylaxis windows, elevating demand for single-dose vial presentations that minimize wastage in remote dispensing.
- Pre Exposure Prophylaxis:Scheduled immunization for veterinary workers, laboratory personnel, and travelers to endemic regions. Underpenetrated cohorts in Southeast Asian agricultural zones represent expansion opportunity as occupational safety regulations tighten.
- Veterinary Immunization:Companion animal and livestock rabies control using transferable cell-culture platforms. Middle-income market mandates in Brazil and Thailand are opening margin pools for human vaccine producers with cross-species manufacturing flexibility.
- Research:Viral challenge studies and immunogenicity assay development for next-generation platform evaluation. Academic and contract research organizations in the United States and Europe sustain niche demand for characterized reference materials.
Post Exposure Prophylaxis commands the dominant revenue share; Veterinary Immunization is climbing the fastest.
End User:
Customer type determines packaging, cold-chain, and regulatory documentation requirements, with public procurement channels imposing distinct compliance burdens versus private clinical settings.
- Vaccination Clinics:Primary dispensing points for bite-case management in urban and semi-urban India. Government health worker networks are replacing passive presentation with active case detection, expanding clinic throughput requirements.
- Veterinary Hospitals:Companion animal immunization sites integrating rabies control with routine veterinary services. Brazilian and Thai regulatory mandates are elevating vaccine procurement volumes through this channel.
- Pharmaceutical Companies:Bulk purchasers for repackaging, combination product development, and distribution partnerships. Cold-chain logistics capabilities differentiate supplier selection for multinational tender participation.
- Research Laboratories:Academic and commercial entities requiring characterized viral stocks for assay development. WHO reference standards and batch release documentation govern supplier qualification.
Vaccination Clinics handle the majority of patient encounters; Veterinary Hospitals are gaining share fastest.
Distribution Channel:
Geography of last-mile infrastructure determines packaging format and temperature validation requirements, with government centralized procurement creating volume anchors distinct from fragmented retail.
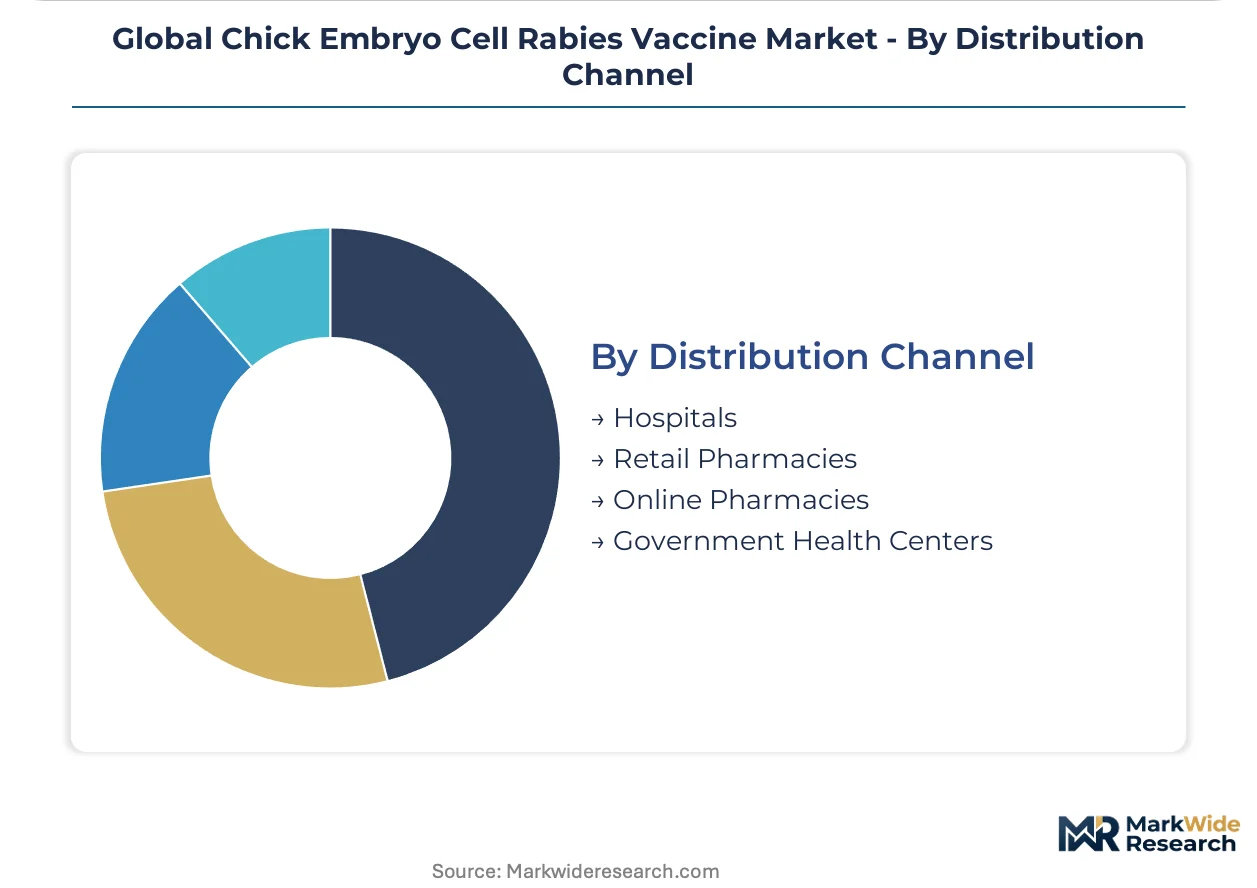
- Hospitals:Emergency department administration for severe bite cases requiring immediate wound care and immunoglobulin co-administration. Tertiary facilities in Indian states with high rabies burden anchor volume absorption.
- Retail Pharmacies:Private-market access for pre-exposure prophylaxis and completion of multi-dose regimens. Cold-chain maintenance capabilities vary, creating quality risk in tropical climates with unreliable refrigeration.
- Online Pharmacies:Emerging channel for pre-exposure prophylaxis scheduling and vaccine appointment booking. Regulatory frameworks for biologic shipment validation remain underdeveloped in most jurisdictions.
- Government Health Centers:Public-sector procurement nodes for WHO and national immunization program supply. UNICEF and Gavi tender participation requires prequalification dossiers that exclude non-compliant manufacturers.
Government Health Centers absorb the bulk of procurement volume; Online Pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs the majority of global procurement volume through Serum Institute of India's WHO-prequalified supply networks. Public-sector tenders in endemic regions are consolidating around cell-culture substrates as nerve tissue formulations face elimination from national immunization schedules.
India
Post-exposure prophylaxis programs in Maharashtra and Gujarat are driving volume absorption through government health centers. CDSCO's accelerated approval pathway for neglected tropical disease vaccines is streamlining market entry for manufacturers with existing WHO prequalification dossiers. The Serum Institute of India anchors production in Pune, supplying UNICEF and Gavi procurement channels across South Asia and Africa.
United States
FDA biologics licensing governs export-oriented manufacturing standards for primary chick fibroblast-derived vaccines. Specific pathogen-free egg sourcing concentrates in southeastern poultry breeding networks, exposing production to avian disease outbreak disruptions. Sanofi Pasteur maintains process mastery capabilities at legacy facilities serving regulated markets.
Germany
EMA centralized marketing authorization conditions access to European procurement channels for purified cell-culture vaccines. IDT Biologika represents domestic manufacturing capacity serving both human and veterinary immunization segments. The country's cold-chain logistics infrastructure supports last-mile distribution into Eastern European and Central Asian markets.
Brazil
ANVISA regulatory mandates for companion animal vaccination are expanding veterinary immunization demand beyond traditional human prophylaxis. Middle-income market procurement is consolidating toward manufacturers with transferable cell-culture platforms. São Paulo-based distribution networks are extending reach into Andean and Southern Cone markets.
China
NMPA operates parallel national regulatory pathways conditioning market entry for domestic versus imported supply. Domestic manufacturers are scaling Vero cell substrate capacity as an alternative to chick embryo cell formulations. The Yangtze River Delta clustering supports bioprocess engineering workforce development for viral vaccine production.
Global Chick Embryo Cell Rabies Vaccine Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale cell-culture infrastructure to meet WHO prequalification demands. The competitive field compresses toward purified cell-culture vaccines, eliminating nerve tissue alternatives from public procurement channels. Three archetypes define positioning: legacy multinational vaccine producers with decades of process mastery, emerging-market volume suppliers leveraging cost-advantaged production, and diversified pharmaceutical conglomerates with transferable viral vaccine platforms. Strategic partnerships with UNICEF and Gavi procurement bodies, alongside geographic expansion into African and Southeast Asian tender markets, constitute the dominant competitive moves.
Among legacy multinational producers, Sanofi Pasteur and GlaxoSmithKline exemplify archetypes differentiated by regulatory depth and distribution reach. Sanofi Pasteur occupies a position anchored in chick embryo cell process expertise accumulated across decades of regulated market supply. GlaxoSmithKline represents the diversified conglomerate archetype, leveraging cold-chain logistics networks that extend into last-mile distribution environments. Serum Institute of India sits within the emerging-market volume supplier tier, anchoring WHO-prequalified tender participation across price-sensitive procurement channels in South Asia and Africa.
| Leading Market Players |
|---|
| Sanofi Pasteur |
| GlaxoSmithKline |
| Merck & Co., Inc. |
| Novartis AG |
| Serum Institute of India |
| Cadila Pharmaceuticals |
| Berna Biotech |
| Chiron Behring Vaccines |
| IDT Biologika |
| Others |
Supply & Pricing Matrix
WHO-prequalified versus non-prequalified supply tiers bifurcate procurement economics, with validation status determining access to Gavi and UNICEF channels and reshaping both manufacturer pricing power and upstream sourcing configurations. Premium positioning attaches to FDA and EMA-authorized production, while volume absorption concentrates at Serum Institute of India's cost-optimized WHO-prequalified facilities.
Pricing Analysis
Volume absorption in public-sector tenders operates on thin margins anchored by multi-year supply agreements, while pre-exposure prophylaxis for laboratory personnel commands premium pricing in reimbursed markets. Price differentiation stems from WHO prequalification tier and cold-chain logistics bundling. Pricing pressure intensifies in African tender markets as Vero cell substitutes enter cost-sensitive evaluations. Government health centers exhibit highest price sensitivity; private vaccination clinics in regulated markets show lowest.
Supply Chain Analysis
India's domestic-content preferences under CDSCO accelerated approval pathways are redirecting component sourcing toward local specific pathogen-free egg networks and primary cell culture media suppliers. Production draws from United States poultry breeding infrastructure for master cell banks, Indian bioprocess engineering clusters for scale-up, and German cold-chain equipment for distribution integrity. Single-source vulnerability concentrates in southeastern US egg supply zones exposed to avian influenza disruption. Distribution feeds through UNICEF central procurement hubs into national immunization program cold chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification functions as a cost-of-compliance moat, with multi-year validation timelines and extensive adventitious agent testing requirements eliminating subscale competitors from Gavi and UNICEF procurement access.
For Market Incumbents: Anticipate Vero cell substitution pressure in African cost-sensitive tenders by deepening primary chick fibroblast process mastery at legacy facilities and securing captive specific pathogen-free egg supply through backward integration into US poultry breeding networks. WHO prequalification renewal cycles and emerging heat-stable formulation competition constitute primary threat vectors; vertical integration into egg supply offers defensive margin protection. For New Entrants and Emerging Players: Begin with CDSCO's accelerated approval pathway for neglected tropical disease vaccines, leveraging existing WHO prequalification dossiers to compress Indian market entry timelines. Veterinary immunization mandates in Brazil and Thailand present the most penetrable white-space, with transferable cell-culture platforms enabling cross-species manufacturing flexibility and companion animal pricing premiums. For Investors and Strategic Acquirers: Re-rating potential sits with emerging-market volume suppliers possessing WHO prequalification and transferable viral vaccine platforms, given Gavi procurement channel expansion across sub-Saharan Africa. Long-term viability over the analysis window favors manufacturers with demonstrated cold-chain logistics reach and multi-substrate manufacturing flexibility. Signal to monitor: national immunization schedule transitions from nerve tissue to cell-culture vaccines accelerating tender volume consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Completion | Unlocks Gavi and UNICEF procurement channels for volume absorption in endemic regions. |
| Heat-Stable Formulation Development | Eliminates cold-chain dependency for rural distribution in India and Nigeria. |
| Specific Pathogen-Free Egg Supply Agreement | Secures master cell bank inputs against avian disease outbreak disruption. |
| Veterinary Immunization Mandate Targeting | Captures companion animal margin pools in Brazil and Thailand regulatory frameworks. |
| CDSCO Accelerated Approval Pursuit | Compresses market entry timelines for manufacturers with existing WHO dossiers. |
Research Methodology
Multi-period observation of WHO prequalification timelines, national immunization schedule transitions, and tender award patterns anchored the trend analysis, supplemented by interviews with vaccine development executives, regulatory affairs leads at CDSCO and EMA, hospital procurement managers in Indian public health systems, and UNICEF supply division officers. Secondary validation drew from WHO prequalification listings, ClinicalTrials.gov rabies vaccine entries, CDSCO approval databases, and Gavi procurement disclosures. Bottom-up manufacturer capacity assessments and top-down public health program demand projections were triangulated.
Segment-weighting across product type, application, and distribution channel dimensions structured the analytical framework, with Purified Chick Embryo Cell, Purified Vero Cell, and nerve tissue alternatives modeled separately. Post-exposure prophylaxis, pre-exposure prophylaxis, and veterinary immunization applications carried distinct volume and margin assumptions. CAGRs were derived from logistic diffusion curves fitted to national transition timelines from nerve tissue to cell-culture vaccines. Forecast inputs incorporated bite-case reporting improvement rates and cold-chain infrastructure expansion trajectories.
Avian disease outbreaks disrupting specific pathogen-free egg supply, accelerated Vero cell substitution in cost-sensitive tenders, and delays in WHO prequalification renewal cycles are the dominant revision risks to modeled projections. Forecasts reflect assumptions about regulatory pathway stability and procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Thrombosis Drugs Market