
 Oral Thin Film Drugs Market | 2026-2036
Oral Thin Film Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Thin Film Drugs Market Analysis
The Oral Thin Film Drugs Market is restructuring around a sharp split between premium polymer-engineered films and commodity-grade oral strips. IntelGenx Corp. leverages its VersaFilm platform to dominate sublingual formulations for CNS indications. LTS Lohmann Therapie-Systeme AG anchors European supply through its toll manufacturing partnerships with Big Pharma. Pfizer Inc. competes by extending its consumer health portfolio into OTC orally disintegrating formats.
Oral thin film drugs are polymeric matrices, typically 50-500 microns thick, that dissolve on the tongue or buccal mucosa to release active pharmaceutical ingredients without water. These films employ hydroxypropyl methylcellulose or pullulan carriers with plasticizers and permeation enhancers to achieve rapid onset for molecules with poor gastrointestinal bioavailability. The sublingual delivery mode leads in revenue contribution due to its acceptance for emergency cardiovascular and addiction-therapy applications. Analgesic films represent the fastest-expanding product type as patients seek non-opioid pain management alternatives. Active pharmaceutical ingredient formulation commands the deepest margin pools because polymer compatibility and stability testing create technical barriers.
FDA bioequivalence requirements for orally disintegrating products and EMA guidelines on polymorph control in thin-film dosage forms shape clinical development timelines and capital allocation. The EU MDR and REACH compliance for polymer excipients add cost layers that favor suppliers with established regulatory dossiers. Stakeholders must monitor how pharmacopeial harmonization between USP-NF and Ph. Eur. monographs for orodispersible films affects multi-region filing strategies.
Market Dynamics
Polymer engineering capabilities are bifurcating the Oral Thin Film Drugs Market into precision-formulation specialists and commodity converters, with regulatory dossier depth becoming the primary competitive moat. FDA fast-track designations and EMA quality guidelines accelerate this split by rewarding firms with established bioequivalence data packages.
Growth Catalysts
- Pediatric formulation demand:Homecare settings for children with swallowing difficulties drive prescriptions for orodispersible formats. Caregivers prioritize water-free administration during travel and school hours.
- EMA polymorph control guidelines:Harmonized standards for thin-film stability testing reduce multi-region filing duplication. Developers consolidate clinical programs around single reference dossiers.
- Sublingual emergency cardiovascular applications:Nitroglycerin and similar APIs with poor GI bioavailability achieve rapid onset through buccal absorption. Hospital discharge protocols increasingly specify take-home film formulations.
Market Restraints
- Pullulan supply concentration:Japanese and Chinese fermentation facilities control pharmaceutical-grade raw material output. Quality variability disrupts batch consistency for Western manufacturers.
- EU MDR excipient compliance costs:REACH documentation and polymer toxicity testing add capital layers that disadvantage mid-scale entrants without dedicated regulatory affairs teams.
- Tablet and liquid substitution:Conventional orodispersible tablets compete on manufacturing cost and equipment ubiquity. Generics manufacturers favor established dosage forms with depreciated asset bases.
Strategic Opportunities
- Non-opioid analgesic films:Post-surgical pain management protocols seek NSAID and local anesthetic alternatives to oral opioids. Formulation partnerships with ambulatory surgery centers create direct distribution channels.
- India CDSCO accelerated approval pathways:Domestic manufacturers leverage priority review for essential medicines to capture regional market share before multinational entry.
- 3D printing convergence with precision dosing:Additive manufacturing enables patient-specific API loading for narrow therapeutic index compounds. Compounding pharmacies pilot personalized film production for rare disease cohorts.
Industry Challenges
- Pharmacopeial harmonization delays:Divergent USP-NF and Ph. Eur. monographs for orodispersible film thickness and dissolution testing force redundant validation studies. Filing timelines extend by quarters when agencies request method cross-walks.
- Polymer-plasticizer compatibility expertise scarcity:Formulation scientists with hydroxypropyl methylcellulose and permeation enhancer co-development experience command premium compensation. Training pipelines lag market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Thin Film Drugs Market |
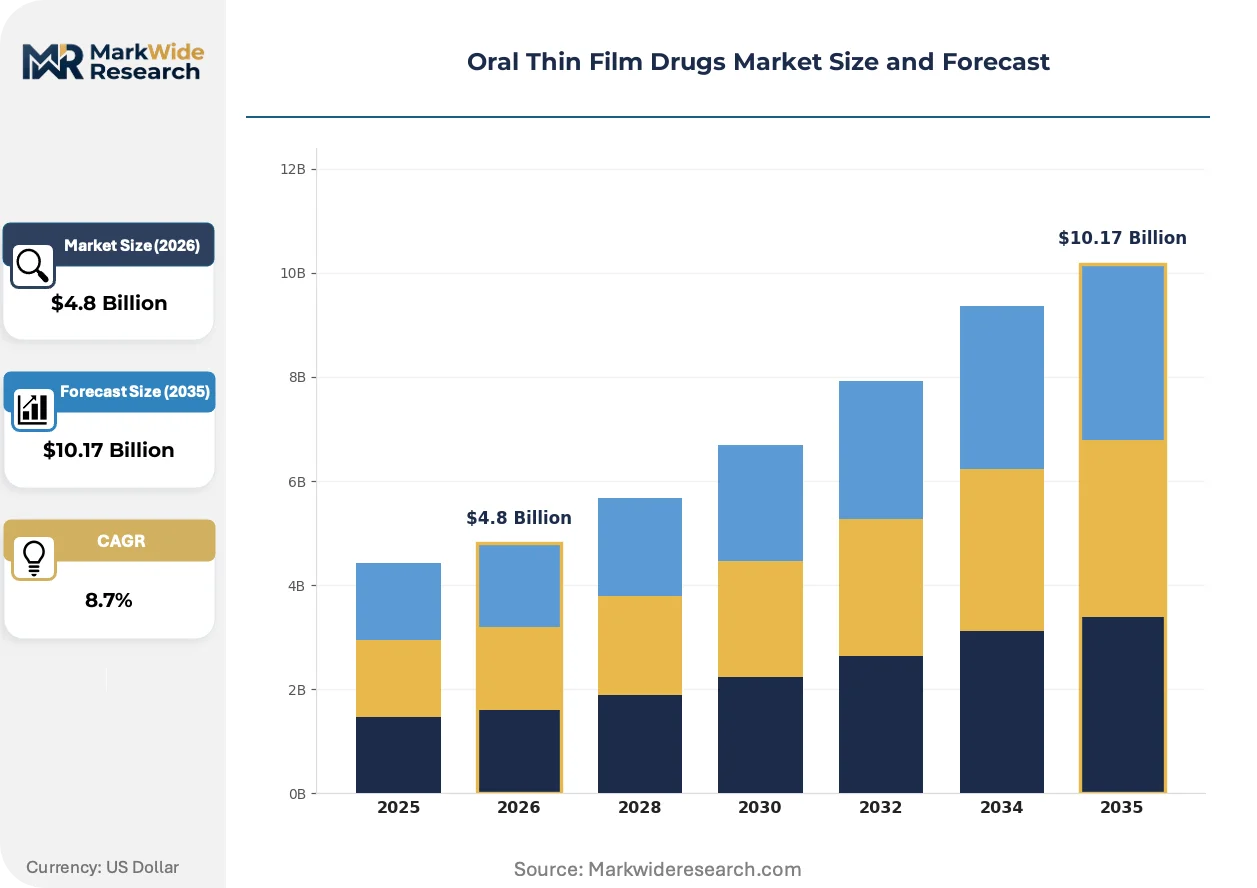
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Analgesics, Antiemetics, Vitamins Delivery Mode: Sublingual, Buccal, Transdermal, Orally Disintegrating Formulation: Active Pharmaceutical Ingredients, Sweeteners, Stabilizers, Hydrophobic Agents End User: Pharmacies, Hospitals, Clinics, Homecare Settings |
| Companies Covered | IntelGenx Corp., LTS Lohmann Therapie-Systeme AG, Pfizer Inc., CURE Pharmaceutical, Indivior Plc, Novartis AG, ZIM Laboratories Limited, Sunovion Pharmaceuticals Inc, Aquestive Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Thin Film Drugs Market Emerging Trajectories
Manufacturing precision and patient-specific delivery are displacing one-size-fits-all film formats. Three developments dominate competitive positioning: advanced polymer systems, regulatory data harmonization, and direct-to-patient distribution restructuring.
Nanostructured lipid carriers embedded in pullulan matrices are converging with conventional polymer films to enhance bioavailability of poorly soluble APIs. CNS-focused developers adopt these hybrid systems for sublingual delivery of antipsychotics and antiemetics. The technology is compressing development timelines for molecules previously abandoned due to dissolution limitations.
REACH polymer registration requirements in Europe are forcing excipient suppliers to consolidate product lines around commercially viable volumes. Manufacturers with pre-registered polymer portfolios capture toll manufacturing contracts from Big Pharma partners seeking supply security. German and Swiss contract development organizations expand capacity to serve this compliance-driven procurement concentration.
Homecare nurses and family caregivers are replacing hospital pharmacists as the primary film dispensing decision-makers. Direct distribution platforms connecting manufacturers with long-term care facilities displace wholesale intermediaries. Japan and Germany exhibit the most advanced channel restructuring, with reimbursement codes now recognizing non-institutional film administration.
Oral Thin Film Drugs Market Segmentation
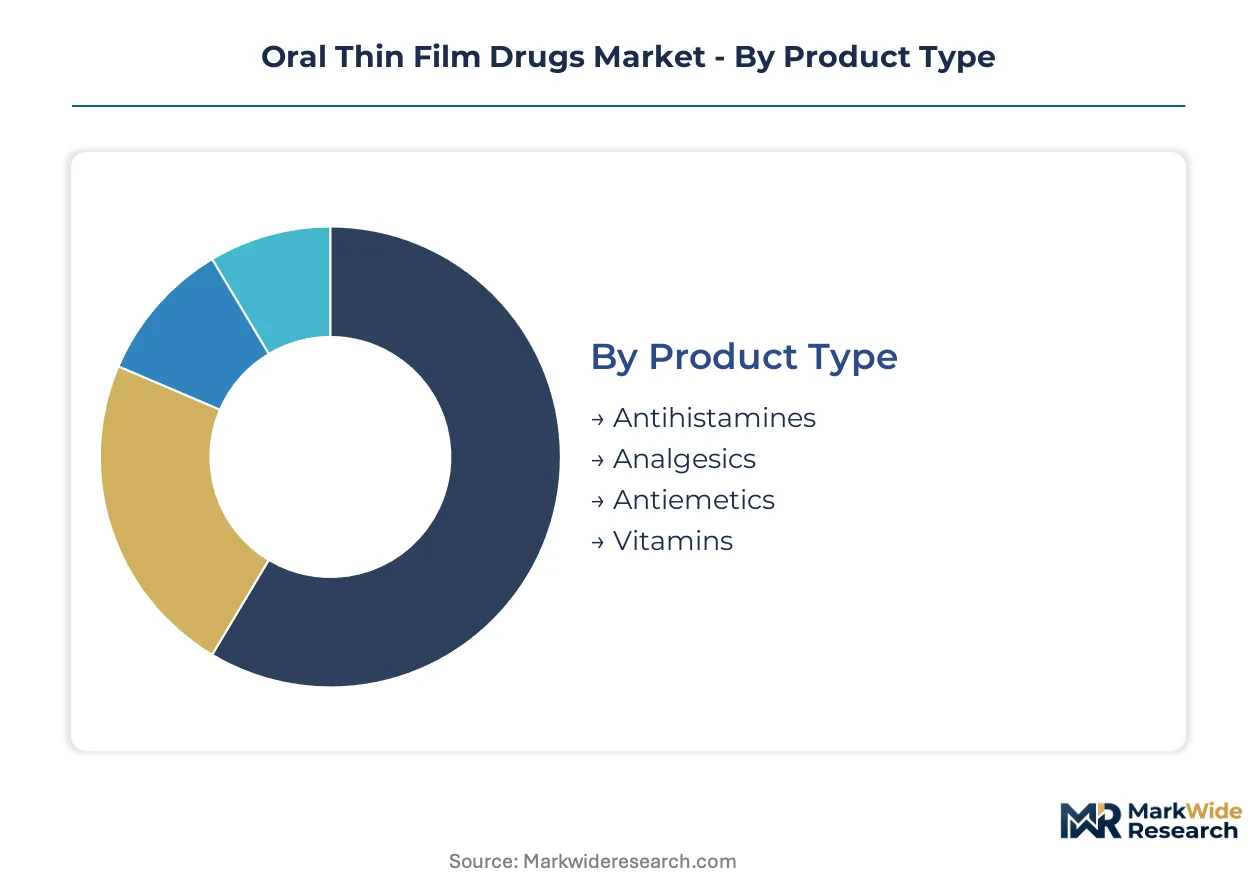
Oral thin film drugs segment across four functional dimensions that determine formulation complexity, regulatory pathway, and margin structure. Each category reflects distinct technical barriers and end-user requirements that shape competitive positioning and capital allocation decisions.
Product Type:
Antihistamine films function as standalone consumer products with minimal clinical support requirements, while analgesic and antiemetic formats embed into broader pain management and oncology protocols.
- Analgesics:NSAID and local anesthetic films incorporate permeation enhancers to accelerate buccal absorption for post-surgical pain protocols. Demand concentrates in ambulatory surgery centers across Germany and Japan where non-opioid alternatives command reimbursement premiums.
- Antiemetics:Ondansetron and similar 5-HT3 antagonist films target chemotherapy-induced nausea with rapid sublingual onset. Oncology clinics in the United States prescribe these for home-based care to reduce infusion center visits.
- Antihistamines:Cetirizine and loratadine films compete in OTC allergy segments with flavor-masked formulations for pediatric use.
- Vitamins:B-complex and vitamin D films address malabsorption in geriatric populations with swallowing difficulties.
Analgesic films lead volumes today; antiemetics are gaining share fastest.
Delivery Mode:
Cost tiers separate emergency cardiovascular applications requiring sublingual rapid onset from maintenance therapies tolerating slower buccal absorption.
- Sublingual:Nitroglycerin and buprenorphine films achieve systemic circulation within minutes through ventral tongue vascularization. Emergency departments in the United States stock these for acute angina and opioid withdrawal protocols.
- Buccal:Hormone and analgesic films adhere to the inner cheek for sustained release over 15-30 minutes. Long-term care facilities in Japan favor this mode for patients with reduced salivary flow.
- Transdermal:Migraine and motion sickness films apply to the oral mucosa with adhesive polymer backings.
- Orally Disintegrating:Antipsychotic and anti-Parkinson's films dissolve on the tongue without water for institutional dosing compliance.
Sublingual formats dominate revenue contribution; buccal applications are climbing the fastest.
Formulation:
Margin pools concentrate in active pharmaceutical ingredient compatibility testing, with excipient suppliers capturing commodity returns on sweeteners and stabilizers.
- Active Pharmaceutical Ingredients:Poorly soluble molecules require nanostructured lipid carriers or cyclodextrin complexes embedded in pullulan matrices. Formulation partnerships with Big Pharma command multi-year toll manufacturing agreements.
- Sweeteners:Aspartame and sucralose mask bitter APIs in pediatric-targeted films.
- Stabilizers:Antioxidants and chelating agents extend shelf life for oxidation-sensitive compounds.
- Hydrophobic Agents:Lipid excipients control moisture ingress in tropical distribution climates.
API formulation commands the deepest margins; stabilizer supply is expanding most quickly.
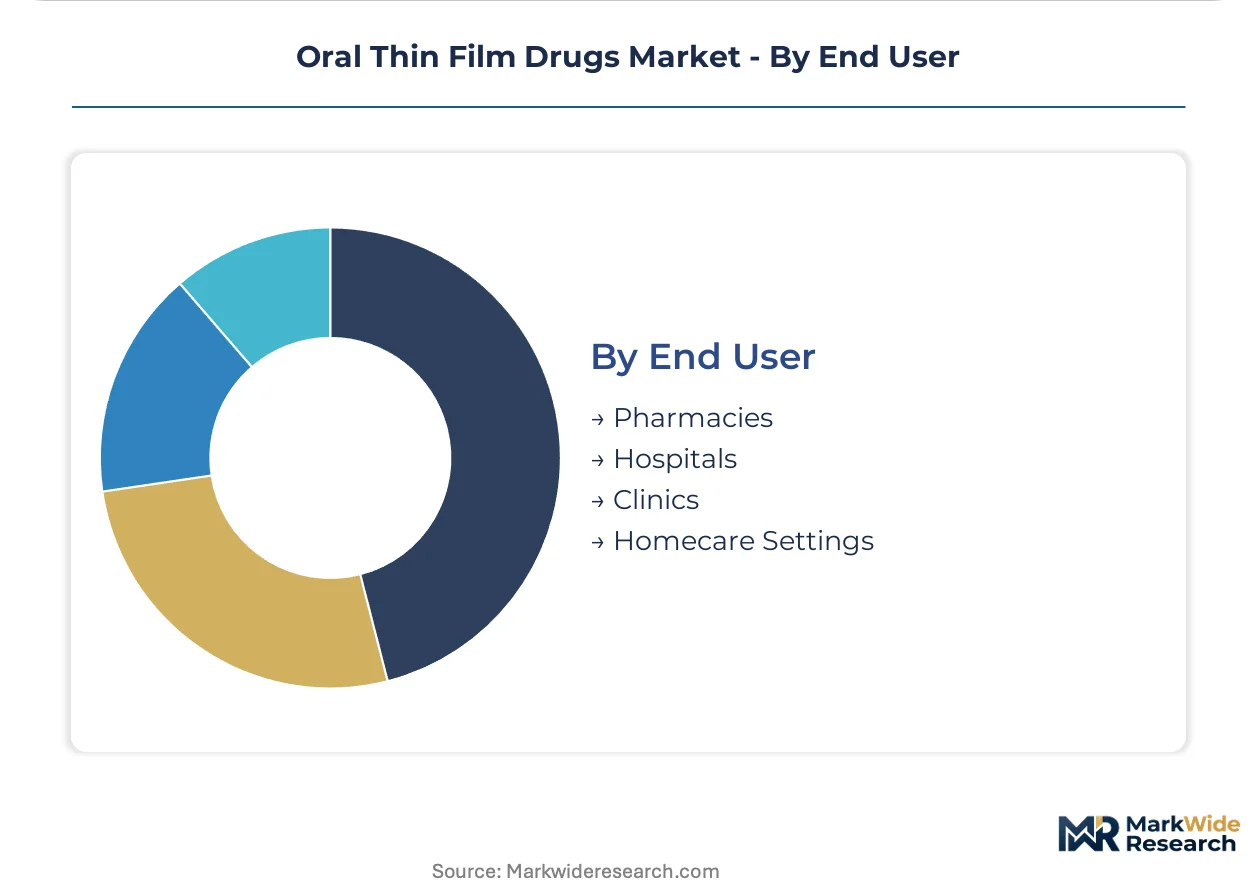
End User:
Customer type determines channel structure, with homecare settings driving direct-to-patient distribution models that bypass wholesale intermediaries.
- Homecare Settings:Family caregivers and visiting nurses administer films for pediatric swallowing disorders and geriatric polypharmacy. Reimbursement codes in Germany and Japan now recognize non-institutional film administration.
- Pharmacies:Retail chains stock OTC antihistamine and vitamin films alongside prescription sublingual formats.
- Hospitals:Emergency departments and oncology units maintain film inventories for rapid administration protocols.
- Clinics:Ambulatory surgery centers prescribe take-home analgesic films as part of enhanced recovery after surgery pathways.
Homecare settings lead volume growth today; hospital procurement is consolidating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's reimbursement infrastructure for non-invasive drug delivery outpaces Japan's regulatory velocity, yet both markets concentrate manufacturing investment more densely than emerging economies.
United States
Emergency cardiovascular protocols and addiction therapy applications drive sublingual film prescriptions through hospital discharge programs. FDA fast-track designations for orally disintegrating products compress clinical development timelines for CNS indications. New Jersey and North Carolina host contract manufacturing clusters serving Big Pharma toll agreements.
Germany
Long-term care facilities prioritize buccal administration modes for geriatric patients with reduced salivary flow. EMA polymorph control guidelines standardize stability testing requirements across EU member states. Bavaria and Baden-Württemberg concentrate polymer engineering specialists and CDMO capacity for European supply.
Japan
Pediatric swallowing disorders and geriatric polypharmacy sustain homecare film demand through visiting nurse networks. PMDA quality guidelines for orodispersible films align with international pharmacopeial standards. Tokyo-Osaka corridor fermentation facilities supply pharmaceutical-grade pullulan to Western manufacturers.
India
Domestic manufacturers exploit CDSCO accelerated approval pathways for essential medicines before multinational market entry. BIS standards for polymer excipients create compliance benchmarks for export-oriented production. Maharashtra and Gujarat house formulation development centers targeting regional price-sensitive segments.
Switzerland
Precision polymer engineering capabilities attract toll manufacturing contracts from global pharmaceutical partners. Swissmedic harmonization with EMA guidelines reduces duplicate filing burdens for multi-region dossiers. Basel-Zurich corridor hosts excipient suppliers with pre-registered REACH portfolios.
Oral Thin Film Drugs Market Vendor Landscape
Top-tier vendors anchor polymer-engineered film platforms, while commodity-grade converters compete on manufacturing scale and regulatory dossier depth. The market structures around precision-formulation specialists with established bioequivalence data packages and toll manufacturing partners serving Big Pharma supply security needs. Strategic archetypes include platform technology licensors, regional CDMOs, and consumer health portfolio extenders. Capacity expansion and regulatory dossier consolidation represent the dominant competitive moves as REACH compliance costs reshape procurement concentration.
Within the platform technology tier, IntelGenx Corp. and Aquestive Therapeutics Inc. exemplify sublingual formulation specialists leveraging proprietary film architectures. LTS Lohmann Therapie-Systeme AG occupies a position among European toll manufacturers anchoring supply partnerships through polymer engineering capabilities. Pfizer Inc. represents the consumer health extension archetype, converting OTC portfolios into orally disintegrating formats.
| Leading Market Players |
|---|
| IntelGenx Corp. |
| LTS Lohmann Therapie-Systeme AG |
| Pfizer Inc. |
| CURE Pharmaceutical |
| Indivior Plc |
| Novartis AG |
| ZIM Laboratories Limited |
| Sunovion Pharmaceuticals Inc |
| Aquestive Therapeutics Inc. |
| Others |
Supply Flow & Price Mechanics
Homecare reimbursement codes in Germany and Japan mandating non-institutional film administration are forcing manufacturers to reconfigure distribution networks toward direct-to-patient channels, compressing margin structures for wholesale-dependent suppliers while rewarding vertically integrated platforms with regulatory dossier depth.
Pricing Analysis
Capacity additions in India and Switzerland are reshaping price floors for commodity-grade polymer films. Three-tier pricing structure across premium engineered films, standard toll-manufactured formats, and economy oral strips dominates transaction structures. Price differentiation rests on FDA bioequivalence certification tier and polymer engineering complexity. Cost compression in standard-grade films is intensifying because REACH compliance documentation advantages incumbent suppliers with pre-registered portfolios. Generic pharmaceutical manufacturers exhibit highest price sensitivity; CNS-focused specialty developers show lowest.
Supply Chain Analysis
Regional distribution centers in Bavaria, Tokyo-Osaka corridor, and New Jersey anchor hub-and-spoke patterns for pharmaceutical-grade pullulan and hydroxypropyl methylcellulose. Geographic supply concentrates in Japan, China, and Germany. Raw material dependencies draw from fermentation-derived pullulan, cellulose ether derivatives, and permeation enhancer compounds. Single-source vulnerability around Japanese pharmaceutical-grade pullulan output presents structural risk. Distribution runs through toll manufacturing partnerships linking polymer engineers to Big Pharma supply security programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA fast-track designations for orally disintegrating products and EMA polymorph control guidelines continuously expand addressable demand through accelerated approval pathways.
For Market Incumbents: Deploy polymer-plasticizer compatibility expertise as a defensive moat against commodity converters. Consolidate regulatory dossier depth around REACH-registered excipient portfolios to capture toll manufacturing contracts from supply-security-seeking pharmaceutical partners. Capacity expansion in German and Swiss CDMO clusters reinforces position against mid-scale entrants lacking dedicated regulatory affairs infrastructure. For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for domestic manufacturers to capture regional market share before multinational entry. Target ambulatory surgery center partnerships for non-opioid analgesic films as the most penetrable segment. Prioritize 3D printing convergence with precision dosing for rare disease compounding pharmacy channels as the lead go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-formulation specialists possessing established bioequivalence data packages and sublingual platform technologies. Five-to-ten-year viability favors toll manufacturing partners with polymer engineering capabilities over commodity-grade converters. Signal to watch: pharmacopeial harmonization progress between USP-NF and Ph. Eur. monographs for orodispersible films as inflection indicator for multi-region filing scalability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Polymer Portfolio Registration | Pre-registered excipient suppliers capture toll manufacturing contracts from Big Pharma partners seeking supply security. |
| Sublingual Platform Technology Licensing | CNS-focused developers leverage proprietary film architectures to secure multi-year formulation partnerships. |
| Direct-to-Patient Distribution Restructuring | Manufacturers bypass wholesale intermediaries by connecting directly with long-term care facilities in Germany and Japan. |
| Nanostructured Lipid Carrier Integration | Hybrid systems enhance bioavailability of poorly soluble APIs, compressing development timelines for abandoned molecules. |
| CDSCO Accelerated Approval Pathway Exploitation | Domestic Indian manufacturers leverage priority review for essential medicines to establish regional market presence. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each market cluster combining interviews with formulation scientists, regulatory affairs leads, contract manufacturing executives, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and pharmacopeial monograph databases. Bottom-up patient population modeling and top-down pharmaceutical spending triangulation anchor demand estimation.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, delivery mode, formulation complexity, and end-user channel structure. CNS indication penetration rates, pediatric swallowing disorder prevalence, and geriatric polypharmacy intensity inform patient-based forecasting. Supply-side capacity utilization at German and Japanese polymer engineering facilities and REACH registration status of excipient portfolios inform production-constrained growth ceilings.
Revisions become necessary when pharmacopeial harmonization delays extend filing timelines, pullulan supply concentration triggers quality variability disruptions, or EU MDR excipient compliance costs accelerate procurement consolidation beyond modeled rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Propofol Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Opioid Induced Constipation Drug Market