
 Global Divalproex Sodium Market | 2026-2036
Global Divalproex Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Divalproex Sodium Market Foresight
Software-defined formulation monitoring is repositioning how pharmaceutical companies contract for divalproex sodium production. Dr. Reddy's Laboratories leverages its integrated API-to-finished-dosage infrastructure to control cost structures across extended-release and delayed-release portfolios. Aurobindo Pharma anchors its competitive stance through high-volume manufacturing of immediate-release tablets for institutional buyers in North America and Europe. Teva Pharmaceutical Industries sustains market presence via specialty distribution relationships with neurology centers and hospital pharmacy networks.
Divalproex sodium is a stable coordination compound of valproic acid and sodium valproate, typically formulated as a 1:1 molar ratio salt with controlled-release polymer matrices to achieve steady plasma concentrations over 12-24 hours. The compound functions primarily as a mood stabilizer and antiepileptic agent, with its efficacy tied to gamma-aminobutyric acid transaminase inhibition and voltage-gated sodium channel blockade. Extended-release formulations command the strongest margin pools due to formulation complexity and patent-protected delivery technologies, while immediate-release tablets dominate volume through generic substitution policies. Epilepsy applications lead therapy area demand, though bipolar disorder prescriptions are expanding fastest in specialty clinic settings where lithium intolerance drives therapeutic switching.
The FDA enforces bioequivalence protocols under 21 CFR 320 that require narrow therapeutic index demonstration for generic divalproex sodium approvals, elevating development costs for ANDA sponsors. The EMA's revised guideline on clinical investigation of medicinal products in epilepsy demands seizure-free interval documentation that shapes trial design for new entrants seeking European market access. India's CDSCO aligns with ICH Q1A stability testing standards that manufacturers must satisfy before export registration. Stakeholders should monitor how pharmacovigilance database expansions in the United States and European Union reshape post-market surveillance obligations and liability exposure for generic producers.
Market Dynamics
FDA bioequivalence protocols under 21 CFR 320 are forcing ANDA sponsors into costly pharmacokinetic studies that reshape competitive entry economics across generic divalproex sodium portfolios.
Growth Catalysts
- Extended-release polymer matrices:Controlled-release technologies enable 12-24 hour plasma concentration maintenance, expanding prescriber preference in neurology centers for epilepsy management.
- India's CDSCO export registration alignment:ICH Q1A stability testing standardization accelerates ANDA filing velocity for contract research organizations supporting complex generic development.
- Bipolar disorder therapeutic switching:Lithium intolerance in specialty clinic settings drives demand acceleration for mood stabilizer alternatives with established antiepileptic profiles.
Market Restraints
- Narrow therapeutic index demonstration costs:FDA-mandated bioequivalence studies for generic anticonvulsants elevate development expenditure beyond small-molecule generic norms.
- API supply concentration:Active pharmaceutical ingredient production clusters in India's pharmaceutical manufacturing belt create geographic dependency risk for finished dosage sponsors.
- Valproic acid teratogenicity warnings:Pregnancy prevention program requirements in multiple jurisdictions constrain prescriber willingness and expand liability exposure.
Strategic Opportunities
- Pediatric epilepsy formulations:Sprinkle capsule and liquid delivery formats remain underdeveloped relative to adult tablet markets, presenting formulation differentiation space.
- EMA seizure-free interval documentation:Revised clinical investigation guidelines for epilepsy products create trial design specialization services for European market entrants.
- Software-defined formulation monitoring:Real-time dissolution tracking and predictive stability modeling converge to reduce batch failure rates and accelerate scale-up timelines.
Industry Challenges
- Pharmacovigilance database expansion:Post-market surveillance obligations in the United States and European Union require dedicated adverse event reporting infrastructure that strains mid-cap generic producers.
- Complex generic characterization:ANDA sponsors face analytical method development hurdles for demonstrating bioequivalence of delayed-release and extended-release formulations with proprietary polymer matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Divalproex Sodium Market |
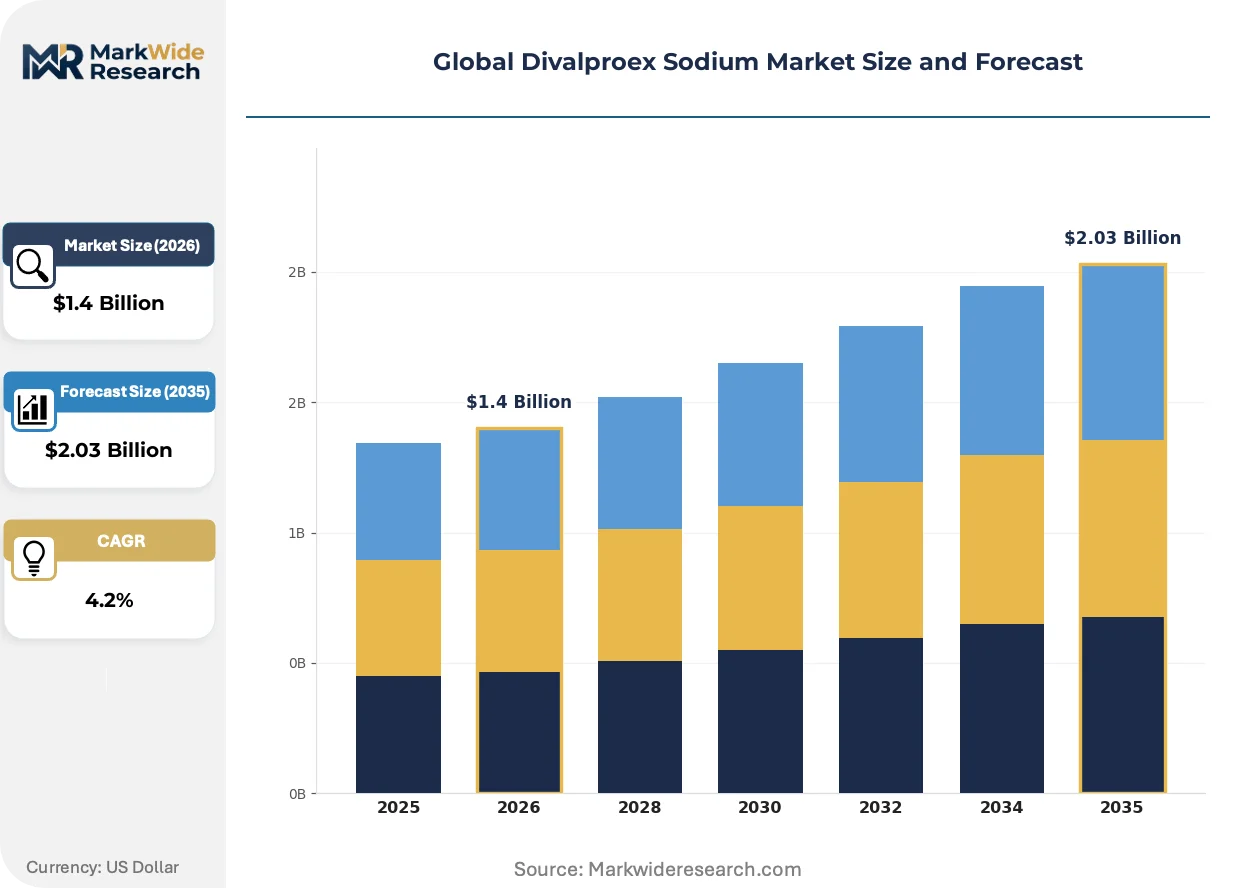
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extended-Release, Delayed-Release, Immediate-Release, Oral Suspension, Tablets Therapy Area: Epilepsy, Bipolar Disorder, Migraine Prophylaxis, Schizoaffective Disorder, Neuropathic Pain End User: Hospitals, Specialty Clinics, Mental Health Centers, Neurology Centers, Pharmacies Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesale Distributors, Direct Sales |
| Companies Covered | Dr. Reddy's Laboratories, Aurobindo Pharma, AbbVie, Lupin, Teva Pharmaceutical Industries, Mylan, Sun Pharmaceutical Industries, Orchid Pharma, Zydus Cadila, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Divalproex Sodium Market Shifts & Advancements
Formulation science and regulatory science are converging to redefine how divalproex sodium products achieve market access, with delivery technology and compliance infrastructure becoming inseparable competitive variables.
Multiparticulate bead-in-capsule systems with pH-dependent polymer coatings are electrifying extended-release development pipelines by enabling dose dumping resistance and food-effect mitigation. Neurology centers in Germany and hospital pharmacy networks in Canada are adopting these formulations for patients with erratic meal patterns. The technology is compressing development timelines for 505(b)(2) pathway entrants while raising the analytical bar for ANDA sponsors seeking substitutability designations.
EMA's revised guideline on clinical investigation of medicinal products in epilepsy mandates seizure-free interval documentation that extends trial duration requirements for new market entrants. Sponsors must now design studies capturing 12-week seizure freedom endpoints rather than simple frequency reduction metrics. European submissions for novel divalproex sodium formulations face extended development cycles, pushing resource allocation toward United States FDA filings where bioequivalence remains the primary hurdle.
Institutional procurement through integrated delivery networks is consolidating purchasing authority for antiepileptic therapies away from individual hospital pharmacies. Group purchasing organizations in the United States and tender-based hospital procurement in France are compressing price realization for immediate-release generic tablets. This concentration is most visible in North American academic medical centers where formulary exclusion decisions now rest with system-level pharmacy and therapeutics committees rather than individual prescribers.
Global Divalproex Sodium Market Segmentation
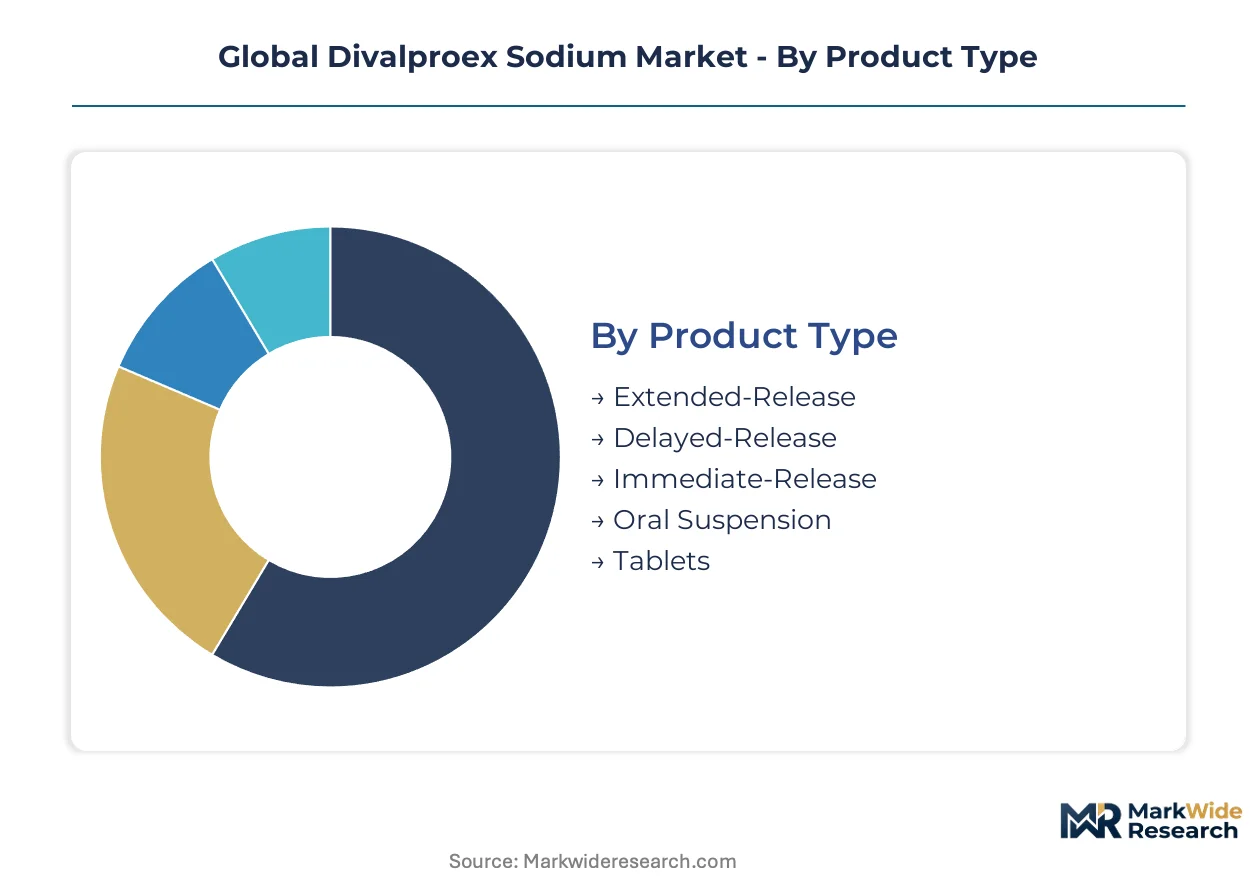
Divalproex sodium formulations vary dramatically in release kinetics, therapeutic positioning, and margin structure. Understanding how these segments split across delivery technologies, clinical applications, and procurement channels exposes where value concentrates and where generic substitution erodes returns.
Product Type:
Formulation complexity determines prescriber preference, reimbursement tiers, and the height of bioequivalence barriers facing generic entrants.
- Extended-Release:Polymer matrix systems maintain plasma concentrations across 12-24 hour intervals, commanding premium positioning in neurology centers managing refractory epilepsy. FDA's narrow therapeutic index requirements for bioequivalence create steep ANDA hurdles that protect incumbent margins.
- Delayed-Release:Enteric-coated formulations release active ingredient in the small intestine, reducing gastrointestinal adverse events that drive discontinuation in bipolar disorder patients. Demand concentrates in specialty mental health facilities where tolerability determines therapeutic persistence.
- Immediate-Release:Simple tablet formulations dominate prescription volumes through aggressive generic substitution policies at retail pharmacies.
- Oral Suspension:Liquid delivery enables dose titration flexibility for pediatric epilepsy and patients with swallowing difficulties.
- Tablets:Solid dosage forms remain the default across all release profiles, with film-coating variations differentiating manufacturer offerings.
Immediate-Release tablets lead volumes today; Extended-Release formulations are gaining share fastest in institutional procurement channels.
Therapy Area:
Clinical indication shapes dosing protocols, prescriber specialty, and the competitive intensity of therapeutic alternatives.
- Epilepsy:Anticonvulsant applications require steady-state plasma concentration maintenance, driving preference for controlled-release technologies in seizure management protocols. India's expanding neurology center network anchors volume demand for both monotherapy and adjunctive regimens.
- Bipolar Disorder:Mood stabilization represents the fastest-expanding prescription category as lithium intolerance prompts therapeutic switching in specialty psychiatric clinics. EMA's seizure-free interval documentation requirements for epilepsy trials indirectly advantage divalproex sodium's established bipolar indication.
- Migraine Prophylaxis:Preventive therapy positioning competes with beta-blockers and anticonvulsants in headache specialist practices.
- Schizoaffective Disorder:Adjunctive use in combined mood and psychotic symptom management occupies a narrower prescriber niche.
- Neuropathic Pain:Off-label utilization in diabetic neuropathy and post-herpetic neuralgia varies by jurisdiction and payer policy.
Epilepsy commands the largest patient base currently; Bipolar Disorder prescriptions are climbing the fastest as diagnostic criteria broaden.
End User:
Institutional setting determines formulary control, procurement mechanics, and the sophistication of therapeutic monitoring infrastructure.
- Hospitals:Acute care settings prioritize immediate-release formulations for rapid therapeutic intervention, with pharmacy and therapeutics committees controlling vendor selection through system-level contracts.
- Specialty Clinics:Outpatient psychiatric and neurology practices drive extended-release adoption through prescriber familiarity with polymer matrix pharmacokinetics.
- Mental Health Centers:Community-based facilities balance cost containment against adherence support requirements for chronic mood disorder patients.
- Neurology Centers:Academic medical centers in Germany and Canada anchor demand for multiparticulate bead-in-capsule technologies.
- Pharmacies:Retail dispensing faces the strongest generic substitution pressure, with pharmacist-level interchange protocols eroding brand loyalty.
Hospitals process the highest prescription volumes today; Specialty Clinics are expanding most quickly as care migrates from inpatient to outpatient settings.
Distribution Channel:
Channel structure determines price realization, inventory holding patterns, and the concentration of purchasing leverage.
- Retail Pharmacies:Community dispensing faces aggressive generic substitution mandates and reimbursement compression from pharmacy benefit managers in the United States.
- Hospital Pharmacies:Integrated delivery network consolidation concentrates purchasing authority with system-level procurement committees rather than individual facilities.
- Online Pharmacies:Digital dispensing channels expand patient access in jurisdictions with supportive telehealth regulations.
- Wholesale Distributors:Three-tier distribution networks in India and the United States intermediate between manufacturers and retail endpoints.
- Direct Sales:Manufacturer-to-institution contracts serve large hospital systems and government tenders in France and Canada.
Retail Pharmacies dominate transaction volumes today; Hospital Pharmacies are capturing share fastest through integrated delivery network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical manufacturing belt generates more API tonnage for divalproex sodium than Germany's specialized neurology centers consume in finished formulations, illustrating a supply-demand asymmetry across continents.
United States
Neurology centers in Boston and Baltimore drive extended-release prescription volumes for refractory epilepsy management. FDA bioequivalence protocols under 21 CFR 320 mandate narrow therapeutic index demonstration that elevates ANDA sponsor costs. Contract research organizations in New Jersey and North Carolina support complex generic development for polymer matrix formulations.
Germany
Academic medical centers in Munich and Heidelberg anchor demand for multiparticulate bead-in-capsule technologies in epilepsy protocols. EMA revised guidelines on clinical investigation of medicinal products in epilepsy require seizure-free interval documentation extending trial durations. Hospital pharmacy networks in the North Rhine-Westphalia cluster consolidate procurement authority through regional tender systems.
India
Hyderabad and Ahmedabad house concentrated API manufacturing capacity serving global finished dosage sponsors. CDSCO alignment with ICH Q1A stability testing standards accelerates export registration timelines for contract research organizations. Maharashtra's pharmaceutical manufacturing belt generates the majority of valproic acid precursor supply for international formulation houses.
Canada
Hospital pharmacy networks in Toronto and Vancouver adopt extended-release formulations for patients with erratic meal patterns. Health Canada enforces bioequivalence standards that mirror FDA narrow therapeutic index requirements for generic anticonvulsants. Quebec's contract manufacturing sector provides analytical method development services for ANDA sponsors targeting North American markets.
Global Divalproex Sodium Market Competitive Landscape
Top-tier vendors anchor integrated API-to-finished-dosage infrastructure, while mid-cap specialists concentrate on high-volume immediate-release tablet production for institutional buyers. The vendor base stratifies across three functional tiers: backward-integrated pharmaceutical conglomerates controlling cost structures, high-volume generic manufacturers serving retail substitution markets, and specialty distribution players maintaining neurology center relationships. Dominant competitive moves include portfolio diversification across release profiles and strategic partnerships with contract research organizations for ANDA filing acceleration.
Among India-based pharmaceutical conglomerates, Dr. Reddy's Laboratories and Aurobindo Pharma exemplify contrasting archetypes within the generic divalproex sodium space. Dr. Reddy's occupies a position representing integrated infrastructure players with captive API supply, while Aurobindo sits within the high-volume manufacturing tier serving institutional procurement channels. Teva Pharmaceutical Industries, as an Israel-based specialty pharmaceutical company, anchors the distribution-relationship archetype through neurology center and hospital pharmacy network presence.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| AbbVie |
| Lupin |
| Teva Pharmaceutical Industries |
| Mylan |
| Sun Pharmaceutical Industries |
| Orchid Pharma |
| Zydus Cadila |
| Others |
Supply & Pricing Matrix
Valproic acid commodity pricing in India's pharmaceutical manufacturing belt cascades through API conversion costs into finished dosage tiering, with polymer matrix formulation premiums widening against immediate-release tablet compression as raw material volatility concentrates margin pressure on high-volume generic producers.
Pricing Analysis
Capacity additions in Hyderabad and Ahmedabad are reshaping price floors for immediate-release tablets as contract manufacturers absorb API cost swings through volume scale. Three-tier pricing structure across extended-release specialty, delayed-release standard, and immediate-release economy levels reflects formulation complexity and bioequivalence certification investment. Pricing pressure stems from integrated delivery network consolidation in the United States as hospital pharmacy committees extract volume discounts from institutional suppliers. Retail pharmacy substitution protocols render this channel most price-sensitive, while neurology center specialty procurement maintains lowest sensitivity due to therapeutic persistence requirements.
Supply Chain Analysis
Valproic acid precursor supply rests on Maharashtra's chemical synthesis clusters and Gujarat's active pharmaceutical ingredient foundries, with downstream formulation drawing from Tamil Nadu's finished dosage plants. Sodium valproate feedstock, controlled-release polymer matrices, and enteric coating materials constitute critical input dependencies. Single-source vulnerability concentrates around pH-dependent polymer coating suppliers in Western India, exposing ANDA sponsors to batch continuity risk. Distribution runs through wholesale distributor networks in the United States and direct tender contracts in European hospital systems, with Canadian group purchasing organizations consolidating regional procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory complexity, with FDA's tightened bioequivalence protocols under 21 CFR 320 driving specialized service demand that rewards compliance infrastructure investment.
For Market Incumbents: Hedge against generic substitution erosion by deepening backward integration into valproic acid precursor production and securing captive polymer matrix supply agreements. EMA's extended seizure-free interval documentation requirements for epilepsy trials threaten European market access timelines, making FDA-first filing strategies the priority lever for margin protection. Reinforce neurology center relationships through real-world evidence generation for extended-release therapeutic persistence. For New Entrants and Emerging Players: CDSCO's ICH Q1A stability testing alignment in India opens a window for contract research organization partnerships that accelerate ANDA filing velocity for complex generic entrants. Pediatric epilepsy formulations remain the most penetrable white-space target, with sprinkle capsule and liquid delivery formats underdeveloped relative to adult tablet saturation. Target specialty clinic channels in North America where lithium intolerance drives bipolar disorder therapeutic switching and prescriber familiarity with divalproex sodium pharmacokinetics supports premium positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap generic manufacturers possessing integrated API-to-finished-dosage infrastructure and established FDA inspection histories. Long-term viability in this market hinges on pharmacovigilance database readiness and adverse event reporting infrastructure that satisfies post-market surveillance expansion in the United States and European Union. Watch for ANDA approval acceleration rates for extended-release formulations as the signal indicating whether bioequivalence barriers are tightening or stabilizing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | ANDA filing acceleration through CDSCO-aligned stability testing reduces time-to-market for complex generics. |
| Manufacturing Scale-Up | Extended-release polymer matrix capacity expansion captures neurology center demand in Boston and Baltimore. |
| Pipeline Diversification | Pediatric sprinkle capsule development addresses formulation gap in epilepsy management protocols. |
| Backward Integration | Captive valproic acid production insulates margin structures from Indian API supply concentration risk. |
| Strategic Partnership | Contract research organization alliances streamline EMA seizure-free interval trial design for European access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at ANDA sponsors, formulary directors at integrated delivery networks, contract research organization executives, and hospital pharmacy procurement managers with secondary validation through FDA Orange Book filings, EMA assessment reports, ClinicalTrials.gov epilepsy trial registries, and Indian CDSCO export registration databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across the analysis window.
Historical reference periods anchored the projection horizon through segment-level growth rate extrapolation, with modeling disaggregated by release profile technology, therapy area indication, end-user institutional setting, and regional regulatory cluster. CAGRs derived from polynomial trend fitting of prescription volume trajectories and value realization patterns, incorporating divalproex sodium's narrow therapeutic index bioequivalence study costs and polymer matrix formulation complexity premiums as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA bioequivalence protocol amendments or EMA clinical investigation guideline revisions. Forecasts reflect assumptions regarding ANDA approval velocity, API supply continuity from Indian manufacturing clusters, and prescriber adherence to valproic acid teratogenicity pregnancy prevention programs. A small set of named triggers—pharmacovigilance database expansion mandates, multiparticulate bead-in-capsule technology adoption rates, and integrated delivery network procurement consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market