
 Global Subdermal Contraceptive Implants Market | 2026-2036
Global Subdermal Contraceptive Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subdermal Contraceptive Implants Market Foresight
Project finance structures for bulk procurement through multilateral health funds is tilting competitive access toward manufacturers with established prequalification records. Bayer AG leverages its WHO-prequalified manufacturing network to sustain large-volume tenders across multiple African markets. Merck & Co., Inc. anchors its position through deep vertical integration in polymer sourcing and controlled-release formulation. Organon & Co. differentiates by specializing in provider training ecosystems that lock in clinic-level loyalty.
Subdermal contraceptive implants are flexible polymer rods or capsules, typically 2-4 cm in length, inserted beneath the skin of the upper arm to release progestin at controlled rates for 3-5 years of pregnancy prevention. Their primary commercial purpose is to provide long-acting reversible contraception with minimal user adherence requirements in both developed and resource-limited settings. Single rod configurations dominate current procurement volumes due to simpler insertion protocols and lower removal complication rates. Progestin-only mechanisms lead the mechanism of action category, while government programs channel the majority of volume through centralized tender structures that compress margins but guarantee scale.
WHO prequalification, FDA 510(k) pathways, and EMA centralized marketing authorizations collectively shape product standards and market access timelines for implant manufacturers. REACH compliance in Europe and evolving EMA guidance on biodegradable polymer degradation profiles are raising technical barriers for new entrants. Stakeholders must monitor how national procurement bodies in high-volume markets calibrate quality thresholds against total cost of ownership metrics.
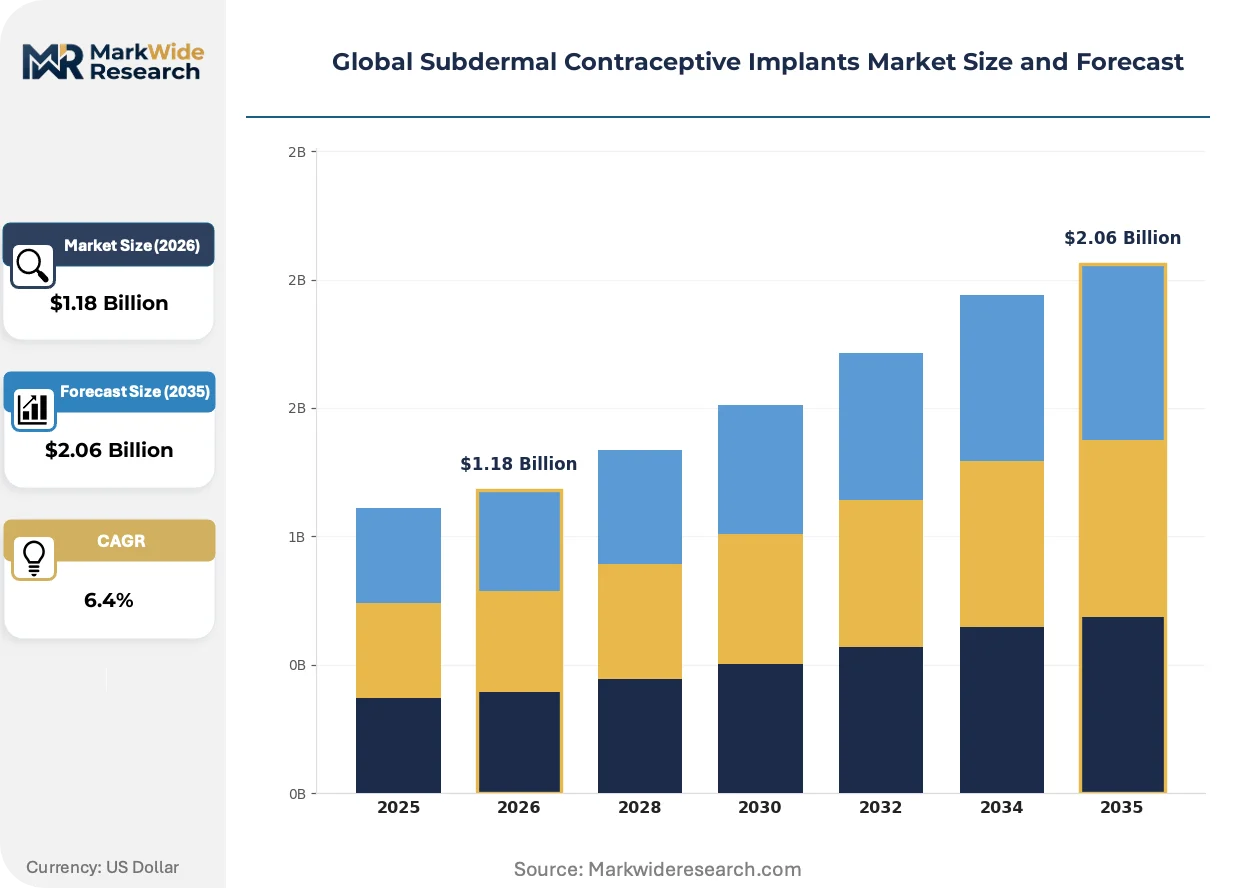
Market Dynamics
Centralized tender structures through multilateral health funds are compressing manufacturer margins while locking in multi-year procurement volumes, fundamentally restructuring competitive access toward WHO-prequalified suppliers with established cold-chain distribution networks.
Growth Catalysts
- National LARC Program Scaling:Health ministries in Nigeria, Ethiopia, and Kenya are expanding implant procurement through dedicated family planning budgets. These programs channel demand into single-rod etonogestrel configurations.
- WHO Prequalification Streamlining:Accelerated assessment pathways for generic etonogestrel implants are reducing registration timelines. This regulatory efficiency opens procurement eligibility to additional manufacturers.
- Polymer Biodegradation Advances:Next-generation ethylene vinyl acetate matrices enable more precise progestin release kinetics. These materials extend effective duration while simplifying removal protocols.
Market Restraints
- Progestin Raw Material Concentration:Active pharmaceutical ingredient synthesis concentrates among specialized contract manufacturers in India and China. Supply disruptions at these nodes propagate through finished-device production.
- Insertion Training Bottlenecks:Provider certification requirements limit clinic-level deployment velocity. Rural health facilities face persistent gaps in trained personnel for implant insertion and removal.
- Alternative Contraceptive Substitution:Intrauterine devices and depot medroxyprogesterone acetate injections compete for the same procurement budgets. These alternatives require less specialized provider training.
Strategic Opportunities
- Underpenetrated West African Markets:Ghana and Côte d'Ivoire exhibit low implant prevalence relative to unmet contraceptive need. Ministry of Health partnerships in these countries offer first-mover positioning.
- Self-Removal Technology Development:Biodegradable polymer systems eliminating surgical removal are advancing through clinical validation. These products address patient discontinuation barriers and provider capacity constraints.
- Private Pharmacy Channel Expansion:Retail pharmacy networks in urban Kenya and Nigeria are emerging as direct-to-patient access points. This channel bypasses centralized tender compression while capturing out-of-pocket expenditure.
Industry Challenges
- EMA Polymer Degradation Documentation:Updated guidance requires extensive biodegradation profile data for new implant submissions. Compliance timelines extend pre-market investment horizons.
- Cold-Chain Infrastructure Gaps:Last-mile distribution in rural Ethiopia and northern Nigeria depends on unreliable temperature-controlled logistics. Product integrity risks concentrate at these network endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subdermal Contraceptive Implants Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Rod, Two Rods, Biodegradable, Non-Biodegradable Mechanism of Action: Progestin-Only, Combination Hormone, Non-Hormonal, Immunocontraceptive End User: Family Planning Clinics, Gynecologists, Community Health Centers, Reproductive Health NGOs Distribution Channel: Pharmacies, Hospitals, Online Retail, Government Programs, Private Clinics |
| Companies Covered | Merck & Co., Inc., Bayer AG, Shanghai Dahua Pharmaceutical Co., Ltd., Organon & Co., Pfizer Inc., Gedeon Richter Plc, DKT WomanCare Global, Cipla Ltd., Celanese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subdermal Contraceptive Implants Market Shifts & Advancements
Product architecture and regulatory pathways are converging to reshape manufacturer competitive requirements, with emphasis shifting from formulation chemistry to integrated service delivery ecosystems.
Biodegradable polymer systems are migrating from experimental prototypes toward commercial feasibility. Research consortia in the Netherlands and Sweden are validating magnesium-based matrices that eliminate removal procedures entirely. These materials promise to compress total cost of ownership for health systems while expanding patient eligibility in settings with limited surgical access.
REACH compliance obligations in Europe are tightening substance restriction thresholds for implant polymer constituents. ECHA has added several phthalate plasticizers to candidate substance lists, forcing reformulation of legacy ethylene vinyl acetate blends. Manufacturers serving EU markets are accelerating migration to bio-based plasticizers ahead of 2027 sunset dates.
Demand concentration among multilateral procurement bodies is consolidating buyer power and standardizing product specifications. The Global Family Planning Supply Chain coalition now coordinates bulk purchasing across 46 countries, displacing fragmented national tender processes. This consolidation favors manufacturers with demonstrated cold-chain reliability and pharmacovigilance infrastructure in Francophone West Africa.
Global Subdermal Contraceptive Implants Market Segmentation
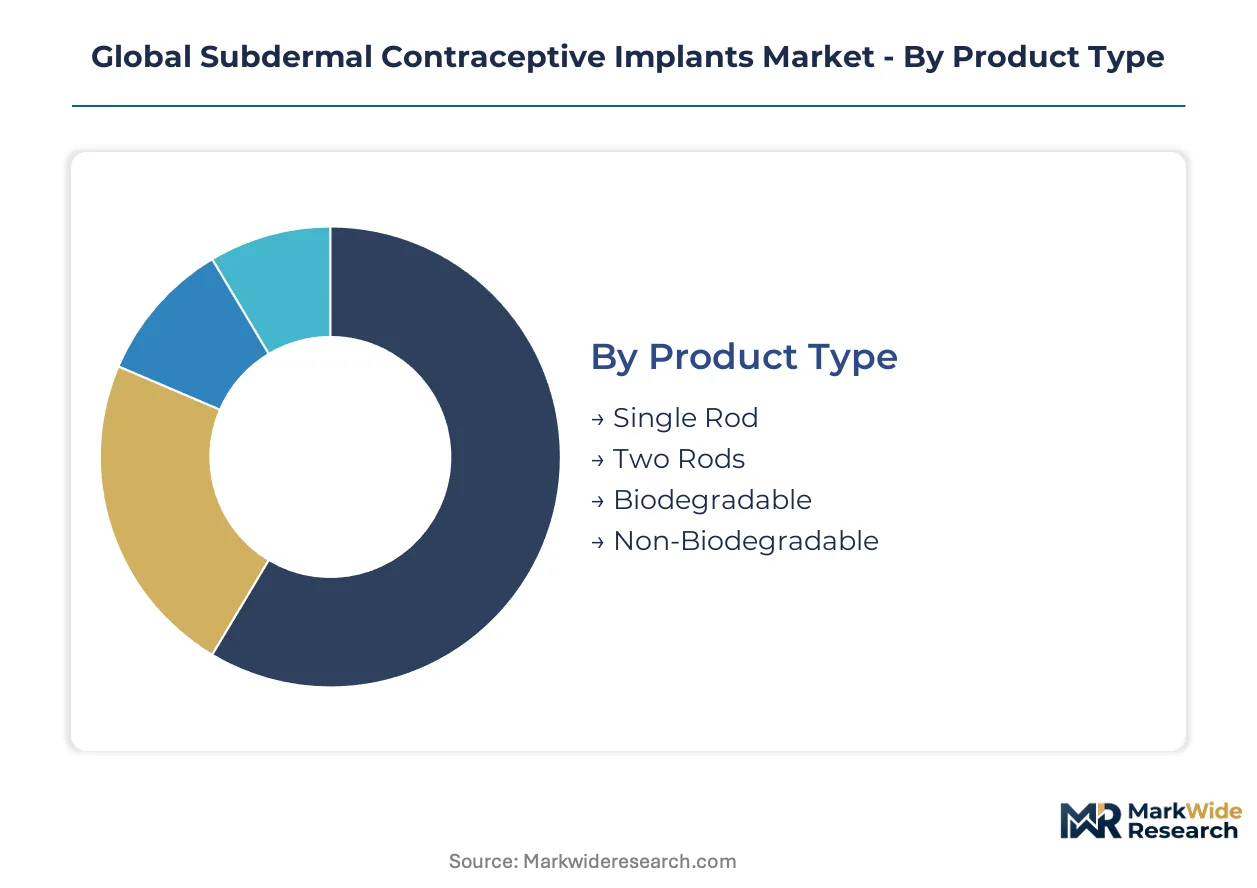
Segmentation in subdermal contraceptive implants reveals how procurement economics, clinical training requirements, and regulatory pathways fragment commercial opportunity across distinct channels and user settings.
Product Type:
After-sales service intensity varies sharply by implant architecture, with removal complexity and follow-up protocols driving provider resource allocation.
- Single Rod:Etonogestrel-releasing polymer rods measuring 2mm by 40mm dominate current procurement volumes. Family planning clinics in Nigeria and Ethiopia favor this configuration for streamlined insertion protocols and lower complication rates during removal.
- Two Rods:Levonorgestrel dual-rod systems require more extensive provider training but offer alternative hormone dosing profiles. Demand concentrates in established reproductive health programs with deeper clinical infrastructure.
- Biodegradable:Magnesium-based matrices eliminating surgical removal are advancing through clinical validation in Dutch and Swedish research consortia.
- Non-Biodegradable:Legacy ethylene vinyl acetate systems require scheduled removal procedures and dominate current government tender structures.
Single Rod holds the largest share; momentum sits with Biodegradable.
Mechanism of Action:
Cost tier stratification separates premium hormone formulations from experimental alternatives still navigating regulatory validation.
- Progestin-Only:Etonogestrel and levonorgestrel release mechanisms account for the substantial majority of implanted devices. WHO prequalification pathways have streamlined registration for generic progestin-only formulations.
- Combination Hormone:Estrogen-progestin combinations face higher thromboembolic risk profiles that limit procurement in resource-limited settings.
- Non-Hormonal:Copper-based mechanisms remain experimental for subdermal delivery and lack established clinical protocols.
- Immunocontraceptive:Vaccine-derived fertility suppression approaches are in preclinical stages with no commercial timeline.
Progestin-Only captures institutional procurement preference; Combination Hormone faces expanding clinical scrutiny.
End User:
Customer type determines pricing elasticity and contract structure, with government-funded channels compressing margins against private clinical premiums.
- Family Planning Clinics:Dedicated contraceptive access points in Kenya and Ghana anchor volume procurement through ministry of health partnerships.
- Gynecologists:Private practice specialists in urban Nigeria command premium pricing for insertion services bundled with counseling.
- Community Health Centers:Frontline facilities face persistent gaps in trained personnel for implant procedures.
- Reproductive Health NGOs:Marie Stopes International and similar organizations coordinate cross-border procurement consortia.
Family Planning Clinics anchor volume; Gynecologists capture value-added service revenue.
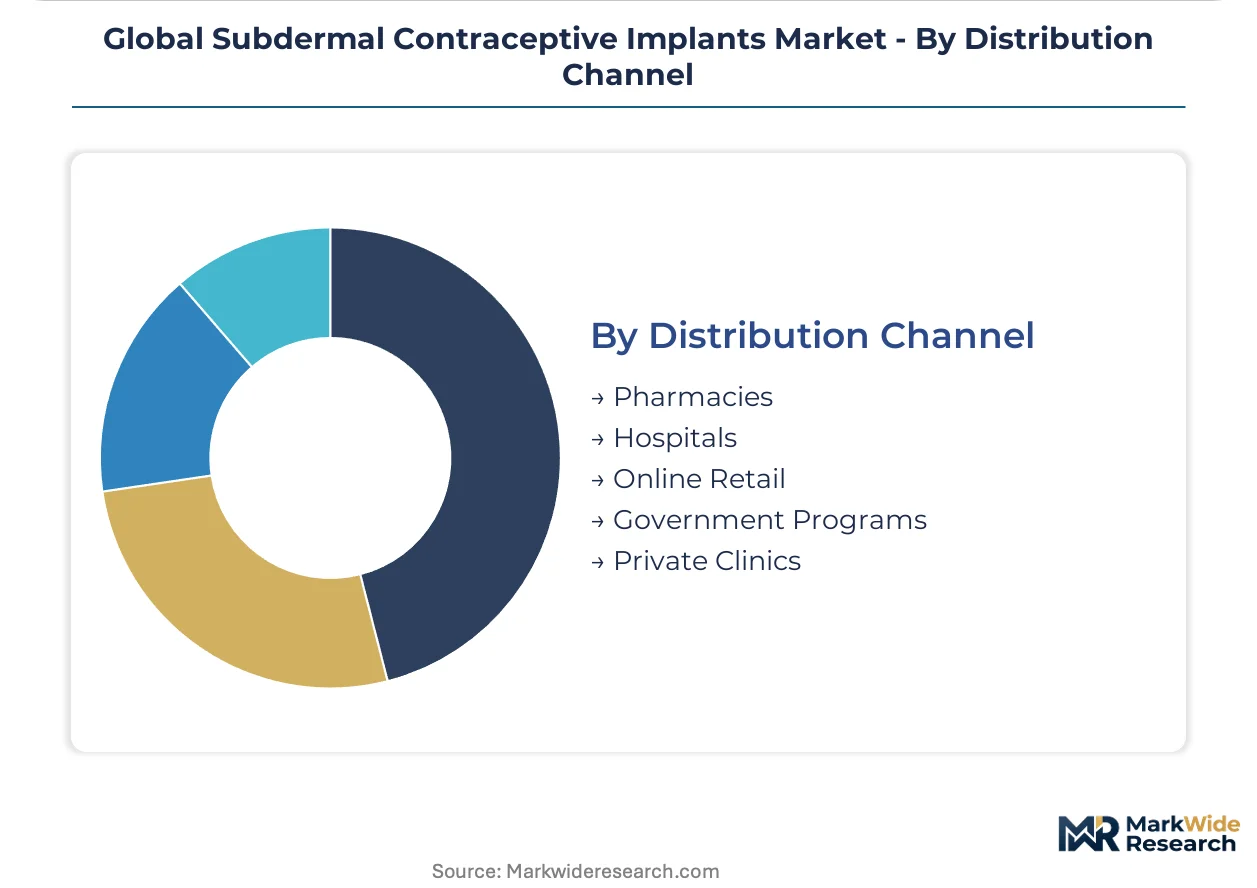
Distribution Channel:
Supply concentration in multilateral procurement bodies is displacing fragmented national tender processes across channel structures.
- Pharmacies:Retail networks in urban Kenya and Nigeria are emerging as direct-to-patient access points for out-of-pocket expenditure.
- Hospitals:Tertiary facilities manage complex insertion cases and removal complications requiring surgical backup.
- Online Retail:Telemedicine-integrated platforms face regulatory uncertainty for prescription-controlled implant procurement.
- Government Programs:Centralized tender structures through the Global Family Planning Supply Chain coalition coordinate bulk purchasing across 46 countries.
- Private Clinics:Independent facilities compete on appointment availability and provider continuity.
Government Programs dominate procurement volume; Pharmacies are expanding most quickly in urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National health ministries in Sub-Saharan Africa are channeling dedicated family planning budgets into long-acting reversible contraceptive procurement. WHO prequalification pathways and streamlined FDA guidance on etonogestrel bioequivalence are accelerating product registration timelines across high-need markets.
Nigeria
Federal Ministry of Health tenders for single-rod etonogestrel implants are expanding through the National Family Planning Blueprint. WHO prequalification serves as mandatory eligibility for federal procurement contracts. Lagos and Abuja anchor distribution networks where cold-chain infrastructure investments are concentrating last-mile delivery capacity.
Ethiopia
The Health Sector Transformation Plan prioritizes implant insertion training for frontline health extension workers. The country's national pharmaceutical regulator coordinates with WHO prequalification to fast-track generic registrations. Addis Ababa hosts regional procurement consortia serving the Horn of Africa.
Kenya
County-level family planning budgets are scaling implant access through devolved health financing. Kenya Pharmacy and Poisons Board alignment with WHO standards enables parallel regulatory approval. Nairobi anchors private pharmacy channel expansion into direct-to-patient retail distribution.
United States
FDA 510(k) pathways for etonogestrel bioequivalence are updating technical guidance for generic submissions. Medicaid reimbursement structures shape provider-level prescribing patterns for long-acting reversible contraceptives. Research consortia in Massachusetts and California are validating biodegradable polymer matrices for next-generation implants.
Netherlands
EMA centralized marketing authorizations and REACH compliance obligations are tightening polymer constituent standards. Dutch research institutes in Leiden and Utrecht are advancing magnesium-based biodegradable matrices through clinical validation. These programs target elimination of surgical removal procedures.
Global Subdermal Contraceptive Implants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tender-driven procurement structures. The vendor base concentrates around WHO-prequalified manufacturers with established cold-chain distribution networks. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, polymer formulation specialists, and provider training ecosystem builders. Competitive moves center on prequalification record accumulation and multilateral fund relationship deepening.
Among vertically integrated pharmaceutical conglomerates, Merck & Co., Inc. and Bayer AG occupy positions shaped by manufacturing scale and regulatory dossier depth. Organon & Co. exemplifies the provider training ecosystem archetype. Shanghai Dahua Pharmaceutical Co., Ltd. represents emerging market manufacturing capacity seeking prequalification entry.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bayer AG |
| Shanghai Dahua Pharmaceutical Co., Ltd. |
| Organon & Co. |
| Pfizer Inc. |
| Gedeon Richter Plc |
| DKT WomanCare Global |
| Cipla Ltd. |
| Celanese |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient synthesis for etonogestrel concentrates among specialized contract manufacturers in India and China, anchoring margin pools downstream with WHO-prequalified finished-device manufacturers who command tender premiums through regulatory dossier depth.
Pricing Analysis
Certification level creates the primary spread across procurement tiers. WHO-prequalified suppliers capture premium positioning in multilateral tenders, while manufacturers lacking prequalification compete on price in fragmented private channels. Three-tier pricing structure separates prequalified premium suppliers from standard-tier regional manufacturers and economy-tier unqualified imports. Pricing pressure stems from centralized tender compression through the Global Family Planning Supply Chain coalition. Government procurement bodies exhibit highest price sensitivity; private gynecology practices in urban Nigeria show lowest sensitivity due to bundled service premiums.
Supply Chain Analysis
Contract manufacturing capacity for progestin API synthesis concentrates at specialized producers in India and China, with polymer rod fabrication clustering in Western Europe and North America. Finished-device assembly draws from ethylene vinyl acetate polymer supplies anchored in Belgium and the Netherlands, progestin active ingredients from Indian pharmaceutical manufacturers, and sterile packaging components from German medical-grade film suppliers. Single-source vulnerability concentrates at API synthesis nodes where regulatory qualification timelines prevent rapid supplier switching. Distribution runs through cold-chain logistics networks terminating at national health ministry warehouses in Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as demand bifurcates between multilateral tender procurement and emerging private pharmacy channels, creating distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Build regulatory dossier moats through accelerated WHO prequalification accumulation for next-generation biodegradable formulations. Deepen backward integration into polymer sourcing to defend margin position against API cost volatility. Threaten substitution from copper IUDs competing for the same ministry budgets demands locked-in provider training ecosystems that cement clinic loyalty. Capacity addition in East African distribution hubs anchors cold-chain reliability that tender structures increasingly mandate. For New Entrants and Emerging Players: Private pharmacy networks in urban Kenya and Nigeria represent the most penetrable entry point for direct-to-patient access bypassing centralized tender compression. West African ministry partnerships in Ghana and Côte d'Ivoire offer first-mover positioning where implant prevalence lags unmet need. Self-removal technology development provides a differentiated go-to-market angle addressing both patient discontinuation barriers and provider capacity constraints that limit rural deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed provider training platform specialists who have built clinic-level loyalty networks in high-volume African markets. Long-term viability hinges on biodegradable polymer transition eliminating removal infrastructure requirements and expanding addressable patient populations. Acquisition target archetype: regional manufacturers with established ministry relationships but lacking prequalification, positioned for regulatory upgrade. Watch biodegradable implant clinical validation milestones in Dutch and Swedish research consortia as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Acceleration | Unlocks eligibility for Global Family Planning Supply Chain coalition procurement across 46 countries. |
| Biodegradable Polymer R&D Partnership | Swedish and Dutch research consortia validate magnesium-based matrices eliminating surgical removal. |
| East African Distribution Hub Expansion | Addis Ababa and Nairobi anchor last-mile cold-chain capacity for Horn of Africa procurement consortia. |
| Provider Training Ecosystem Development | Locks in clinic-level loyalty through certified insertion protocols that raise switching costs. |
| Private Pharmacy Channel Integration | Captures out-of-pocket expenditure in urban Kenya and Nigeria beyond tender-compressed margins. |
Research Methodology
A spread of perspectives from regulatory affairs specialists at WHO prequalification units, procurement managers at multilateral health funds, biomedical engineers at polymer research institutes, and family planning clinic directors converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA centralized marketing authorization databases, WHO prequalification product lists, and national health ministry tender documents. Bottom-up volume triangulation from country-level procurement data and top-down value estimation from manufacturer revenue patterns were reconciled.
Demand-supply balance dynamics across progestin API manufacturing capacity and finished-device assembly throughput shaped the analytical framework. Segmentation dimensions modeled include product architecture, mechanism of action, end-user channel, and distribution pathway across the projection horizon. CAGRs were derived from regression analysis of historical procurement volumes against ministry budget expansion trajectories. Forecast inputs incorporated WHO prequalification pipeline status and biodegradable polymer clinical trial progression.
Practitioners should monitor regulatory pathway delays at EMA for polymer degradation documentation requirements and cold-chain infrastructure investment gaps in rural Ethiopia as early signals for forecast revision. Forecasts reflect assumptions about continued multilateral fund commitment levels and generic manufacturer entry timelines. Quarterly review of ministry tender award patterns and prequalification approval cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Self-Injections Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
EEG Amplifiers Market
Medical Devices
North America C-Arms Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Colposcopes Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Bathroom and Toilet Assist Devices Market