
 Steroid-Free Nasal Sprays Market | 2026-2036
Steroid-Free Nasal Sprays Market Size, Share, and Industry Trends Forecast 2026-2036
Steroid-Free Nasal Sprays Market Analytics
The gap between premium preservative-free formulations and commodity saline rinses is expanding. Johnson & Johnson leverages its consumer health infrastructure to dominate pharmacy channels. Glenmark Pharmaceuticals anchors its position through specialized antihistamine sprays in emerging markets. Sanofi competes by extending its respiratory portfolio into steroid-free alternatives.
Steroid-free nasal sprays are aqueous or aerosolized formulations delivering active ingredients such as antihistamines, decongestants, or saline solutions without corticosteroid compounds, typically administered via pump or metered-dose mechanisms to treat nasal passage inflammation and congestion. These products serve consumers seeking symptomatic relief from allergic rhinitis, sinusitis, and cold symptoms while avoiding hormonal side effects associated with long-term steroid exposure. Saline and antihistamine product types command the largest volume pools, though nasal antiviral formulations represent the fastest-growing innovation corridor. Pediatric end users generate outsized margin capture as caregivers prioritize safety-certified, steroid-free options for chronic conditions.
The FDA oversees OTC monograph compliance and active ingredient safety thresholds, while the EPA regulates propellant chemistry in aerosol delivery systems, and ISO 10993 governs biocompatibility testing for prolonged mucosal contact. These frameworks elevate formulation costs but simultaneously filter out substandard competitors, concentrating market access among manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving OTC switch pathways for prescription antihistamines and preemptive allergen immunotherapy advances that could reshape the addressable patient base.
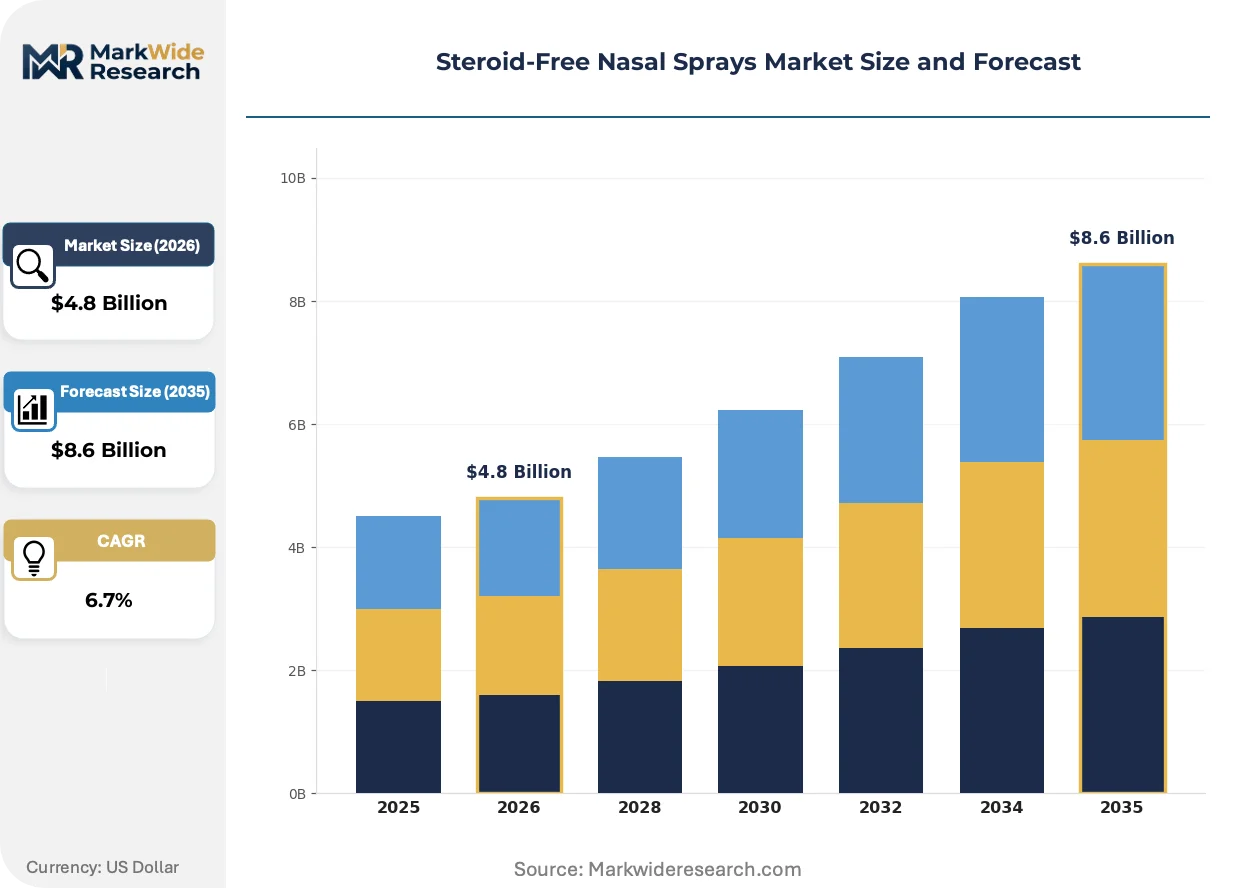
Market Dynamics
The FDA's OTC monograph reforms are compressing approval timelines for active ingredients while simultaneously elevating biocompatibility testing costs, creating asymmetric access advantages for manufacturers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Pediatric Safety Certification:Caregivers in the United States increasingly demand steroid-free formulations for chronic allergic rhinitis management in children, expanding the addressable patient base beyond adult populations.
- REACH Compliance Alignment:European manufacturers leveraging pre-validated preservative-free chemistries capture cross-border distribution efficiencies as ECHA substance restrictions tighten.
- Saline Irrigation Standardization:ISO 10993 biocompatibility protocols for prolonged mucosal contact filter substandard competitors, concentrating market access among qualified producers.
Market Restraints
- Propellant Chemistry Constraints:EPA regulations on hydrofluorocarbon aerosol delivery systems force reformulation investments, compressing margins for legacy aerosolized product lines.
- Active Ingredient Sourcing Concentration:Antihistamine API production clusters in Indian pharmaceutical corridors, exposing formulators to single-geography supply disruption risks.
- Prescription-to-OTC Switch Velocity:Accelerated FDA pathways for formerly prescription antihistamines threaten to commoditize incumbent OTC positioning.
Strategic Opportunities
- Nasal Antiviral Formulation White Space:Post-pandemic residual demand for non-steroidal prophylactic nasal interventions creates innovation corridors beyond traditional allergy and congestion applications.
- Emerging Market Pharmacy Modernization:India's CDSCO streamlined OTC registration processes enable first-mover positioning in underserved urban retail pharmacy networks.
- Smart Pump Convergence:Integration of Bluetooth-enabled dose-tracking hardware with saline delivery mechanisms opens subscription-based chronic disease management revenue models.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Specialized expertise in FDA OTC monograph navigation and EPA propellant compliance commands premium compensation, constraining mid-tier manufacturer expansion.
- Legacy System Integration Friction:ERP and quality management system upgrades required for ISO 13485 medical device alignment disrupt production scheduling for multiproduct facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steroid-Free Nasal Sprays Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saline, Antihistamine, Decongestant, Nasal Antiviral Application: Allergic Rhinitis, Nasal Congestion, Sinusitis, Cold Symptoms Delivery Mode: Aerosol, Pump Spray, Metered Dose, Disposable End User: Adults, Pediatric Patients, Clinics, Pharmacies |
| Companies Covered | AstraZeneca, Johnson & Johnson, GlaxoSmithKline, PharmaCorp, Sanofi, Glenmark Pharmaceuticals, Novartis International AG, Allergy Relief Solutions, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steroid-Free Nasal Sprays Market Evolving Landscape
Formulation science and delivery mechanism engineering are converging to reshape competitive positioning, with preservative-free chemistries and connected devices emerging as distinct innovation vectors.
Electromechanical micro-pump technology is electrifying metered-dose delivery precision. Pediatric caregivers and chronic rhinitis patients in Germany and Japan adopt Bluetooth-integrated spray devices that log usage patterns for physician review. This capability compression is electrifying subscription-based adherence programs while devaluing commodity pump mechanisms.
The EU F-Gas Regulation phase-down of hydrofluorocarbon propellants is forcing aerosolized nasal spray reformulations across European manufacturing facilities. Compressed gas and aqueous pump alternatives capture volume as propellant-dependent products face supply rationing. Aerosol-dependent decongestant categories in France and Italy experience the most acute portfolio restructuring pressures.
Direct-to-consumer pharmacy channels are fragmenting traditional wholesale distribution hierarchies. Allergy sufferers in the United States increasingly purchase saline and antihistamine sprays through telehealth-integrated platforms that bundle diagnostic testing with recurring product shipments. This channel rotation is most pronounced in suburban markets where pharmacy deserts concentrate digital-first purchasing behavior.
Steroid-Free Nasal Sprays Market Segmentation
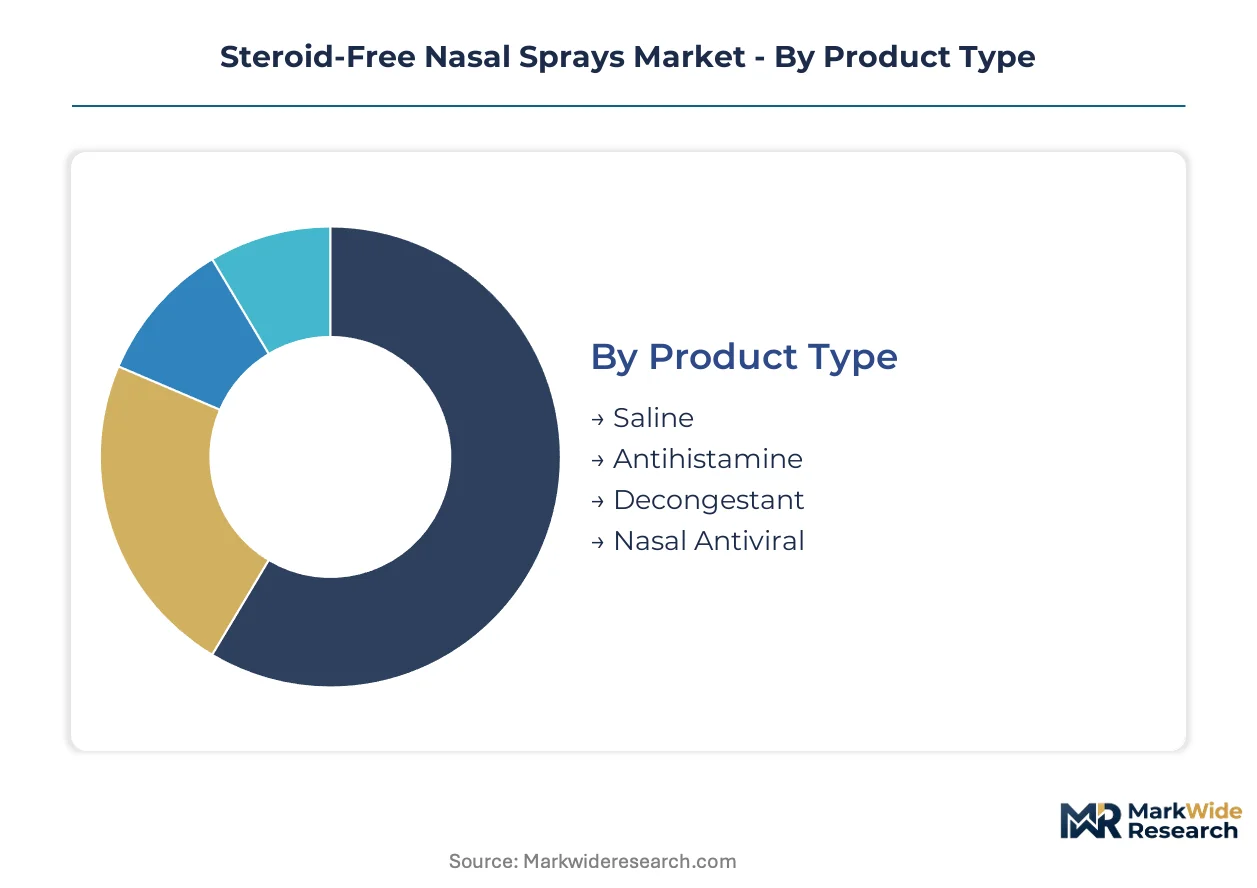
Steroid-free nasal spray manufacturers configure production lines around formulation chemistry and delivery mechanism combinations. Segment-level supply concentration determines which product categories absorb capital investment and which remain contract-manufactured specialties.
Product Type:
Manufacturing capacity clusters around aqueous formulation expertise, with preservative-free chemistry capabilities creating asymmetric access to pharmacy and hospital procurement channels.
- Saline:Isotonic sodium chloride solutions deliver mechanical mucosal irrigation without pharmacological activity. United States pharmacy chains capture volume through private-label sourcing, though margin compression limits branded expansion.
- Antihistamine:Azelastine and olopatadine hydrochloride formulations block H1 receptors for allergic rhinitis management. Indian API corridors supply active ingredients to European and North American formulators, creating single-geography dependency risks.
- Decongestant:Oxymetazoline and phenylephrine formulations provide vasoconstrictive relief.
- Nasal Antiviral:Zinc salts and proprietary polymer barriers target viral particle neutralization.
Saline absorbs the bulk of installed capacity; nasal antiviral is expanding most quickly.
Application:
Clinical trial endpoints and reimbursement coding shape which indications attract formulation investment versus generic substitution.
- Allergic Rhinitis:Seasonal and perennial IgE-mediated inflammation drives chronic use patterns. Pediatric certification requirements in Germany and Japan elevate barrier-to-entry for new entrants.
- Nasal Congestion:Acute symptomatic relief from upper respiratory infections commands impulse purchase volumes. United States retail pharmacy placement determines market access.
- Sinusitis:Adjunctive therapy for bacterial and viral sinus inflammation.
- Cold Symptoms:Multi-symptom relief positioning in over-the-counter portfolios.
Allergic rhinitis captures the majority of prescription-to-OTC switch value; nasal congestion maintains the highest unit velocity.
Delivery Mode:
Propellant chemistry regulations and device engineering capabilities partition manufacturers between aerosol and mechanical pump competencies.
- Aerosol:Hydrofluorocarbon-propelled metered-dose systems deliver fine particle dispersion. EPA phase-down mandates in the United States force reformulation timelines.
- Pump Spray:Mechanical squeeze-actuated mechanisms dominate preservative-free positioning. European manufacturers leverage REACH-aligned chemistries for cross-border distribution.
- Metered Dose:Precision-volume delivery systems for clinical settings.
- Disposable:Single-use vials for surgical and emergency applications.
Pump spray commands the largest production footprint; metered dose is climbing the fastest on connected device integration.
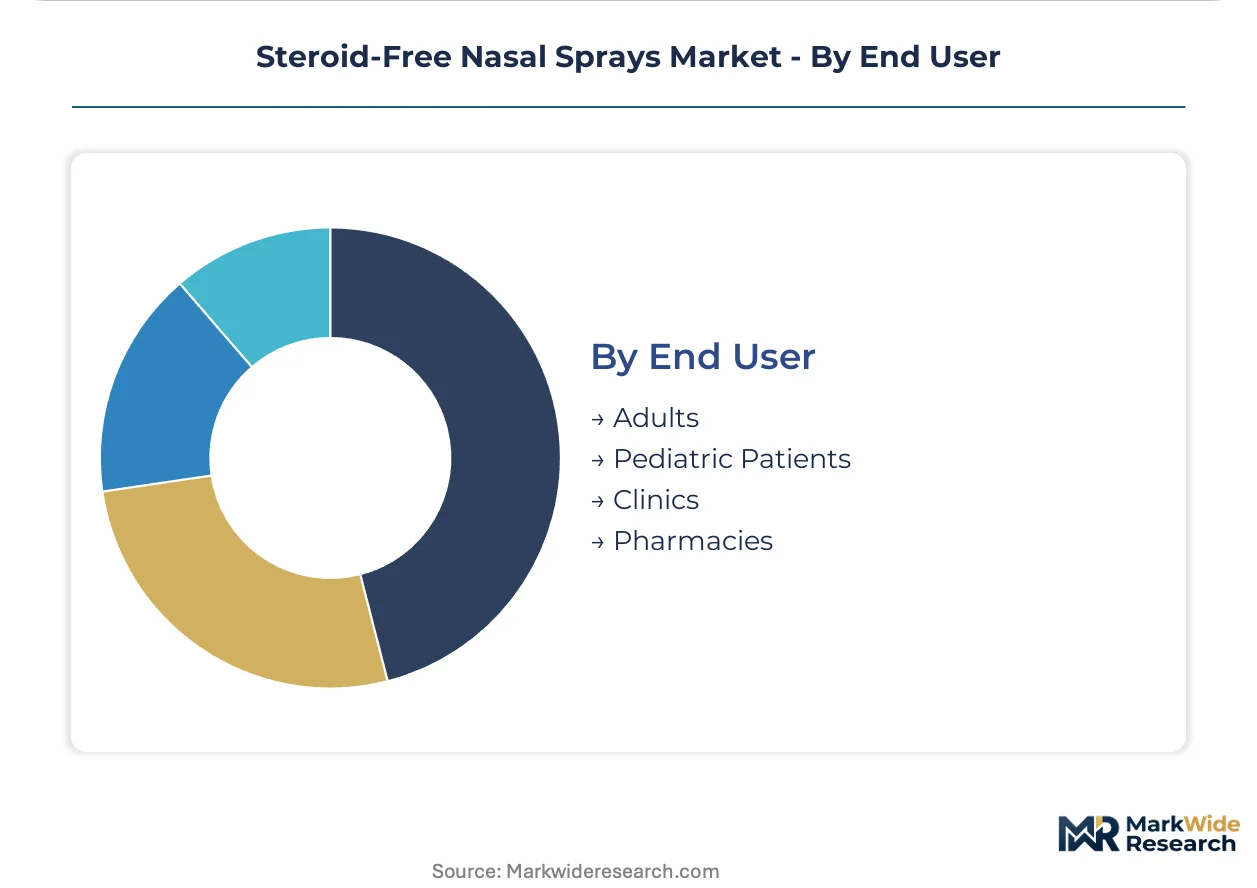
End User:
Procurement authority and safety certification requirements segment pricing power across consumer, clinical, and institutional channels.
- Adults:Self-directed purchase decisions favor established brands with pharmacy shelf presence. United States direct-to-consumer channels fragment traditional wholesale hierarchies.
- Pediatric Patients:Caregiver-mediated demand prioritizes steroid-free safety certification. ISO 10993 biocompatibility testing filters substandard competitors from chronic use segments.
- Clinics:Institutional procurement through group purchasing organizations.
- Pharmacies:Retail and hospital pharmacy dispensing networks.
Adults generate the highest absolute revenue; pediatric patients produce the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors API production corridors serving North American and European formulators, while Mumbai-based Glenmark Pharmaceuticals channels specialized antihistamine sprays into emerging pharmacy networks.
United States
FDA OTC monograph reforms compress active ingredient approval timelines for saline and antihistamine formulations. The EPA's hydrofluorocarbon phase-down mandates force aerosolized product reformulations by 2025. Johnson & Johnson leverages its consumer health infrastructure to dominate pharmacy shelf placement in suburban markets.
Germany
REACH-aligned preservative-free chemistries capture cross-border distribution efficiencies into neighboring EU states. The EU F-Gas Regulation accelerates propellant chemistry transitions in aerosol manufacturing facilities. Berlin-Brandenburg clusters host biocompatibility testing laboratories certifying pediatric safety standards.
India
CDSCO streamlined OTC registration processes enable first-mover positioning in underserved urban retail pharmacy networks. The PLI scheme for pharmaceuticals attracts formulation investment into Gujarat and Maharashtra production corridors. Cipla and Glenmark Pharmaceuticals anchor domestic manufacturing while supplying APIs to European contract formulators.
Japan
PMDA pediatric certification requirements elevate barrier-to-entry for chronic rhinitis product entrants. METI standards for connected medical devices accelerate Bluetooth-integrated spray pump adoption. Osaka-Kansai manufacturing clusters specialize in precision metered-dose mechanisms for clinical settings.
United Kingdom
MHRA post-Brexit regulatory autonomy creates divergence from EU OTC monograph alignment timelines. London-Southeast distribution hubs consolidate direct-to-consumer pharmacy channel fulfillment. Allergy Relief Solutions occupies specialist positioning within independent pharmacy networks.
Steroid-Free Nasal Sprays Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification depth. The vendor base stratifies between multinational consumer health conglomerates with dedicated regulatory affairs infrastructure and mid-tier regional specialists dependent on contract manufacturing. Three archetypes dominate: vertically integrated pharmaceutical majors with respiratory portfolios, API-forward Indian formulators leveraging cost-advantaged production, and niche allergen-focused specialists. Capacity expansion and portfolio diversification into pediatric-certified segments represent the dominant competitive vectors.
Within the pharmaceutical major tier, Johnson & Johnson and Sanofi exemplify scale-driven positioning through consumer health infrastructure and respiratory portfolio extension respectively. Among API-integrated specialists, Glenmark Pharmaceuticals occupies a distinctive position bridging Indian manufacturing cost structures with European regulatory compliance capabilities. AstraZeneca represents the prescription-to-OTC switch archetype, anchoring the competitive landscape where former prescription antihistamines threaten incumbent OTC positioning.
| Leading Market Players |
|---|
| AstraZeneca |
| Johnson & Johnson |
| GlaxoSmithKline |
| PharmaCorp |
| Sanofi |
| Glenmark Pharmaceuticals |
| Novartis International AG |
| Allergy Relief Solutions |
| Cipla |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturers in the United States and Europe enforce pricing discipline through consolidated API sourcing agreements, while simultaneously absorbing REACH and FDA biocompatibility testing costs that filter out subscale competitors. This ownership pattern concentrates margin capture among players with dedicated regulatory affairs infrastructure capable of navigating pediatric certification premiums.
Pricing Analysis
Value-based pricing anchors on ISO 10993 pediatric safety certification tiers, with preservative-free formulations commanding premium positioning over commodity saline rinses. Three-tier pricing structure across premium, standard, and economy levels separates certified pediatric sprays from adult-focused antihistamines and private-label saline irrigants. Pricing pressure stems from Indian API cost advantages compressing margins for European formulators. Pediatric caregivers exhibit lowest price sensitivity; pharmacy chain procurement teams drive hardest bargaining on commodity saline volumes.
Supply Chain Analysis
Direct-to-consumer pharmacy channels handle hyperscale demand from allergy sufferers in suburban United States markets, bypassing traditional wholesale hierarchies. API production concentrates in India, with formulation finishing in Germany and the United States. Supply chains draw from azelastine hydrochloride, olopatadine, and isotonic sodium chloride inputs. Single-source vulnerability in Indian pharmaceutical corridors exposes formulators to geography-specific disruption risks. Distribution runs through telehealth-integrated platforms bundling diagnostic testing with recurring shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA OTC monograph compliance costs force subscale competitors toward exit or acquisition, concentrating viable production among regulatory-capable manufacturers.
For Market Incumbents: Lock in pediatric certification moats by accelerating ISO 10993 biocompatibility testing investments before ECHA substance restrictions tighten further. Defend against prescription-to-OTC switch threats from AstraZeneca's respiratory portfolio by securing exclusive pharmacy shelf placement through Johnson & Johnson-style consumer health infrastructure. Prioritize backward integration into preservative-free chemistry capabilities to capture cross-border distribution efficiencies under REACH alignment. For New Entrants and Emerging Players: Enter via nasal antiviral formulation white space where post-pandemic prophylactic demand outpaces incumbent R&D pipelines. Target India's CDSCO-streamlined OTC registration corridors for first-mover positioning in underserved urban retail pharmacy networks. Deploy Bluetooth-integrated smart pump hardware as a subscription-based chronic disease management wedge against commodity pump manufacturers. For Investors and Strategic Acquirers: FDA pediatric safety certification acceleration is the leading indicator that margin expansion will concentrate among qualified producers over the projection horizon. Position acquisition screening around API-integrated Indian formulators with European regulatory compliance capabilities, analogous to Glenmark Pharmaceuticals' bridging model. Watch for EPA hydrofluorocarbon phase-down compliance failures as forced divestiture catalysts among legacy aerosol-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Safety Certification Investment | ISO 10993 biocompatibility testing filters substandard competitors from chronic use segments. |
| Preservative-Free Chemistry Backward Integration | REACH-aligned chemistries capture cross-border distribution efficiencies into EU pharmacy networks. |
| Smart Pump Hardware Development | Bluetooth-enabled dose-tracking opens subscription-based adherence revenue models in Germany and Japan. |
| Indian API Corridor Supply Agreements | CDSCO-registered production anchors cost-advantaged sourcing for European and North American formulators. |
| Direct-to-Consumer Channel Launch | Telehealth-integrated platforms fragment wholesale hierarchies in United States suburban pharmacy deserts. |
Research Methodology
FDA OTC monograph filings, ECHA substance restriction databases, and ClinicalTrials.gov pediatric study registries formed the secondary backbone, cross-referenced against primary interviews with regulatory affairs directors, pharmacy procurement managers, and contract manufacturing executives. Bottom-up and top-down triangulation validated volume estimates across saline, antihistamine, decongestant, and nasal antiviral formulation categories.
Bottom-up modeling anchored on installed manufacturing capacity and pediatric certification penetration rates, while top-down analysis cross-checked against pharmaceutical industry trade flows and pharmacy retail audit data. Segmentation dimensions included product type chemistry, delivery mechanism engineering, application indication, and end-user procurement authority. CAGRs derived from regression analysis of historical OTC switch velocity and regulatory approval timeline compression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA propellant phase-down acceleration or Indian API export restriction scenarios. Periodic stress-testing of base assumptions is recommended given prescription-to-OTC switch pathway volatility and emerging market pharmacy modernization cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Egypt Diabetes Drugs Market