
 Global Anorexiants Market | 2026-2036
Global Anorexiants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anorexiants Market Foresight
Asset-light licensing and royalty-based partnerships are reshaping competitive dynamics in anorexiants, allowing mid-tier firms to commercialize without manufacturing infrastructure. Novo Nordisk A/S leverages its vertically integrated peptide production network to dominate the GLP-1 adjacent positioning. Currax Pharmaceuticals LLC sustains market presence through specialized channel control in outpatient obesity clinics. Pfizer Inc. competes via broad retail pharmacy distribution reach for its legacy phentermine portfolio.
Anorexiants comprise centrally acting sympathomimetics, lipase inhibitors, and serotonin receptor agonists formulated for short-to-intermediate-term obesity pharmacotherapy, typically prescribed at dosages ranging from 8 mg to 37.5 mg daily depending on mechanism and regulatory schedule. Their primary commercial purpose is to reduce caloric intake or nutrient absorption in patients with BMI thresholds exceeding 30 kg/m², or 27 kg/m² with comorbidities. Phentermine and diethylpropion retain volume leadership in retail pharmacy channels due to generic availability and established DEA scheduling, while orlistat anchors margin pools in online pharmacy direct-to-consumer segments where OTC status permits broader access. The therapy area segmentation shows obesity management commanding the largest addressable base, with metabolic disorders representing the fastest-growing prescriber category as endocrinologists expand pharmacological intervention protocols.
The FDA's REMS framework and DEA Schedule IV controls constrain prescribing freedom for sympathomimetic anorexiants, while the EMA's pharmacovigilance requirements under the EU MDR shape product labeling and post-market surveillance obligations for orlistat-containing formulations in Europe. Health Canada's PMRA maintains parallel controlled-substance scheduling that limits cross-border product standardization for phentermine derivatives. Stakeholders must monitor evolving reimbursement criteria for pharmacological obesity treatment as public health agencies recalibrate cost-effectiveness thresholds for weight management interventions.
Market Dynamics
GLP-1 receptor agonists are compressing demand for traditional sympathomimetic anorexiants as physicians resequence pharmacotherapy protocols, forcing legacy phentermine portfolios into narrower BMI-band positioning and shorter-duration prescribing windows.
Growth Catalysts
- Hospital-based obesity management protocols:Integrated health systems in the United States are expanding prescriber pools beyond endocrinology into cardiology and sleep medicine, broadening eligibility assessments for appetite suppressants.
- DEA Schedule IV framework:Controlled-substance scheduling creates formulary predictability that retail pharmacy chains leverage for inventory planning and patient compliance programs.
- Orlistat OTC status:Direct-to-consumer online pharmacy channels bypass prescriber gatekeeping, capturing patients below surgical intervention thresholds who self-select for nutrient absorption inhibition.
Market Restraints
- Active pharmaceutical ingredient concentration:Sympathomimetic API synthesis clusters in Indian and Chinese contract manufacturers, exposing formulators to import inspection delays and geopolitical supply friction.
- Cardiovascular safety profiling:Fenfluramine legacy liabilities perpetuate echocardiographic monitoring requirements that inflate total cost-of-care and deter primary care prescribing.
- GLP-1 substitution elasticity:Semaglutide and tirzepatide access expansion through employer health plans is displacing first-line anorexiant prescriptions in commercially insured populations.
Strategic Opportunities
- Germany's DiGA reimbursement pathway:Digital health applications for obesity coaching create bundled prescribing opportunities where anorexiants pair with app-based behavioral monitoring for statutory insurer reimbursement.
- Fixed-dose combination formulations:Phentermine-topiramate extended-release platforms address polypharmacy adherence gaps in metabolic syndrome patients requiring multi-mechanism intervention.
- Specialty pharmacy distribution:Hub-and-spoke models for REMS-compliant products reduce retail pharmacy handling complexity while capturing patient data for outcomes contracting with integrated delivery networks.
Industry Challenges
- REMS program administration:Risk Evaluation and Mitigation Strategy compliance requires certified prescriber enrollment, patient registry maintenance, and periodic safety reporting that burdens smaller outpatient clinic operators.
- Cross-jurisdictional scheduling harmonization:Phentermine's Schedule IV status in the United States, controlled substance classification in Canada, and prescription-only status in Japan fragment regulatory dossier requirements and delay market entry sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anorexiants Market |
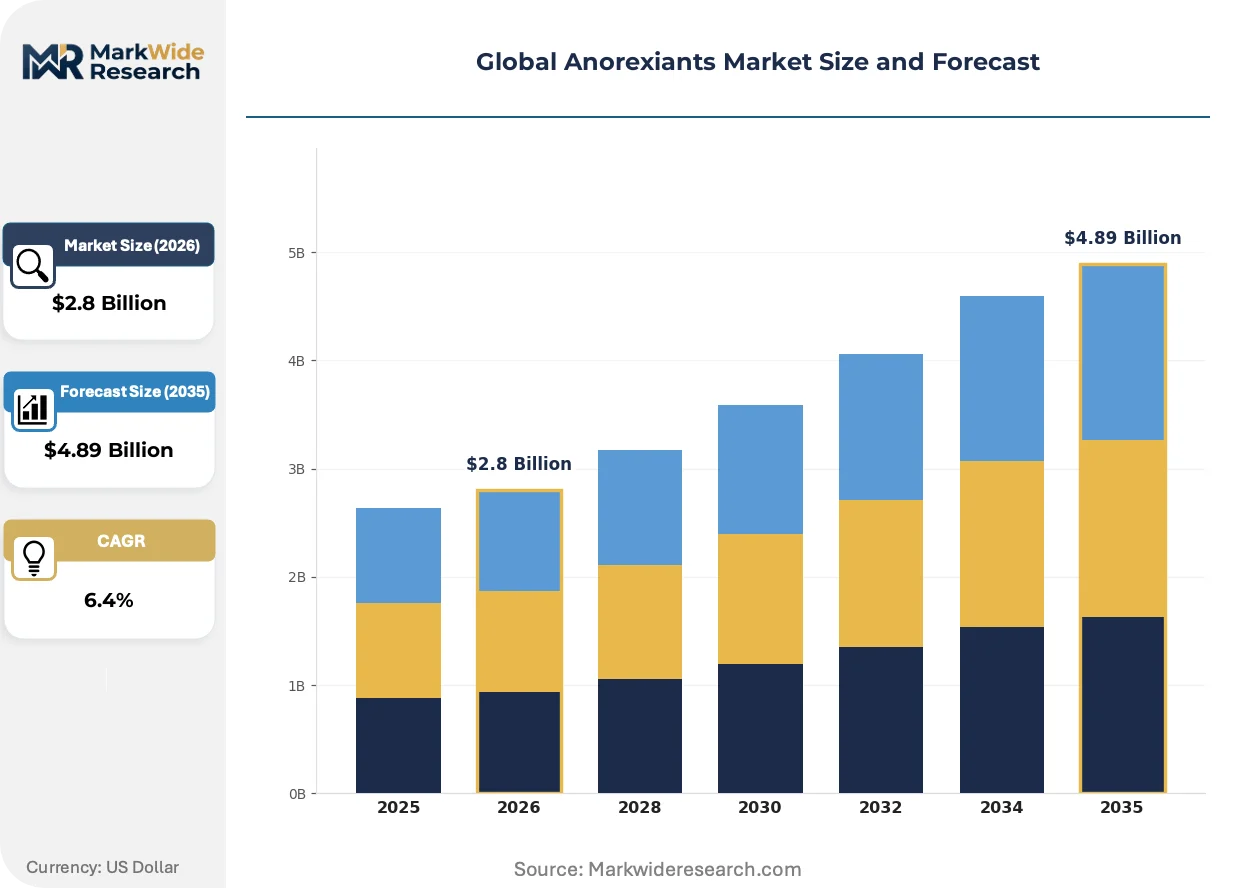
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phentermine, Orlistat, Lorcaserin, Diethylpropion, Benzphetamine Therapy Area: Obesity Management, Weight Loss, Appetite Suppression, Metabolic Disorders End User: Hospitals, Specialized Clinics, Outpatient Care Centers, Wellness Facilities Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesale Distributors |
| Companies Covered | Novo Nordisk A/S, Currax Pharmaceuticals LLC, Pfizer Inc., F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Lannett Co. Inc., Bausch Health Companies Inc., Johnson & Johnson Services Inc., Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anorexiants Market Shifts & Advancements
Virtual care platforms are rewiring patient acquisition and medication adherence monitoring, compressing the traditional prescriber-pharmacy-patient triad into integrated digital workflows that reshape how anorexiants reach their addressable populations.
Telemedicine prescribing infrastructure is virtualizing the initial patient encounter for obesity pharmacotherapy. Direct-to-consumer platforms in the United States now conduct BMI verification, comorbidity screening, and prior authorization submission through asynchronous clinical workflows. This virtualization collapses geographic access barriers that previously concentrated prescribing in urban endocrinology practices.
EMA's Medical Device Regulation and EU MDR pharmacovigilance extensions are tightening post-market surveillance for orlistat-containing products. Manufacturers must now submit periodic safety update reports with real-world cardiovascular outcome data. European formulators are responding by investing in patient registries that track long-term metabolic endpoints beyond weight reduction.
Employer-sponsored health benefit designs are narrowing pharmacy networks for weight management medications. Large self-insured plans in the United States are tiering GLP-1 coverage ahead of legacy anorexiants, forcing manufacturers to demonstrate cost-offset through reduced orthopedic and diabetes-related claims. This procurement compression is most visible in Fortune 500 manufacturing and logistics sectors where workforce BMI distributions drive premium calculations.
Global Anorexiants Market Segmentation
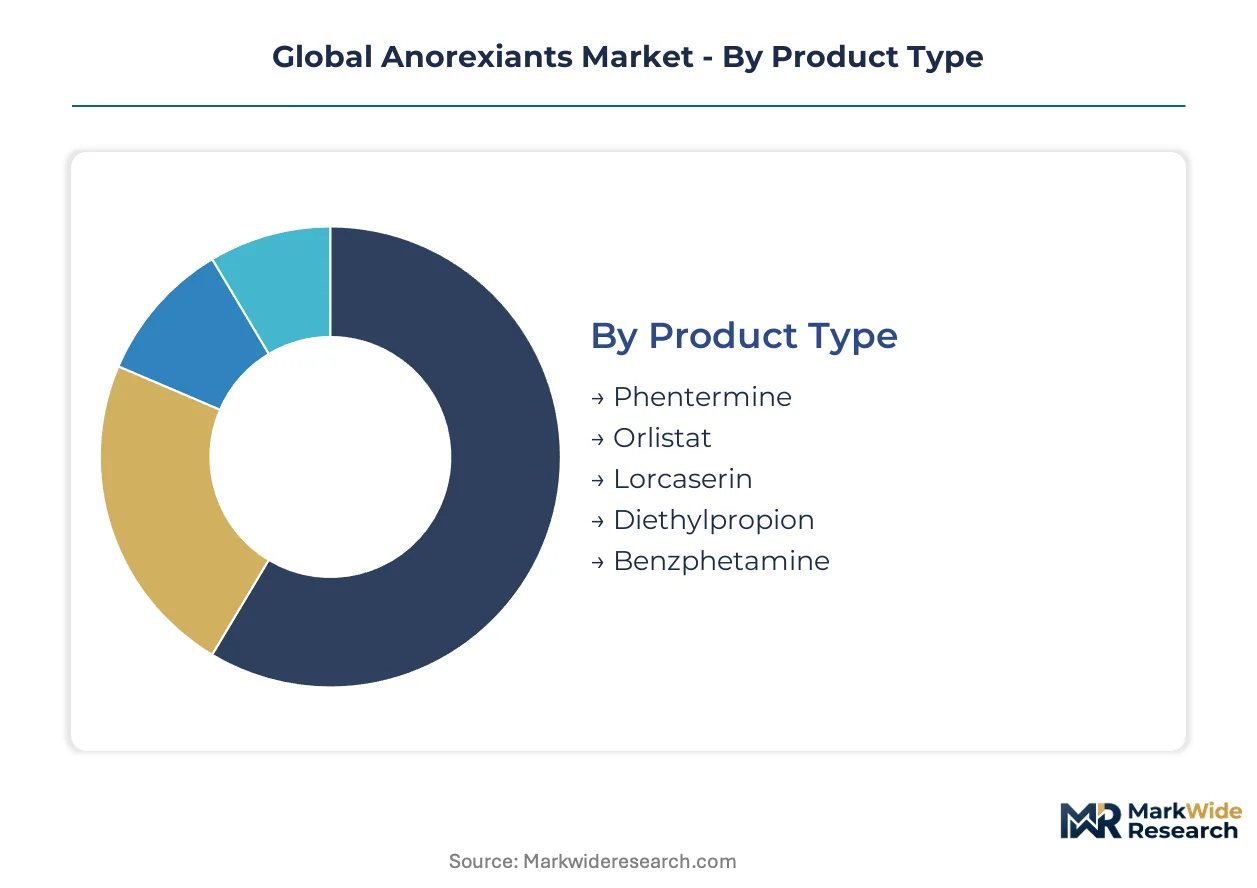
Segmentation in anorexiants reveals how regulatory scheduling, reimbursement pathways, and prescriber specialization fragment commercial opportunity across distinct channels and patient populations. Understanding these divides enables manufacturers to align formulation development with specific access constraints and compliance burdens.
Product Type:
After-sales service intensity varies sharply across this category, with controlled substances requiring REMS-certified prescriber support and registry maintenance that OTC alternatives bypass entirely.
- Phentermine:Sympathomimetic amine with 8 mg to 37.5 mg daily dosing schedules. Demand concentrates in United States retail pharmacy chains where DEA Schedule IV status creates formulary predictability for inventory planning and patient compliance programs.
- Orlistat:Lipase inhibitor available in prescription and OTC strengths that reduces dietary fat absorption by approximately 30%. Direct-to-consumer online pharmacy channels in Germany and Japan capture patients below surgical intervention thresholds who self-select for nutrient absorption inhibition without prescriber gatekeeping.
- Lorcaserin:Serotonin 2C receptor agonist withdrawn from multiple markets due to cardiovascular safety signals, now serving as a cautionary benchmark for post-market surveillance requirements.
- Diethylpropion:Short-acting sympathomimetic with similar DEA scheduling to phentermine but narrower prescriber familiarity, limiting volume despite comparable efficacy profiles.
- Benzphetamine:Prodrug converted to amphetamine in vivo with stricter controlled-substance handling requirements that constrain distribution to specialty pharmacy networks.
By volume, phentermine leads. By growth pace, orlistat is ahead.
Therapy Area:
Cost tier stratification separates acute intervention from chronic disease management, with metabolic disorder protocols commanding premium pricing through endocrinology specialist access.
- Obesity Management:Primary indication for BMI thresholds exceeding 30 kg/m² or 27 kg/m² with comorbidities. Hospital-based protocols in the United States are expanding prescriber pools beyond endocrinology into cardiology and sleep medicine.
- Weight Loss:Cosmetic and lifestyle-driven demand segment with higher patient self-payment rates and lower reimbursement coverage, concentrating in wellness facilities and direct-to-consumer channels.
- Appetite Suppression:Mechanism-specific positioning for short-to-intermediate-term pharmacotherapy, typically 12-week prescribing windows that limit recurring revenue per patient.
- Metabolic Disorders:Fastest-expanding prescriber category as endocrinologists broaden pharmacological intervention protocols for insulin resistance and prediabetes populations.
By addressable patient base, obesity management leads. By prescriber expansion rate, metabolic disorders is climbing the fastest.
End User:
Customer type determines compliance infrastructure requirements, with hospital systems absorbing REMS administrative burdens that burden smaller outpatient operators.
- Hospitals:Integrated health systems with certified prescriber networks and in-house pharmacy capabilities that streamline controlled-substance handling and patient registry maintenance.
- Specialized Clinics:Outpatient obesity clinics with dedicated bariatric programs and established prior authorization workflows, particularly concentrated in urban United States markets.
- Outpatient Care Centers:Primary care and multi-specialty settings where GLP-1 substitution elasticity is displacing first-line anorexiant prescriptions in commercially insured populations.
- Wellness Facilities:Lifestyle medicine and corporate health programs with limited pharmaceutical dispensing, serving as referral sources rather than direct prescribing sites.
By prescription volume, hospitals lead. By patient acquisition efficiency, specialized clinics is gaining share fastest.
Distribution Channel:
Geography of dispensing shapes regulatory exposure, with cross-jurisdictional online pharmacies navigating fragmented controlled-substance scheduling across United States, Canadian, and Japanese markets.
- Retail Pharmacies:Chain and independent pharmacies with established DEA registration and inventory tracking systems, capturing the majority of phentermine and diethylpropion volume.
- Online Pharmacies:Direct-to-consumer platforms conducting asynchronous BMI verification and comorbidity screening, collapsing geographic access barriers that previously concentrated prescribing in urban centers.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks, enabling hub-and-spoke models for REMS-compliant products that reduce handling complexity.
- Wholesale Distributors:Secondary channel for generic orlistat and legacy sympathomimetics, with inventory concentration exposing formulators to import inspection delays from Indian and Chinese API manufacturers.
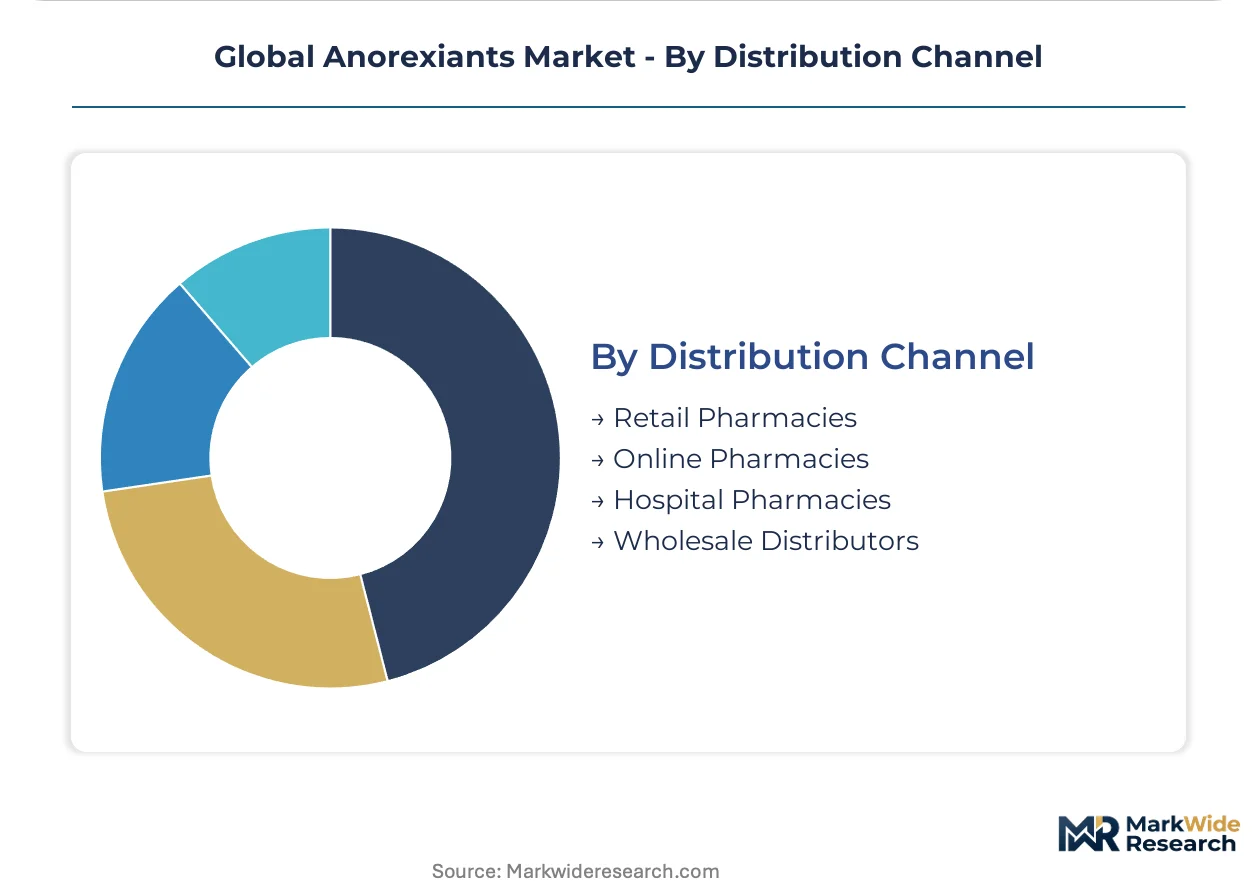
By transaction volume, retail pharmacies lead. By expansion trajectory, online pharmacies is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks for pharmacological weight management are maturing across multiple jurisdictions, concentrating demand in markets where statutory insurers recognize obesity as a chronic disease indication. The FDA's REMS infrastructure and Germany's DiGA pathway exemplify how regulatory design shapes commercial access for controlled-substance and OTC anorexiants respectively.
United States
Employer-sponsored health benefit designs are tiering GLP-1 coverage ahead of legacy sympathomimetics in Fortune 500 manufacturing and logistics sectors where workforce BMI distributions drive premium calculations. The FDA's DEA Schedule IV framework and REMS compliance requirements create formulary predictability that retail pharmacy chains leverage for inventory planning. Hospital-based obesity management protocols in integrated health systems are expanding prescriber pools beyond endocrinology into cardiology and sleep medicine in urban centers.
Germany
Statutory health insurers are expanding reimbursement for pharmacological obesity interventions through the DiGA pathway, creating bundled prescribing opportunities where anorexiants pair with app-based behavioral monitoring. The EMA's pharmacovigilance requirements under EU MDR shape product labeling and post-market surveillance obligations for orlistat-containing formulations. Manufacturing and distribution clusters in North Rhine-Westphalia and Bavaria are investing in patient registries that track long-term metabolic endpoints beyond weight reduction.
Japan
Metabolic disorder protocols are commanding premium pricing through endocrinology specialist access as the PMDA maintains prescription-only status for phentermine derivatives. Health system reforms are recalibrating cost-effectiveness thresholds for weight management interventions in aging populations with elevated diabetes comorbidity burdens. Tokyo and Osaka medical centers are pioneering fixed-dose combination formulations that address polypharmacy adherence gaps in metabolic syndrome patients.
Canada
Health Canada's PMRA maintains parallel controlled-substance scheduling that limits cross-border product standardization for phentermine derivatives with the United States. Provincial formularies are narrowing pharmacy networks for weight management medications, forcing manufacturers to demonstrate cost-offset through reduced orthopedic and diabetes-related claims. Ontario and Quebec health systems are absorbing REMS administrative burdens that burden smaller outpatient clinic operators in Atlantic provinces.
United Kingdom
NHS England's specialized commissioning frameworks are tiering access to obesity pharmacotherapy based on BMI thresholds and comorbidity profiles. The MHRA's post-Brexit regulatory autonomy is permitting faster market entry sequencing for novel anorexiant formulations than EU harmonization timelines. London and Southeast England obesity clinics are capturing patient acquisition efficiency through telemedicine prescribing infrastructure that conducts asynchronous BMI verification and comorbidity screening.
Global Anorexiants Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated peptide manufacturers and fragmented among generic sympathomimetic formulators with divergent channel strategies. Three strategic archetypes dominate: GLP-1 adjacent positioning through captive production networks, specialized channel control in outpatient obesity clinics, and broad retail pharmacy distribution for legacy phentermine portfolios. Competitive moves concentrate on fixed-dose combination development and hub-and-spoke specialty pharmacy partnerships that reduce REMS handling complexity.
Within the vertically integrated tier, Novo Nordisk A/S anchors positioning through its peptide production network. Currax Pharmaceuticals LLC and Pfizer Inc. occupy contrasting channel archetypes, with the former exemplifying specialized clinic-focused distribution and the latter representing broad retail pharmacy reach for established sympathomimetic formulations. These three entities collectively illustrate how supply-side configuration maps to divergent patient access points across controlled-substance and OTC regulatory pathways.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Currax Pharmaceuticals LLC |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Lannett Co. Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson Services Inc. |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Indian and Chinese contract manufacturers cluster sympathomimetic API synthesis, concentrating margin capture downstream in REMS-compliant specialty pharmacy networks where formulary predictability commands premium positioning against generic retail channels.
Pricing Analysis
Certification level creates the primary spread across the anorexiants market, with FDA REMS-certified formulations capturing premium positioning against DEA Schedule IV generics. Three-tier pricing structure across branded extended-release, authorized generic, and commodity phentermine reflects prescriber enrollment burdens and patient registry maintenance costs. Pricing pressure stems from GLP-1 substitution elasticity in employer-sponsored plans, compressing first-line sympathomimetic reimbursement. Self-pay patients in direct-to-consumer channels exhibit lowest price sensitivity, while Medicaid formularies drive aggressive generic substitution.
Supply Chain Analysis
Upstream feedstock for phentermine derivatives concentrates in Gujarat and Zhejiang manufacturing clusters, with diethylpropion API sourcing similarly anchored in Indian pharmaceutical export zones. Key inputs include ephedrine precursor chemicals, specialized reactor vessels for controlled-substance synthesis, and tamper-evident packaging for DEA compliance. Single-source vulnerability runs through concentrated API import inspection points, exposing formulators to FDA enforcement delays. Distribution runs through hub-and-spoke specialty pharmacy models for REMS products, while generic orlistat flows through direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated health systems and self-insured employers, consolidating procurement leverage that fragments pricing power among legacy sympathomimetic manufacturers.
For Market Incumbents: Insulate formulary position by deepening backward integration into peptide-adjacent production networks and securing exclusive specialty pharmacy partnerships for REMS administration. GLP-1 displacement threatens phentermine volume; vertical control over manufacturing insulates margin pools from API cost volatility. For New Entrants and Emerging Players: Pursue Germany's DiGA reimbursement pathway for bundled digital-therapeutic combinations, where statutory insurer appetite for app-based behavioral monitoring creates white-space for novel anorexiant positioning. Online pharmacy direct-to-consumer channels offer lowest regulatory barriers for orlistat-containing formulations. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-tier firms with captive API supply and established REMS infrastructure, positioned to capture share as GLP-1 access constraints persist. The signal to watch is employer health plan tiering decisions that resequence obesity pharmacotherapy protocols.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Program Certification | Enables formulary access in integrated delivery networks with certified prescriber pools. |
| Fixed-Dose Combination Development | Addresses polypharmacy adherence gaps in metabolic syndrome patient populations. |
| Specialty Pharmacy Partnership | Reduces handling complexity for controlled substances while capturing patient outcome data. |
| Digital Health Integration | Aligns with Germany's DiGA pathway for statutory insurer reimbursement bundling. |
| API Manufacturing Scale-Up | Mitigates import inspection exposure from concentrated Indian and Chinese supply. |
Research Methodology
Desk research of FDA REMS documentation, DEA controlled-substance scheduling records, and statutory insurer formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov entries, EMA pharmacovigilance reports, and CMS Medicare Part D claims patterns. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated against manufacturer revenue disclosures.
Assumptions held fixed include current DEA Schedule IV classification for sympathomimetics, existing GLP-1 reimbursement tiering in employer plans, and stable EMA MDR surveillance requirements. Segmentation dimensions spanned product type, therapy area, end-user setting, and distribution channel. CAGRs were derived from prescription volume trajectories and average selling price trends across the projection horizon, incorporating patent expiry schedules and authorized generic entry patterns.
Macroeconomic conditions sit as an overlay; deviation in statutory health spending growth, employer premium contribution rates, or API import tariff regimes would shift the trajectory. Cross-checking against IQVIA prescription audit data and Symphony Health claims benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Global Paracetamol Market