
 Posaconazole Market | 2026-2036
Posaconazole Market Size, Share, and Industry Trends Forecast 2026-2036
Posaconazole Market Insights
Maintenance contracts for therapeutic drug monitoring are pivoting how posaconazole vendors structure hospital relationships. Merck & Co., Inc. leverages its original formulation expertise to sustain institutional loyalty across academic medical centers. Organon International anchors its position through geographic dominance in European hospital networks. Solara Active Pharma Sciences competes on manufacturing scale for oral suspension supply to emerging markets.
Posaconazole is a triazole antifungal agent with a broad spectrum of activity against Aspergillus and Candida species, formulated as delayed-release tablets containing 100 mg of the active compound for oral administration. It functions primarily as a prophylactic and therapeutic agent in patients with hematologic malignancies, stem cell transplants, or prolonged neutropenia who face elevated risk of invasive fungal infections. Tablet formulations command the deepest margin pools due to bioavailability advantages and patient compliance benefits over oral suspension. Prophylaxis applications represent the fastest-expanding therapy area as transplant protocols standardize antifungal coverage. Hospital pharmacies remain the dominant distribution node, though specialty pharmacies are capturing growing share in outpatient oncology settings.
FDA bioequivalence requirements for generic posaconazole shape product development timelines and market access conditions for manufacturers seeking abbreviated new drug approvals. EMA's orphan drug incentives and REACH compliance obligations for active pharmaceutical ingredient imports influence European supply strategies and pricing structures. CDSCO's phased manufacturing standards for imported antifungals in India create regulatory differentiation between established multinationals and domestic formulators. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar guidance documents that will determine competitive positioning in prophylactic antifungal therapy.
Market Dynamics
Hospital consolidation across the United States is compressing formulary decisions into centralized pharmacy committees, forcing posaconazole suppliers to restructure contract negotiations around therapeutic drug monitoring bundles rather than unit pricing.
Growth Catalysts
- Transplant protocol standardization:Stem cell transplant centers in the United States are embedding posaconazole prophylaxis into neutropenia management pathways, creating institutional demand lock-in.
- FDA abbreviated approval pathways:Streamlined bioequivalence requirements for generic antifungals are accelerating competitive entry and expanding patient access to prophylactic therapy.
- Delayed-release tablet bioavailability:Superior pharmacokinetic profiles versus oral suspension formulations are driving formulary preference shifts in academic medical centers.
Market Restraints
- Active pharmaceutical ingredient concentration:Chinese manufacturers dominate azole intermediate supply, exposing formulators to geopolitical disruption risk and import tariff volatility.
- Therapeutic drug monitoring cost structure:Specialized laboratories and trained clinical pharmacists required for posaconazole level interpretation inflate total cost of care beyond drug acquisition.
- Fluconazole substitution threat:Lower-cost triazole alternatives retain formulary preference in Candida-prophylaxis-only indications, constraining posaconazole expansion.
Strategic Opportunities
- Outpatient oncology channel expansion:Specialty pharmacies in the United States are capturing growing share of oral antifungal dispensing as transplant protocols shift to ambulatory care models.
- EMA orphan drug incentives:European regulatory pathways for rare disease indications offer extended market exclusivity and premium pricing potential for pediatric formulations.
- CDSCO phased manufacturing standards:India's evolving import requirements create first-mover advantage for domestic formulators meeting stepped compliance obligations.
Industry Challenges
- Clinical pharmacology talent scarcity:Qualified therapeutic drug monitoring specialists are concentrated in major academic medical centers, limiting service model scalability.
- Bioanalytical method transfer complexity:LC-MS/MS assay validation for posaconazole quantification requires specialized equipment and regulatory documentation that delays laboratory network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Posaconazole Market |
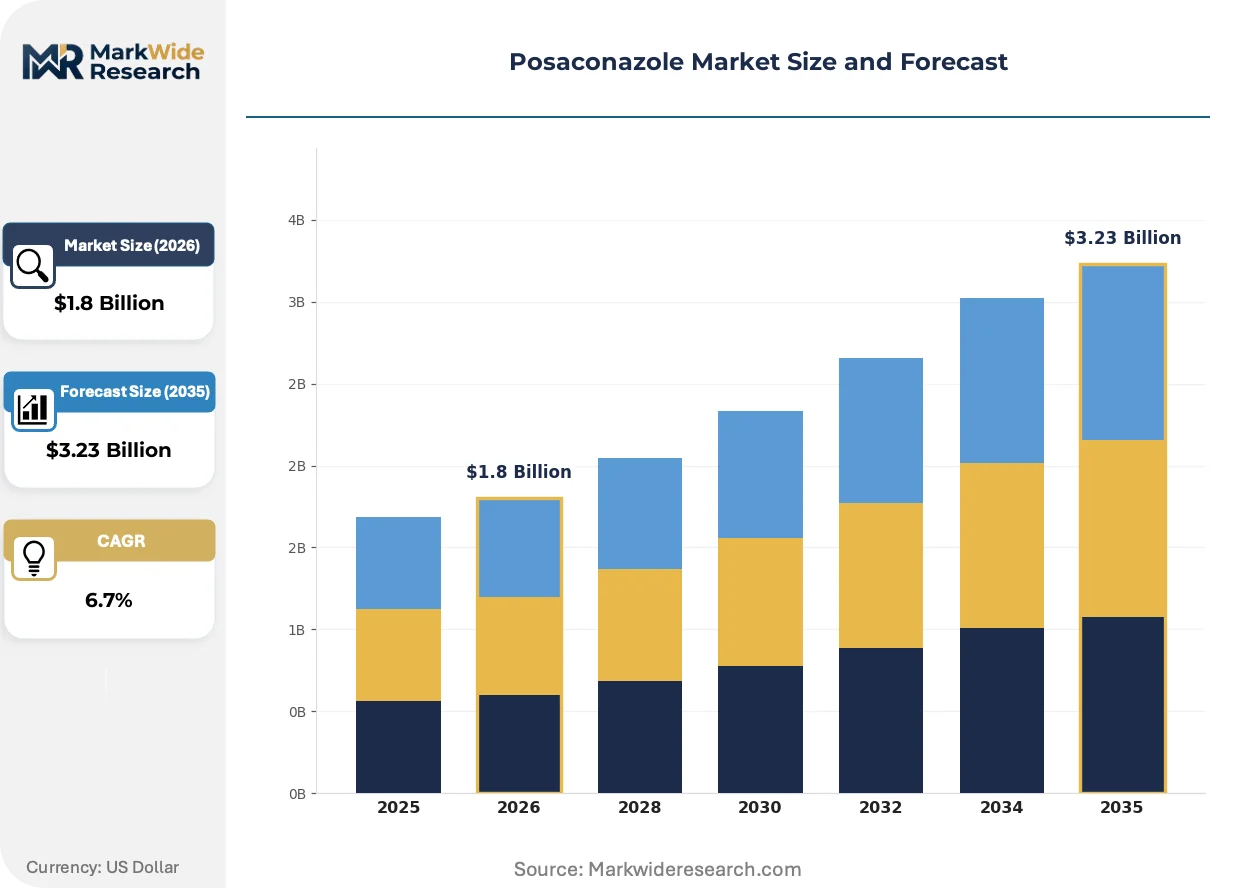
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Suspension, Injectable, Powder Form Therapy Area: Fungal Infections, Prophylaxis, Onychomycosis, Systemic Mycoses End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | Merck & Co., Inc., Thermo Fisher Scientific Inc., Organon International, BrightGene Bio-Medical Technology, Rochem International Inc., Tecoland Corporation, Solara Active Pharma Sciences, Beijing Lunarsun Pharmaceutical Co., Ltd., Aspen Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Posaconazole Market Trends and Innovations
Point-of-care diagnostic integration is reshaping how antifungal therapy is initiated and monitored, shifting clinical decision-making from centralized laboratories to bedside protocols.
Oral suspension reformulation with enhanced bioavailability excipients is decentralizing prophylaxis initiation from inpatient to outpatient settings. Transplant centers in the United States are adopting these formulations for pre-transplant fungal prophylaxis. The technology is compressing hospital length-of-stay metrics and expanding addressable patient populations.
EMA's updated pharmacovigilance mandates for antifungal agents are intensifying post-market surveillance obligations across European hospital networks. Manufacturers must now submit periodic safety update reports with real-world evidence from institutional registries. This regulatory pressure is favoring established suppliers with dedicated medical affairs infrastructure over emerging entrants.
Consolidated purchasing organizations are unbundling drug procurement from clinical pharmacy services in the United States. Hospital systems are negotiating posaconazole contracts separately from therapeutic drug monitoring agreements, fragmenting vendor relationships. This behavioral shift is most pronounced in multi-hospital health systems with centralized formulary control.
Posaconazole Market Segmentation
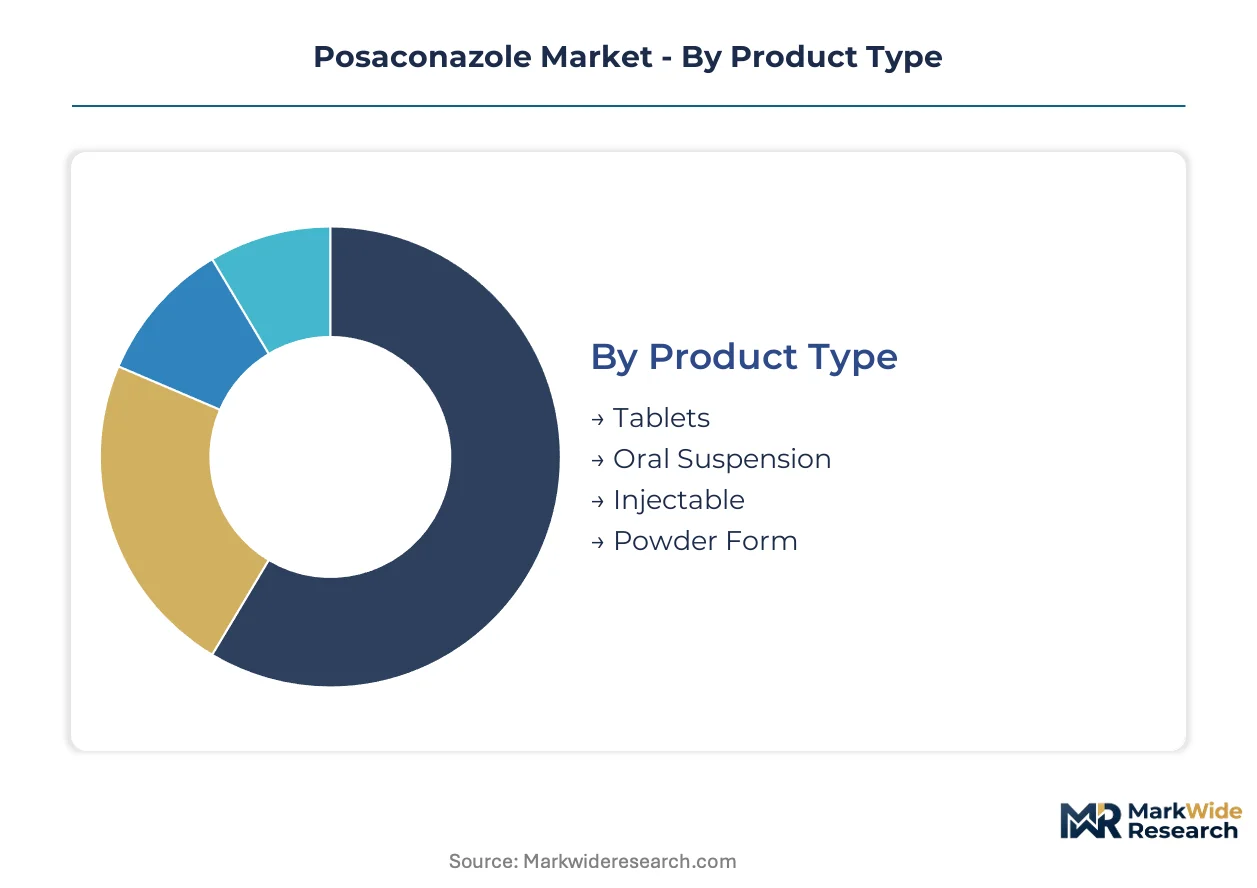
Posaconazole procurement decisions split across formulation preferences, clinical setting requirements, and supply chain reliability demands. Understanding these segment boundaries clarifies where vendors must differentiate versus where scale economics dominate competitive positioning.
Product Type:
Hospital formulary committees weigh bioavailability profiles against total cost of care when selecting formulations for prophylaxis protocols.
- Tablets:Delayed-release 100 mg tablets deliver superior pharmacokinetic stability with reduced food-effect variability. Academic medical centers in the United States prioritize tablet formulations for outpatient stem cell transplant prophylaxis due to compliance monitoring advantages. These formulations anchor the deepest margin pools through premium pricing justified by therapeutic drug monitoring efficiency.
- Oral Suspension:Aqueous formulations containing 40 mg/mL posaconazole serve inpatient initiation protocols where swallowing function is compromised. Emerging markets in India favor suspension supply from domestic CDSCO-compliant manufacturers for cost-sensitive hospital procurement. Reformulation with enhanced bioavailability excipients is expanding outpatient eligibility for this traditionally inpatient-limited delivery form.
- Injectable:Intravenous formulations address breakthrough infections in patients unable to tolerate enteral administration during prolonged neutropenia.
- Powder Form:Bulk active pharmaceutical ingredient powder supplies compounding pharmacies and institutional preparation facilities with formulation flexibility.
Volume sits with oral suspension in emerging markets; growth tilts toward delayed-release tablets in transplant center consolidation.
Therapy Area:
Reimbursement pathways and protocol standardization determine which indications drive procurement scale versus pricing power.
- Prophylaxis:Preventive administration in hematologic malignancy and stem cell transplant patients represents the steepest expansion trajectory as institutional protocols hardwire antifungal coverage into neutropenia management. United States transplant centers now embed posaconazole prophylaxis as default standard of care, creating demand lock-in through clinical pathway integration.
- Fungal Infections:Treatment of documented invasive aspergillosis and refractory candidiasis in immunocompromised hosts requires therapeutic drug monitoring and dose optimization. Hospital pharmacy budgets allocate premium resources here for salvage therapy in failed fluconazole cases.
- Systemic Mycoses:Disseminated fungal disease management in solid organ transplant recipients commands specialized infectious disease consultation.
- Onychomycosis:Dermatologic nail infection applications remain niche due to cost positioning against topical alternatives and terbinafine.
Revenue concentrates in prophylaxis; clinical complexity peaks in refractory fungal infection treatment.
End User:
Site-of-care migration is fragmenting traditional hospital-centric distribution toward ambulatory and home-based administration models.
- Hospitals:Inpatient hematology-oncology units and transplant wards administer the majority of posaconazole through centralized pharmacy operations. Consolidated purchasing organizations across United States health systems are unbundling drug procurement from clinical pharmacy services, forcing separate contract negotiations.
- Specialty Pharmacies:United States outpatient oncology channels are capturing growing oral antifungal dispensing volume as transplant protocols shift to ambulatory care models. These pharmacies bundle therapeutic drug monitoring with medication delivery, creating stickier patient relationships than traditional retail.
- Clinics:Community oncology practices with limited on-site pharmacy capabilities rely on external specialty pharmacy partnerships for patient access.
- Homecare Settings:Post-transplant patients on extended prophylaxis receive home nursing support for medication administration and adverse event monitoring.
Procurement authority rests with hospital pharmacy committees; patient volume migrates toward specialty pharmacy channels.
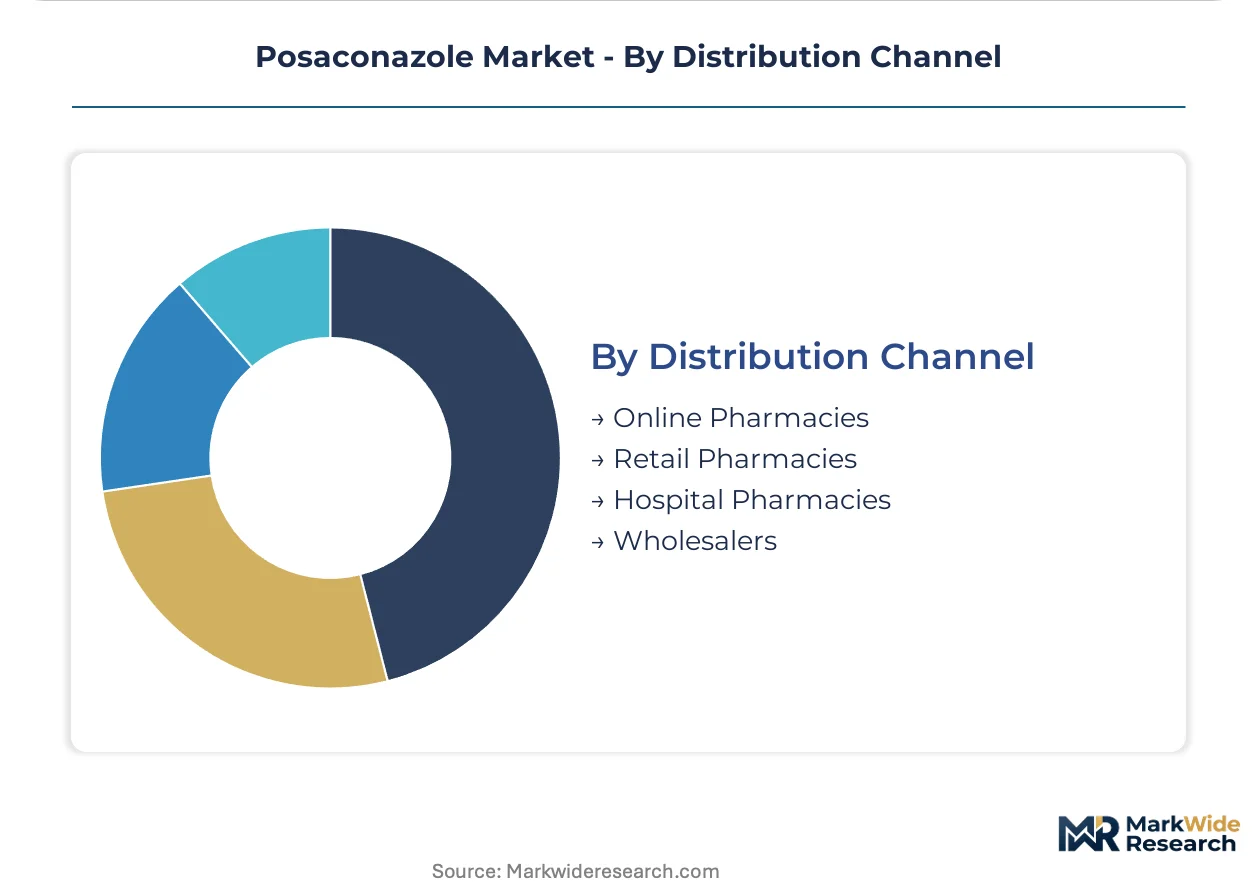
Distribution Channel:
Channel selection reflects urgency requirements, formulary control points, and inventory carrying cost tolerance across the supply chain.
- Hospital Pharmacies:Institutional procurement dominates posaconazole volume through 340B pricing eligibility and therapeutic drug monitoring integration. Centralized formulary committees at multi-hospital systems compress vendor relationships toward preferred supplier contracts with bundled service agreements.
- Wholesalers:AmerisourceBergen, McKesson, and Cardinal Health distribute to retail and specialty pharmacy networks with cold-chain compliance for temperature-sensitive formulations. These intermediaries manage inventory risk for manufacturers while capturing margin through distribution fees.
- Retail Pharmacies:Community pharmacy dispensing remains limited for posaconazole due to prior authorization requirements and specialty handling needs.
- Online Pharmacies:Mail-order channels serve stable outpatient prophylaxis patients with predictable refill patterns and insurance-mandated 90-day supply requirements.
Margin capture favors hospital direct contracting; network reach depends on wholesale distribution partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation production clusters in India and China supply active pharmaceutical ingredients to consuming markets in the United States and Europe. Transplant center density and regulatory pathway efficiency determine regional demand intensity and pricing power.
United States
Academic medical centers in Boston, Houston, and Seattle drive posaconazole consumption through standardized stem cell transplant protocols. FDA's abbreviated new drug approval pathways accelerate generic entry and expand patient access. The 340B drug pricing program at major transplant hospitals creates procurement concentration in consolidated health systems.
Germany
University hospitals in Munich, Heidelberg, and Berlin anchor European demand for prophylactic antifungal therapy in hematology-oncology units. EMA's orphan drug incentives and REACH compliance obligations shape European supply strategies and pricing structures. The country's therapeutic drug monitoring infrastructure supports precision dosing in transplant protocols.
India
Domestic manufacturers in Hyderabad, Mumbai, and Ahmedabad supply oral suspension formulations to cost-sensitive hospital procurement. CDSCO's phased manufacturing standards for imported antifungals create regulatory differentiation between established multinationals and domestic formulators. The country's active pharmaceutical ingredient production clusters export azole intermediates globally.
China
Specialized chemical manufacturers in Zhejiang and Jiangsu provinces dominate azole intermediate supply for global posaconazole synthesis. NMPA's bioequivalence requirements for generic antifungals influence product development timelines for domestic formulators. The country's concentration in API production exposes formulators to geopolitical disruption risk.
Switzerland
Specialty pharmaceutical operations in Basel and Zurich focus on high-purity API production and clinical trial supply. Swissmedic's regulatory framework supports early-access programs for antifungal therapies in rare disease indications. The country's precision manufacturing infrastructure serves European hospital network demand.
Posaconazole Market Competitive Landscape
Top-tier vendors anchor institutional formulary relationships through therapeutic drug monitoring bundles, while mid-tier manufacturers compete on manufacturing scale and geographic reach. The vendor base stratifies across originator formulation expertise, generic manufacturing capacity, and active pharmaceutical ingredient supply. Three archetypes dominate: multinational pharmaceutical companies with hospital pharmacy channel control, contract manufacturing organizations with API-to-finished-dose capabilities, and regional formulators with domestic regulatory approvals. Competitive moves concentrate on strategic partnerships for therapeutic drug monitoring service integration and capacity expansion in CDSCO-compliant manufacturing facilities.
Among originator-expertise multinationals, Merck & Co., Inc. and Organon International exemplify the institutional loyalty archetype through sustained academic medical center relationships. Solara Active Pharma Sciences occupies a position within the manufacturing-scale tier, competing on oral suspension supply to emerging markets. These three companies represent the competitive spectrum from premium formulation development to cost-optimized production.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Thermo Fisher Scientific Inc. |
| Organon International |
| BrightGene Bio-Medical Technology |
| Rochem International Inc. |
| Tecoland Corporation |
| Solara Active Pharma Sciences |
| Beijing Lunarsun Pharmaceutical Co., Ltd. |
| Aspen Holdings |
| Others |
Pricing and Supply Chain Analysis
Delayed-release tablet bioavailability advantages are compressing cost economics for oral suspension manufacturers while simultaneously concentrating formulation expertise among FDA-validated production facilities. This technological bifurcation rewards suppliers with therapeutic drug monitoring integration capabilities and penalizes pure-play generic formulators lacking hospital pharmacy service bundles.
Pricing Analysis
Margin tightening in oral suspension tiers reflects CDSCO-compliant domestic manufacturing scale advantages in India. Three-tier pricing structure across premium, standard, and economy levels separates patented delayed-release formulations from bioequivalent generics and unbranded hospital procurement contracts. Pricing pressure intensifies in emerging markets as Chinese API suppliers consolidate azole intermediate production. Academic medical centers in the United States exhibit lowest price sensitivity due to bundled therapeutic drug monitoring contracts, while Indian district hospitals prioritize economy-tier suspension supply.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Jiangsu province manufacturers dominating azole intermediate synthesis for global posaconazole production. Active pharmaceutical ingredient supply draws from China, India, and Switzerland, with finished dose formulation concentrated in United States and European Union facilities. Raw material dependencies include triazole intermediates, hydroxypropyl methylcellulose excipients, and specialized coating polymers. Tariff exposure on Chinese chemical imports threatens cost structures for non-vertically integrated formulators. Distribution runs through hospital pharmacy direct contracting for institutional volume and wholesale intermediaries for specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints in CDSCO-validated facilities prop premium pricing for compliant suppliers, creating a supply-constrained market structure favoring incumbent consolidation.
For Market Incumbents: Cement institutional loyalty through exclusive therapeutic drug monitoring service contracts that bundle delayed-release tablet supply with clinical pharmacist consultation. Expand backward integration into azole intermediate production to insulate margins from Chinese supply disruption. Prioritize EMA orphan drug pathway investments for pediatric formulation exclusivity against emerging generic entrants. For New Entrants and Emerging Players: Digital pharmacy platform partnerships offer the lowest-friction route to outpatient oncology channel access without hospital formulary committee barriers. Target specialty pharmacy dispensing in United States ambulatory transplant centers where therapeutic drug monitoring bundling creates stickier relationships than pure price competition. Pursue CDSCO phased manufacturing compliance for oral suspension supply to Indian district hospital procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational pharmaceutical companies seeking therapeutic drug monitoring service infrastructure. Long-term viability hinges on regulatory compliance depth rather than manufacturing scale alone. Monitor FDA abbreviated new drug approval velocity as the critical inflection signal for generic competitive intensity and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Therapeutic Drug Monitoring Service Integration | Bundled clinical pharmacist consultation locks hospital formulary preference against pure price competitors. |
| CDSCO Manufacturing Compliance Investment | Phased domestic production standards in India create regulatory moat for emerging market supply contracts. |
| EMA Orphan Drug Pathway Pursuit | Extended exclusivity for pediatric formulations commands premium pricing in European hospital networks. |
| Azole Intermediate Backward Integration | Captive API supply insulates margin from Chinese tariff exposure and geopolitical disruption risk. |
| Specialty Pharmacy Channel Partnership | Ambulatory oncology dispensing captures patient volume migrating from inpatient transplant protocols. |
Research Methodology
Multi-period observation of FDA abbreviated new drug approval filings, EMA orphan drug designations, and CDSCO manufacturing compliance certifications anchored the trend analysis, supplemented by interviews with hospital formulary directors, specialty pharmacy procurement managers, clinical pharmacists in transplant centers, and regulatory affairs leads at generic manufacturers. Secondary validation drew from FDA Orange Book listings, EMA EPAR documents, ClinicalTrials.gov protocol registries, and Indian pharmaceutical export data. Bottom-up patient volume modeling across therapy areas triangulated against top-down health system procurement spend estimates.
Segment-weighting across formulation type, therapy area, end-user site of care, and regional regulatory cluster determined value allocation throughout the forecast period. CAGRs derived from protocol standardization adoption curves in United States transplant centers and CDSCO compliance progression timelines in India. Industry-specific forecast inputs included hematologic malignancy incidence projections and stem cell transplant center capacity expansion plans.
The model holds under stable FDA bioequivalence requirements and EMA pharmacovigilance mandates; deviation in CDSCO import restriction timing or Chinese API export licensing would shift competitive positioning materially. Forecasts reflect documented assumptions regarding protocol standardization velocity and therapeutic drug monitoring reimbursement stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Anorexiants Market