
 Anti-Viral Therapeutics Market | 2026-2036
Anti-Viral Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Viral Therapeutics Market Outlook
RNA-targeting nucleoside chemistries is realigning cost structures across antiviral manufacturing, displacing older small-molecule synthesis routes that required lengthier purification stages. Gilead Sciences Inc. leverages captive nucleotide prodrug platforms to sustain margin capture on hepatitis and respiratory portfolios. Merck & Co., Inc. anchors its position through oral antiviral formulations that compete directly with infusion-dependent alternatives. F. Hoffmann-La Roche Ltd differentiates via polymerase chain diagnostics paired with companion therapeutic positioning.
Anti-viral therapeutics constitute synthetic or biologically derived agents engineered to interrupt viral replication cycles through enzymatic inhibition, genome integration blockade, or capsid assembly disruption, typically formulated for systemic circulation with half-life optimization spanning eight to twenty-four hours. Their primary purpose centers on reducing viral load, preventing disease progression, and limiting transmission in infected populations. Nucleoside Analogues and Polymerase Inhibitors command the largest revenue pools due to established HIV and hepatitis treatment protocols, while Protease Inhibitors represent the fastest-expanding category as next-generation respiratory antivirals gain formulary placement. Oral delivery mode dominates prescription volume, though subcutaneous formulations are gaining share in homecare settings where patient self-administration reduces hospital burden.
The FDA's Breakthrough Therapy designation and EMA's PRIME scheme are compressing clinical development timelines, reshaping how sponsors prioritize pipeline candidates for expedited review. CDSCO in India and NMPA in China enforce localized bioequivalence standards that filter which imported antivirals reach government procurement lists. WHO prequalification remains the decisive gateway for volume access in low-income markets. Stakeholders must monitor how payer consolidation in the United States and Europe recalibrates pricing power for novel mechanisms against genericized incumbent classes.
Market Dynamics
RNA-targeting nucleoside chemistries are compressing manufacturing timelines and displacing legacy small-molecule synthesis routes that required extended purification stages. This technological inflection is redistributing margin capture toward integrated platform owners while fragmenting contract manufacturing relationships.
Growth Catalysts
- FDA Breakthrough Therapy designation:The pathway compresses Phase II-to-approval timelines for novel mechanisms, pulling investment toward high-unmet-need indications. Sponsors now prioritize candidates with biomarker-defined responder populations.
- Hospital standardization of acute care protocols:Emergency departments are embedding intravenous antiviral regimens into sepsis-like response workflows. This creates pull-through demand for companion diagnostics and infusion infrastructure.
- Specialty pharmacy networks:United States distribution is concentrating through limited-distribution channels that manage prior authorization and adherence monitoring. These networks anchor commercialization strategy for oral outpatient therapies.
Market Restraints
- Active pharmaceutical ingredient concentration:Nucleotide prodrug synthesis depends on captive production in India and China, exposing supply to export license volatility and geopolitical friction.
- CDSCO bioequivalence requirements:India's local testing mandates filter which imported antivirals reach government procurement lists, creating regulatory friction for multinational sponsors.
- Genericized incumbent classes:First-generation HIV nucleoside analogues face commoditization, compressing pricing power and forcing novel mechanisms to justify premium positioning through head-to-head outcomes data.
Strategic Opportunities
- WHO prequalification pathway:Low-income market access depends on this gateway, creating volume opportunity for sponsors willing to accept tiered pricing and localized manufacturing partnerships.
- Subcutaneous homecare formulations:Self-administration protocols reduce hospital burden and expand addressable patient populations beyond infusion-capable centers.
- Polymerase chain diagnostics integration:Companion therapeutic positioning with point-of-care viral load monitoring enables test-and-treat models that capture value through outcomes guarantees.
Industry Challenges
- Nucleotide chemistry expertise scarcity:Phosphoramidate prodrug synthesis requires specialized skill sets concentrated at limited contract development organizations, creating bottlenecks for pipeline expansion.
- Accelerated approval evidence requirements:FDA confirmatory trial obligations demand post-market investment that strains smaller sponsors, particularly when surrogate endpoints require long-term follow-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Viral Therapeutics Market |
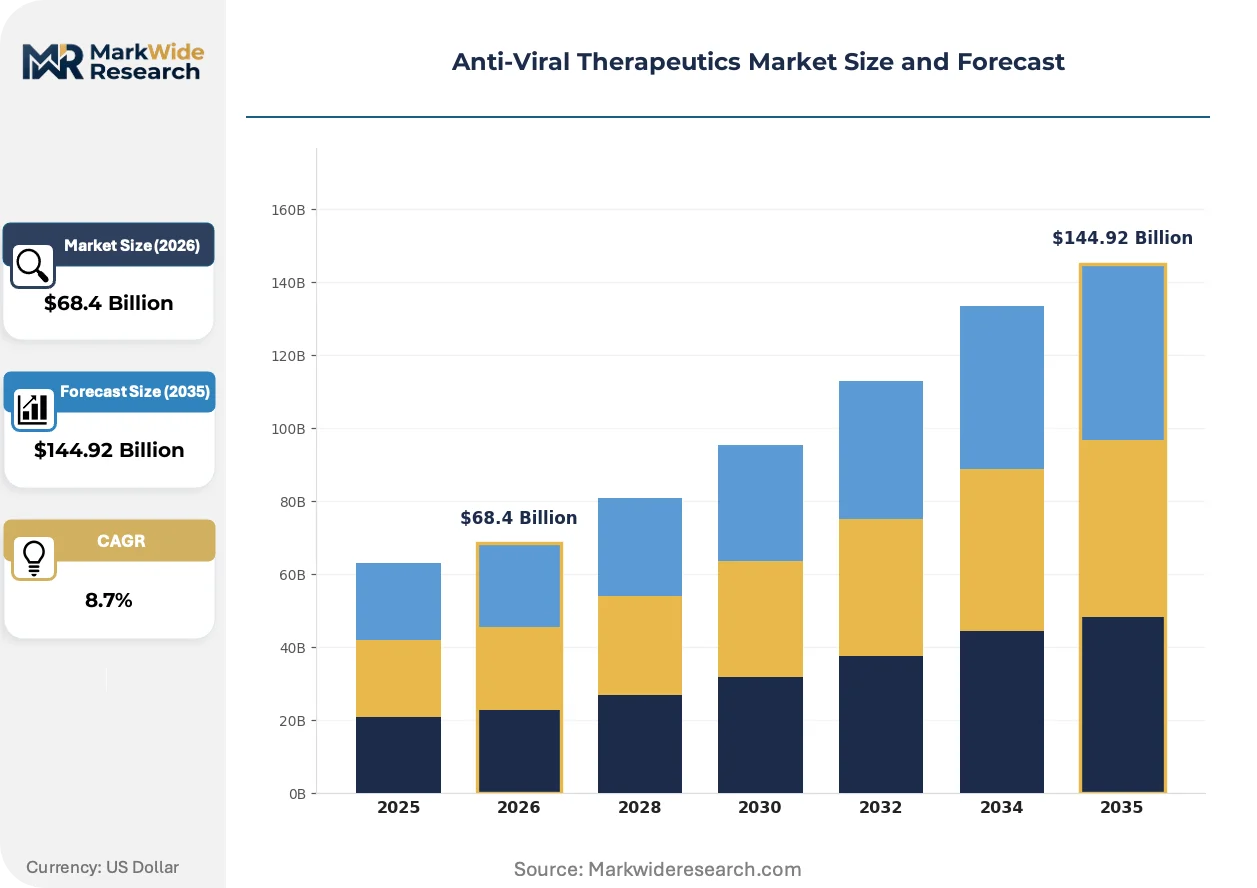
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleoside Analogues, Non-Nucleoside Inhibitors, Protease Inhibitors, Polymerase Inhibitors Therapy Area: HIV, Hepatitis, Influenza, Herpes Simplex Delivery Mode: Intravenous, Oral, Topical, Subcutaneous End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Gilead Sciences Inc., Merck & Co., Inc., F. Hoffmann-La Roche Ltd, AbbVie Inc., GlaxoSmithKline plc, Bristol-Myers Squibb Company, Johnson & Johnson, Cipla Inc., Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Viral Therapeutics Market Strategic Shifts
Antiviral development is converging on platform-based manufacturing and regulatory science that compresses the gap between preclinical validation and commercial supply. These shifts are redrawing competitive boundaries between integrated pharmaceutical companies and specialized biotechnology developers.
RNA-dependent RNA polymerase inhibitors are unifying previously separate antiviral categories by targeting conserved enzymatic domains across respiratory and hepatitis indications. Hospital systems are adopting these agents as first-line alternatives to infusion-dependent regimens. The technology is unifying manufacturing investments around single-platform flexibility that reduces campaign changeover costs.
EMA's PRIME scheme is accelerating access to scientific advice and accelerated assessment for medicines targeting unmet medical needs. This regulatory tailwind is pulling development investment toward European trial sites and manufacturing capacity. Hepatitis C combination therapies have benefited most directly, with several candidates receiving marketing authorization based on surrogate endpoints.
Specialty pharmacy networks are consolidating patient access services under single-source contracts that bundle distribution with adherence monitoring and outcomes reporting. This channel transformation displaces traditional wholesale relationships for high-cost oral antivirals. The United States Medicare Part D structure amplifies this concentration, where limited-distribution arrangements optimize rebate capture and risk-sharing agreements.
Anti-Viral Therapeutics Market Segmentation
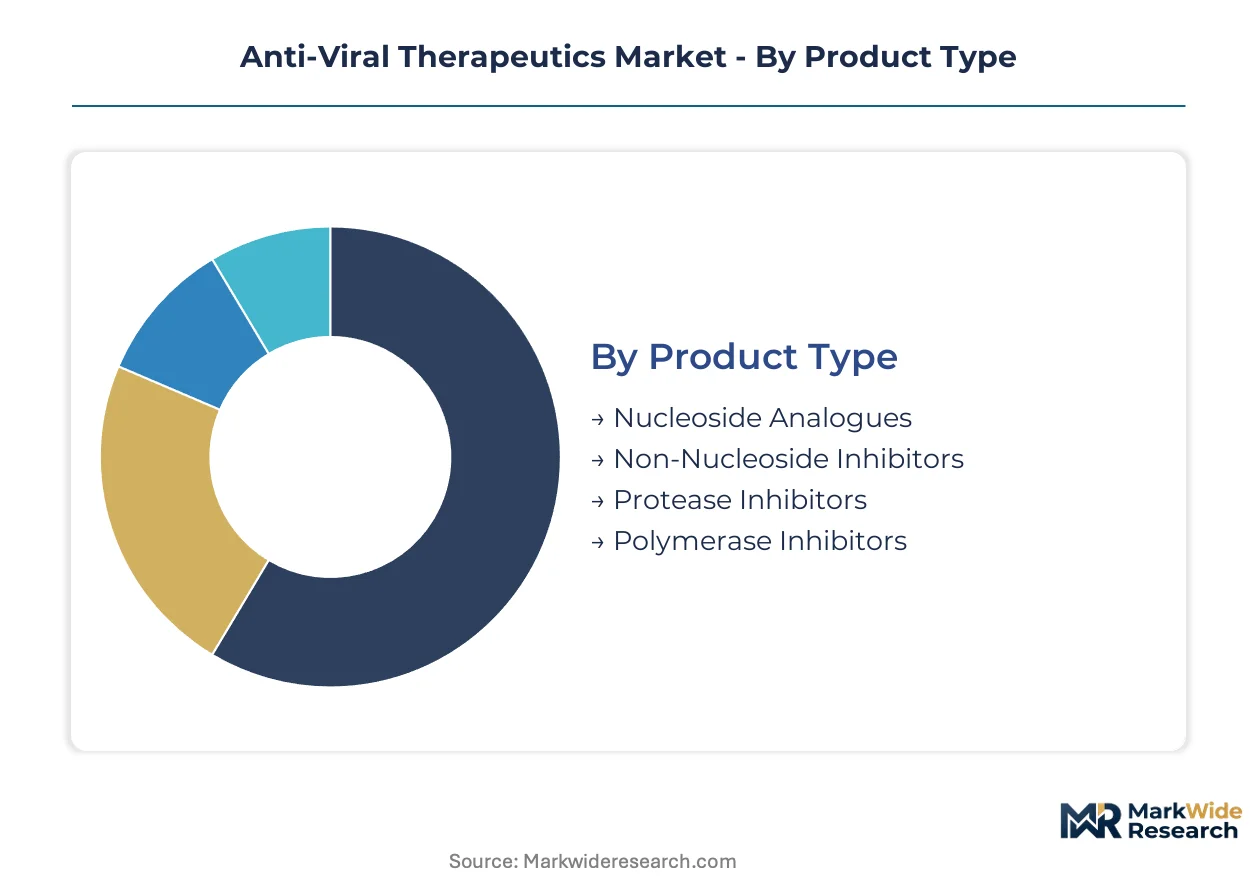
Antiviral market segmentation reveals how formulation chemistry, disease target, and care setting interact to determine commercial strategy. Technology platforms and regulatory pathways diverge sharply across these dimensions, reshaping where sponsors allocate development resources.
Product Type:
Nucleoside chemistry platforms anchor manufacturing investment and intellectual property positioning across antiviral portfolios.
- Nucleoside Analogues:Synthetic nucleoside mimics terminate viral DNA chain elongation through competitive substrate incorporation. Hospital procurement in the United States concentrates demand for established HIV and hepatitis regimens where Medicare reimbursement structures lock in formulary placement. CDSCO bioequivalence requirements in India filter which imported versions reach government tenders.
- Polymerase Inhibitors:Direct-acting enzymatic blockers target viral RNA-dependent RNA polymerase with higher specificity than nucleoside scaffolds. Emergency department protocols in acute care centers are embedding these agents into sepsis-like response workflows, creating pull-through demand for companion diagnostics. EMA's PRIME scheme accelerates assessment for candidates in this class.
- Protease Inhibitors:Peptidomimetic compounds obstruct viral maturation through active site occupation.
- Non-Nucleoside Inhibitors:Allosteric binders modulate viral enzyme conformation without competing at catalytic sites.
Mature deployment sits with Nucleoside Analogues. Newer deployment is concentrated in Polymerase Inhibitors.
Therapy Area:
Disease-specific development tracks diverge based on chronic versus acute treatment paradigms and payer concentration.
- HIV:Lifelong suppressive therapy creates recurring revenue pools anchored by Medicare Part D and specialty pharmacy networks in the United States. First-generation nucleoside analogues face genericization pressure, forcing novel mechanisms to justify premium positioning through head-to-head outcomes data against entrenched standards.
- Hepatitis:Curative intent protocols compress treatment duration while elevating per-course pricing power. EMA accelerated assessment pathways have benefited combination therapies most directly, with several candidates receiving marketing authorization based on surrogate endpoints. WHO prequalification opens volume access in low-income markets for sponsors accepting tiered pricing.
- Influenza:Seasonal demand spikes require flexible manufacturing campaigns and stockpiling arrangements with government purchasers.
- Herpes Simplex:Recurrent outbreak management drives prescription volume through retail pharmacy channels.
Revenue concentration peaks in HIV. Steepest expansion trajectory appears in Hepatitis curative protocols.
Delivery Mode:
Route of administration determines distribution infrastructure requirements and patient access economics.
- Oral:Small-molecule tablets and capsules dominate outpatient prescription volume through specialty pharmacy networks that bundle distribution with adherence monitoring. The United States Medicare structure amplifies this concentration, where limited-distribution arrangements optimize rebate capture and risk-sharing agreements for high-cost regimens.
- Intravenous:Hospital-based infusion protocols require sepsis-like response workflows and dedicated pharmacy infrastructure. Acute care standardization in emergency departments creates pull-through demand for companion diagnostics and infusion capacity expansion.
- Subcutaneous:Self-administration formats reduce hospital burden and extend addressable populations beyond infusion-capable centers.
- Topical:Localized application limits systemic exposure for superficial infections.
Prescription volume leadership belongs to Oral. Fastest share gain occurs in Subcutaneous homecare formats.
End User:
Care setting segmentation maps to reimbursement pathways and procurement authority concentration.
- Hospitals:Integrated delivery networks command procurement authority for intravenous regimens through formulary committees and acute care protocol design. Standardization of sepsis-like response workflows embeds antiviral administration into emergency department operations, creating locked-in demand for specific agents.
- Homecare:Self-administration protocols expand addressable populations beyond facility-based treatment capacity. Subcutaneous formulations gain traction where patient mobility or hospital capacity constraints limit infusion access, particularly in Medicare Advantage plans emphasizing cost avoidance.
- Clinics:Outpatient infusion centers bridge hospital and home settings for intermediate acuity.
- Research Institutions:Academic medical centers drive early adoption of novel mechanisms through investigator-initiated trials.
Procurement authority concentrates in Hospitals. Patient volume expansion is accelerating fastest in Homecare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biopharma corridor and Switzerland's Basel-Land tax zone concentrate antiviral R&D investment through accelerated depreciation schemes and patent box regimes. These fiscal structures pull manufacturing capacity toward established pharmaceutical clusters while regulatory harmonization efforts reshape cross-border commercialization timelines.
United States
Specialty pharmacy networks and Medicare Part D reimbursement structures anchor commercialization strategy for oral outpatient therapies. FDA Breakthrough Therapy designation compresses Phase II-to-approval timelines, pulling investment toward high-unmet-need indications. The Greater Boston biopharma corridor concentrates nucleotide prodrug platform development alongside Cambridge-based contract research organizations.
Switzerland
Basel-Land's patent box regime and cantonal R&D tax credits concentrate antiviral manufacturing investment for export-oriented production. Swissmedic maintains alignment with EMA accelerated assessment pathways while preserving sovereign approval authority for domestic market access. The Basel-Zurich corridor hosts integrated pharmaceutical companies with captive nucleoside chemistry capabilities.
India
CDSCO bioequivalence requirements filter which imported antivirals reach government procurement lists, creating regulatory friction for multinational sponsors. The country's national pharmaceutical regulator enforces localized testing mandates that protect domestic generic manufacturers. Hyderabad and Ahmedabad clusters specialize in active pharmaceutical ingredient synthesis for nucleotide prodrug intermediates.
China
NMPA's localized clinical trial requirements and import licensing protocols govern market access for novel antiviral mechanisms. The national medical products administration prioritizes domestic innovation through conditional approval pathways for breakthrough therapies. Shanghai and Suzhou biotech parks concentrate polymerase inhibitor development alongside state-backed venture capital deployment.
Germany
EMA's PRIME scheme accelerates scientific advice and assessment timelines for medicines targeting unmet medical needs. The European Medicines Agency's headquarters in Amsterdam coordinates with German national regulatory authority BfArM on decentralized procedures. The Rhine-Main and Munich biotech clusters specialize in companion diagnostic integration with antiviral therapeutic positioning.
Anti-Viral Therapeutics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies commanding nucleoside chemistry platforms while biotechnology developers rely on captive CDMO relationships. The vendor base concentrates around three archetypes: platform-integrated incumbents with captive manufacturing, specialty biotechnology developers with outsourced synthesis, and generic manufacturers with cost-optimized API sourcing. Dominant competitive moves include strategic partnerships for nucleotide prodrug synthesis capacity and geographic expansion through WHO prequalification pathways.
Within the platform-integrated tier, Gilead Sciences Inc. and Merck & Co., Inc. exemplify archetypes of nucleoside chemistry ownership and oral formulation commercialization respectively. F. Hoffmann-La Roche Ltd occupies a position emphasizing diagnostic-therapeutic bundling. These three entities represent distinct strategic postures: captive prodrug platform control, outpatient oral therapy focus, and companion diagnostic integration.
| Leading Market Players |
|---|
| Gilead Sciences Inc. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc. |
| GlaxoSmithKline plc |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Cipla Inc. |
| Aurobindo Pharma Limited |
| Others |
Value Chain & Pricing Dynamics
API pricing indices for nucleoside intermediates cascade through contract manufacturing tiers into three distinct procurement bands: captive synthesis for integrated sponsors, preferred CDMO partnerships for mid-cap developers, and spot-market sourcing for generic manufacturers facing Medicare reimbursement compression.
Pricing Analysis
Lead-time-driven pricing premiums attach to phosphoramidate prodrug campaigns requiring sub-six-month turnaround, while spot inventory of standard nucleoside scaffolds trades at discounts reflecting genericized HIV therapy competition. Pricing stratifies across premium, standard, and economy tiers based on FDA Breakthrough Therapy designation status and CDSCO bioequivalence certification level. Cost compression in first-generation nucleoside analogues is intensifying because Medicare Part D rebate structures favor formulary placement of established regimens. Generic manufacturers exhibit highest price sensitivity due to procurement list eligibility requirements, while specialty pharmacy networks absorb premium positioning for novel polymerase inhibitors.
Supply Chain Analysis
Single-source vulnerability sits with phosphoramidate prodrug synthesis capacity concentrated at Hyderabad and Ahmedabad contract development organizations. Active pharmaceutical ingredient production draws from India, China, and Switzerland for nucleotide intermediates, with captive fermentation capacity tethered to Basel-Land tax-advantaged zones. Isopropylalanine esters, phosphorochloridates, and pyrimidine bases constitute critical raw material dependencies. Export license volatility from India's DGFT creates regulatory friction disrupting campaign scheduling. Distribution runs through limited-distribution specialty pharmacy networks in the United States and hospital procurement consortia for intravenous regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphoramidate synthesis bottleneck concentration props pricing power for integrated platform owners while fragmenting access for pipeline-stage developers.
For Market Incumbents: Deploy captive nucleotide prodrug platform expansion to lock in margin capture against emerging biotechnology competitors outsourcing to capacity-constrained CDMOs. Secure backward integration into pyrimidine base synthesis to insulate from Indian export license volatility. Reinforce specialty pharmacy network exclusivity through Medicare Part D risk-sharing arrangements that generic manufacturers cannot replicate. For New Entrants and Emerging Players: Begin with subcutaneous homecare formulation development targeting Medicare Advantage plans emphasizing hospital cost avoidance, the most penetrable channel given infusion capacity constraints. Pursue WHO prequalification pathway for low-income market volume access where tiered pricing acceptance opens procurement relationships. Anchor go-to-market strategy through polymerase chain diagnostic bundling that captures value via test-and-treat outcomes guarantees. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotechnology developers with Phase II-ready polymerase inhibitors in the Greater Boston corridor, where nucleotide chemistry expertise scarcity creates acquisition scarcity value. Long-term viability centers on regulatory approval pathway ownership across FDA Breakthrough Therapy and EMA PRIME designations. Watch CDSCO bioequivalence requirement harmonization with WHO standards as the inflection signal for Indian market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses Phase II-to-approval timelines for novel RNA-targeting mechanisms in high-unmet-need indications. |
| Captive Nucleotide Prodrug Platform Investment | Locks margin capture for Gilead Sciences and integrated incumbents against fragmented CDMO relationships. |
| Specialty Pharmacy Network Exclusivity | Bundles distribution with adherence monitoring under Medicare Part D rebate-optimized arrangements. |
| WHO Prequalification Pathway Entry | Opens volume access in low-income markets for sponsors accepting tiered pricing and localized manufacturing. |
| Polymerase Chain Diagnostic Integration | Enables test-and-treat models with point-of-care viral load monitoring through F. Hoffmann-La Roche positioning. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA 510(k) submissions, EMA assessment reports, ClinicalTrials.gov entries, and CMS Medicare Part D spending data provided validation layers. Bottom-up prescription volume modeling and top-down revenue reconciliation triangulated market sizing across the analysis window.
Segment-level granularity applied nucleoside chemistry platform, therapy area, delivery mode, and end-user setting as core dimensions, with regional regulatory cluster differentiation for United States, Switzerland, India, China, and Germany. CAGRs were derived through log-linear trend fitting adjusted for patent expiry curves and generic entry timing. Forecast inputs incorporated hospital protocol standardization velocity, specialty pharmacy network consolidation rates, and CDSCO bioequivalence testing capacity constraints.
Regulatory pathway delays, API export license restrictions, and confirmatory trial outcome failures are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market