
 Global Aminoglycosides Market | 2026-2036
Global Aminoglycosides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aminoglycosides Market Foresight
Market Context
China's fermentation capacity expansion for aminoglycoside active pharmaceutical ingredients is narrowing the historical supply gap between Asian bulk manufacturers and Western finished-dose formulators. Pfizer Inc. leverages its hospital infectious disease franchise to sustain preferential formulary placement for parenteral gentamicin across major US health systems. Cipla Limited anchors its competitive position through backward integration into streptomyces fermentation and cost-optimized generic tobramycin supply for emerging markets. Teva Pharmaceutical Industries competes on manufacturing scale, operating multi-ton API facilities that feed both proprietary and contract finished-dose production.
Technical Definition and Segment Structure
Aminoglycosides constitute a class of bactericidal antibiotics derived from Streptomyces and Micromonospora species, characterized by an aminocyclitol nucleus linked to amino sugars via glycosidic bonds, with activity against aerobic Gram-negative bacilli through irreversible 30S ribosomal subunit binding. These agents serve primarily as second-line or combination therapy for hospital-acquired pneumonia, complicated urinary tract infections, and sepsis where beta-lactam resistance or patient intolerance limits first-line options. Gentamicin dominates the product type landscape due to its lowest cost per treatment course and established synergistic protocols with beta-lactams for enterococcal endocarditis, while amikacin captures the fastest growth trajectory as a reserve agent against carbapenem-resistant Enterobacterales. The intravenous delivery mode commands the largest revenue pool reflecting inpatient administration requirements and therapeutic drug monitoring protocols, though inhaled tobramycin for cystic fibrosis patients represents a concentrated margin segment with limited generic penetration.
Regulatory Framework and Outlook
The FDA's boxed warning requirements for nephrotoxicity and ototoxicity, combined with EMA pharmacovigilance obligations under the MDR framework, elevate post-market surveillance costs and constrain label expansion opportunities for manufacturers operating across both jurisdictions. India's CDSCO mandates batch release testing through central laboratories for imported aminoglycoside APIs, adding procedural friction that domestic fermentation-based producers circumvent through BIS-certified local supply chains. China's NMPA enforces progressively tighter impurity profiling for aminoglycoside submissions under updated pharmacopoeia standards, reshaping supplier qualification criteria for multinational finished-dose marketers. Stakeholders must monitor evolving resistance surveillance data from WHO GLASS and national health institutes to anticipate shifts in clinical guidelines that could abruptly reclassify specific aminoglycosides from essential to reserve therapy status.
Market Dynamics
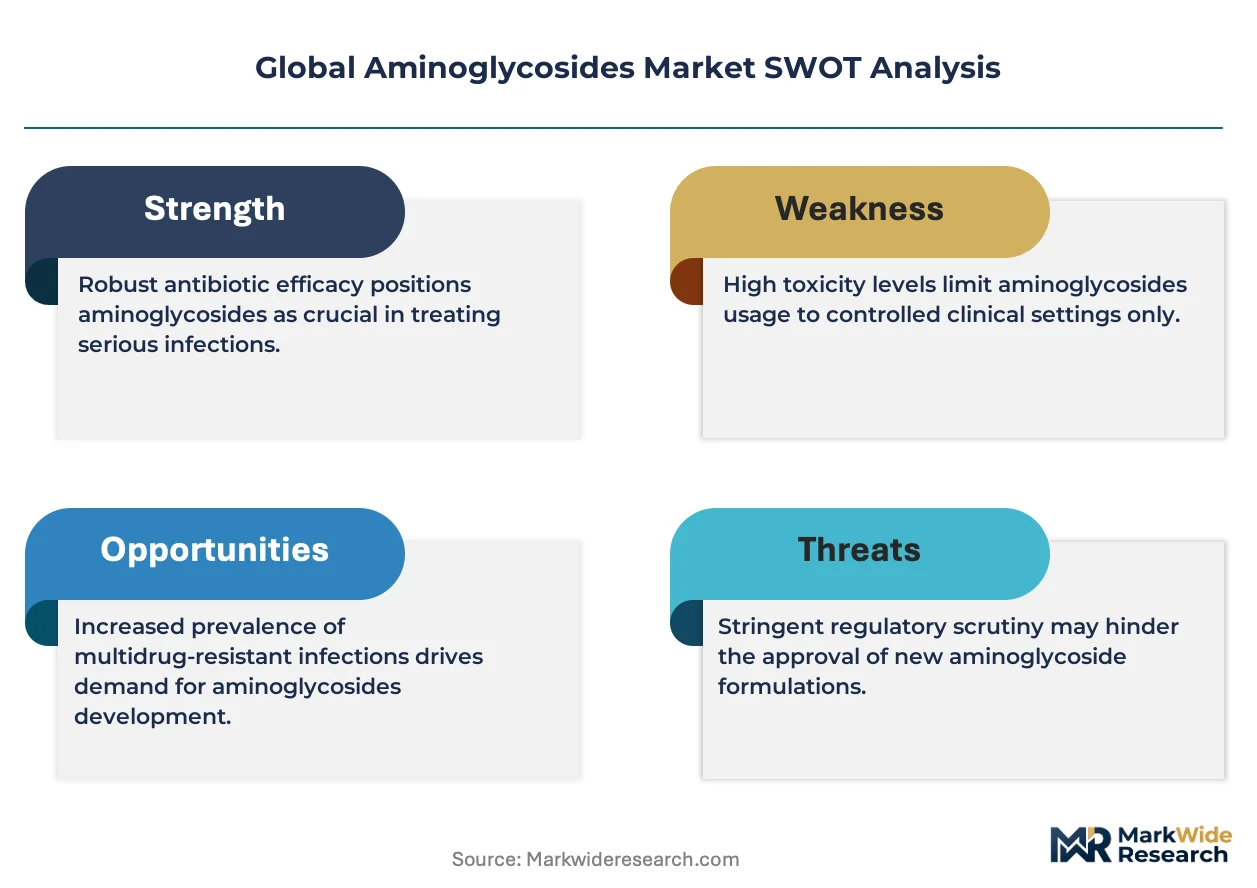
FDA tightening of nephrotoxicity labeling requirements is forcing manufacturers to restructure clinical trial protocols and post-market surveillance systems, while China's fermentation capacity expansion compresses API pricing power across Western finished-dose suppliers.
Growth Catalysts
- Carbapenem-resistant Enterobacterales (CRE) proliferation:Hospital-acquired infections resistant to first-line beta-lactams pull aminoglycosides back into combination protocols for sepsis and pneumonia management.
- India's PLI scheme for bulk drugs:Domestic fermentation incentives expand API self-sufficiency and reduce import dependency for streptomycin and gentamicin precursors.
- Inhaled delivery platform maturation:Nebulized tobramycin for cystic fibrosis patients creates durable revenue pools with limited generic erosion due to device-drug combination complexity.
Market Restraints
- Fermentation input volatility:Streptomyces culture media costs fluctuate with agricultural commodity markets, squeezing margin predictability for API producers.
- Single-region supply concentration:China's Zhejiang and Shandong provinces host over 70% of global aminoglycoside fermentation capacity, creating geopolitical and logistics vulnerability.
- Ototoxicity liability exposure:Irreversible vestibular damage claims elevate product liability insurance premiums and constrain label expansion for pediatric indications.
Strategic Opportunities
- Sub-Saharan Africa hospital networks:Underpenetrated infectious disease infrastructure in Nigeria and Kenya offers volume expansion for parenteral gentamicin as WHO essential medicine programs deepen.
- RNA-guided fermentation optimization:CRISPR-edited Streptomyces strains promise yield improvements and impurity profile tightening for amikacin and netilmicin production.
- EMA MDR pharmacovigilance waivers:Streamlined post-market surveillance pathways for established antibiotics reduce compliance overhead relative to novel therapeutic classes.
Industry Challenges
- Therapeutic drug monitoring integration:Real-time pharmacokinetic dosing systems require hospital IT infrastructure upgrades that strain capital budgets in mid-tier health systems.
- API-to-finished-dose regulatory divergence:Mismatched impurity specifications between China's NMPA pharmacopoeia updates and FDA bioequivalence standards complicate multi-jurisdictional filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aminoglycosides Market |
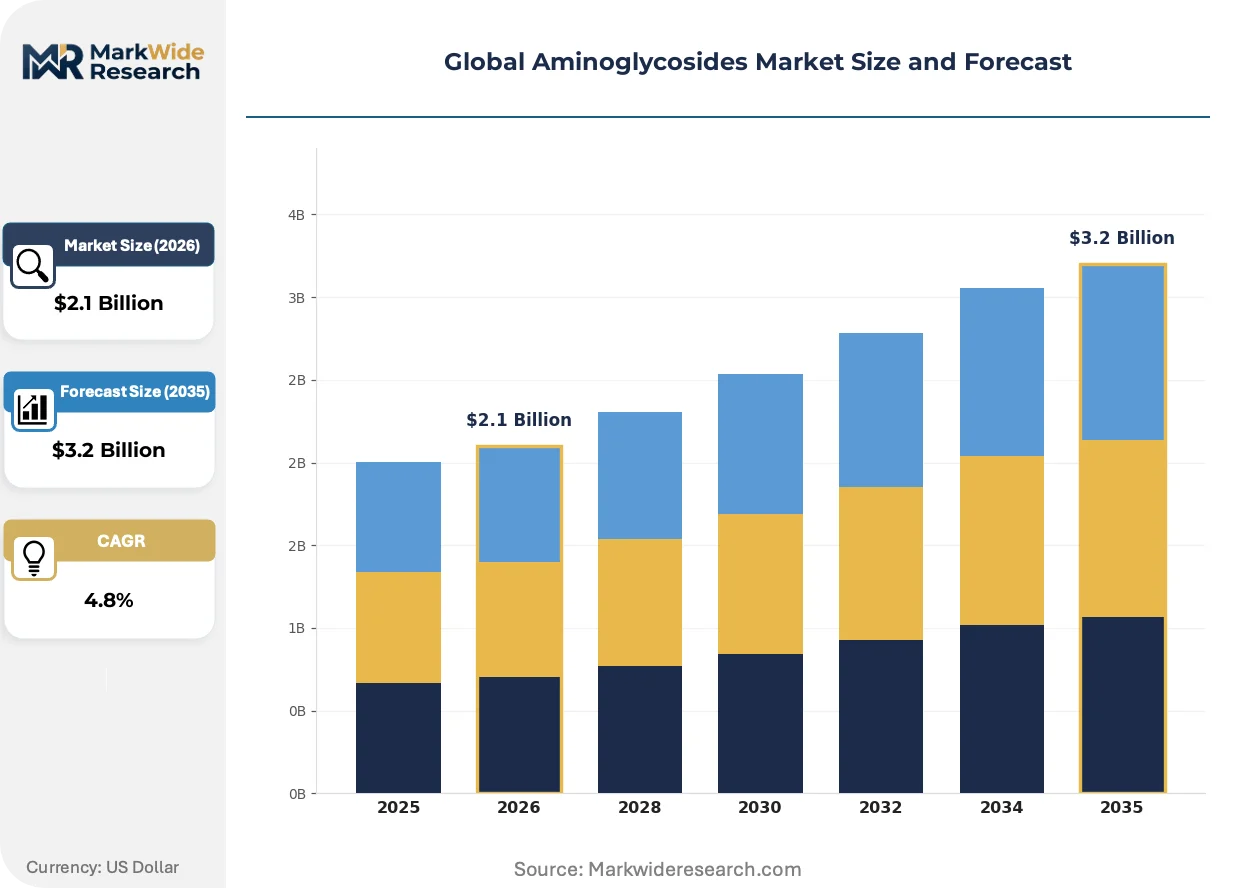
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gentamicin, Tobramycin, Amikacin, Neomycin Delivery Mode: Intravenous, Intramuscular, Oral, Inhalation Therapy Area: Infections, Respiratory Disorders, Tuberculosis, Sepsis End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Pfizer Inc., Cipla Limited, Teva Pharmaceutical Industries, AbbVie Inc., Merck & Co., Inc., Sun Pharmaceutical Industries, Aurobindo Pharma, Fresenius Kabi, Lupin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aminoglycosides Market Shifts & Advancements
Digitalization of therapeutic drug monitoring and RNA-guided strain engineering are compressing traditional development timelines while regulatory divergence between FDA and EMA pharmacovigilance frameworks reshapes competitive positioning.
Biosynthetic production platforms utilizing CRISPR-edited Streptomyces chassis are virtualizing the traditional fermentation-to-extraction pipeline, enabling direct precursor synthesis without multi-stage downstream processing. Academic-industry partnerships at Wageningen University and Jiangnan University are piloting these systems at 2,000-liter scale. The technology is virtualizing capital allocation patterns, redirecting investment from stainless-steel fermentation assets toward modular bioreactor skids and computational strain design capabilities.
EMA's Medical Device Regulation framework now classifies drug-device combination products like nebulized tobramycin under heightened conformity assessment requirements, extending approval timelines by 12-18 months for inhaled antibiotic formulations. Manufacturers must now maintain parallel technical documentation streams for the drug substance, device component, and integrated system. European cystic fibrosis centers are responding by consolidating procurement through specialized pharmacy compounding arrangements that bypass finished-dose device combinations.
Hospital formulary committees in the United States are unbundling antibiotic purchasing from traditional group purchasing organization contracts, establishing direct therapeutic class-specific negotiations with manufacturers. This disintermediation compresses distributor margins while rewarding manufacturers with robust pharmacovigilance databases and ready-to-implement therapeutic drug monitoring protocols. The shift is most visible in academic medical centers with dedicated antimicrobial stewardship programs, where aminoglycoside selection now hinges on integrated clinical decision support tools rather than legacy contract tiering.
Global Aminoglycosides Market Segmentation
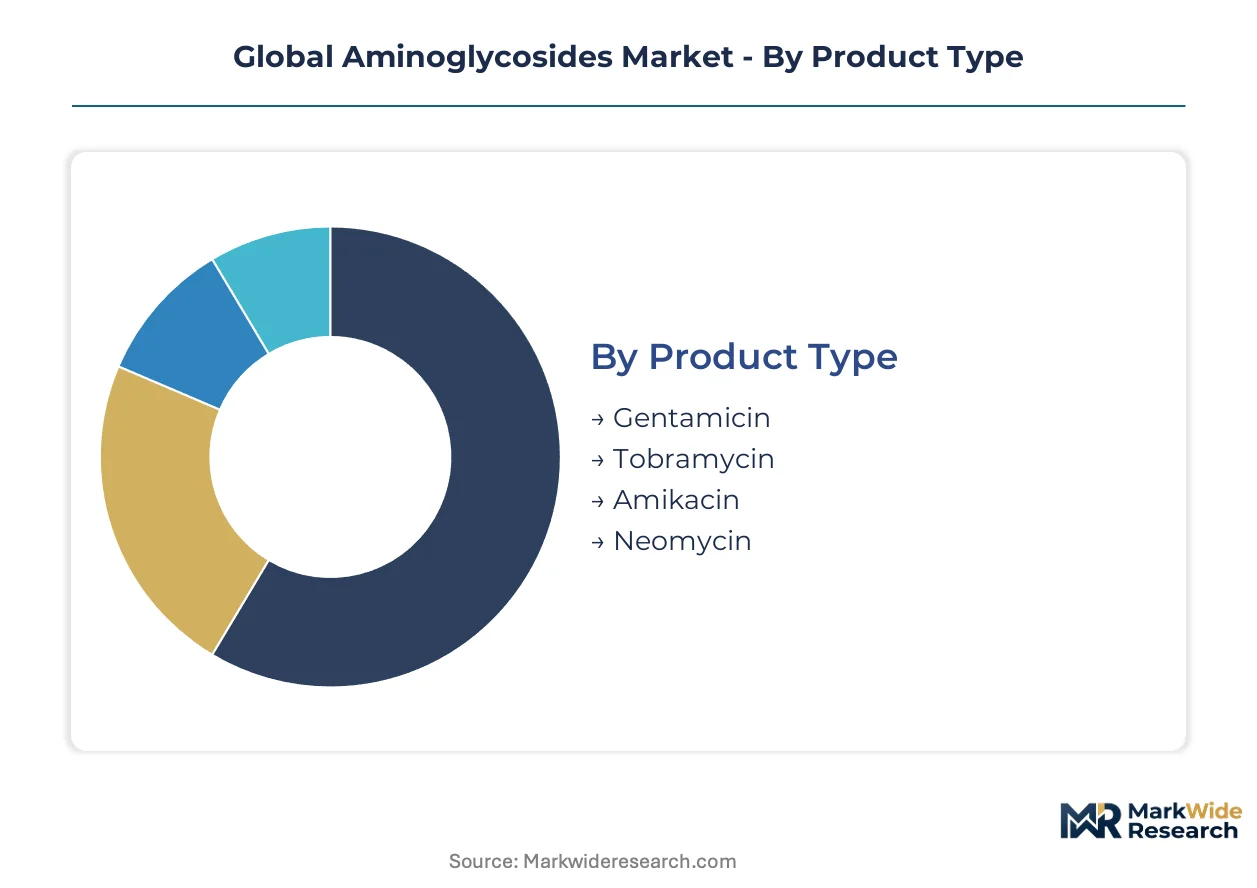
Aminoglycoside segmentation reflects divergent clinical economics across administration routes and resistance patterns. Product type and delivery mode splits determine manufacturing investment priorities, while therapy area and end-user dimensions shape regulatory filing strategies and commercial access models.
Product Type:
The maturity spectrum stretches from decades-old first-line agents to reserve antibiotics deployed against multidrug-resistant pathogens.
- Gentamicin:A first-generation aminoglycoside with broad Gram-negative coverage and established synergistic protocols with beta-lactams for enterococcal endocarditis. Demand concentrates in Indian government procurement for hospital-acquired pneumonia and complicated urinary tract infections, driven by lowest-in-class cost per treatment course and WHO essential medicine status.
- Amikacin:A semisynthetic derivative of kanamycin with enhanced stability against aminoglycoside-modifying enzymes, positioned as a reserve agent for carbapenem-resistant Enterobacterales. Japanese tertiary care centers and US academic medical centers are pulling this agent into combination sepsis protocols as last-resort resistance profiles expand.
- Tobramycin:Derived from Streptomyces tenebrarius with particular efficacy against Pseudomonas aeruginosa, serving inhaled cystic fibrosis maintenance regimens.
- Neomycin:A broad-spectrum agent limited to topical and oral bowel preparation applications due to systemic toxicity profile, confined to surgical prophylaxis and hepatic encephalopathy management.
Gentamicin handles the majority of throughput; amikacin is expanding most quickly on share as resistance surveillance data reshapes formulary tiering.
Delivery Mode:
Cost tier differentiation separates capital-intensive parenteral infrastructure from self-administered ambulatory formats.
- Intravenous:Requires hospital-based infusion infrastructure with mandatory therapeutic drug monitoring for nephrotoxicity surveillance. Intensive care units across Germany, France, and the United Kingdom anchor demand as sepsis bundle compliance mandates pull aminoglycosides into empirical protocols.
- Inhalation:Device-drug combinations for cystic fibrosis patients generate concentrated margins through nebulized tobramycin formulations. North American and Western European cystic fibrosis centers sustain this segment despite EMA MDR compliance costs extending approval timelines.
- Intramuscular:Deployed in resource-limited settings where venous access constraints preclude IV administration, common in sub-Saharan Africa outpatient protocols.
- Oral:Restricted to non-absorbed applications—hepatic encephalopathy decontamination and preoperative bowel preparation—due to negligible systemic bioavailability.
Intravenous administration commands the dominant revenue pool; inhalation delivery claims the steepest margin profile despite volume constraints.
Therapy Area:
Application urgency varies from elective prophylaxis to life-threatening emergency intervention.
- Sepsis:Empirical combination therapy in suspected Gram-negative bacteremia demands rapid IV aminoglycoside loading with pharmacokinetic-guided dosing. Australian and Canadian intensive care networks are embedding real-time monitoring systems to optimize exposure while minimizing renal injury.
- Infections:Complicated intra-abdominal and urinary tract infections where beta-lactam resistance or intolerance limits first-line options. Brazilian and Mexican hospital networks are expanding aminoglycoside access through public procurement programs targeting multidrug-resistant Klebsiella pneumoniae.
- Respiratory Disorders:Chronic Pseudomonas suppression in cystic fibrosis through inhaled tobramycin, with treatment duration extending across decades of patient life.
- Tuberculosis:Streptomycin and amikacin serve as second-line agents for multidrug-resistant Mycobacterium tuberculosis, concentrated in WHO-endorsed programmatic management in South Africa, India, and Russia.
Infections category handles the majority of throughput; sepsis applications are gaining share fastest as carbapenem resistance expands.
End User:
Customer type determines reimbursement pathway complexity and pharmacovigilance obligation intensity.
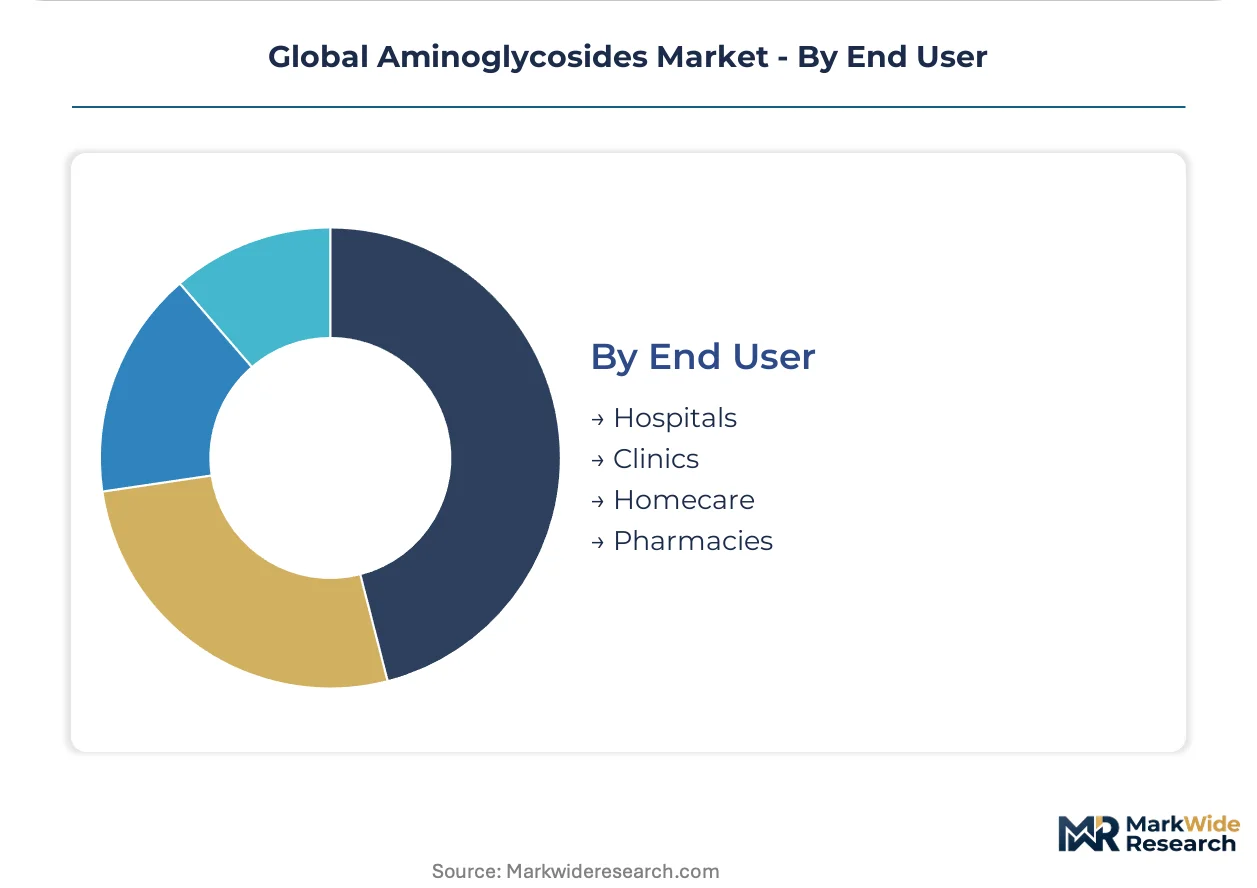
- Hospitals:Integrated therapeutic drug monitoring infrastructure and antimicrobial stewardship programs enable safe parenteral aminoglycoside deployment. US academic medical centers and German university hospitals are unbundling antibiotic procurement from group purchasing contracts to negotiate directly on pharmacovigilance databases and clinical decision support tools.
- Homecare:Specialized infusion services for cystic fibrosis patients on chronic inhaled tobramycin, requiring coordination between pulmonology centers and pharmacy benefit managers.
- Clinics:Outpatient parenteral antimicrobial therapy programs in urban centers, constrained by monitoring capability limitations.
- Pharmacies:Retail dispensing limited to topical neomycin formulations and oral bowel preparation kits, with minimal systemic antibiotic exposure.
Hospitals handle the majority of throughput; homecare is climbing fastest as cystic fibrosis patient survival extends treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's pharmaceutical cold-chain terminals anchor China's aminoglycoside export capacity, connecting Zhejiang fermentation clusters to European and African hospital networks. This maritime infrastructure underwrites Beijing's leverage over global API pricing.
China
Zhejiang and Shandong provinces concentrate over seventy percent of global aminoglycoside fermentation capacity, with Hangzhou and Jinan hosting multi-thousand-ton streptomyces facilities. NMPA's tightened impurity profiling under updated pharmacopoeia standards is disqualifying smaller API exporters from Western supply chains. Qingdao's biopharma zone is absorbing stranded fermentation assets as consolidation accelerates.
India
Maharashtra's antibiotic manufacturing belt around Mumbai and Pune processes domestically fermented gentamicin for government hospital procurement. CDSCO's mandatory batch release testing through central laboratories for imported APIs creates procedural friction that BIS-certified local producers circumvent. The PLI scheme for bulk drugs is expanding fermentation self-sufficiency for streptomycin precursors in Gujarat's Vapi cluster.
United States
Academic medical centers in Boston and Baltimore are unbundling aminoglycoside procurement from group purchasing organization contracts, negotiating directly on pharmacovigilance databases. FDA's boxed warning requirements for nephrotoxicity and ototoxicity elevate post-market surveillance costs for parenteral gentamicin marketers. Philadelphia's hospital networks anchor demand for therapeutic drug monitoring-integrated dosing systems.
Germany
University hospitals in Berlin and Munich embed real-time pharmacokinetic monitoring for sepsis bundle compliance, pulling aminoglycosides into empirical Gram-negative protocols. EMA's MDR framework extends approval timelines for nebulized tobramycin by twelve to eighteen months. Frankfurt's procurement consortia are consolidating antibiotic purchasing through therapeutic class-specific negotiations.
Brazil
Public hospital networks in São Paulo and Rio de Janeiro are expanding aminoglycoside access through procurement programs targeting multidrug-resistant Klebsiella pneumoniae. ANVISA's regulatory alignment with FDA bioequivalence standards complicates filing strategies for Asian API suppliers. Campinas' pharmaceutical manufacturing zone is attracting regional finishing capacity for parenteral formulations.
Global Aminoglycosides Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API fermentation and finished-dose supply. The aminoglycoside market structures around three tiers: multinational hospital franchise holders, backward-integrated Indian generic houses, and Chinese bulk fermentation operators. Competitive moves concentrate on pharmacovigilance database depth for formulary access, and CRISPR-guided strain engineering for yield compression.
Among multinational pharmaceutical incumbents, Pfizer Inc. and Merck & Co., Inc. occupy positions anchored by hospital infectious disease franchises and therapeutic drug monitoring protocol integration. Indian generic specialists Cipla Limited and Sun Pharmaceutical Industries exemplify the backward-integrated archetype, leveraging domestic fermentation assets for cost-optimized supply to emerging market procurement programs. These players represent contrasting pathways to formulary placement: proprietary clinical data infrastructure versus manufacturing scale and geographic proximity to expanding Asian and African hospital networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Cipla Limited |
| Teva Pharmaceutical Industries |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries |
| Aurobindo Pharma |
| Fresenius Kabi |
| Lupin Limited |
| Others |
Supply & Pricing Matrix
Zhejiang province's fermentation capacity expansion for aminoglycoside APIs is compressing pricing power for Western finished-dose formulators while elevating margin capture for integrated Asian producers. This supply-side concentration enables volume-discount tiering that favors hospital procurement consortia with multi-year offtake commitments.
Pricing Analysis
Volume-discount tiering structures separate GPO-anchored hospital networks from mid-tier health systems and standalone clinics. Price differentiation hinges on therapeutic drug monitoring protocol bundling and FDA bioequivalence certification tier. Cost compression in parenteral gentamicin is intensifying because Chinese API exports are flooding spot markets. Government procurement programs in India exhibit the highest price sensitivity; cystic fibrosis centers in North America show the least due to device-drug combination stickiness.
Supply Chain Analysis
Streptomyces culture media and soy-derived fermentation substrates anchor upstream feedstock dependencies for aminoglycoside production. Geographic supply concentration centers on China, India, and Italy for API fermentation and finished-dose formulation. Single-source vulnerability runs through Zhejiang province's cluster dominance, where logistics disruptions or NMPA enforcement actions cascade immediately. Distribution runs through hospital GPOs in the United States, government tender systems in India, and specialized pharmacy networks for inhaled formulations in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as carbapenem-resistant Enterobacterales proliferation pulls reserve aminoglycosides back into frontline sepsis protocols. Penetration tailwinds from WHO essential medicine program deepening in sub-Saharan Africa justify capacity positioning ahead of demand inflection.
For Market Incumbents: Pre-empt biosynthetic displacement by securing CRISPR-edited Streptomyces strain partnerships at Wageningen University and Jiangnan University. Defend formulary placement through pharmacovigilance database depth that satisfies FDA boxed warning surveillance obligations and EMA MDR post-market requirements. Deepen backward integration into fermentation assets in Gujarat's Vapi cluster to offset Chinese API pricing pressure. For New Entrants and Emerging Players: Build out sub-Saharan Africa hospital network coverage for parenteral gentamicin as Nigerian and Kenyan infectious disease infrastructure expands under WHO programs. Target cystic fibrosis homecare services in North America with nebulized tobramycin compounding capabilities that bypass EMA MDR device-drug combination timelines. Anchor go-to-market through direct therapeutic class-specific negotiations with academic medical centers unbundling from traditional GPO contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with pharmacovigilance infrastructure over pure-play API fermenters facing yield compression. Long-term viability across the five-to-ten year window rests on RNA-guided strain engineering capabilities and hospital IT integration for real-time dosing systems. Watch CRISPR-edited strain yield improvements at pilot scale as the inflection signal for manufacturing cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Engineering Partnership | Wageningen University pilot programs promise yield compression for amikacin and netilmicin production. |
| Therapeutic Drug Monitoring Integration | Real-time pharmacokinetic systems satisfy FDA surveillance demands for nephrotoxicity risk management. |
| EMA MDR Compliance Pathway | Streamlined device-drug combination documentation reduces approval timeline exposure for inhaled formulations. |
| Sub-Saharan Africa Distribution Buildout | Nigerian and Kenyan hospital networks offer volume expansion under WHO essential medicine deepening. |
| Backward Integration into Fermentation | Gujarat Vapi cluster assets reduce import dependency for streptomycin and gentamicin precursors. |
Research Methodology
Initial hypotheses were tested against primary input from hospital infectious disease specialists, regulatory affairs directors at finished-dose manufacturers, antimicrobial stewardship program leads, and API procurement managers at Indian generic houses, then refined through secondary validation against FDA 510(k) filings, EMA marketing authorization databases, CDSCO batch release records, WHO GLASS resistance surveillance reports, and pharmacovigilance disclosure documents. Bottom-up prescription volume modeling and top-down hospital expenditure triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, delivery mode, therapy area, and regional regulatory cluster. CAGRs were derived from infection incidence projections cross-referenced with resistance surveillance data and formulary tiering shifts. Industry-specific forecast inputs included carbapenem resistance prevalence trajectories from national health institutes and therapeutic drug monitoring adoption curves from hospital IT expenditure surveys.
Stress conditions across fermentation input cost volatility, NMPA pharmacopoeia enforcement intensity, and EMA MDR approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding resistance pattern evolution and stewardship program penetration. Cross-checking against WHO GLASS resistance surveillance benchmarks and national hospital procurement database audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Global Electronic Aspirin Market