
 Asia - Pacific Glass Bottles and Containers Market | 2026-2036
Asia - Pacific Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia - Pacific Glass Bottles and Containers Market Outlook
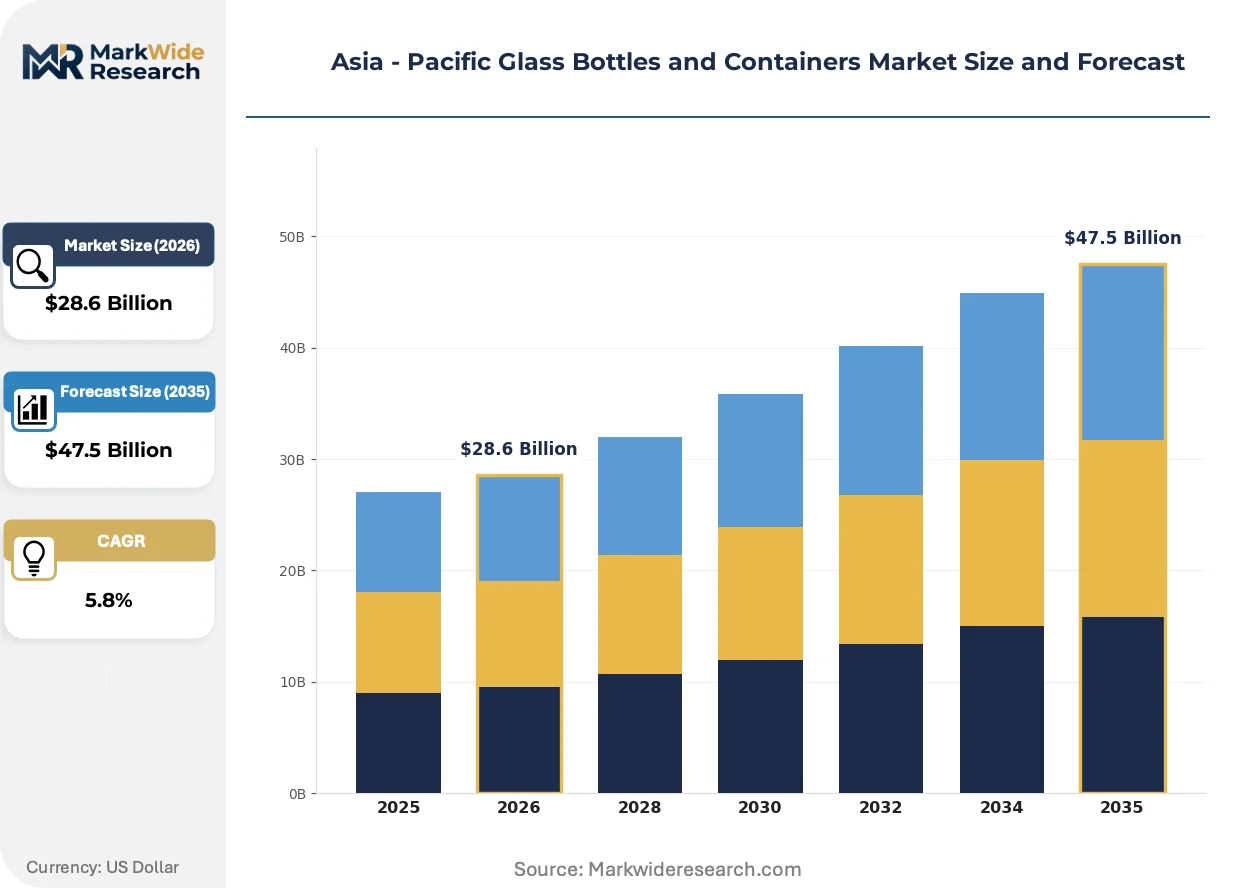
Subscription-based mold maintenance and software-defined furnace diagnostics are decoupling capital equipment ownership from production uptime in the Asia-Pacific glass container sector. Owens-Illinois, Inc. leverages its regional furnace network to sustain bulk supply contracts with multinational beverage bottlers. Piramal Glass Private Limited anchors India's pharmaceutical glass exports through dedicated Type I borosilicate lines. AGI Glaspac differentiates via specialized cosmetic bottle finishes for Southeast Asian personal care brands.
Asia-Pacific glass bottles and containers are hollow-formed silica-soda-lime or borosilicate vessels, typically manufactured through blow-and-blow or press-and-blow processes with wall thicknesses ranging from 2mm to 6mm depending on thermal shock requirements, serving primarily as chemically inert, infinitely recyclable packaging for liquid and semi-solid goods. Pharmaceutical containers command premium margins due to USP Type I compliance and stringent hydrolytic resistance testing, while beverage bottles dominate unit volume across ASEAN brewing clusters. Cosmetic bottles represent the fastest-growing product type as K-beauty and J-beauty brands prioritize tactile glass aesthetics over plastic alternatives.
India's BIS certification mandates and China's GB standards for food-contact glass establish baseline quality thresholds that filter out subscale producers across the region. Japan's METI circular economy guidelines and Australia's TGA pharmaceutical packaging rules further tighten material traceability requirements for export-oriented manufacturers. Stakeholders must monitor evolving EPR schemes in Thailand and Vietnam, where pending packaging waste legislation will reshape collection infrastructure and post-consumer cullet economics.
Market Dynamics
Lightweight borosilicate innovations are compressing unit costs for pharmaceutical-grade containers while India's BIS mandates and China's dual carbon goals simultaneously tighten compliance thresholds and accelerate furnace modernization across the Asia-Pacific glass container sector.
Growth Catalysts
- India's BIS certification mandates:Quality thresholds for food-contact glass are filtering out subscale producers and consolidating capacity around certified manufacturers in Hyderabad and Mumbai corridors.
- Pharmaceutical export compliance:Injectable drug shipments to regulated markets require Type I borosilicate hydrolytic resistance, pulling investment toward dedicated production lines.
- Lightweighting technology:Advanced press-and-blow processes are reducing wall thickness to 2mm-4mm ranges without sacrificing thermal shock performance, cutting raw material intensity per unit.
Market Restraints
- Natural gas price volatility:Furnace operations depend on consistent energy inputs, and spot market fluctuations in LNG contracts directly compress margin predictability for continuous-melt facilities.
- Post-consumer cullet supply fragmentation:Collection infrastructure gaps across Thailand and Vietnam limit closed-loop recycling economics despite pending EPR legislation.
- Aluminum can substitution:Beverage brands in ASEAN brewing clusters are evaluating metal alternatives for certain SKUs where transport weight reduction outweighs premium glass positioning.
Strategic Opportunities
- Vietnam's pending packaging waste legislation:EPR scheme implementation will reshape collection infrastructure and create first-mover advantages for integrated cullet-to-container operators.
- Cosmetic glass aesthetics:K-beauty and J-beauty brands are prioritizing tactile surface finishes and custom mold capabilities over plastic alternatives in premium personal care lines.
- Software-defined furnace diagnostics:Predictive maintenance platforms are converging with mold telemetry to enable subscription-based uptime guarantees decoupled from capital ownership.
Industry Challenges
- Type I certification timelines:USP hydrolytic resistance testing and TGA pharmaceutical packaging compliance require 18-24 month validation cycles that delay revenue recognition for new production lines.
- Skilled furnace engineering scarcity:Specialized expertise in borosilicate melt chemistry and thermal profile optimization concentrates among retiring cohorts in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia - Pacific Glass Bottles and Containers Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverage Bottles, Pharmaceutical Containers, Food Jars, Cosmetic Bottles End User: Beverage Industry, Pharmaceutical Companies, Food Manufacturers, Personal Care Brands Capacity: Under 250ml, 250ml to 500ml, 500ml to 1L, Above 1L Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Owens-Illinois, Inc., Gerresheimer AG, Ardagh Group S.A., Piramal Glass Private Limited, Hindusthan National Glass & Industries Ltd., AGI Glaspac, Central Glass Co. Ltd., Tokyo Glass Co Ltd, Maidao Industry Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia - Pacific Glass Bottles and Containers Market Strategic Shifts
Digital furnace control systems and predictive analytics are compressing the traditional trade-off between production scale and batch flexibility across Asia-Pacific glass container manufacturing.
Electromagnetic boosting technology is converging with oxy-fuel combustion architecture to enable precise thermal zone management in borosilicate melting. Pharmaceutical manufacturers in India's western corridor are adopting these hybrid furnace configurations to meet Type I compliance without sacrificing throughput flexibility. This convergence is compressing the capital cost differential between dedicated pharmaceutical lines and general-purpose soda-lime capacity.
China's GB standards for food-contact glass are tightening migration limits for heavy metal leaching, forcing furnace refractory upgrades and raw material sourcing audits across Shandong and Guangdong production bases. Manufacturers serving export markets must simultaneously satisfy GB compliance and destination-country pharmacopeia requirements. Dual-certification overhead is compressing margins for mid-scale operators while accelerating consolidation toward integrated quality management systems.
Subscription-based mold maintenance contracts are displacing traditional break-fix service models among multinational beverage bottlers. Owens-Illinois and regional furnace networks are packaging predictive diagnostics with guaranteed uptime SLAs, transferring operational risk from bottlers to equipment providers. This procurement evolution is most visible in ASEAN brewing clusters where capacity utilization directly ties to seasonal demand spikes.
Asia - Pacific Glass Bottles and Containers Market Segmentation
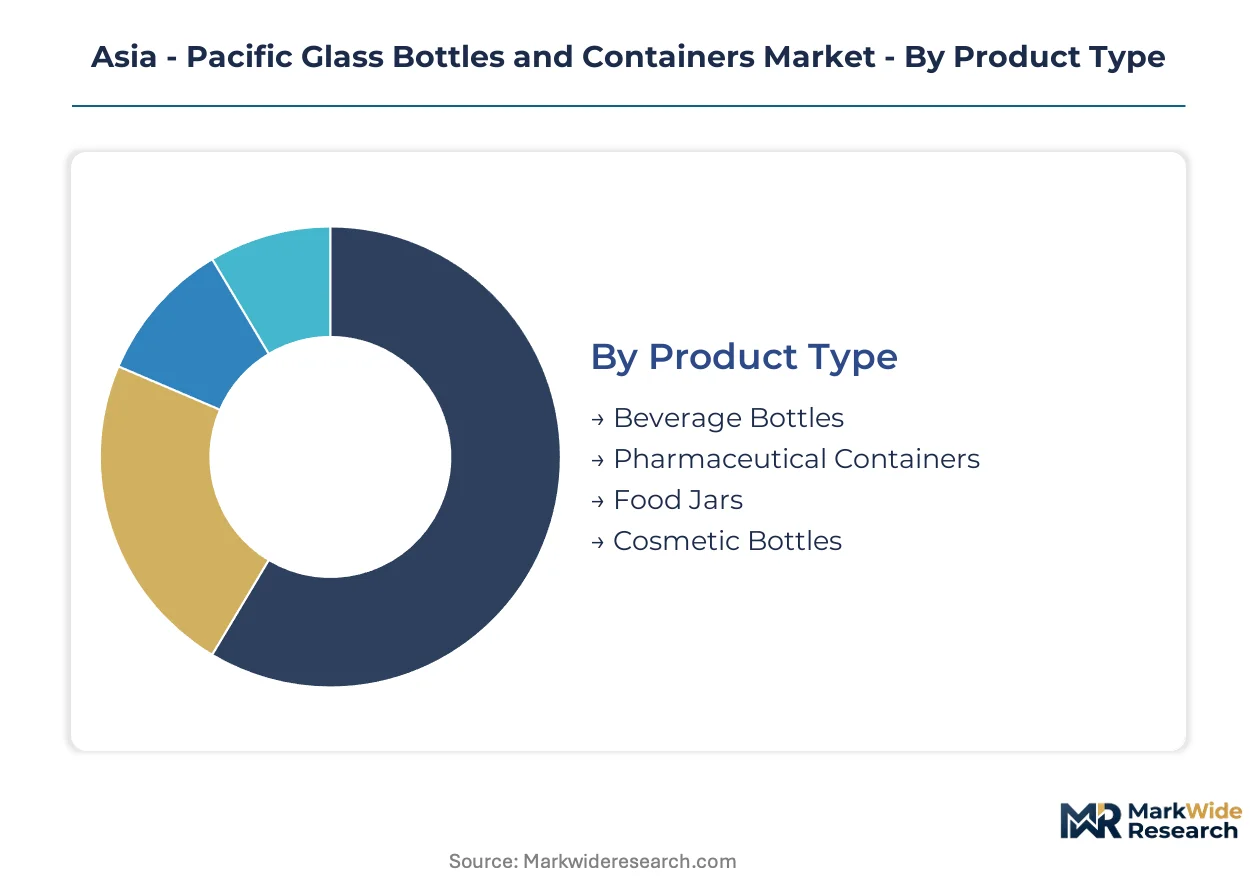
Glass container buyers in Asia-Pacific exhibit sharply divergent technical requirements across end-use applications, with pharmaceutical and beverage purchasers prioritizing incompatible performance attributes that reshape manufacturing priorities and margin structures.
Product Type:
Buyers differentiate primarily by hydrolytic resistance mandates and thermal shock specifications rather than unit economics alone.
- Beverage Bottles:Soda-lime silica construction dominates this segment with wall thickness calibrated for carbonation pressure retention and pasteurization cycles. Demand clusters around ASEAN brewing corridors in Vietnam and Thailand where multinational bottlers negotiate multi-year supply agreements tied to furnace network access.
- Pharmaceutical Containers:Type I borosilicate glass commands premium positioning through USP hydrolytic resistance certification and TGA compliance for injectable drug exports. Hyderabad and Mumbai pharmaceutical corridors drive specification intensity as CDSCO-regulated manufacturers supply regulated markets in Europe and North America.
- Food Jars:Thermal shock resistance for hot-fill applications defines performance thresholds, with FSSAI-mandated migration limits shaping raw material selection across Indian food processing clusters.
- Cosmetic Bottles:Surface finish aesthetics and custom mold capabilities differentiate offerings for K-beauty and J-beauty brands prioritizing tactile packaging over plastic alternatives.
Volume sits with Beverage Bottles; growth tilts toward Cosmetic Bottles.
End User:
Procurement scale and certification burden separate enterprise buyers from mid-tier purchasers across the value chain.
- Beverage Industry:Multinational bottlers leverage furnace network proximity and guaranteed uptime contracts to secure supply security for seasonal demand spikes. These buyers drive standardization around lightweight 2mm-4mm wall specifications.
- Pharmaceutical Companies:CDSCO-regulated manufacturers in India's western corridor require 18-24 month validation cycles for Type I certification, creating captive supplier relationships and limiting vendor switching.
- Food Manufacturers:Processors of sauces, preserves, and ready-to-eat meals specify thermal shock performance for hot-fill lines, with BIS certification filtering supplier pools.
- Personal Care Brands:Premium positioning demands custom mold development and small-batch flexibility, with Southeast Asian brands prioritizing aesthetic differentiation over unit cost minimization.
Procurement concentration favors Beverage Industry; margin expansion concentrates with Pharmaceutical Companies.
Capacity:
Fill-line compatibility and logistics economics shape buyer preferences across volume tiers.
- Under 250ml:Pharmaceutical ampoules and premium cosmetic samples dominate this tier, with precision forming requirements limiting viable supplier pools.
- 250ml to 500ml:Standard beverage and personal care applications concentrate here, with lightweighting technology compressing material intensity per unit.
- 500ml to 1L:Wine, spirits, and cooking oil packaging drive demand, with Australia's TGA-regulated pharmaceutical liquids also specifying this range.
- Above 1L:Bulk food service and industrial chemical containment require reinforced wall structures, with lower unit margins offset by reduced per-liter logistics costs.
Unit economics favor 250ml to 500ml; specification intensity peaks Under 250ml.
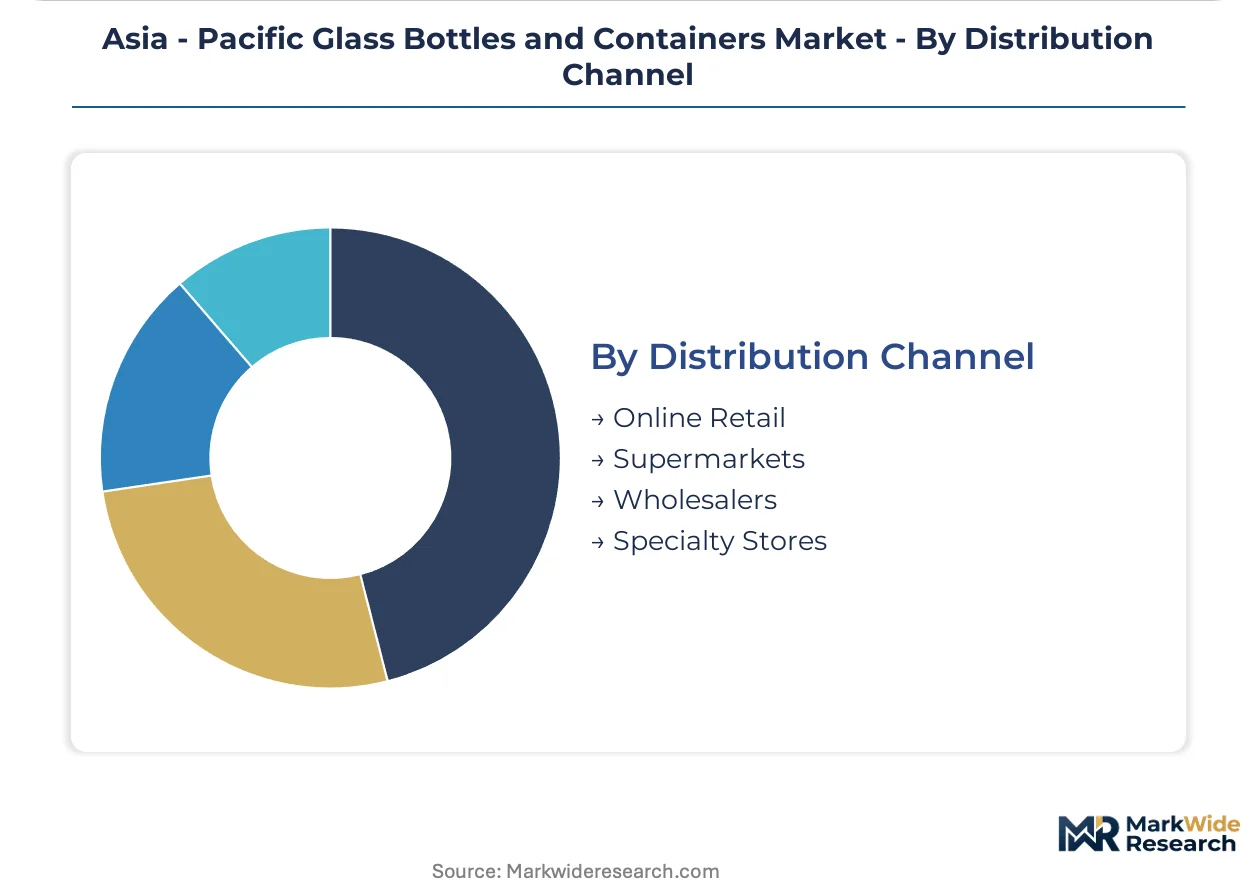
Distribution Channel:
Order fragmentation and service level requirements distinguish channel strategies.
- Online Retail:Direct-to-consumer cosmetic and specialty food brands drive small-lot orders with premium positioning, requiring flexible mold changeover capabilities.
- Supermarkets:Private-label beverage and food jar volumes concentrate here, with buyers negotiating consolidated procurement across multiple SKUs.
- Wholesalers:Standardized beverage bottles and commodity food jars flow through this channel, with price sensitivity highest and brand differentiation lowest.
- Specialty Stores:Premium spirits, artisanal food products, and luxury cosmetics specify custom finishes and limited production runs.
Throughput scale concentrates with Supermarkets; margin capture concentrates with Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's furnace modernization outpaces domestic consumption growth, while India and Southeast Asian markets absorb surplus pharmaceutical-grade capacity. This production-consumption divide shapes investment flows across the region.
China
Shandong and Guangdong production bases supply lightweight beverage bottles to ASEAN brewing clusters while domestic pharmaceutical demand absorbs Type I borosilicate output. GB standards for food-contact glass are tightening heavy metal migration limits, forcing furnace refractory upgrades. Yangtze River Delta manufacturers are retrofitting oxy-fuel combustion systems to satisfy dual carbon goals.
India
Hyderabad and Mumbai pharmaceutical corridors drive specification intensity for injectable drug exports to regulated markets. BIS certification mandates for food-contact glass are filtering out subscale producers and consolidating capacity around certified manufacturers. Western corridor producers are adopting hybrid furnace configurations to compress Type I compliance costs.
Japan
Domestic demand centers on premium cosmetic and pharmaceutical applications with stringent surface finish requirements. METI circular economy guidelines are tightening material traceability standards for export-oriented manufacturers. Kanto-based producers are transferring borosilicate melt chemistry expertise to Southeast Asian joint ventures.
Vietnam
Ho Chi Minh City and Hanoi industrial zones are attracting furnace investments to serve ASEAN beverage bottlers. Pending packaging waste legislation will establish EPR schemes and reshape collection infrastructure. Northern provinces are developing cullet processing capacity to feed closed-loop glass manufacturing.
Australia
TGA pharmaceutical packaging rules are driving import substitution for Type I borosilicate containers previously sourced from European suppliers. Melbourne and Sydney pharmaceutical manufacturers are qualifying domestic suppliers for injectable drug packaging. Wine export volumes are sustaining demand for premium bottle finishes in South Australia.
Asia - Pacific Glass Bottles and Containers Market Competitive Environment
Capital-heavy furnace operators compete with asset-light mold specialists and brand-owning bottlers across tiered supply arrangements. The market structure concentrates around integrated multinational networks, mid-scale regional specialists, and captive pharmaceutical lines. Three archetypes dominate: furnace-network multinationals securing bulk beverage contracts, Type I-certified pharmaceutical specialists, and cosmetic finish innovators serving K-beauty and J-beauty brands. Competitive moves center on subscription-based uptime guarantees and lightweighting technology licensing.
Within the multinational furnace-network tier, Owens-Illinois, Inc. exemplifies scale-driven supply security for seasonal beverage demand. Among India-based pharmaceutical specialists, Piramal Glass Private Limited occupies a position anchored to Type I borosilicate export compliance. AGI Glaspac represents the cosmetic finish innovation archetype, with specialization in tactile surface capabilities for premium personal care positioning.
| Leading Market Players |
|---|
| Owens-Illinois, Inc. |
| Gerresheimer AG |
| Ardagh Group S.A. |
| Piramal Glass Private Limited |
| Hindusthan National Glass & Industries Ltd. |
| AGI Glaspac |
| Central Glass Co. Ltd. |
| Tokyo Glass Co Ltd |
| Maidao Industry Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Hybrid furnace configurations integrating electromagnetic boosting with oxy-fuel combustion are compressing capital cost differentials between pharmaceutical-grade borosilicate and general-purpose soda-lime capacity, simultaneously reshaping unit economics and consolidating production around technology-leaders in Shandong and Hyderabad corridors.
Pricing Analysis
Margin tightening in commodity beverage bottles traces to lightweighting technology diffusion and aluminum can substitution threats in ASEAN brewing clusters. Three-tier pricing structure across Type I certified pharmaceutical, BIS-compliant food-contact, and standard soda-lime tiers separates buyers by compliance burden and volume scale. Cost-down pressure accelerates as multinational bottlers negotiate subscription-based uptime guarantees that transfer operational risk to furnace operators. Beverage industry buyers exhibit highest price sensitivity; pharmaceutical companies accept premium positioning for USP hydrolytic resistance certification.
Supply Chain Analysis
Freight cost escalation from Shandong and Guangdong production bases to ASEAN markets is compressing margins for spot-market beverage contracts and incentivizing furnace network regionalization. Raw material sourcing draws from silica sand deposits in China, soda ash from synthetic and natural producers, and boron compounds from Turkish and American suppliers. Single-source vulnerability concentrates in specialized borosilicate melt chemistry expertise retiring from Japanese and German engineering cohorts. Distribution runs through furnace-network direct contracts for beverage volumes, with pharmaceutical lines employing captive supplier relationships validated through 18-24 month TGA compliance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into cullet collection infrastructure and mold maintenance capabilities is emerging as the decisive competitive lever as EPR legislation reshapes post-consumer economics across Vietnam and Thailand.
For Market Incumbents: Deepen backward integration into captive cullet processing capacity ahead of Vietnam's pending packaging waste legislation implementation. Acquire specialized borosilicate melt chemistry expertise through Southeast Asian joint ventures with Japanese technology partners to offset retiring German engineering cohorts. Defend against aluminum can substitution by locking multinational beverage bottlers into multi-year furnace network access contracts with guaranteed uptime SLAs.
For New Entrants and Emerging Players: Begin with cosmetic glass aesthetics for K-beauty and J-beauty brands where tactile surface finish requirements limit viable supplier pools and support premium positioning. Target India's western pharmaceutical corridor with hybrid furnace configurations that compress Type I compliance costs below dedicated line economics. Pursue software-defined furnace diagnostics partnerships to offer subscription-based uptime guarantees without capital-heavy furnace ownership.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale regional specialists with BIS certification and established CDSCO-regulated customer relationships in Hyderabad and Mumbai corridors. Long-term viability favors integrated operators controlling cullet-to-container economics under evolving EPR frameworks. Monitor Thailand and Vietnam regulatory filing timelines as inflection indicators for collection infrastructure investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Furnace Configuration Deployment | Compresses Type I borosilicate compliance costs for Indian pharmaceutical exporters. |
| Cullet Collection Infrastructure Buildout | Creates first-mover advantage under Vietnam's pending EPR packaging waste legislation. |
| Subscription-Based Mold Maintenance Contracts | Transfers operational risk from ASEAN beverage bottlers to equipment providers. |
| Cosmetic Glass Surface Finish Specialization | Captures premium positioning from K-beauty and J-beauty brand aesthetic priorities. |
| Type I Certification Line Investment | Secures captive supplier status with CDSCO-regulated injectable drug exporters. |
Study Parameters
Document review covered furnace technology patents, BIS and GB regulatory filings, and CDSCO pharmaceutical packaging guidelines, complemented by interviews with plant managers at Shandong and Guangdong production bases, procurement leads at multinational beverage bottlers, regulatory affairs specialists at Indian pharmaceutical exporters, and technical R&D directors specializing in borosilicate melt chemistry. Secondary validation drew from customs trade data, SEC filings of listed container manufacturers, and METI circular economy implementation reports. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish market sizing.
Unit volume and value projections across the analysis window reflect segmented modeling by product type, end-use industry, capacity tier, and distribution channel, with CAGRs derived from regression analysis against macroeconomic indicators and regulatory implementation timelines. Forecast inputs incorporated natural gas price volatility scenarios, EPR legislation adoption curves, and aluminum substitution elasticity estimates for ASEAN beverage applications.
Underlying measurement precision varies by segment; Type I pharmaceutical containers and beverage bottle volumes carry tighter precision than emerging cosmetic glass categories. Forecasts reflect documented assumptions regarding regulatory implementation schedules and energy input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Amber Glass Packaging Market