
 Cosmetic and Perfume Glass Bottle Market | 2026-2036
Cosmetic and Perfume Glass Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic and Perfume Glass Bottle Market Outlook
European specialty glass furnace output is rebalancing after energy cost spikes reshaped production economics across Germany and France. Gerresheimer leverages its pharmaceutical-grade glass expertise to serve perfume houses demanding crystal-clarity standards. Stoelzle Glass Group sustains decorative firing capacity in Austria that anchors supply for luxury fragrance flacons. Verescence competes through proprietary lightweighting technology that reduces unit material without compromising wall thickness uniformity.
Cosmetic and perfume glass bottles are rigid containers fabricated from soda-lime or borosilicate glass, typically ranging from 30 ml to 100 ml in finished volume, formed through blow-and-blow or press-and-blow processes and subsequently treated with silk-screening, hot stamping, or metallization to achieve brand-specific aesthetics. Their primary commercial purpose is to preserve volatile fragrance compounds from photodegradation and oxidation while communicating premium positioning through tactile weight and visual clarity. Spray and pump mechanisms command the highest value-add per unit among product types because integrated actuator systems require precision tolerances between glass neck finish and polymer components. Frosted decoration treatments carry elevated margins versus printed alternatives due to additional acid-etching or sandblasting steps that demand skilled labor and controlled environmental conditions.
EU REACH compliance and the F-Gas Regulation shape material choices for glass coating processes, while FDA 21 CFR requirements for cosmetic packaging contact substances govern export-bound production from Chinese and European manufacturers serving United States brands. ECHA restrictions on cadmium and lead in decorative enamels are forcing reformulation of traditional colored glass recipes toward mineral-based alternatives. Stakeholders must monitor how extended producer responsibility schemes in France and Italy shift cost burdens from municipalities to brand owners and their packaging suppliers.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing virgin glass procurement timelines while forcing furnace operators to requalify recycled cullet streams for cosmetic-grade clarity standards.
Growth Catalysts
- EPR scheme expansion:France and Italy now assign full end-of-life cost responsibility to brand owners, accelerating premium glass recovery rates and closing material loops for high-cullet-content production.
- Borosilicate furnace clustering:Hebei province concentration enables just-in-time supply to Northeast Asian beauty brands, reducing lead times for limited-edition fragrance launches.
- REACH Annex XVII reformulation:ECHA cadmium and lead restrictions in decorative enamels are spurring mineral-based colorant R&D, creating patentable differentiation for compliant suppliers.
Market Restraints
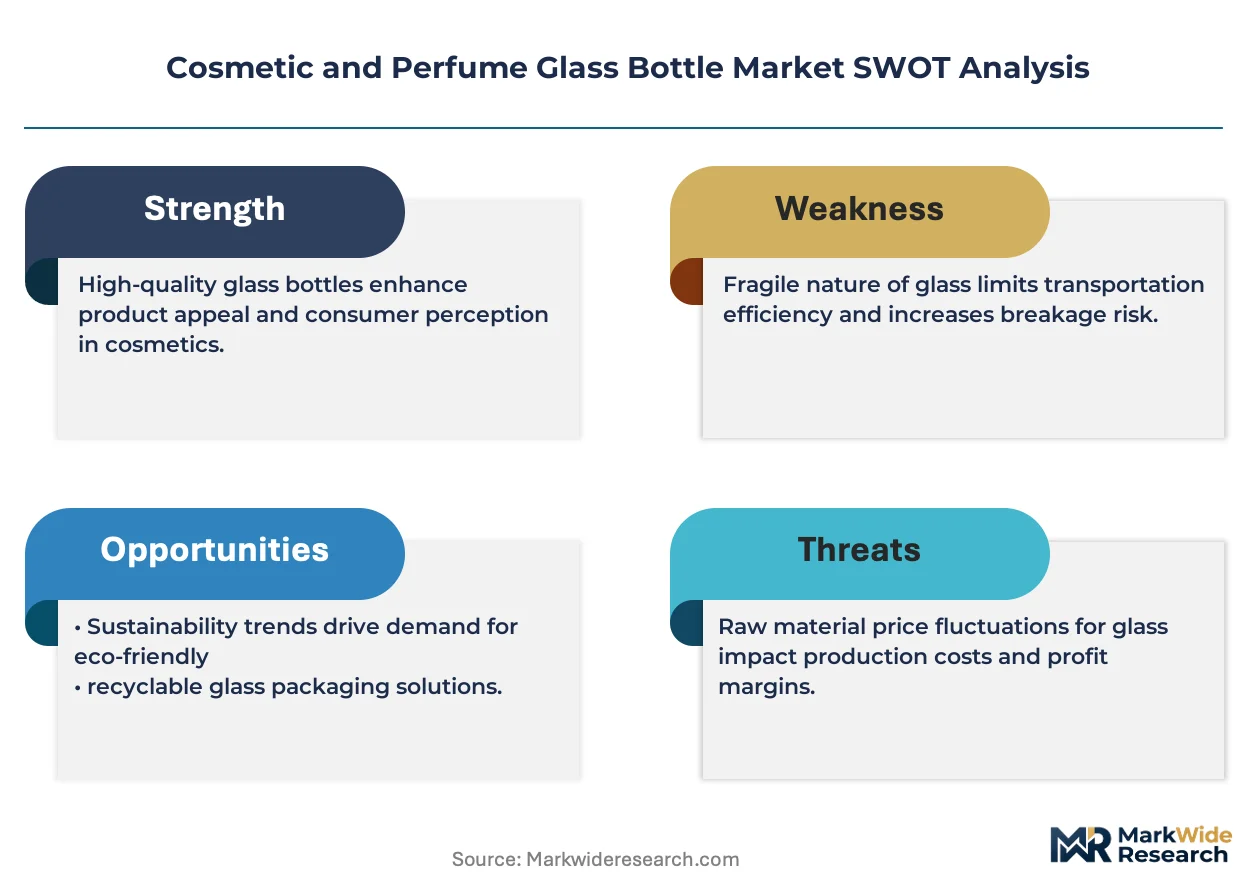
- Natural gas cost volatility:European specialty glass furnace operations face structurally higher energy input costs versus Asian competitors, eroding margin buffers on decorative firing runs.
- Single-source boron supply:Turkey and Kazakhstan concentrate refined boron output, creating geopolitical exposure for borosilicate bottle manufacturers dependent on thermal shock resistance.
- Polymer actuator tolerances:Precision molding limitations in pump mechanism neck finishes restrict unit yield rates, capping throughput for integrated spray-pump configurations.
Strategic Opportunities
- Lightweighting technology licensing:Proprietary wall-thickness uniformity patents from French furnace operators can be monetized across mid-tier Asian manufacturers seeking premium positioning.
- Pharmaceutical-grade cross-certification:Gerresheimer's existing FDA 21 CFR compliance infrastructure enables rapid qualification for US-bound cosmetic brands demanding identical purity standards.
- Direct-to-brand digital sampling:Virtual prototyping platforms are collapsing traditional distributor layers, allowing Hebei cluster producers to pitch finished flacon designs directly to Italian fragrance houses.
Industry Challenges
- Acid-etching artisan scarcity:Frosted decoration treatments require skilled operators in controlled environments; labor pipeline gaps in Austrian decorative firing facilities constrain capacity expansion.
- Dual certification timelines:Simultaneous EU REACH and FDA 21 CFR qualification for recycled-content glass batches extends validation cycles, freezing furnace reconfiguration decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic and Perfume Glass Bottle Market |
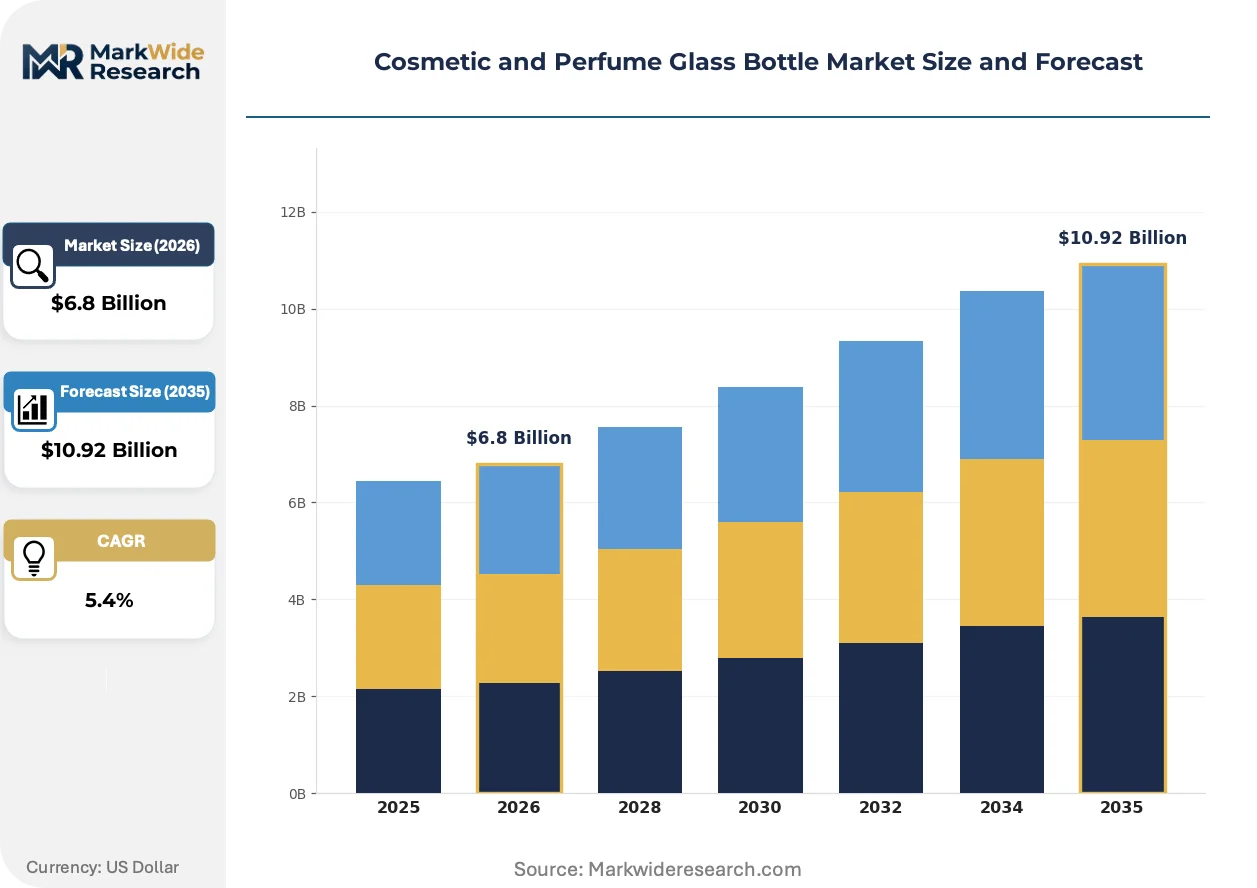
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On, Spray, Pump, Dropper Decoration Type: Frosted, Printed, Labelled, Embossed Closure Type: Cork, Plastic Cap, Metal Cap, Screw Cap End User: Cosmetics Brands, Perfume Manufacturers, Personal Care, Retailers |
| Companies Covered | Stoelzle Glass Group, Hebei Welllive Trade, Verescence, Heinz-Glass, Roma International, Gerresheimer, Zignago Vetro, Vidraria Anchieta, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic and Perfume Glass Bottle Market Strategic Shifts
Glass formation and surface treatment processes are converging with digital control systems and circular material mandates, compressing development cycles while elevating quality consistency thresholds.
Vision-guided robotic inspection is automating defect detection in hot-end glass formation, replacing manual quality checks at Austrian and German furnace operations. Premium fragrance houses now specify 99.97% visual clarity acceptance rates, forcing adoption of machine-learning-based bubble and stone detection. This automation is compressing labor cost differentials between European and Asian production sites.
F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based coatings traditionally used for hydrophobic surface treatments on perfume flacons. German furnace operators now transition to plasma-enhanced chemical vapor deposition alternatives. Decorative metallization segments face 18-month reformulation timelines to maintain EU market access.
Brand-owned material traceability requirements are displacing anonymous bulk purchasing of virgin sand and cullet. Italian luxury fragrance houses now mandate blockchain-documented supply chain records from furnace to filling line. This verification burden falls heaviest on Hebei province exporters serving EU markets without established recovery infrastructure partnerships.
Cosmetic and Perfume Glass Bottle Market Segmentation
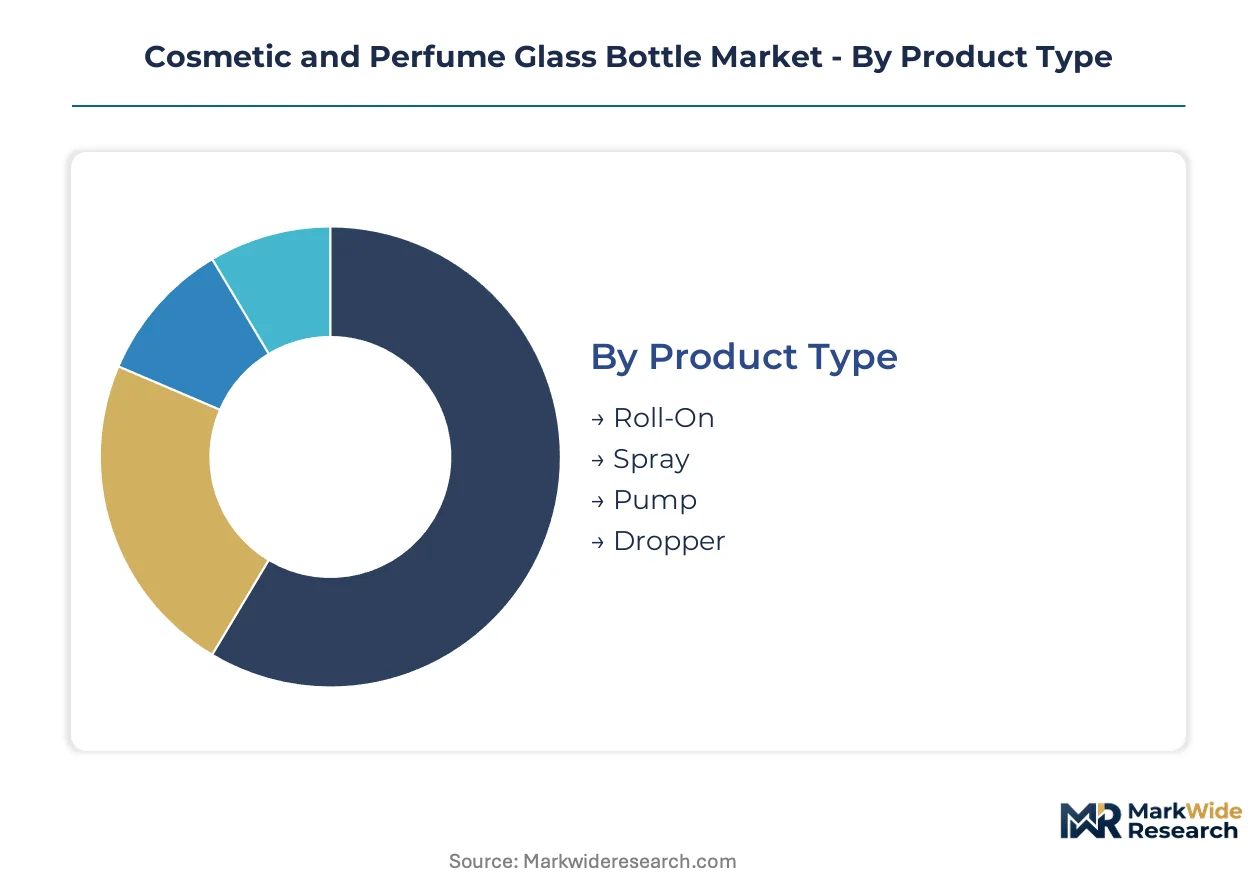
Glass bottle specifications diverge sharply across fragrance delivery mechanisms and surface treatments, with each segment carrying distinct regulatory burdens and margin profiles. Procurement teams must match product type to end-use certification requirements while balancing decoration complexity against furnace throughput constraints.
Product Type:
Spray and pump configurations demand FDA 21 CFR compliance for polymer-glass interface safety, while roll-on and dropper formats face lighter REACH Annex XVII scrutiny on contact substances.
- Spray:Integrated actuator systems require precision tolerances between borosilicate neck finishes and polymer components. French premium fragrance houses concentrate procurement here for limited-edition launches demanding 99.97% visual clarity.
- Pump:Precision molding limitations in mechanism neck finishes restrict unit yield rates. German furnace operators struggle with energy cost volatility when requalifying recycled cullet streams for these high-value configurations.
- Roll-On:Ball-bearing retention demands simpler glass wall specifications suited to mass-market cosmetic brands in Northeast China.
- Dropper:Pipette compatibility requires controlled bore diameter consistency for serum and oil formulations.
Spray sits at the top of the volume ranking, with pump climbing the fastest.
Decoration Type:
Margin stratification follows labor intensity and environmental control requirements, with acid-etching operations commanding premium positioning over printed alternatives.
- Frosted:Acid-etching or sandblasting steps demand skilled labor and controlled environmental conditions. Austrian decorative firing facilities face artisan scarcity that constrains capacity expansion for Italian luxury fragrance houses.
- Printed:Silk-screening and hot stamping offer faster throughput but lower per-unit margins. Hebei province clusters dominate volume supply for mid-tier beauty brands.
- Labelled:Adhesive substrate compatibility requires surface energy matching for durable brand presentation.
- Embossed:Mold engraving costs limit economic viability to high-volume SKU commitments.
Printed holds the largest volume share, though frosted gains share fastest on premium positioning.
Closure Type:
Material substitution timelines vary by regulatory pressure, with metal and plastic caps diverging under ECHA restrictions and F-Gas Regulation phase-down schedules.
- Metal Cap:ECHA cadmium and lead restrictions in decorative enamels force reformulation toward mineral-based alternatives. German metallization segments face 18-month compliance timelines.
- Plastic Cap:Polymer actuator tolerances restrict unit yield rates for integrated spray-pump configurations. FDA 21 CFR contact substance rules govern US-bound shipments from Chinese manufacturers.
- Cork:Natural material sourcing requires blockchain-documented traceability for Italian luxury house procurement.
- Screw Cap:Thread standardization enables cross-supplier compatibility but limits design differentiation.
Plastic cap leads by unit volume, while metal cap expands most quickly on premium fragrance demand.
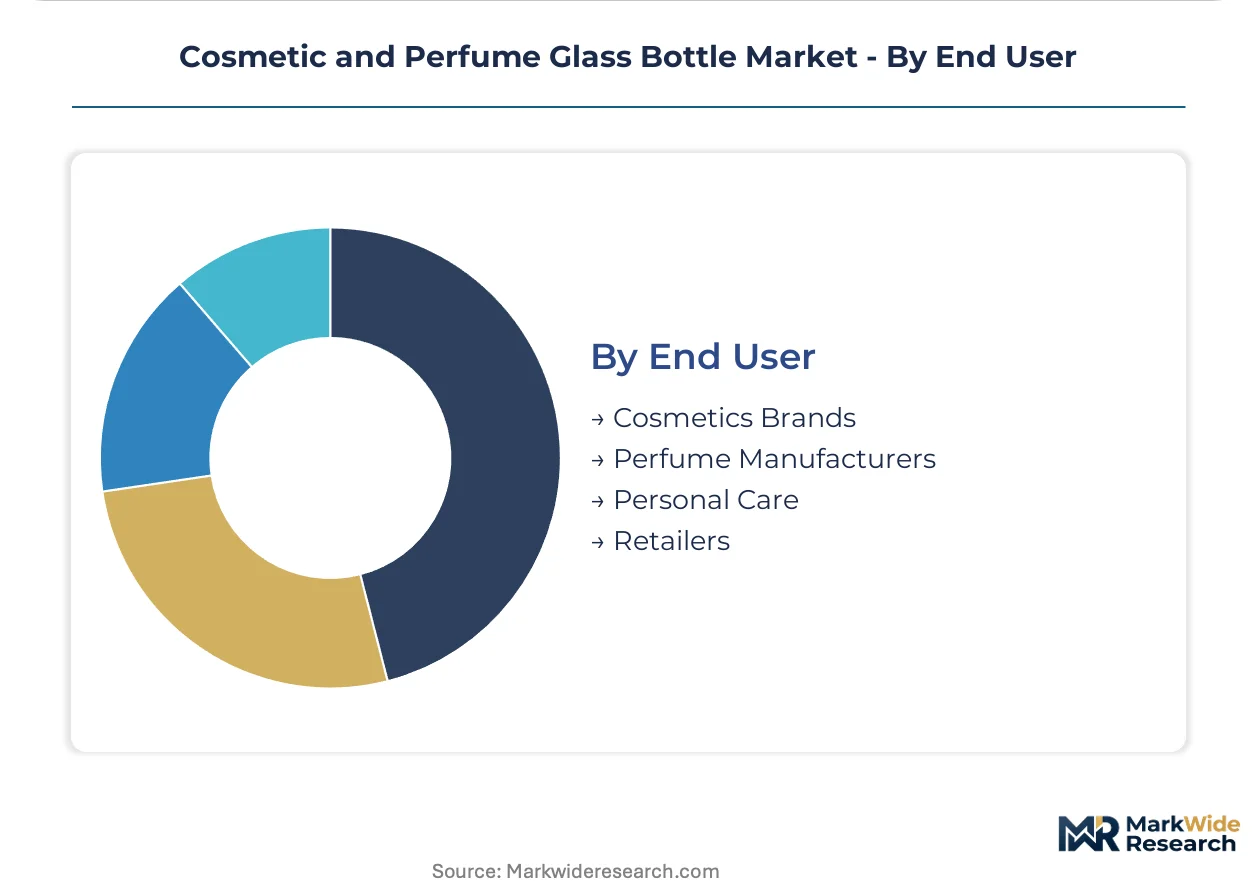
End User:
Customer scale and certification sophistication determine supplier qualification pathways, with perfume manufacturers imposing stricter purity standards than retail private-label programs.
- Perfume Manufacturers:Crystal-clarity standards and REACH compliance requirements align with Gerresheimer's pharmaceutical-grade glass expertise. French and Italian houses mandate blockchain-documented supply chain records.
- Cosmetics Brands:SKU proliferation demands just-in-time supply from Hebei province borosilicate furnace clusters for limited-edition launches.
- Personal Care:Volume scale favors soda-lime glass over borosilicate for cost-sensitive shampoo and lotion packaging.
- Retailers:Private-label programs prioritize standard neck finishes to minimize tooling investment across fragrance and cosmetic categories.
Cosmetics brands anchor volume demand, with perfume manufacturers posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as European energy costs and compliance burdens push brand owners toward Asian furnace clusters while EU markets retain premium positioning through traceability mandates.
France
Limited-edition fragrance launches from Paris-based houses drive borosilicate procurement for crystal-clarity flacons. ECHA REACH Annex XVII restrictions on cadmium and lead in decorative enamels force reformulation of traditional colored glass toward mineral-based alternatives. The Champagne-Ardenne region hosts decorative firing capacity serving Italian luxury brands.
China
Northeast Asian beauty brands demand just-in-time supply for SKU proliferation in serums and oils. NMPA cosmetic packaging standards and dual carbon goals from MEE tighten furnace emission controls. Hebei province concentrates borosilicate glass furnaces that export directly to EU fragrance houses requiring blockchain-documented supply chains.
Germany
Pharmaceutical-grade glass expertise crosses over to perfume applications demanding identical purity standards. F-Gas Regulation phase-down schedules eliminate hydrofluorocarbon coatings, forcing 18-month transitions to plasma-enhanced chemical vapor deposition. Saxony-Anhalt specialty glass operations face structurally higher natural gas input costs versus Asian competitors.
Italy
Luxury fragrance houses mandate recycled-content mandates under EU Packaging and Packaging Waste Regulation timelines. Extended producer responsibility schemes assign full end-of-life cost responsibility to brand owners, accelerating premium glass recovery. Lombardy-based design studios specify frosted acid-etching treatments from Austrian suppliers facing artisan scarcity.
United States
FDA 21 CFR requirements for cosmetic packaging contact substances govern import qualification from Chinese and European manufacturers. Domestic brands prioritize spray and pump configurations with precision polymer-glass tolerances. New Jersey and Pennsylvania distribution hubs consolidate shipments from Hebei exporters seeking rapid US market access.
Cosmetic and Perfume Glass Bottle Market Competitive Environment
European producers anchor the premium tier through decorative firing heritage and pharmaceutical-grade cross-certification; Chinese specialists hold volume positioning via Hebei province furnace clustering and compressed lead times. The vendor base separates into three strategic archetypes: heritage European houses with artisan decoration capabilities, Asian scale producers with just-in-time logistics, and pharmaceutical-crossover operators leveraging FDA compliance infrastructure. Competitive moves concentrate on lightweighting technology licensing and direct-to-brand digital sampling platforms that collapse traditional distributor layers.
Among heritage European fabricators, Stoelzle Glass Group and Gerresheimer exemplify the pharmaceutical-grade crossover archetype, with the former representing Austrian decorative firing heritage and the latter anchoring FDA 21 CFR compliance infrastructure for US-bound shipments. Verescence occupies a position within the French premium tier through proprietary lightweighting patents. Hebei Welllive Trade sits within the Asian scale-producer archetype, exemplifying the Hebei province cluster model that supplies Northeast Asian beauty brands with compressed lead times for limited-edition launches.
| Leading Market Players |
|---|
| Stoelzle Glass Group |
| Hebei Welllive Trade |
| Verescence |
| Heinz-Glass |
| Roma International |
| Gerresheimer |
| Zignago Vetro |
| Vidraria Anchieta |
| SGD Pharma |
| Others |
Value Chain & Pricing Dynamics
Natural gas input costs cascade through European furnace economics into three-tier pricing structure across premium, standard, and economy levels, with Austrian and German decorative firing operations passing energy premiums downstream while Hebei province clusters compress lead-time premiums for Northeast Asian beauty brands.
Pricing Analysis
Distributor margin compression runs through mid-tier printed decoration segments as Hebei province exporters disintermediate traditional European supply layers. Price differentiation separates acid-etched frosted treatments from silk-screened alternatives, with artisan scarcity in Austrian facilities supporting premium positioning. Cost compression in standard-grade soda-lime configurations is intensifying because Turkish boron supply concentration feeds raw material volatility. Cosmetics brands with SKU proliferation demands show highest price sensitivity; French perfume houses with limited-edition launches exhibit least.
Supply Chain Analysis
Container freight rate volatility from China to EU fragrance hubs shapes total delivered cost for Hebei province exporters serving Italian luxury houses. Geographic supply concentration centers on China, Germany, and Austria, with borosilicate furnace clustering in Hebei province and decorative firing heritage in Central Europe. Raw material dependencies draw from Turkish refined boron, high-purity silica sand deposits, and mineral-based colorant feedstocks. Single-source boron vulnerability creates geopolitical exposure for thermal shock-resistant formulations. Distribution runs through brand-direct digital sampling platforms collapsing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a regulatory compounder, with recycled-content mandates and extended producer responsibility schemes forcing furnace requalification investments that favor compliant incumbents with cross-certification infrastructure.
For Market Incumbents: Acquire acid-etching artisan capacity in Austrian decorative firing facilities before labor pipeline gaps harden into permanent bottlenecks. Build backward integration into blockchain-documented cullet recovery partnerships to satisfy Italian luxury house traceability mandates. Threat substitution from polymer actuator precision limitations in pump configurations creates defensible glass neck-finish expertise. Certification investment in simultaneous EU REACH and FDA 21 CFR qualification locks out mid-tier Asian competitors. For New Entrants and Emerging Players: Direct-to-brand digital sampling platforms offer the most penetrable channel wedge, enabling Hebei province producers to pitch finished flacon designs to Paris-based fragrance houses without distributor markup layers. White-space targets include lightweighting technology licensing to mid-tier Asian manufacturers seeking premium positioning, and plasma-enhanced chemical vapor deposition coating services for German metallization segments facing F-Gas Regulation phase-down deadlines. Go-to-market angle: virtual prototyping collapsing 18-month traditional design cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification timelines extend validation cycles and freeze furnace reconfiguration decisions, trapping sub-scale operators without compliance infrastructure. Long-term viability over the coming decade favors pharmaceutical-crossover archetypes with existing FDA 21 CFR compliance pathways and heritage European houses with irreplaceable decorative firing artisan networks. Acquisition target archetype: Austrian or German specialty glass operators with underutilized decorative capacity and reachable REACH compliance. Signal to watch: ECHA cadmium and lead restriction enforcement accelerating mineral-based colorant patent filings.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Licensing | French furnace operators monetize proprietary wall-thickness uniformity patents across Asian mid-tier manufacturers seeking premium positioning. |
| Blockchain-Documented Cullet Recovery | Italian luxury houses mandate material traceability from furnace to filling line, favoring suppliers with established recovery infrastructure partnerships. |
| Pharmaceutical-Grade Cross-Certification | Gerresheimer's existing FDA 21 CFR compliance infrastructure enables rapid qualification for US-bound cosmetic brands demanding identical purity standards. |
| Plasma-Enhanced CVD Coating Transition | German metallization segments face 18-month reformulation timelines to maintain EU market access under F-Gas Regulation phase-down schedules. |
| Direct-to-Brand Digital Sampling | Virtual prototyping platforms collapse traditional distributor layers, allowing Hebei cluster producers to pitch finished designs directly to fragrance houses. |
Study Parameters
Coverage spans France, Italy, Germany, China, and the United States, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged furnace operations managers at Stoelzle Glass Group and Verescence, procurement leads at Paris-based fragrance houses, regulatory affairs specialists navigating ECHA REACH Annex XVII reformulations, and Hebei province export coordinators serving EU-bound shipments. Secondary sources included EU Packaging and Packaging Waste Regulation compliance filings, FDA 21 CFR cosmetic packaging contact substance guidance, NMPA cosmetic packaging standards documentation, and customs records tracking borosilicate glass trade flows. Bottom-up furnace capacity assessments and top-down brand procurement spend estimates were triangulated to anchor volume and value outputs.
Rate-of-change decomposition across the analysis window separates volume growth from pricing mix shifts and currency translation effects. Segmentation dimensions modeled include product type, decoration treatment, closure material, and end-user certification sophistication, with furnace technology tier and regional regulatory cluster as industry-specific cross-cuts. CAGRs were derived from regression-adjusted trend extrapolation incorporating named regulatory milestone impacts and energy cost scenario weightings. Industry-specific forecast inputs encompass boron supply contract renewal cycles and artisan labor pipeline graduation rates from Austrian decorative firing training programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Turkish-Kazakh boron supply geopolitics and EU ETS carbon pricing trajectories affecting furnace economics. Projections reflect assumptions around ECHA enforcement intensity for cadmium and lead restrictions and the pace of F-Gas Regulation coating alternative adoption. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation recycled-content mandate timelines or significant boron supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
United Kingdom Container Glass Market