
 Packaging Testing Services Market | 2026-2036
Packaging Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Testing Services Market Outlook
Pharmaceutical manufacturers are unwinding legacy reliance on generic food-grade testing protocols and instead commissioning dedicated extractables-leachables programs. SGS SA leverages its network of European laboratories to anchor complex stability-migration studies for biologics packaging. Bureau Veritas competes through specialized environmental conditioning chambers that simulate tropical distribution lanes. Intertek Group plc dominates accelerated aging protocols for prefilled syringe systems.
Packaging testing services encompass mechanical, barrier, environmental, and compatibility assessments that verify structural integrity, shelf-life performance, and material safety across supply chains. These services employ controlled parameters such as tensile strength thresholds, oxygen transmission rates, and accelerated temperature-humidity cycling to certify compliance with end-use requirements. Mechanical testing and barrier testing together occupy the largest share of service revenue, reflecting persistent demand for drop-impact validation and moisture-vapor protection in pharmaceutical and electronics verticals. Non-destructive testing represents the fastest-expanding test method category as manufacturers seek to reduce sample destruction costs while maintaining statistical confidence in lot release decisions.
FDA stability guidelines and EMA annexes on plastic immediate packaging materials shape protocol design for pharmaceutical testing programs, while EU REACH and F-Gas Regulation constrain permissible barrier coating chemistries. The EU Green Deal's packaging waste targets are forcing laboratories to develop new compostability and recyclability certification streams. Stakeholders must monitor how divergent national implementation timelines for extended producer responsibility frameworks reshape regional testing demand patterns.
Market Dynamics
Pharmaceutical manufacturers are abandoning legacy food-grade testing protocols in favor of dedicated extractables-leachables programs, while EU Green Deal mandates force laboratories to develop entirely new compostability certification streams. This dual regulatory and technical pressure is compressing testing timelines and expanding required service portfolios simultaneously.
Growth Catalysts
- EMA Annexes on Plastic Immediate Packaging:Pharmaceutical manufacturers commission dedicated stability-migration studies to meet evolving European Medicines Agency requirements for biologics packaging materials.
- Germany:Packaging clusters around Düsseldorf and Hamburg drive specialized testing capacity concentration, creating regional demand density for advanced barrier and mechanical validation services.
- Biodegradable Material Validation:EU single-use plastics directives accelerate laboratory investment in compostability and recyclability certification streams for sustainable packaging alternatives.
Market Restraints
- Specialized Environmental Conditioning Infrastructure:Tropical distribution lane simulation requires capital-intensive chamber investments that constrain mid-tier laboratory expansion.
- F-Gas Regulation Constraints:EU restrictions on fluorinated greenhouse gases limit permissible barrier coating chemistries, complicating moisture-vapor transmission testing protocol design.
- Accelerated Aging Equipment Lead Times:Prefilled syringe system validation demand outstrips supply of qualified thermal cycling chambers, creating testing bottlenecks for sterile packaging programs.
Strategic Opportunities
- Non-Destructive Testing Expansion:Manufacturers seek to reduce sample destruction costs while maintaining statistical confidence in lot release decisions, creating service differentiation potential.
- Extended Producer Responsibility Divergence:Fragmented national implementation timelines across EU member states reshape regional testing demand patterns, opening geographic arbitrage opportunities.
- Biologics Packaging Convergence:Extractables-leachables programs intersect with accelerated aging protocols, enabling integrated service bundles for cell and gene therapy packaging systems.
Industry Challenges
- Extractables-Leachables Chemist Shortage:Specialized analytical chemistry expertise for pharmaceutical packaging migration studies remains scarce relative to biologics pipeline expansion.
- Multi-Standard Harmonization Complexity:Laboratories must simultaneously maintain FDA stability guidelines, EMA annexes, and ISO 11607 compliance without protocol consolidation.
- Legacy Equipment Obsolescence:Existing mechanical testing infrastructure requires retrofitting for biodegradable material validation, straining capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Testing Services Market |
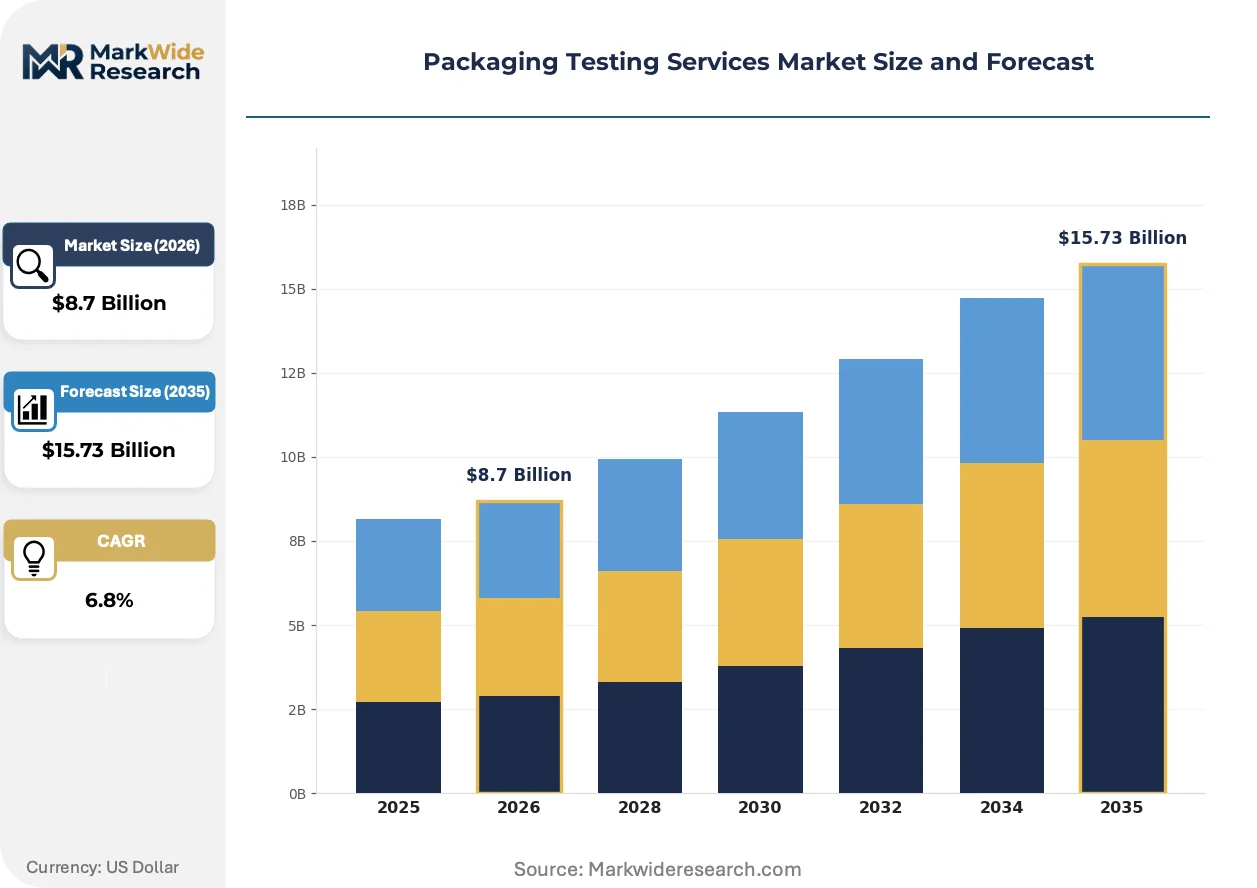
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical Testing, Barrier Testing, Environmental Testing, Compatibility Testing Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Test Method: Destructive Testing, Non-Destructive Testing, Accelerated Life Testing, Shelf Life Testing Material Type: Plastics, Glass, Metal, Composites |
| Companies Covered | SGS SA, Intertek Group plc, Bureau Veritas, Eurofins Scientific SE, TÜV SÜD AG, ALS Limited, Microbac Laboratories, Inc., EMSL Analytical, Inc., Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Testing Services Market Strategic Shifts
Digital traceability systems and automated sample handling are compressing turnaround times for complex stability studies, while regulatory fragmentation across jurisdictions forces laboratories to maintain parallel certification tracks. These forces are reshaping competitive positioning around speed and geographic coverage rather than equipment scale alone.
Non-destructive testing methods incorporating X-ray computed tomography and terahertz imaging are supplanting traditional destructive sampling for barrier integrity validation. Pharmaceutical manufacturers adopt these techniques to preserve limited biologics batches during release testing. The shift is compressing per-lot testing costs while enabling 100% inspection protocols that were previously economically unfeasible for high-value packaging systems.
The EU Green Deal's packaging waste targets are forcing laboratories to develop new compostability and recyclability certification streams. Industrial consequence includes mandatory biodegradation timeline verification under divergent national extended producer responsibility frameworks. Germany and France lead implementation, with testing demand concentrating in laboratories capable of simultaneous mechanical performance and end-of-life validation.
Buyer consolidation among contract development and manufacturing organizations is compressing vendor qualification cycles and demanding integrated service bundles spanning extractables-leachables, stability, and transportation simulation. Traditional single-test procurement is giving way to multi-year framework agreements with preferred laboratory networks. This pattern is most visible in the United States, where top pharmaceutical manufacturers reduce qualified supplier lists to simplify audit burden and streamline regulatory submission packages.
Packaging Testing Services Market Segmentation
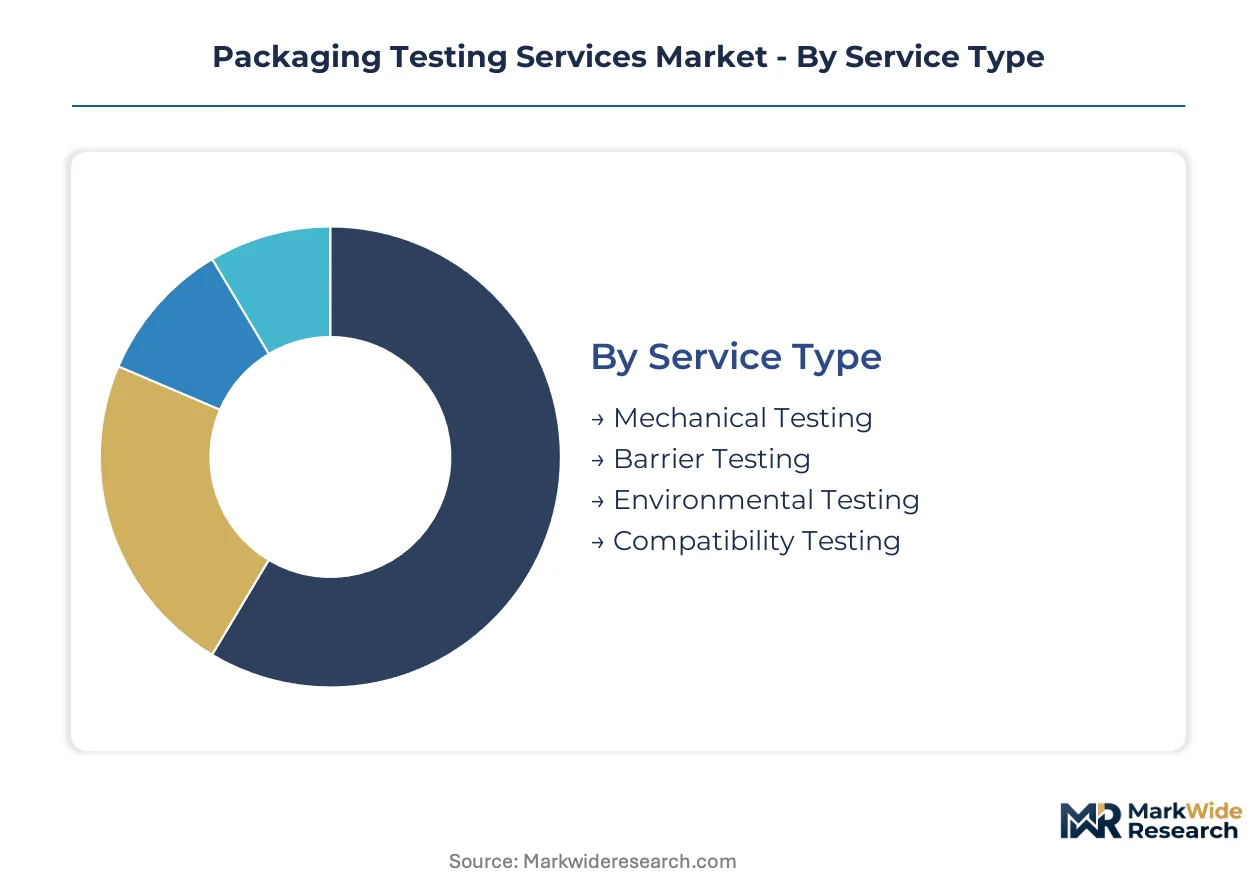
Testing service providers configure laboratory capacity around distinct technical protocols and end-use specifications. Segmentation reveals where capital equipment investments concentrate and which regulatory frameworks shape protocol design for each customer category.
Service Type:
FDA stability guidelines and EMA annexes on plastic immediate packaging materials differentiate protocol requirements across mechanical, barrier, environmental, and compatibility disciplines.
- Mechanical Testing:Drop-impact validation, compression resistance, and tensile strength verification employ standardized ASTM and ISO protocols. Pharmaceutical manufacturers in Germany commission specialized burst-testing for prefilled syringe systems to meet EMA migration study requirements.
- Barrier Testing:Oxygen transmission rate and moisture-vapor transmission rate measurements determine shelf-life performance for oxygen-sensitive biologics. Demand concentrates in laboratories serving Hamburg packaging clusters where tropical distribution lane simulation capabilities anchor regional competitiveness.
- Environmental Testing:Temperature-humidity cycling and thermal shock protocols validate packaging performance across climatic zones.
- Compatibility Testing:Extractables-leachables programs assess chemical migration between packaging materials and contained pharmaceutical products.
Established volume favors Mechanical Testing; emerging adoption favors Barrier Testing.
Industry Vertical:
Cost tier differentiation separates commodity food-grade validation from premium pharmaceutical programs requiring dedicated analytical chemistry expertise.
- Food & Beverage:Generic migration studies and shelf-life validation dominate service procurement. Mid-tier laboratories in France compete on turnaround speed for routine mechanical and barrier assessments under EU food contact regulations.
- Pharmaceuticals:Biologics packaging demands integrated extractables-leachables, stability-migration, and accelerated aging protocols. FDA and EMA submission requirements force manufacturers to qualify specialized laboratory networks with demonstrated cell and gene therapy packaging experience.
- Cosmetics:Compatibility testing for active ingredient stability drives demand for chemical resistance validation.
- Electronics:Moisture sensitivity level certification and electrostatic discharge protection testing address semiconductor packaging requirements.
Pharmaceuticals commands premium pricing tiers; Food & Beverage sustains volume throughput.
Test Method:
Volume concentration in destructive methods contrasts with margin expansion in non-destructive technologies that preserve limited biologics batches.
- Destructive Testing:Traditional sampling approaches require larger batch quantities for statistical confidence. Electronics manufacturers in Japan continue procuring burst and drop testing despite rising sample costs.
- Non-Destructive Testing:X-ray computed tomography and terahertz imaging enable 100% inspection protocols for high-value packaging systems. Pharmaceutical manufacturers adopt these techniques to reduce per-lot testing expenditures while maintaining lot release confidence.
- Accelerated Life Testing:Thermal cycling chambers simulate long-term aging effects within compressed timelines for regulatory submission deadlines.
- Shelf Life Testing:Real-time stability studies under controlled environmental conditions establish expiration dating for regulated products.
Destructive Testing retains volume dominance; Non-Destructive Testing climbs the fastest.
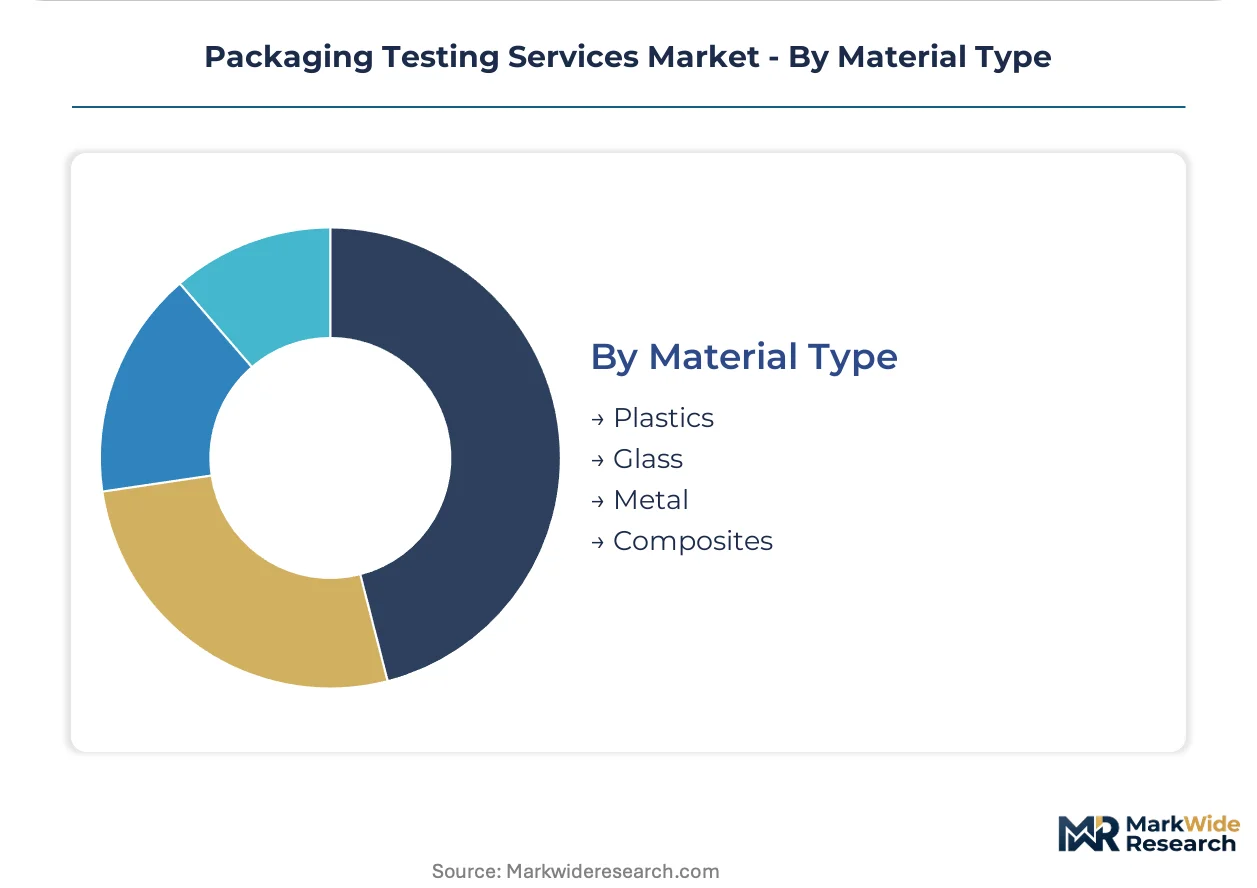
Material Type:
Supply concentration in plastics testing infrastructure reflects pharmaceutical and food packaging demand, while biodegradable alternatives force capital reallocation.
- Plastics:Polymer characterization, additive migration analysis, and thermal property verification anchor laboratory service menus. EU single-use plastics directives and Green Deal waste targets accelerate compostability certification demand for biodegradable polymer alternatives.
- Glass:Chemical durability, hydrolytic resistance, and delamination testing address parenteral packaging requirements for biologics.
- Metal:Corrosion resistance and coating integrity validation serve aerosol and canned product applications.
- Composites:Multi-layer structure analysis and interlayer adhesion testing support advanced barrier packaging systems.
Plastics sustains infrastructure investment; Composites gain share fastest among material categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and multinational food brands drive testing demand concentration in mature regulatory jurisdictions with dense packaging innovation clusters.
Germany
Biologics packaging migration studies and accelerated aging protocols dominate service procurement from Düsseldorf and Hamburg industrial zones. EMA annexes on plastic immediate packaging materials mandate specialized extractables-leachables validation that only accredited laboratories provide. The Hamburg packaging cluster anchors tropical distribution simulation capacity serving Northern European pharmaceutical exporters.
United States
FDA stability guidelines for sterile packaging and prefilled syringe systems generate premium-tier testing demand from Boston-Cambridge biotech corridors. The agency's evolving container closure integrity requirements compress submission timelines and expand required protocol portfolios. New Jersey and North Carolina pharmaceutical manufacturing belts concentrate qualified laboratory networks with demonstrated biologics experience.
China
NMPA biocompatibility standards for imported medical device packaging drive foreign laboratory qualification campaigns among domestic manufacturers. The regulator's convergence with ISO 11607 protocols forces infrastructure upgrades at Shanghai and Suzhou testing facilities. Yangtze River Delta packaging clusters absorb capital investment in environmental conditioning chambers for tropical climate simulation.
France
ANSM pharmaceutical packaging material notifications and EU Green Deal waste targets create dual compliance pressure on Paris-region laboratories. Extended producer responsibility implementation timelines ahead of EU minimums accelerate compostability certification demand. Lyon and Strasbourg industrial basins develop integrated mechanical-end-of-life validation streams for biodegradable alternatives.
Switzerland
Swissmedic biologics packaging requirements and proximity to Basel pharmaceutical headquarters sustain premium testing demand. The regulator's emphasis on container closure integrity for cell and gene therapy products drives specialized capability investment. Zurich and Geneva laboratory networks maintain parallel FDA-EMA submission tracks for multinational pharmaceutical clients.
Packaging Testing Services Market Competitive Environment
Player mix skews toward diversified inspection and certification conglomerates with cross-border laboratory networks. Market structure concentrates around three global entities with pharmaceutical-specialized capabilities, while mid-tier environmental and food-safety laboratories compete on turnaround speed for commodity protocols. Strategic archetypes include integrated life-science testing platforms, regional mechanical-barrier specialists, and emerging biodegradable validation boutiques. Dominant competitive moves encompass laboratory network expansion through strategic partnerships and portfolio diversification into cell and gene therapy packaging protocols.
Within the integrated testing platform tier, SGS SA, Intertek Group plc, and Bureau Veritas exemplify archetypes capable of anchoring complex multi-jurisdiction submission packages. SGS SA occupies a position representing European laboratory network density for stability-migration studies. Intertek Group plc exemplifies the accelerated aging and container closure integrity specialization vector. Bureau Veritas represents environmental conditioning infrastructure scale for tropical distribution lane simulation. These three entities sit within a competitive set where pharmaceutical manufacturer vendor consolidation favors laboratories with demonstrated FDA and EMA dual-track experience.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group plc |
| Bureau Veritas |
| Eurofins Scientific SE |
| TÜV SÜD AG |
| ALS Limited |
| Microbac Laboratories, Inc. |
| EMSL Analytical, Inc. |
| Krones AG |
| Others |
Value Chain & Pricing Dynamics
Capital-intensive environmental conditioning infrastructure in Germany and the United States creates pronounced scale economies that compress unit costs for tropical distribution simulation while elevating price floors for mid-tier laboratories lacking comparable chamber investments. This concentration of qualified capacity around Düsseldorf, Hamburg, and New Jersey pharmaceutical corridors simultaneously anchors premium pricing tiers and constrains supply elasticity for accelerated aging protocols.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate long-term framework agreements between pharmaceutical manufacturers and integrated testing platforms. Three-tier pricing structure across premium, standard, and economy levels separates EMA-accredited extractables-leachables programs from routine mechanical validation and commodity food-grade assessments. Price differentiation hinges on certification tier and geographic proximity to pharmaceutical manufacturing clusters. Cost compression in standard-tier barrier testing is intensifying because mid-tier laboratories in France and Spain compete aggressively on turnaround speed for generic protocols. Contract development and manufacturing organizations exhibit highest price sensitivity due to buyer consolidation compressing vendor qualification cycles, while cell and gene therapy developers show lowest sensitivity given limited qualified supplier alternatives.
Supply Chain Analysis
Germany, the United States, and Switzerland anchor specialized analytical chemistry capacity for pharmaceutical packaging migration studies. Equipment supply draws from thermal cycling chamber manufacturers in Japan and environmental simulation system producers in the United States. Raw material dependencies encompass fluorinated barrier coating chemistries constrained by EU F-Gas Regulation, high-purity reference standards for extractables identification, and certified polymer films for validation protocols. Single-source vulnerability permeates qualified thermal cycling chamber supply, where prefilled syringe validation demand outstrips manufacturing lead times. Distribution runs through accredited laboratory networks maintaining parallel FDA-EMA submission tracks rather than spot procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging testing services function as a service-attach opportunity where recurring validation contracts and multi-year framework agreements expand faster than one-time equipment certification revenue. After-sales protocol maintenance and regulatory submission support layers compound lifetime customer value beyond initial test execution.
For Market Incumbents: Consolidate vendor qualification advantages by deepening captive supply of specialized extractables-leachables chemists and expanding Hamburg tropical simulation capacity ahead of Northern European pharmaceutical export growth. EMA-FDA dual-track accreditation represents the critical defensive moat against emerging biodegradable validation boutiques capturing Green Deal-driven compostability demand. For New Entrants and Emerging Players: ANSM fast-track certification for Paris-region extended producer responsibility compliance offers entry into France's accelerated biodegradation timeline verification market. White-space concentrates in biodegradable material validation where legacy mechanical testing infrastructure requires retrofitting, and in cell and gene therapy packaging where extractables-leachables protocols intersect with accelerated aging. Target Lyon and Strasbourg industrial basins developing integrated mechanical-end-of-life validation streams, positioning on turnaround speed for compostability certification under divergent national frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratories with demonstrated biologics packaging experience and non-destructive testing infrastructure capable of 100% inspection protocols. Long-term viability rests on regulatory submission density rather than equipment scale alone, with five-to-ten-year value accretion tied to FDA-EMA dual-track maintenance and cell and gene therapy protocol diversification. Acquisition targets should display specialized environmental conditioning capacity and extractables-leachables chemist retention. The signal to watch is NMPA biocompatibility standard convergence accelerating foreign laboratory qualification campaigns among Chinese domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Destructive Testing Infrastructure Investment | X-ray computed tomography and terahertz imaging capabilities enable 100% inspection protocols for high-value biologics packaging systems. |
| Dual-Track Accreditation Expansion | Parallel FDA-EMA submission capability anchors multi-jurisdiction pharmaceutical manufacturer framework agreements. |
| Biodegradable Validation Capability Buildout | Compostability and recyclability certification streams capture EU Green Deal packaging waste target compliance demand. |
| Extractables-Leachables Chemist Recruitment | Specialized analytical chemistry expertise scarcity constrains biologics pipeline expansion service capacity. |
| Tropical Distribution Simulation Capacity Addition | Environmental conditioning chambers for climatic zone validation anchor regional competitiveness in Hamburg and New Jersey corridors. |
Study Parameters
A spread of perspectives from pharmaceutical regulatory affairs leads, laboratory operations directors, contract development and manufacturing organization procurement managers, and biodegradable material R&D heads converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from FDA stability guideline publications, EMA annexes on plastic immediate packaging materials, EU REACH and F-Gas Regulation documentation, and ISO 11607 protocol standards. Bottom-up service revenue estimates triangulated against top-down pharmaceutical packaging expenditure allocations.
Segmentation dimensions modeled encompass service type, industry vertical, test method, material type, and regional regulatory cluster across the analysis window. CAGRs derived from historical laboratory capacity expansion rates, pharmaceutical pipeline biologics share trajectories, and EU extended producer responsibility implementation timelines. Forecast inputs incorporated biodegradable polymer substitution elasticities and non-destructive testing adoption curves for high-value packaging systems.
Decision-makers should treat outputs as directional under sustained EMA-FDA regulatory convergence and EU Green Deal waste target enforcement; material deviation in national extended producer responsibility timelines or fluorinated gas regulation stringency would warrant model refresh. Recalibration cycles align with material shifts in pharmaceutical biologics pipeline composition and biodegradable material mechanical performance certification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Packaging Burst Strength Test Market