
 Global Twin Neck Dosing Bottle Market | 2026-2036
Global Twin Neck Dosing Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Twin Neck Dosing Bottle Market Outlook
Multi-source procurement is recalibrating as pharmaceutical packagers diversify mold suppliers across Asia and Europe. Silgan Plastics Corporation leverages captive blow-molding capacity across North American plants to anchor large-format contracts. Bharat Propack Private Limited specializes in multi-cavity tooling for 10ml to 100ml twin neck formats, competing on unit economics for generic drug exporters.
Twin neck dosing bottles integrate two separate chambers connected by a common neck, typically blow-molded from HDPE or PET with calibrated volumetric chambers enabling precise ratio dispensing without external measuring devices. The design serves pharmaceutical reconstitution, agricultural chemical mixing, and industrial two-part adhesive systems where cross-contamination prior to use must be eliminated. Plastic dominates unit volume due to resin cost efficiency and impact resistance, though glass variants command premium positioning in biotechnology cold-chain applications where inertness outweighs freight penalties. Liquid dosing leads application value as oral suspensions and reconstitutable antibiotics require exact dilution ratios at point of use.
FDA 21 CFR Part 211 cGMP standards and EMA Annex 1 sterile manufacturing guidelines shape material selection, dimensional tolerance requirements, and extractables testing protocols for pharmaceutical-grade twin neck containers. REACH SVHC disclosure obligations and EU MDR traceability mandates add compliance layers for suppliers serving European medical device and diagnostic reagent markets. Stakeholders must monitor evolving pharmacopeial chapters on plastic packaging systems as USP and EP revisions tighten leachable thresholds for pediatric liquid formulations.
Market Dynamics
Pharmaceutical contract packaging consolidation is concentrating purchasing power among fewer buyers, forcing twin neck dosing bottle suppliers to demonstrate FDA and EMA compliance documentation upfront while compressing lead times for multi-cavity tooling programs.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:The updated guidelines mandate enhanced container closure integrity for reconstitutable antibiotics, driving replacement demand for tamper-evident twin neck formats across European generic drug exporters.
- Reconstitutable biologics:Lyophilized monoclonal antibodies requiring precise dilution ratios at point-of-use are expanding addressable volume beyond traditional oral suspensions into cold-chain therapeutics.
- China's NMPA track-and-trace mandates:Serialized packaging requirements for liquid pharmaceuticals are accelerating adoption of integrated twin neck systems with molded-in datamatrix compatibility.
Market Restraints
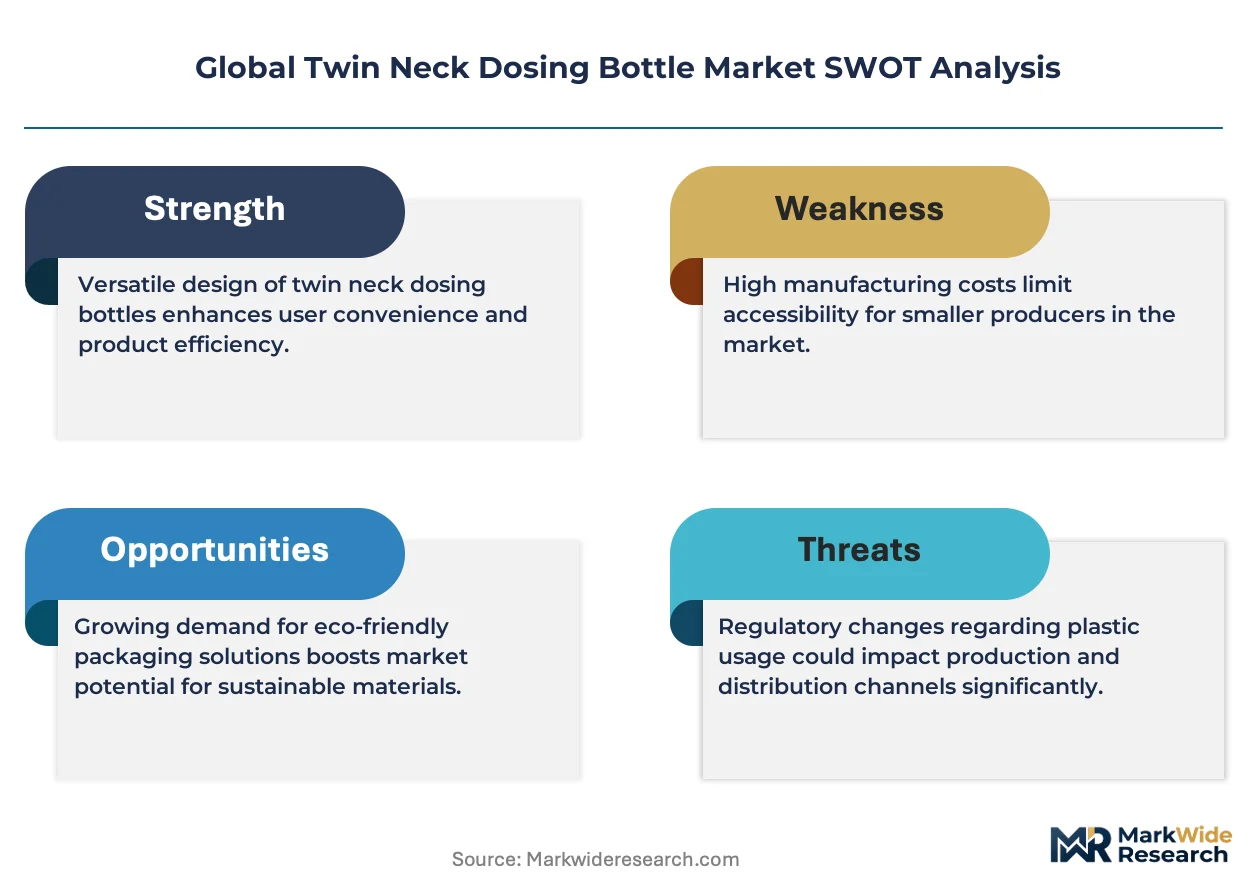
- HDPE resin price volatility:Feedstock fluctuations tied to naphtha cracking margins in Asian petrochemical hubs compress margin visibility for high-volume contract manufacturers.
- Mold fabrication concentration:Precision multi-cavity tooling for calibrated volumetric chambers relies on a limited supplier base concentrated in southern Germany and Zhejiang Province, creating queue risk.
- Glass substitution in biotech:Borosilicate vials with separate diluent ampoules retain preference for parenteral applications where USP glass inertness outweighs twin neck convenience.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Gujarat and Telangana are scaling liquid formulation capacity, creating demand for 10ml to 50ml twin neck formats with CDSCO-compliant child-resistant closures.
- Agricultural drone chemical mixing:Two-part herbicide systems requiring field-side ratio dispensing represent an emerging application outside pharmaceutical packaging with less stringent extractables testing.
- EU MDR traceability incentives:Medical device reagents with dual-component chemistries qualify for accelerated market access when packaged in tamper-evident twin neck systems with embedded RFID tags.
Industry Challenges
- Extractables validation timelines:USP 1664.1 protocol execution for new resin grades adds 18-24 months to pharmaceutical qualification programs, delaying revenue recognition.
- Blow-molding technician scarcity:Parison programming expertise for calibrated dual-chamber wall thickness control is concentrated among aging workforces in North American and European converter facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Twin Neck Dosing Bottle Market |
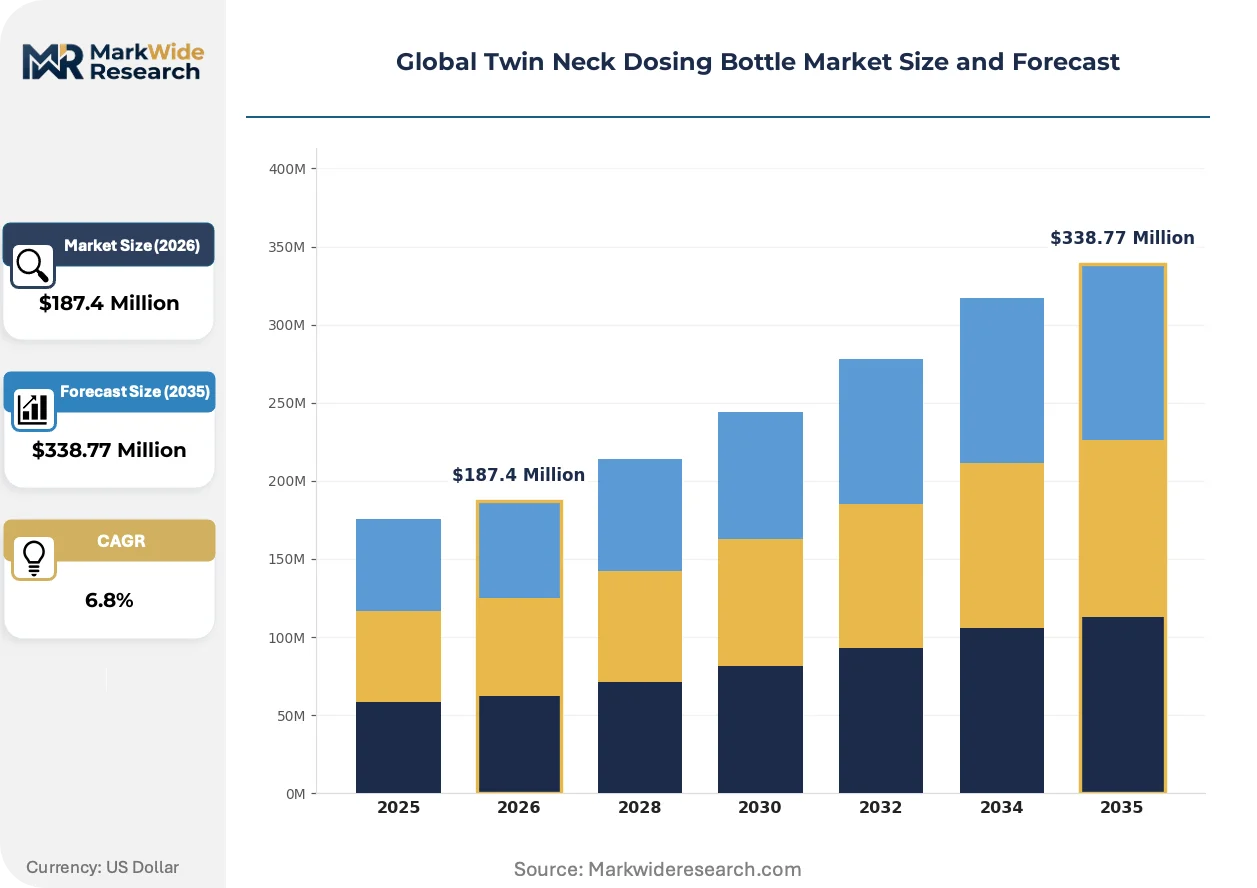
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Flexible End User: Pharmaceuticals, Biotechnology, Chemicals, Food & Beverage Application: Liquid Dosing, Powder Dosing, Laboratory Use, Industrial Use Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Silgan Plastics Corporation, Richmond Containers CTP Ltd., IGH Holdings, Inc., Bharat Propack Private Limited, Hebei ShengXiang Package Materials Co.,Ltd., Kaufman Container Company, Charles Tennant & Company Ltd., Richards Packaging, Inc., Hangzhou Glory Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Twin Neck Dosing Bottle Market Strategic Shifts
Active pharmaceutical ingredient stability requirements and point-of-care dilution protocols are reshaping material selection and chamber geometry in twin neck dosing bottle design. Suppliers now compete on validated extractables profiles rather than unit cost alone.
Post-consumer recycled HDPE is absorbing pharmaceutical packaging specifications as EMA and FDA issue draft guidance on recycled plastic use in drug containers. Generic antibiotic manufacturers in India and Eastern Europe are piloting 30% rHDPE content in non-sterile oral suspension bottles. The technology is absorbing price premiums that previously favored virgin resin, compressing the cost gap between sustainable and conventional formats.
REACH SVHC disclosure obligations are tightening leachable thresholds for pediatric liquid formulations across European supply chains. The regulation forces reformulation of colorants and processing aids in HDPE masterbatches. Pediatric antibiotic packagers in Germany and France are accelerating supplier audits to preempt ECHA candidate list expansions.
Hospital pharmacy consolidation is compressing vendor qualification cycles as centralized purchasing departments demand single-source packaging for formulary standardization. Integrated delivery networks in the United States are replacing fragmented distributor relationships with direct manufacturer contracts. The shift concentrates volume with converters offering validated sterile filling partnerships rather than component-only supply.
Global Twin Neck Dosing Bottle Market Segmentation
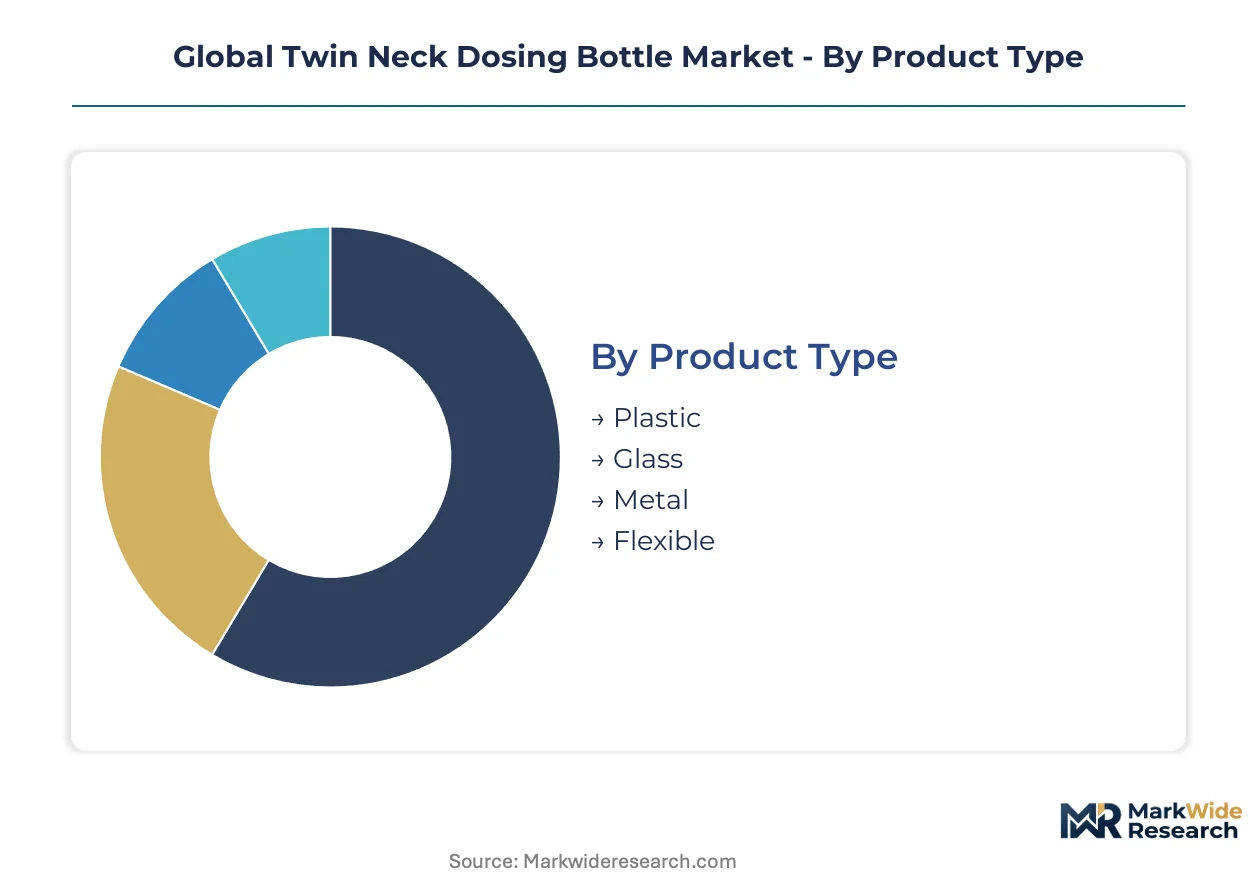
Twin neck dosing bottle procurement patterns diverge sharply between high-volume pharmaceutical contracts and specialized biotech applications. Material selection, end-use requirements, and channel economics each create distinct competitive battlegrounds with different margin profiles and qualification barriers.
Product Type:
Volume deployment favors resin-based formats while premium positioning concentrates in inert materials for sensitive payloads.
- Plastic:HDPE and PET dominate unit economics through blow-molding efficiency and impact resistance. Oral suspension manufacturers in India and Eastern Europe are piloting 30% post-consumer recycled content as EMA and FDA draft guidance on recycled plastics tightens.
- Glass:Borosilicate variants command cold-chain premiums where USP inertness outweighs freight penalties. Lyophilized monoclonal antibody packagers in Germany and Switzerland specify glass for parenteral reconstitution despite handling complexity.
- Metal:Aluminum twin-neck systems serve industrial adhesive applications requiring pressure resistance beyond plastic capabilities.
- Flexible:Multi-layer films with calibrated chambers emerge for single-use diagnostic reagents in point-of-care settings.
Mature deployment sits with Plastic. Newer deployment is concentrated in Flexible.
End User:
Regulatory intensity separates pharmaceutical compliance requirements from industrial flexibility.
- Pharmaceuticals:FDA 21 CFR Part 211 cGMP and EMA Annex 1 standards mandate extractables validation and child-resistant closure integration. Contract packagers in the United States concentrate purchasing power through consolidated vendor qualification.
- Biotechnology:Cold-chain therapeutics demand chamber geometries preserving lyophilized cake structure during reconstitution. Swiss and German biologics manufacturers drive specification tightening for monoclonal antibody formats.
- Chemicals:Agricultural drone mixing systems require field-side ratio dispensing with less stringent leachable thresholds than drug applications.
- Food & Beverage:Concentrate and flavoring systems adopt twin-neck convenience for consumer mixing applications with food-contact compliance.
Established qualification sits with Pharmaceuticals. Emerging specification intensity concentrates in Biotechnology.
Application:
Precision requirements escalate from industrial mixing through laboratory calibration to clinical dosing.
- Liquid Dosing:Oral suspensions and reconstitutable antibiotics require exact dilution ratios at point of use. Indian CDMOs in Gujarat and Telangana are scaling 10ml to 50ml format demand with CDSCO-compliant closures.
- Powder Dosing:Lyophilized biologics and effervescent formulations need moisture-segregated chambers until activation. European generic exporters are replacing legacy formats under revised EMA sterile manufacturing guidelines.
- Laboratory Use:Diagnostic reagents with dual-component chemistries specify molded-in datamatrix compatibility for China's NMPA track-and-trace mandates.
- Industrial Use:Two-part adhesive and coating systems prioritize cost efficiency over extractables documentation.
Volume concentration sits with Liquid Dosing. Specification complexity is expanding fastest in Powder Dosing.
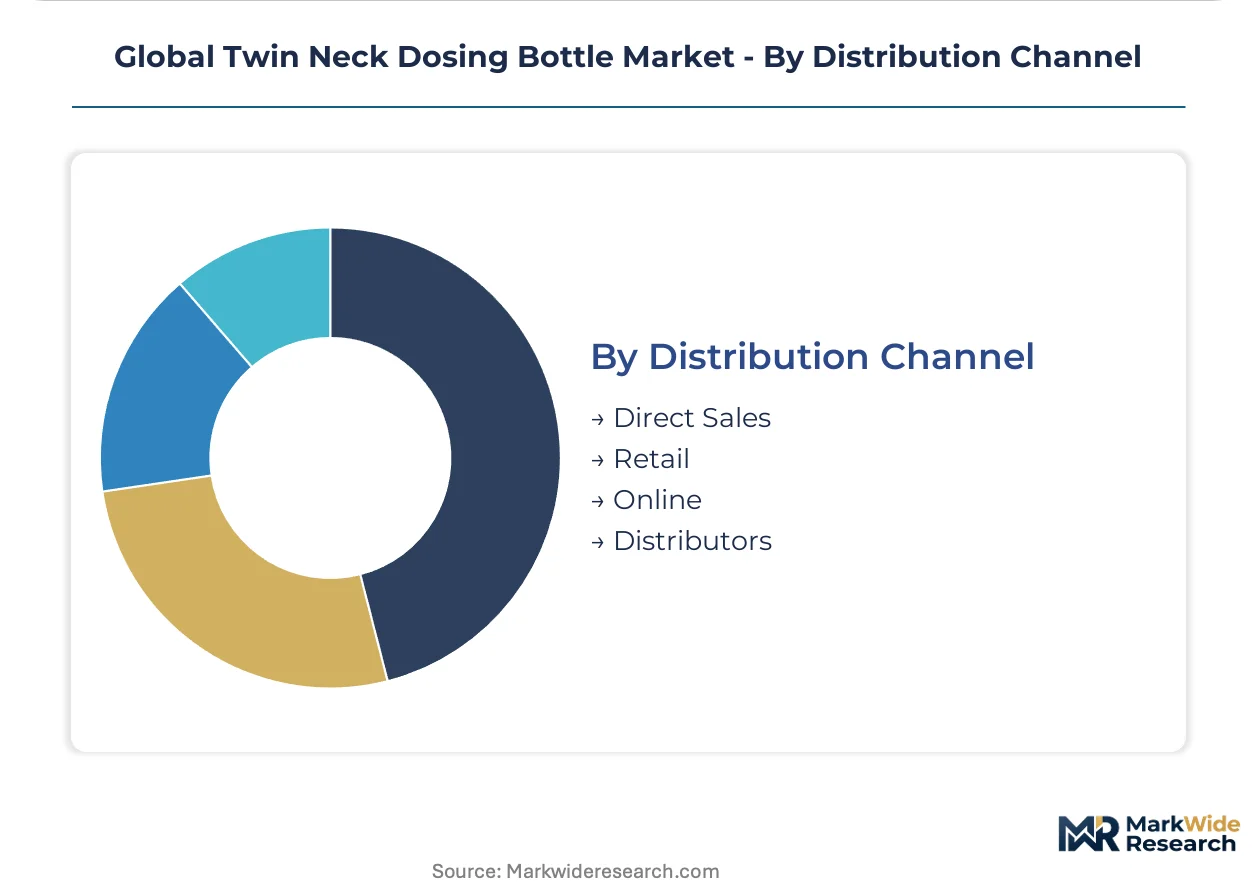
Distribution Channel:
Channel selection reflects order scale, customization depth, and regulatory documentation requirements.
- Direct Sales:Large pharmaceutical contracts bypass intermediaries for validated sterile filling partnerships. Integrated delivery networks in the United States are consolidating fragmented distributor relationships into direct manufacturer agreements.
- Retail:Consumer-facing concentrate systems reach pharmacies and agricultural supply stores through packaged goods distribution.
- Online:Specialty laboratory suppliers and small-batch chemical formulators procure through digital channels for specification transparency.
- Distributors:Regional packaging distributors serve mid-tier generic manufacturers with standardized multi-cavity tooling programs.
Relationship depth sits with Direct Sales. Digital penetration is climbing fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha cracking margins in Asian petrochemical hubs concentrate HDPE resin supply, shaping manufacturing economics across dosing bottle production clusters worldwide.
United States
Integrated delivery networks in the Midwest and Southeast are consolidating fragmented distributor relationships into direct manufacturer contracts for validated sterile filling partnerships. FDA 21 CFR Part 211 cGMP compliance documentation anchors purchasing decisions among large pharmaceutical contract packagers. Chicago and New Jersey corridor converters are expanding multi-cavity blow-molding capacity to capture hospital pharmacy formulary standardization contracts.
Germany
EMA Annex 1 sterile manufacturing revisions are driving replacement demand for tamper-evident twin neck formats among generic drug exporters. REACH SVHC disclosure obligations and EU MDR traceability mandates tighten leachable thresholds for pediatric liquid formulations. Southern Baden-Württemberg mold fabrication clusters face queue risk as precision multi-cavity tooling demand outstrips regional capacity.
China
NMPA track-and-trace mandates for serialized liquid pharmaceuticals are accelerating adoption of integrated twin neck systems with molded-in datamatrix compatibility. Zhejiang Province mold suppliers dominate precision multi-cavity tooling for calibrated volumetric chambers. Yangtze River Delta contract packaging services are expanding fastest as domestic biologics manufacturers scale reconstitutable antibody production.
India
CDSCO-compliant child-resistant closures are required as contract development and manufacturing organizations in Gujarat and Telangana scale liquid formulation capacity. PLI scheme incentives for pharmaceutical manufacturing are drawing twin neck format demand for 10ml to 50ml antibiotic suspensions. Ahmedabad and Hyderabad industrial corridors are piloting 30% post-consumer recycled HDPE content in non-sterile oral suspension bottles.
Switzerland
Swissmedic oversight of cold-chain therapeutics preserves borosilicate glass preference for parenteral reconstitution despite handling complexity. Basel and Zurich biologics manufacturers drive specification tightening for monoclonal antibody chamber geometries preserving lyophilized cake structure. Premium positioning for biotechnology applications sustains inert material demand against plastic unit economics.
Global Twin Neck Dosing Bottle Market Competitive Environment
Global majors compete with regional champions across blow-molding capacity and mold fabrication expertise, producing a tiered structure where FDA/EMA compliance documentation separates qualified suppliers from commodity converters. The vendor base stratifies between captive resin processors, independent multi-cavity tooling specialists, and integrated sterile filling partners. Three archetypes dominate: North American contract manufacturers with validated pharmaceutical partnerships, Asian resin-integrated converters competing on unit economics, and European precision mold fabricators serving biotechnology cold-chain specifications. Capacity expansion and backward integration into captive resin compounding represent the dominant competitive vectors.
Among North American fabricators, Silgan Plastics Corporation exemplifies the captive blow-molding archetype with multi-plant resin processing infrastructure. Bharat Propack Private Limited anchors the Asian specialist tier, representing multi-cavity tooling expertise for mid-volume generic drug export formats. Richmond Containers CTP Ltd. occupies a position within the European compliance-focused segment, reflecting the regulatory documentation intensity shaping purchasing decisions among EMA-aligned pharmaceutical packagers.
| Leading Market Players |
|---|
| Silgan Plastics Corporation |
| Richmond Containers CTP Ltd. |
| IGH Holdings, Inc. |
| Bharat Propack Private Limited |
| Hebei ShengXiang Package Materials Co.,Ltd. |
| Kaufman Container Company |
| Charles Tennant & Company Ltd. |
| Richards Packaging, Inc. |
| Hangzhou Glory Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade certification tiers create a sharp bifurcation between validated sterile filling partnerships and commodity component supply, with EMA and FDA compliance documentation commanding substantial premiums while generic antibiotic packagers in India and Eastern Europe drive unit economics toward virgin resin parity with recycled alternatives. This tier divergence manifests in procurement structures where large integrated delivery networks in the United States consolidate direct manufacturer contracts for validated sterile filling, while mid-tier generic exporters fragment purchases across regional distributors with standardized multi-cavity tooling programs.
Pricing Analysis
Extractables validation warranties bundled with pharmaceutical-grade twin neck formats separate premium positioning from unbundled commodity supply where buyers assume qualification costs. Three-tier pricing structure across certified sterile filling, documented pharmaceutical component, and undifferentiated industrial formats reflects FDA 21 CFR Part 211 cGMP and EMA Annex 1 compliance depth as the primary differentiation driver. Cost compression in high-volume HDPE formats is intensifying because naphtha cracking margin volatility in Asian petrochemical hubs erodes margin visibility for contract manufacturers. Generic drug exporters in India demonstrate highest price sensitivity, while Swiss biologics manufacturers accept substantial premiums for borosilicate glass cold-chain specifications.
Supply Chain Analysis
Precision multi-cavity mold fabrication rests on southern German and Zhejiang Province supplier clusters, creating queue risk as calibrated volumetric chamber demand outstrips regional tooling capacity. HDPE resin supply draws from naphtha cracking operations concentrated in China, South Korea, and Saudi Arabia, with blow-molding technician scarcity in North American and European converter facilities compounding production constraints. Single-source vulnerability in mold fabrication represents the dominant structural risk, particularly for pharmaceutical packagers requiring 18-24 month USP 1664.1 extractables validation timelines. Distribution runs through direct manufacturer contracts for large pharmaceutical accounts, with regional packaging distributors serving mid-tier generic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract packaging consolidation is compressing vendor qualification cycles and forcing weaker mold fabricators and commodity converters out of pharmaceutical supply chains as purchasing power concentrates among fewer buyers demanding upfront FDA and EMA compliance documentation.
For Market Incumbents: Anticipate aggressive qualification demands from hospital pharmacy consolidation by securing captive blow-molding capacity expansions in Chicago and New Jersey corridor plants before integrated delivery networks finalize formulary standardization contracts. Deepen backward integration into resin compounding to hedge naphtha cracking margin volatility, while preemptively auditing colorant and processing aid suppliers against REACH SVHC candidate list expansions to defend EMA-aligned positioning. For New Entrants and Emerging Players: Begin with agricultural drone chemical mixing applications for two-part herbicide systems, where field-side ratio dispensing requirements lack pharmaceutical extractables testing barriers and established suppliers maintain minimal presence. Gujarat and Telangana CDMO expansion for 10ml to 50ml antibiotic suspension formats offers the most penetrable geography, with CDSCO-compliant child-resistant closure integration as the specific go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by North American contract manufacturers seeking validated sterile filling partnerships, with European precision mold fabricators serving biotechnology cold-chain specifications as secondary liquidity routes. Long-term viability favors converters with demonstrated FDA and EMA compliance documentation and captive multi-cavity tooling capacity across the analysis window. Watch NMPA track-and-trace mandate enforcement velocity in China as the signal indicating accelerated adoption of molded-in datamatrix compatible systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply hedges naphtha cracking margin volatility in Asian petrochemical hubs. |
| Multi-Cavity Tooling Capacity Expansion | Chicago and New Jersey corridor additions capture hospital pharmacy formulary standardization contracts. |
| Extractables Validation Partnership | USP 1664.1 protocol execution with pharmaceutical packagers accelerates 18-24 month qualification timelines. |
| Post-Consumer Recycled Content Pilot | 30% rHDPE adoption in Indian non-sterile oral suspension bottles aligns with EMA and FDA draft guidance. |
| Molded-in Datamatrix Compatibility Development | Integrated twin neck systems address China's NMPA serialized packaging mandates for liquid pharmaceuticals. |
Study Parameters
Multi-period observation of FDA 21 CFR Part 211 cGMP compliance documentation requirements, EMA Annex 1 sterile manufacturing guideline revisions, and NMPA track-and-trace mandate implementation anchored the trend analysis, supplemented by interviews with pharmaceutical contract packaging procurement directors, blow-molding facility operations managers, precision mold fabrication engineers, and regulatory affairs specialists at generic drug exporters. Secondary validation drew from FDA warning letter databases, EMA inspection findings, CDSCO manufacturing license records, USP plastic packaging system monographs, and REACH SVHC candidate list publications. Bottom-up volume modeling across material type, end-use segment, and geographic production cluster triangulated against top-down pharmaceutical packaging expenditure estimates.
Input-output matrices linking HDPE resin supply from naphtha cracking operations through blow-molding converter capacity to downstream pharmaceutical and biotech demand shaped the analytical framework across the analysis window. Segmentation dimensions modeled included material type, end-use regulatory intensity, application precision requirements, and distribution channel relationship depth. CAGRs were derived from elasticity-adjusted demand projections incorporating EMA Annex 1 revision compliance deadlines and China's NMPA serialization rollout pace. Industry-specific forecast inputs encompassed mold fabrication queue lengths and USP 1664.1 validation timeline distributions.
EMA guideline revision timing, REACH SVHC list expansion scope, and naphtha cracking margin volatility are the dominant revision risks to projection outputs. Forecasts reflect assumptions regarding regulatory enforcement consistency and petrochemical feedstock cost stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market