
 Container Glass in the UAE Market | 2026-2036
Container Glass in the UAE Market Size, Share, and Industry Trends Forecast 2026-2036
Container Glass in the UAE Market Insights
Multi-source raw material procurement is decoupling from the traditional single-supplier model that dominated UAE container glass manufacturing for decades. RAK Ghani Glass LLC leverages its Ras Al Khaimah furnace complex to sustain cost advantages on high-volume bottle orders. Gulf Glass Industries anchors its position through specialized pharmaceutical vial production that meets Gulf Cooperation Council pharmacopeia standards.
Container glass is a non-porous, chemically inert packaging material formed from silica sand, soda ash, and limestone melted at approximately 1,500°C, then shaped by blow-and-blow or press-and-blow forming for liquid and semi-solid containment. Its primary purpose is to protect sensitive contents from oxidation, moisture ingress, and UV degradation across food, pharmaceutical, and cosmetic supply chains. Bottles command the largest volume share within product type segments, though vials extract higher unit margins from pharmaceutical cold-chain applications. Food & Beverage end users dominate absolute tonnage, while Cosmetics generates premium pricing through decorative surface treatment capabilities.
ESMA's UAE Standards for Glass Packaging and the Gulf Standardization Organization's technical regulations shape mandatory recyclability thresholds and chemical leaching limits for all domestic production. Dubai Municipality's sustainable manufacturing guidelines enforce waste-heat recovery benchmarks that raise capital requirements for new furnace installations. Stakeholders must monitor how Abu Dhabi's industrial tariff restructuring affects imported cullet pricing, which determines whether local batch reformulation or foreign recycled glass sourcing becomes the lower-carbon compliance path.
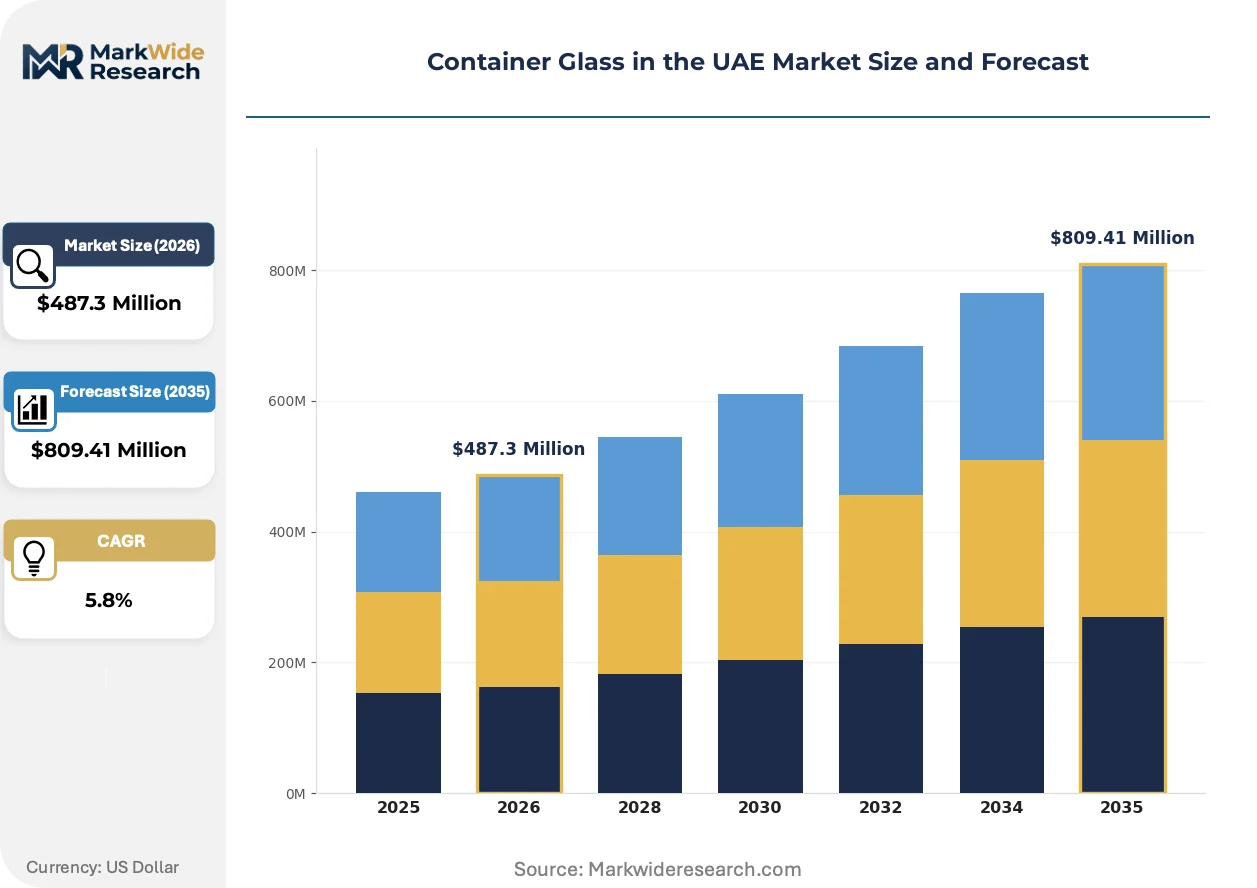
Market Dynamics
ESMA's recyclability mandates are compressing batch reformulation timelines across UAE furnace operations, forcing producers to choose between domestic cullet processing investments and imported recycled glass sourcing.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Abu Dhabi and Dubai health authorities are mandating temperature-stable packaging for biologics distribution, pulling demand for borosilicate vials that withstand thermal shock.
- REACH-aligned export requirements:Gulf Cooperation Council pharmacopeia standards now mirror European chemical leaching thresholds, qualifying UAE-made vials for EU pharmaceutical supply chains.
- Premium cosmetic packaging:Dubai Design District brands specify heavier decorated glass bottles over plastic alternatives, creating margin-rich demand for surface-treated container glass.
Market Restraints
- Natural gas price volatility:Furnace operations depend on Emirates National Oil Company pipeline supply contracts, exposing batch costs to regional energy market swings.
- Single-furnace supply concentration:Ras Al Khaimah hosts the majority of domestic melting capacity, creating geographic vulnerability to logistics disruptions at Jebel Ali port.
- Aluminum can substitution:Beverage bottlers in Dubai Industrial City are trialing lightweight metal formats for sparkling water and ready-to-drink categories.
Strategic Opportunities
- Sharjah pharmaceutical cluster:Underpenetrated emirate offers greenfield sites for vial production serving northern Gulf markets with shorter lead times than European imports.
- Waste-heat recovery incentives:Dubai Municipality sustainable manufacturing guidelines reward furnace upgrades with expedited permitting for capacity expansion.
- Decorative surface technologies:Convergence of digital printing and organic coatings enables cosmetic brands to execute limited-edition runs without mold changeover costs.
Industry Challenges
- Furnace engineering talent scarcity:Specialized refractory maintenance and combustion optimization skills concentrate with aging European technical consultants.
- ESMA certification timelines:New product qualification for pharmaceutical vials requires 18-24 months of leaching stability documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Glass in the UAE Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Chemicals Manufacturing Stage: Primary Production, Surface Treatment, Quality Control, Packaging Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | RAK Ghani Glass LLC, Saverglass LLC, Al Tajir Glass Industries, Gulf Glass Industries, Frigoglass Jebel Ali FZE, Emirates Glass LLC, Global Packaging FZC, Hotpack Packaging Industries LLC, Al Wara Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Glass in the UAE Market Trends and Innovations
Electrification of melting technology and digital decoration systems are compressing the traditional trade-off between production scale and customization flexibility across UAE container glass operations.
Oxy-fuel combustion retrofitting is replacing regenerative air-gas furnace designs in Ras Al Khaimah facilities. RAK Ghani Glass and Gulf Glass Industries are completing burner conversions that cut nitrogen oxide emissions by half. This technology is integrating with existing furnace infrastructure without requiring full rebuilds, preserving capital for downstream forming equipment.
ESMA's UAE Standards for Glass Packaging now mandate minimum post-consumer recycled content thresholds for all domestic production. The regulation forces batch houses to qualify new cullet suppliers or invest in in-house beneficiation lines. Pharmaceutical vial manufacturers face the steepest compliance burden due to purity requirements that limit recycled glass ratios.
Cosmetic brand procurement teams are consolidating supplier relationships around single-source decorative capabilities. Dubai Design District headquarters now specify vendors offering both container forming and surface treatment under one roof. This pattern concentrates contract value with integrated producers while marginalizing standalone decorators in Ajman industrial zones.
Container Glass in the UAE Market Segmentation
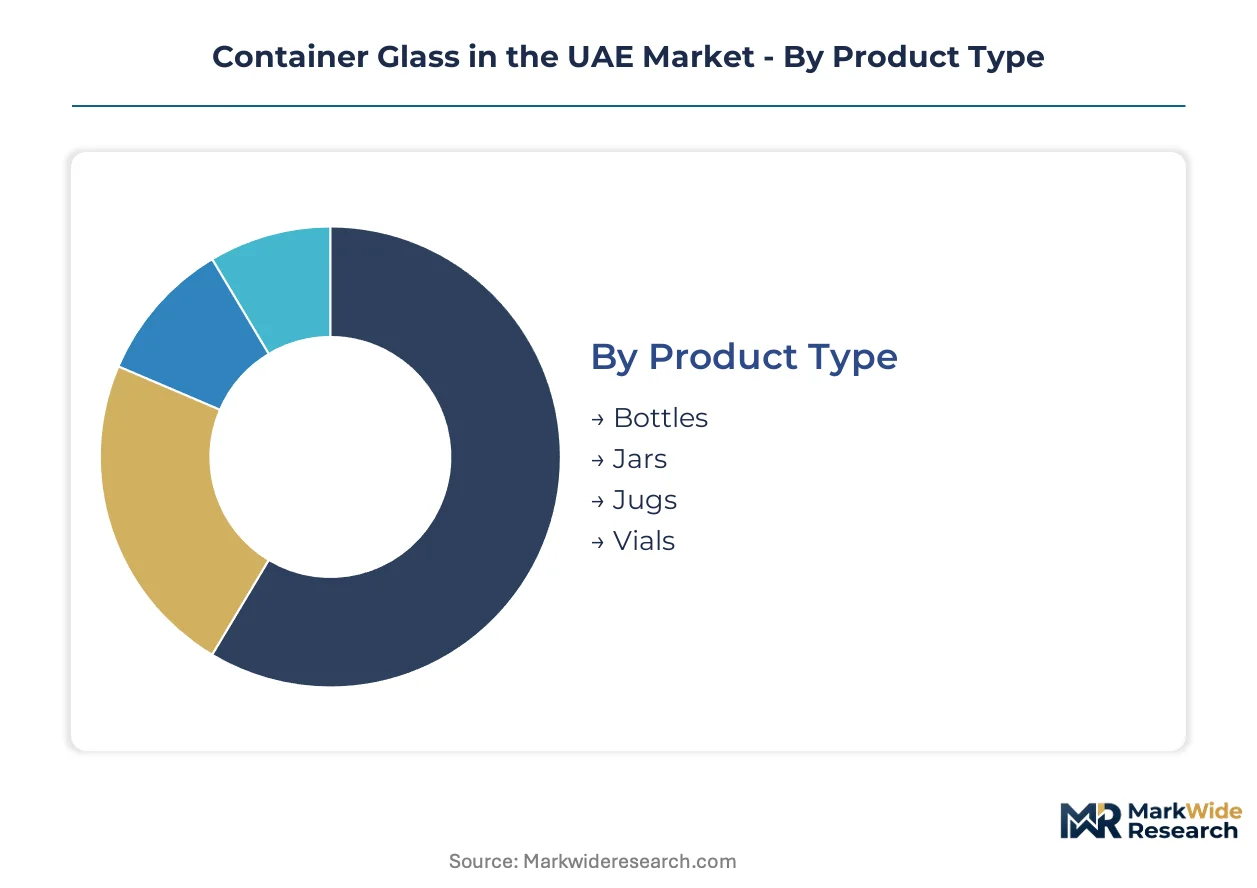
Segmentation reveals how UAE container glass producers allocate furnace capacity across divergent margin profiles. Pharmaceutical vials command premium pricing against commodity beverage bottles, while surface treatment capabilities determine access to Dubai's cosmetic brand headquarters.
Product Type:
Volume concentration sits with high-tonnage formats serving mass-market beverages. Premium extraction concentrates in specialized pharmaceutical and cosmetic containers requiring thermal or decorative performance.
- Bottles:Formed through blow-and-blow or press-and-blow processes for liquid containment across carbonated drinks, spirits, and oils. Food & Beverage bottlers in Dubai Industrial City pull the majority of domestic furnace output for standard amber and flint grades.
- Vials:Small-diameter borosilicate or soda-lime containers engineered for pharmaceutical stability and thermal shock resistance. Abu Dhabi and Dubai health authority mandates for biologics cold-chain distribution are accelerating demand for Type I borosilicate vials that withstand autoclave sterilization cycles.
- Jars:Wide-mouth containers for semi-solid food preservation and cosmetic creams. RAK Ghani Glass furnaces produce standard jar formats for regional condiment brands.
- Jugs:Large-format containers for edible oils and industrial chemicals. Limited domestic production; most volume imports from European suppliers.
Mature deployment sits with bottles. Newer deployment is concentrated in vials.
End User:
Application-driven specifications separate commodity tonnage from value-added contracts. ESMA leaching limits and GCC pharmacopeia standards create tiered compliance burdens across customer categories.
- Food & Beverage:Dominates absolute furnace tonnage through high-volume bottle orders for water, juice, and dairy. Dubai Municipality packaging regulations mandate minimum recycled content thresholds that reshape batch house sourcing.
- Pharmaceuticals:Demands borosilicate vials with documented chemical stability and USP/EP compliance. Abu Dhabi health authority procurement specifications for temperature-stable biologics distribution are pulling specialized container investment.
- Cosmetics:Premium brands in Dubai Design District specify heavier decorated glass with organic coatings and digital printing. Surface treatment capabilities determine supplier selection more than base container cost.
- Household Chemicals:Standard amber and flint containers for cleaning agents and solvents. Price-sensitive procurement favors imported over domestic supply.
Pharmaceuticals is climbing the fastest among end-user categories.
Manufacturing Stage:
Capital intensity varies dramatically across the production chain. Furnace melting absorbs 60-70% of fixed investment, while downstream stages offer modular expansion paths.
- Primary Production:Silica sand, soda ash, and limestone melting at 1,500°C in regenerative or oxy-fuel furnaces. Ras Al Khaimah hosts the majority of UAE melting capacity.
- Surface Treatment:Organic coating, digital printing, and labeling that transforms commodity containers into premium cosmetic packaging. Dubai Design District brands now require integrated forming and decoration capabilities.
- Quality Control:Automated inspection for dimensional tolerance, wall thickness, and chemical leaching stability. ESMA certification timelines extend 18-24 months for pharmaceutical vial qualification.
- Packaging:Palletization and protective wrapping for Jebel Ali port distribution. Waste-heat recovery investments upstream reduce per-unit energy costs at this stage.
Primary production capacity expansion is stalling. Surface treatment investment is accelerating.
Distribution Channel:
Channel selection reflects order scale and customization requirements. Direct relationships dominate pharmaceutical and cosmetic procurement, while wholesale intermediaries serve fragmented food & beverage accounts.
- Direct Sales:Long-term contracts between producers and major beverage bottlers or pharmaceutical manufacturers. Emirates National Oil Company pipeline supply contracts for furnace energy are often bundled with volume commitments.
- Wholesale:Distributor networks serving mid-size food processors and regional trading houses. Jebel Ali port logistics concentration shapes inventory positioning.
- Online Retail:Emerging channel for specialty cosmetic containers and small-batch decorative orders. Digital printing capabilities enable limited-edition runs without mold changeover costs.
- Supermarkets:Indirect channel through private-label beverage and condiment suppliers. Price pressure favors lightweight plastic substitution in sparkling water categories.
Direct sales relationships are deepening. Online retail experimentation is expanding most quickly among cosmetic container suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical and cosmetic packaging demand concentrates in Dubai and Abu Dhabi, while furnace capacity clusters in Ras Al Khaimah. This geographic split between demand centers and production infrastructure shapes logistics costs and supplier selection criteria across the emirates.
Dubai
Dubai Design District headquarters specify heavier decorated glass bottles for premium cosmetics, pulling surface treatment investment toward the emirate. Dubai Municipality enforces sustainable manufacturing guidelines with waste-heat recovery benchmarks for furnace operations. Jebel Ali port logistics concentration creates vulnerability to supply chain disruptions for northern emirate producers.
Abu Dhabi
Health authority mandates for temperature-stable biologics distribution accelerate demand for borosilicate vials. The emirate's pharmaceutical procurement specifications now require documented cold-chain packaging performance. Khalifa Industrial Zone offers greenfield sites for vial production serving northern Gulf markets with shorter lead times than European imports.
Sharjah
Underpenetrated emirate status attracts pharmaceutical cluster development interest from producers seeking proximity to Dubai without premium land costs. Sharjah's industrial zones offer competitive utility pricing for energy-intensive furnace operations. Hamriyah Free Zone positioning enables export access to Saudi Arabia and Oman markets.
Ras Al Khaimah
RAK Ghani Glass LLC anchors the majority of domestic melting capacity at its furnace complex. The emirate's cost advantages on high-volume bottle orders sustain competitiveness for commodity beverage containers. Geographic concentration of primary production creates single-point-of-failure risk for national supply security.
Northern Emirates
Ajman industrial zones host standalone decorators facing margin pressure from integrated cosmetic packaging producers. Fujairah's port infrastructure offers alternative shipping routes bypassing Jebel Ali congestion. Umm Al Quwain maintains limited container glass presence focused on trading and distribution rather than manufacturing.
Container Glass in the UAE Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit furnaces with oxy-fuel combustion technology to meet ESMA emissions thresholds. The vendor base splits between integrated manufacturers with captive melting capacity and downstream specialists in surface treatment and decoration. Two strategic archetypes define positioning: scale-driven commodity bottle producers serving beverage accounts, and premium-tier specialists capturing cosmetic and pharmaceutical margins. Competitive moves cluster around furnace technology licensing partnerships and backward integration into cullet beneficiation to secure recycled glass supply.
Within the integrated manufacturing tier, RAK Ghani Glass LLC and Gulf Glass Industries exemplify divergent specialization strategies. RAK Ghani Glass anchors scale-driven production from its Ras Al Khaimah furnace complex, while Gulf Glass Industries occupies a position focused on pharmaceutical vial qualification. Saverglass LLC represents the premium cosmetic packaging archetype with decorative surface capabilities. Emirates Glass LLC and Al Tajir Glass Industries sit within the mid-tier commodity segment serving regional beverage and food accounts. Frigoglass Jebel Ali FZE, Global Packaging FZC, Hotpack Packaging Industries LLC, and Al Wara Group distribute across various downstream and trading positions without primary melting capacity.
| Leading Market Players |
|---|
| RAK Ghani Glass LLC |
| Saverglass LLC |
| Al Tajir Glass Industries |
| Gulf Glass Industries |
| Frigoglass Jebel Ali FZE |
| Emirates Glass LLC |
| Global Packaging FZC |
| Hotpack Packaging Industries LLC |
| Al Wara Group |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade certification separates premium vial producers from commodity bottle manufacturers, creating a bifurcation where ESMA leaching documentation and GCC pharmacopeia compliance command 40-60% unit price premiums over standard amber grades. This certification ladder concentrates pricing power with Gulf Glass Industries and integrated decorators in Dubai Design District, while Ras Al Khaimah furnace operators compete on volume throughput for beverage accounts. Supply chain configuration reinforces this split: direct long-term contracts dominate pharmaceutical procurement, whereas wholesale intermediaries fragment price discovery for food and beverage bottlers.
Pricing Analysis
Volume-margin splits separate three distinct pricing tiers across UAE container glass. Pharmaceutical vials extract premium returns through USP/EP compliance documentation and 18-24 month ESMA qualification timelines, while cosmetic surface treatment commands price premiums via digital printing and organic coating capabilities. Commodity beverage bottles face cost compression from aluminum can substitution trials in Dubai Industrial City and natural gas price volatility under ENOC pipeline contracts. Food and beverage bottlers exhibit highest price sensitivity, negotiating annual volume commitments against spot cullet costs, whereas pharmaceutical procurement teams prioritize supply security over unit economics.
Supply Chain Analysis
Direct-to-pharma channels handle temperature-sensitive biologics packaging demand from Abu Dhabi and Dubai health authorities, while wholesale distributors serve fragmented food processor accounts across the northern emirates. Primary melting capacity concentrates in Ras Al Khaimah at RAK Ghani Glass facilities, with surface treatment and decoration clustering around Dubai Design District brand headquarters. Raw material sourcing draws from silica sand deposits in the UAE, imported soda ash from North American suppliers, and cullet beneficiation investments responding to ESMA recycled content mandates. Single-furnace geographic concentration creates vulnerability to Jebel Ali port logistics disruptions, with alternative Fujairah routing offering partial mitigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container glass manufacturing in the UAE is consolidating around integrated capabilities as ESMA emissions thresholds and pharmaceutical certification burdens force standalone decorators and single-furnace operators toward acquisition or exit. Stricter recyclability mandates and 18-24 month vial qualification timelines are accelerating this filtration.
For Market Incumbents: Lock in pharmaceutical certification advantages by completing GCC pharmacopeia documentation for borosilicate vial exports to European supply chains. Extend backward integration into cullet beneficiation to secure ESMA-compliant recycled glass feedstock before imported material faces Abu Dhabi industrial tariff restructuring. Aluminum can substitution in sparkling water categories and oxy-fuel combustion retrofit costs threaten commodity bottle margins without premium segment diversification. For New Entrants and Emerging Players: Enter via Sharjah pharmaceutical cluster development, where greenfield vial production sites offer proximity to Dubai demand centers without premium land costs. Target underpenetrated northern Gulf markets through Hamriyah Free Zone positioning, delivering shorter lead times than European imports for temperature-stable biologics packaging. Go-to-market execution should emphasize integrated forming and surface treatment capabilities to capture Dubai Design District cosmetic brand procurement consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with integrated manufacturers possessing captive furnace capacity and pharmaceutical qualification documentation, given REACH-aligned export requirements and biologics cold-chain expansion across the Gulf. Long-term viability over a multi-year horizon favors producers with oxy-fuel combustion completion and waste-heat recovery compliance under Dubai Municipality guidelines. The signal to watch is Abu Dhabi industrial tariff restructuring on imported cullet, which determines whether domestic beneficiation investments or foreign recycled glass sourcing becomes the lower-carbon compliance path.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Combustion Retrofit | RAK Ghani Glass and Gulf Glass Industries cut nitrogen oxide emissions by half while preserving capital for forming equipment. |
| Cullet Beneficiation Investment | Batch houses qualify new suppliers or build in-house lines to meet ESMA post-consumer recycled content thresholds. |
| Pharmaceutical Vial Qualification | 18-24 month leaching stability documentation opens REACH-aligned export pathways to European supply chains. |
| Integrated Surface Treatment Capability | Dubai Design District brands consolidate supplier relationships around single-source decorative glass procurement. |
| Sharjah Greenfield Expansion | Underpenetrated emirate offers competitive utility pricing and Hamriyah Free Zone access to Saudi and Oman markets. |
Research Methodology
Multi-period observation of furnace capacity utilization, ESMA certification timelines, and pharmaceutical procurement specifications anchored the trend analysis, supplemented by interviews with plant managers at Ras Al Khaimah melting facilities, procurement leads at Dubai Design District cosmetic brands, regulatory affairs specialists navigating GCC pharmacopeia alignment, and distribution channel partners at Jebel Ali port operators. Secondary validation drew from ESMA technical regulations, Dubai Municipality sustainable manufacturing guidelines, Gulf Standardization Organization pharmacopeia standards, and customs data on cullet import flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed value and volume forecasts across product type dimensions including bottles, vials, jars, and jugs, with end-user stratification across food and beverage, pharmaceutical, cosmetic, and household chemical applications. Manufacturing stage splits between primary production, surface treatment, quality control, and packaging captured capital intensity differentials. CAGRs were derived from elasticity modeling against pharmaceutical cold-chain expansion rates, premium cosmetic packaging pull from Dubai Design District, and natural gas price volatility under ENOC contract structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ESMA regulatory tightening or sustained aluminum can substitution in beverage categories. Periodic stress-testing of base assumptions is recommended, particularly regarding Abu Dhabi industrial tariff restructuring effects on imported cullet economics and oxy-fuel combustion technology adoption timelines across Ras Al Khaimah furnace operations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Decanters Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Hungary Container Glass Market