
 United Kingdom (UK) Glass Bottles and Containers Market | 2026-2036
United Kingdom (UK) Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom (UK) Glass Bottles and Containers Market Insights
Supermarket private-label supply chains is narrowing as retailers consolidate their glass packaging procurement around fewer, larger suppliers. Encirc leverages its Elton facility's furnace efficiency to anchor supply contracts with major grocery multiples. Beatson Clark competes through specialized pharmaceutical amber glass expertise that sustains margins in regulated medical segments. Ardagh Group controls significant share of the beer and cider bottle trade through long-standing brewery relationships.
United Kingdom glass bottles and containers are silica-based packaging vessels formed through blow-and-blow or press-and-blow processes, typically containing 70-74% silicon dioxide with soda ash and limestone fluxes, designed to provide inert, impermeable storage for consumable and industrial products. The Food & Beverage segment dominates volume throughput, with premium spirits and craft beer driving demand for custom shapes and embossed branding that commands higher unit economics. The Pharmaceuticals segment specializes in smaller-format amber and flint bottles with tight dimensional tolerances, where compliance with MHRA standards creates defensive margin pools for qualified suppliers. Medium Bottles represent the most contested size tier across multiple end-use applications.
MHRA guidelines on pharmaceutical packaging integrity, combined with DEFRA's packaging waste regulations and the UK Plastic Packaging Tax, collectively elevate glass as the compliant default for brands seeking to avoid polymer levies. The British Standards Institution maintains dimensional and thermal shock specifications that shape manufacturing investments and quality certification requirements. Stakeholders must monitor how post-Brexit divergence from EU packaging directives affects export certification burdens for UK-based molders serving European brand owners.
Market Dynamics
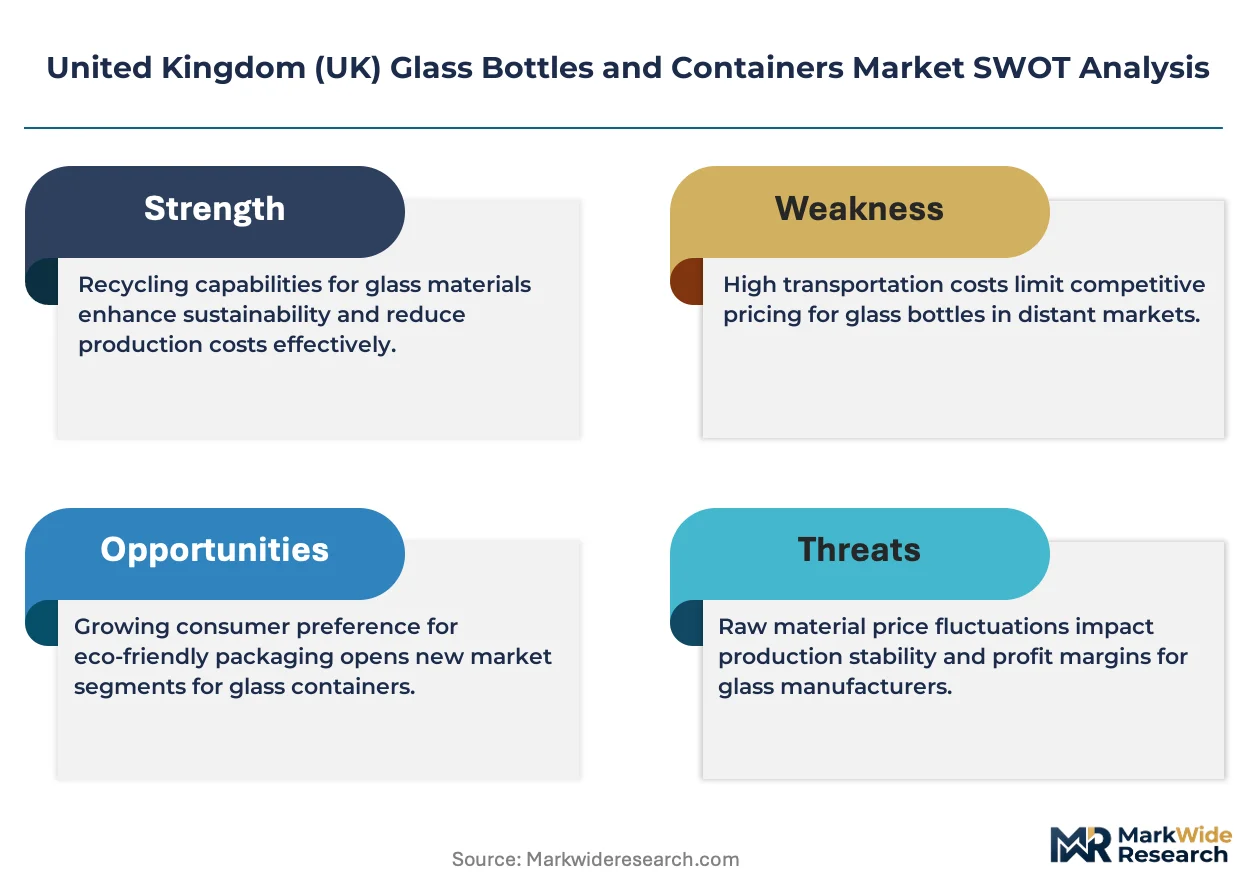
The UK Plastic Packaging Tax and extended producer responsibility regulations are compressing polymer alternatives while concentrating procurement around furnace-efficient suppliers capable of certifying lower-carbon batch formulations.
Growth Catalysts
- DEFRA packaging waste regulations:Mandatory recycling targets and modulated fees based on recyclability are elevating glass above competing substrates in beverage and food applications.
- Premium spirits embossing demand:Scotch whisky and English gin brands are commissioning proprietary mold designs that lock in multi-year supply agreements with specialized blow-mold houses.
- Scottish Highlands production corridor:Proximity between distilleries and container fabricators reduces freight emissions and supports just-in-time filling schedules for aged spirit releases.
Market Restraints
- Natural gas price volatility:Furnace operations depend on methane feedstock for melting silica-soda-lime batches, exposing margin structures to wholesale energy market swings.
- English Midlands supplier concentration:Three furnace operators control the majority of flint and amber glass capacity, creating bottleneck risk during maintenance cycles or batch reformulation periods.
- Aluminum can substitution:Lightweight metal packaging captures share in beer and carbonated soft drinks where transport cost minimization outweighs premium positioning requirements.
Strategic Opportunities
- Northern England craft brewery expansion:Yorkshire and Lancashire micro-distilleries represent unserved demand for short-run custom bottles with regional heritage embossing.
- MHRA amber glass certification gaps:Qualified pharmaceutical packaging suppliers remain scarce for high-volume generic drug contracts requiring dimensional stability within tight tolerances.
- Post-Brexit export certification divergence:UK-specific testing protocols create captive demand from domestic manufacturers previously served by continental molders.
Industry Challenges
- Furnace refractory engineering talent:Specialized knowledge for regenerative burner optimization and crown repair is aging out of the workforce faster than apprenticeship pipelines refill.
- Legacy mold inventory digitization:Decades of hand-cut tooling records resist CAD conversion, delaying rapid prototyping for custom-shaped premium contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom (UK) Glass Bottles and Containers Market |
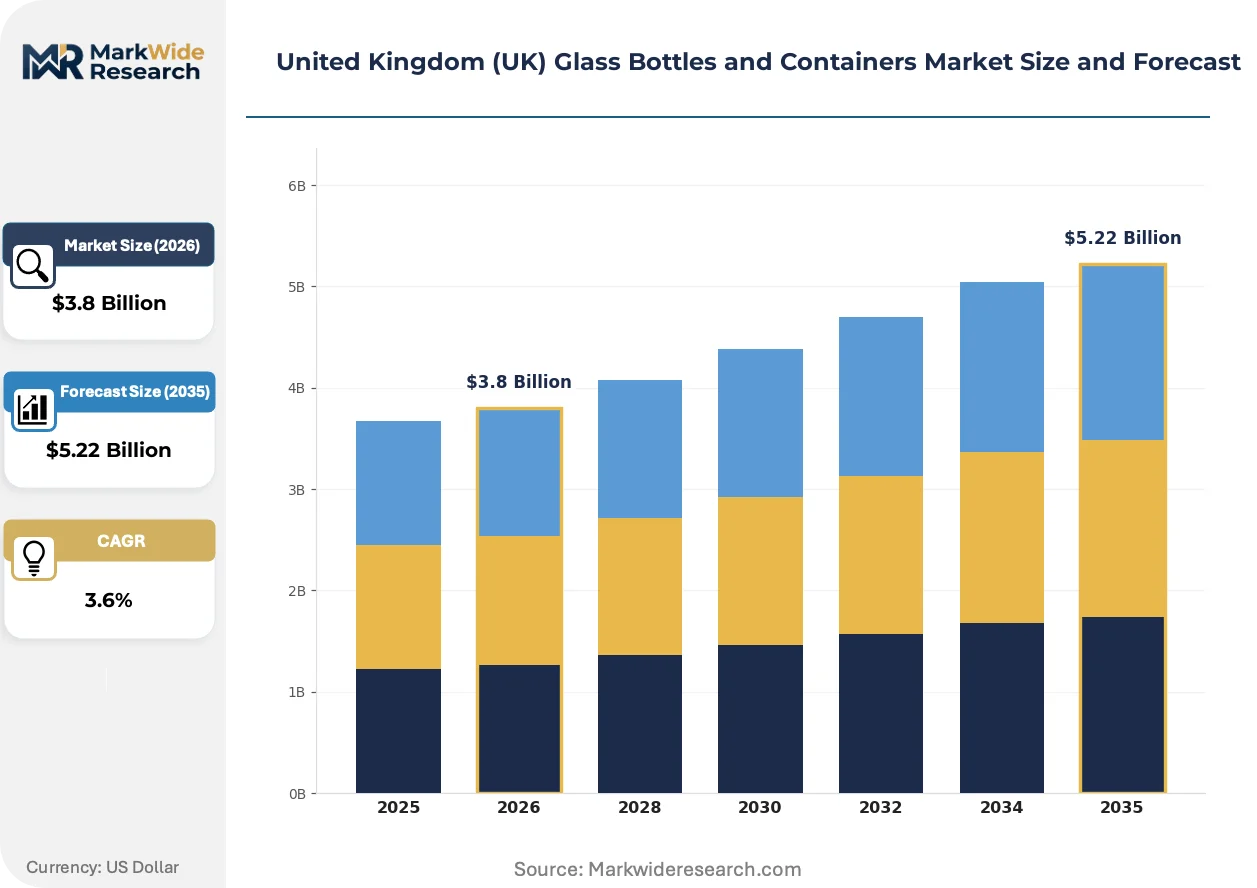
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.22 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals End User: Household, Restaurants, Retail, Industrial Size: Small Bottles, Medium Bottles, Large Bottles, Jars Shape: Cylindrical, Square, Oval, Custom Shapes |
| Companies Covered | Verallia Packaging, Beatson Clark, Ardagh Group, O-I Glass, Encirc, Allied Glass, Ciner Glass, Stoelzle Flaconnage, Gaasch Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom (UK) Glass Bottles and Containers Market Trends and Innovations
Electrification of melting operations and digital mold workflows are compressing lead times while regulatory carbon accounting forces batch chemistry transparency through the supply chain.
Hybrid furnace architectures is hybridizing gas-fired melting with electric boosting systems to reduce scope-one emissions during peak grid renewable generation windows. Premium spirits distillers in Scotland are piloting these configurations for carbon-neutral product lines. The technology is compressing allowable furnace rebuild cycles as operators balance capital replacement against incremental efficiency gains.
DEFRA's extended producer responsibility modulated fee structure is forcing brand owners to document recycled content percentages and end-of-life recovery rates. Glass container fabricators must now certify batch cullet ratios through third-party audit trails. The Pharmaceuticals segment faces the steepest compliance burden as MHRA packaging integrity requirements intersect with waste accountability rules.
Supermarket private-label consolidation has compressed the buyer base from fragmented regional procurement to centralized national tenders with volume-commitment clauses. Major grocery multiples now specify furnace efficiency benchmarks and carbon disclosure thresholds as mandatory bid criteria. The English Midlands manufacturing corridor shows the most visible concentration of this procurement model evolution.
United Kingdom (UK) Glass Bottles and Containers Market Segmentation
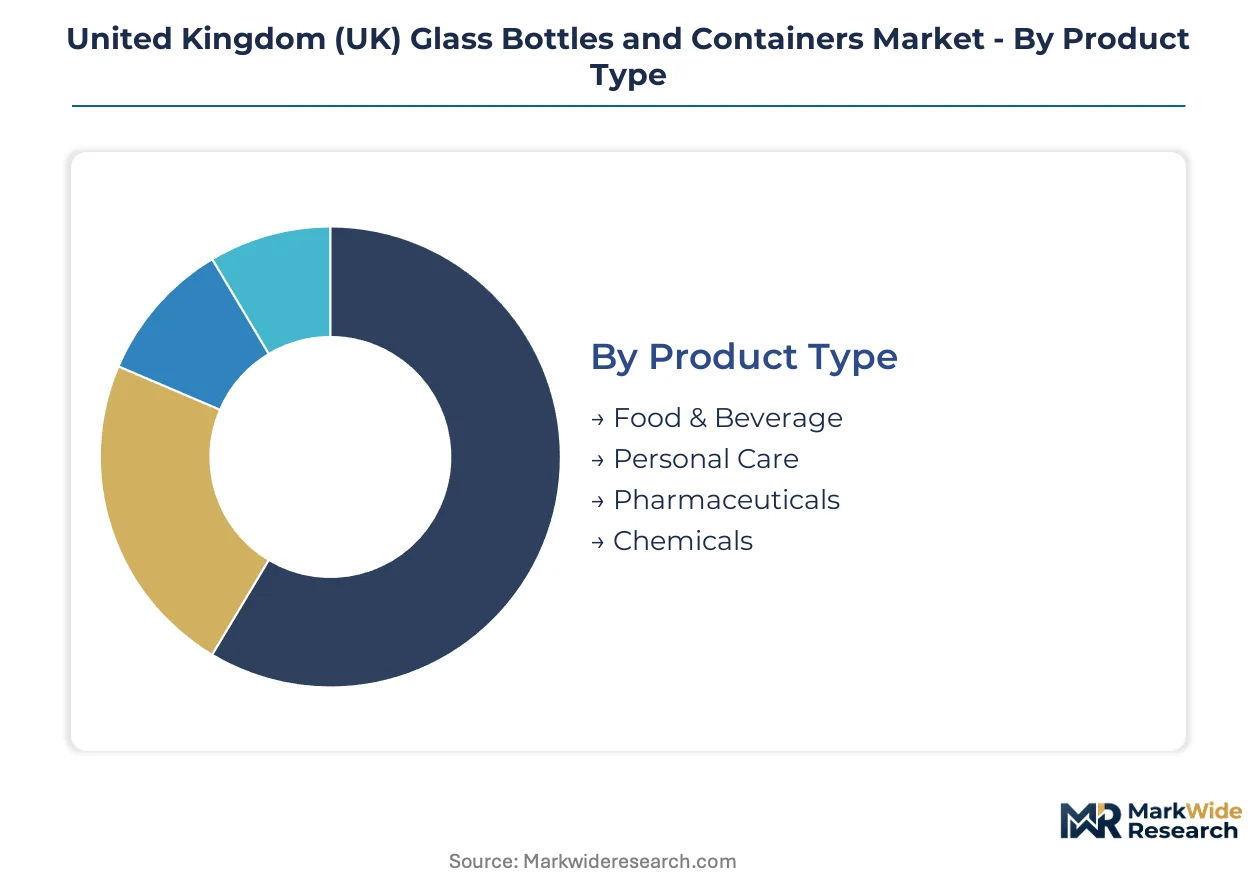
Glass container demand across the United Kingdom fragments across four distinct classification systems. Each dimension reveals how furnace operators, mold houses, and brand owners align capabilities with regulatory requirements and premium positioning strategies.
Product Type:
End-use applications span consumable goods, regulated medical products, and industrial chemicals with radically different compliance burdens and margin structures.
- Food & Beverage:Silica-soda-lime vessels with 70-74% silicon dioxide content provide inert storage for spirits, beer, and preserved foods. English Midlands manufacturers and Scottish Highlands distillers drive demand for custom embossing and proprietary mold designs that lock in multi-year supply agreements.
- Pharmaceuticals:Amber and flint bottles with tight dimensional tolerances serve MHRA-regulated drug packaging. Compliance with packaging integrity guidelines creates defensive margin pools for qualified suppliers, while scarcity of certified molders limits competitive entry.
- Personal Care:Cosmetic and fragrance containers prioritize aesthetic differentiation through colored glass and distinctive silhouettes. Yorkshire and Lancashire formulators source short-run custom bottles with regional heritage embossing.
- Chemicals:Industrial-grade containers withstand corrosive contents through thicker wall specifications and chemical-resistant batch formulations. Laboratory reagent and agricultural chemical distributors specify UN-certified packaging for hazardous material transport.
The dominant share belongs to Food & Beverage, while Pharmaceuticals is closing the gap fastest as MHRA certification requirements deepen supplier scarcity.
End User:
Procurement scale and technical specification intensity vary dramatically across customer categories, from mass-market retail chains to specialized industrial buyers.
- Retail:Supermarket private-label consolidation has compressed procurement to centralized national tenders with furnace efficiency benchmarks and carbon disclosure thresholds as mandatory bid criteria.
- Household:Direct-to-consumer channels and subscription services demand smaller lot sizes with rapid mold changeover capabilities.
- Restaurants:Foodservice operators prioritize standardized formats with reliable supply continuity for condiment and beverage service applications.
- Industrial:Manufacturing integrators specify bulk containers with automated filling line compatibility and palletization efficiency.
Retail commands procurement volume leadership, though Industrial buyers extract the most stringent technical specifications.
Size:
Format dimensions determine furnace batch economics, mold inventory requirements, and freight optimization across the supply chain.
- Medium Bottles:The most contested size tier across multiple end-use applications, balancing production efficiency with handling convenience. Spirits and wine categories concentrate demand here, with premium brands commissioning proprietary designs.
- Small Bottles:Pharmaceutical samples, travel retail spirits, and cosmetic minis require precision molding with tight neck finish tolerances for closure compatibility.
- Large Bottles:Magnum spirits formats and institutional food service containers prioritize structural integrity for stacking and transport.
- Jars:Wide-mouth configurations serve preserved foods and spreads, with vacuum seal compatibility driving finish specification intensity.
Medium Bottles anchor production scheduling, while Small Bottles climb fastest as single-serve and sample formats proliferate.
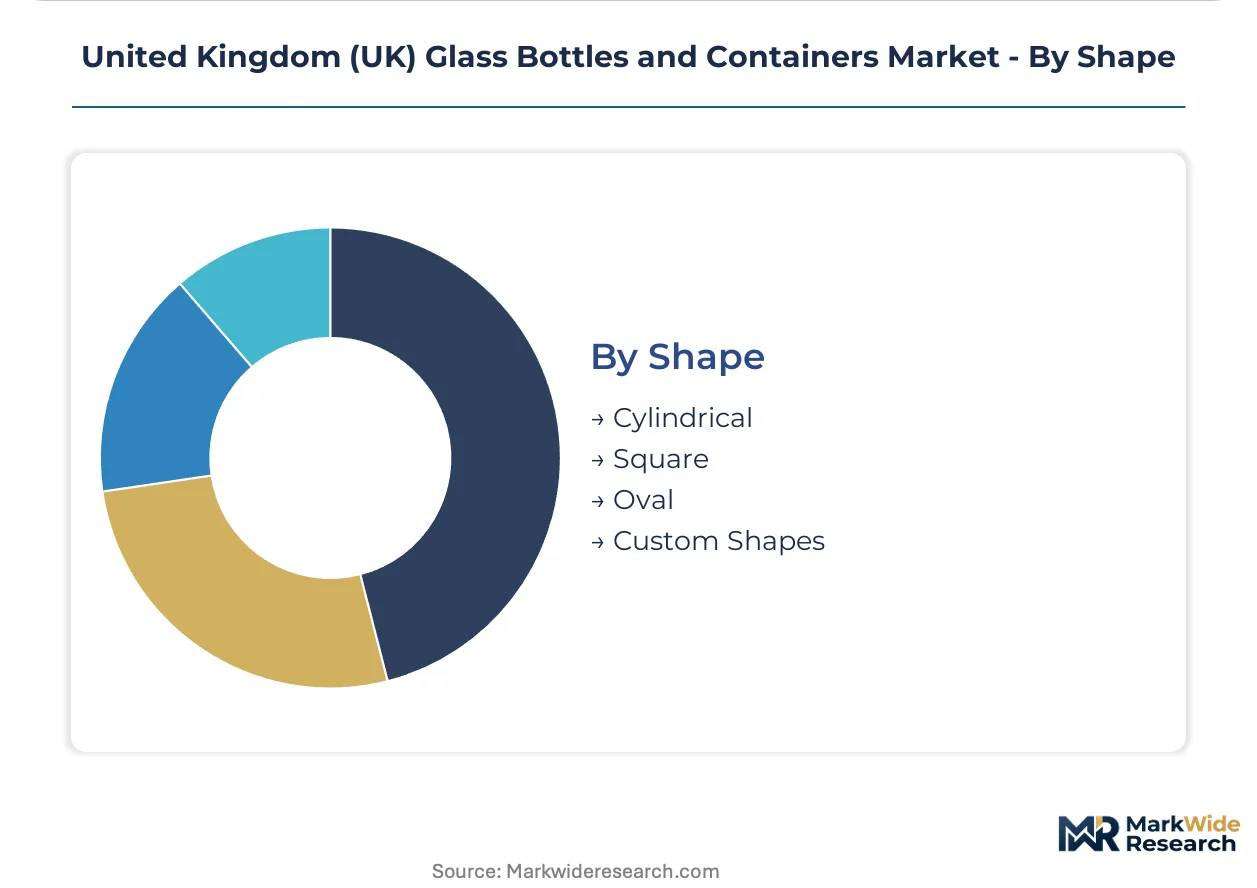
Shape:
Geometric complexity directly correlates with mold cost amortization, production cycle time, and brand differentiation potential.
- Custom Shapes:Proprietary mold designs commissioned by premium spirits brands command higher unit economics and lock in multi-year supply agreements. Scottish whisky and English gin producers drive investment in digital mold workflows to compress prototyping lead times.
- Cylindrical:Standard round profiles maximize production efficiency and label adhesion consistency for high-volume beer and soft drink applications.
- Square:Space-efficient palletization and shelf presence drive adoption in food service and retail condiment segments.
- Oval:Ergonomic handling characteristics suit personal care and specialty food applications where hand-fit matters.
Cylindrical forms dominate throughput tonnage, though Custom Shapes gain share fastest as premium positioning intensifies across spirits categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M6 motorway corridor and associated freight rail links anchor England's glass manufacturing geography, connecting Scottish Highlands distilleries to Midlands furnace capacity and North Sea container ports.
English Midlands
Flint and amber glass furnace concentration here supplies beverage and pharmaceutical demand across the UK. DEFRA's extended producer responsibility regulations force batch chemistry transparency on operators. Birmingham and Stoke-on-Trent host the majority of domestic melting capacity, where three furnace operators control throughput scheduling.
Scottish Highlands
Scotch whisky distilleries commission custom embossing and proprietary mold designs from regional fabricators. The UK Plastic Packaging Tax elevates glass above polymer alternatives for premium spirit exports. Speyside and Islay production clusters maintain just-in-time filling relationships with specialized blow-mold houses.
North England
Yorkshire and Lancashire craft breweries drive short-run demand for heritage-embossed bottles. MHRA pharmaceutical packaging requirements create certification bottlenecks for amber glass suppliers. Sheffield and Leeds formulators source regional molders for generic drug contracts requiring dimensional stability.
Wales
Industrial glass demand from South Wales chemical processors sustains specialized container fabrication. Natural gas price volatility compresses margin structures for furnace-dependent operators. Newport and Cardiff corridors supply UN-certified packaging for hazardous material distributors.
London and Southeast
Premium cosmetics and fragrance brands source aesthetic-differentiated containers through Thames Valley distributors. British Standards Institution thermal shock specifications shape quality certification investments. Greater London procurement offices consolidate national tenders with carbon disclosure thresholds.
United Kingdom (UK) Glass Bottles and Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with mold engineering and batch chemistry expertise. The UK market consolidates around furnace-efficient operators capable of certifying lower-carbon formulations. Three archetypes dominate: multinational container platforms with brewery relationships, regional specialists in pharmaceutical amber glass, and private-label suppliers anchored to grocery multiples. Competitive moves concentrate on strategic partnerships for renewable energy sourcing and selective capacity expansion at regenerative burner facilities.
Among UK-based fabricators, Encirc and Beatson Clark exemplify divergent specialization paths. Encirc occupies a position within the furnace-efficiency tier, leveraging scale advantages for supermarket private-label contracts. Beatson Clark represents the pharmaceutical-specialist archetype, where MHRA certification requirements sustain defensive margin pools. Ardagh Group anchors the multinational platform category, with long-standing brewery relationships spanning beer and cider categories. These three collectively illustrate how regulatory compliance and procurement consolidation reshape competitive positioning.
| Leading Market Players |
|---|
| Verallia Packaging |
| Beatson Clark |
| Ardagh Group |
| O-I Glass |
| Encirc |
| Allied Glass |
| Ciner Glass |
| Stoelzle Flaconnage |
| Gaasch Packaging |
| Others |
Pricing and Supply Chain Analysis
English Midlands furnace utilization rates averaging 85-90% anchor supplier pricing power, compressing procurement leverage for buyers while rewarding furnace-efficient operators with volume-commitment premiums from grocery multiples.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates UK glass container procurement, with premium tiers capturing custom-embossed spirits contracts and economy tiers serving standardized beer formats. Price differentiation hinges on carbon disclosure certification and MHRA pharmaceutical compliance grade, with DEFRA's extended producer responsibility modulated fees adding compliance cost layers. Cost compression in flint glass is intensifying because natural gas price volatility feeds directly into batch melting economics. Supermarket private-label buyers exhibit highest price sensitivity, while premium spirits brands demonstrate lowest sensitivity due to packaging's brand-equity contribution.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supermarket private-label procurement, straining working capital for smaller mold houses while favoring furnace-consolidated platforms with balance-sheet depth. Geographic supply concentration rests on England, Scotland, and Ireland, with English Midlands furnaces supplying flint and amber capacity and Scottish Highlands fabricators serving distillery clusters. Raw material dependencies center on silica sand from Lochaline, soda ash from natural deposits, and limestone fluxes from Derbyshire quarries. Single-source vulnerability concentrates in regenerative burner engineering talent for furnace rebuilds. Distribution runs through M6 motorway corridors connecting Midlands capacity to North Sea ports and Scottish distillery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK glass container market sits at a platform-economics inflection where DEFRA's carbon accounting interoperability forces batch chemistry transparency through tiered supplier certification ecosystems.
For Market Incumbents: Entrench furnace efficiency advantages through regenerative burner optimization and captive cullet recycling streams, defending against aluminum can substitution in beer categories by locking brewery relationships into multi-year carbon-neutral product line contracts. For New Entrants and Emerging Players: Pursue MHRA-certified amber glass capacity gaps in North England pharmaceutical corridors, targeting Sheffield and Leeds generic drug formulators with dimensional stability guarantees and rapid mold prototyping capabilities unavailable from incumbent suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-specialist molders with MHRA certification moats, suggesting long-term viability through regulatory compliance deepening rather than commodity volume exposure; watch for furnace electrification pilot announcements as inflection signals for carbon-cost positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Pilot | Hybrid gas-electric melting reduces scope-one emissions for DEFRA compliance and spirits brand carbon-neutral claims. |
| MHRA Certification Investment | Amber glass dimensional stability qualification opens generic drug contract pipelines from Leeds formulators. |
| Cullet Recycling Integration | Backward integration into post-consumer glass recovery secures batch chemistry transparency for EPR modulated fees. |
| Digital Mold Workflow Deployment | CAD-converted tooling archives compress prototyping lead times for premium spirits custom embossing contracts. |
| Scottish Highlands Capacity Expansion | Speyside proximity reduces freight emissions for just-in-time whisky filling schedules and export logistics. |
Research Methodology
Cross-validation between trade association furnace capacity data and DEFRA packaging waste registry filings anchors the qualitative findings, combining primary interviews with plant engineers, grocery multiple procurement directors, pharmaceutical packaging compliance officers, and distillery supply chain managers with secondary validation from British Glass Federation statistics, MHRA guidance documents, and customs export records. Bottom-up segmentation modeling triangulates against top-down macro demand indicators.
Calibration against historical furnace throughput and batch chemistry disclosure trends shapes the projection framework across product type, end user, size tier, and shape complexity dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating natural gas price scenarios and EPR fee schedule implementations. Forecast inputs include spirits export volume trajectories and pharmaceutical generic drug approval pipelines.
Macroeconomic conditions sit as an overlay; deviation in wholesale energy prices, sterling exchange rates, or Brexit-aligned regulatory divergence would shift the trajectory. Forecasts reflect documented assumptions about furnace rebuild cycles and carbon accounting protocol adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Glass Growlers Market