
 APAC Alcoholic Drinks Packaging Market | 2026-2036
APAC Alcoholic Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Alcoholic Drinks Packaging Market Outlook
Aftermarket service revenue for packaging line maintenance and retrofit is reshaping margin distribution across the value chain. Amcor Group GmbH leverages its regional film and flexible packaging footprint to serve high-volume beer producers. Gerresheimer AG anchors premium spirits glass supply through specialized molding capabilities in Southeast Asian facilities. Ball Corporation dominates aluminum can output for the Asia-Pacific beverage sector with continuous casting investments.
APAC Alcoholic Drinks Packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, withstand carbonation pressures, and comply with food-contact migration limits. Glass bottles for wine and spirits typically feature borosilicate or soda-lime compositions with wall thickness calibrated for impact resistance during regional distribution. Aluminum cans for beer capture expanding share as breweries prioritize lightweighting and chill-performance. Pouches remain nascent but attract craft cider producers seeking differentiation in urban retail.
China's SAMR enforces GB standards for food-contact materials that dictate allowable substances in recycled glass and aluminum. India's FSSAI mandates label integrity and tamper-evidence for alcoholic beverages sold through licensed retail channels. Japan's METI oversees container recycling laws that shape producer responsibility obligations. Stakeholders must monitor how extended producer responsibility frameworks evolve across jurisdictions to anticipate capital allocation for circular infrastructure.
Market Dynamics
Premium spirits brands across Southeast Asia are compressing glass weight specifications while China's SAMR tightens migration limits for recycled content, forcing converters to revalidate material streams.
Growth Catalysts
- Lightweighting mandates:Thai and Vietnamese distillers now specify sub-400g bottles for 750ml spirits, reducing freight costs per case.
- Extended Producer Responsibility:Japan's METI container recycling laws are expanding deposit-return coverage to include aluminum cans for RTD cocktails.
- Urban retail corridor expansion:Licensed alcohol retail in Mumbai, Delhi, and Bangalore is consolidating into high-throughput format stores requiring shelf-ready secondary packaging.
Market Restraints
- Soda-lime silica cost volatility:Float glass feedstock prices fluctuate with natural gas benchmarks, squeezing margin on standard wine bottles.
- Single-source mold fabrication:Precision blow molds for premium spirits neck finishes concentrate with Italian and German toolmakers, creating 14-16 week lead times.
- Recycled aluminum purity thresholds:China's GB standards for food-contact aluminum exclude post-consumer scrap above 0.15% iron contamination, limiting domestic circular supply.
Strategic Opportunities
- Craft cider pouch formats:Australian and New Zealand producers are testing spouted flexible pouches for 330ml single-serve chilled distribution.
- Digital printing on aluminum:Variable-data can decoration enables batch-level traceability for export beer entering Japan's METI-tracked recycling system.
- Secondary packaging automation:Indian beverage companies are retrofitting lines for shrink-wrapped multi-packs to serve modern trade expansion in Tier-2 cities.
Industry Challenges
- Colorant chemistry reformulation:Chrome-based green glass colorants face substitution pressure under China's MEE environmental discharge rules, requiring furnace requalification.
- Legacy line integration:Southeast Asian breweries running 1990s-era canning equipment struggle to accommodate lighter 202-end aluminum specifications without starwheel replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Alcoholic Drinks Packaging Market |
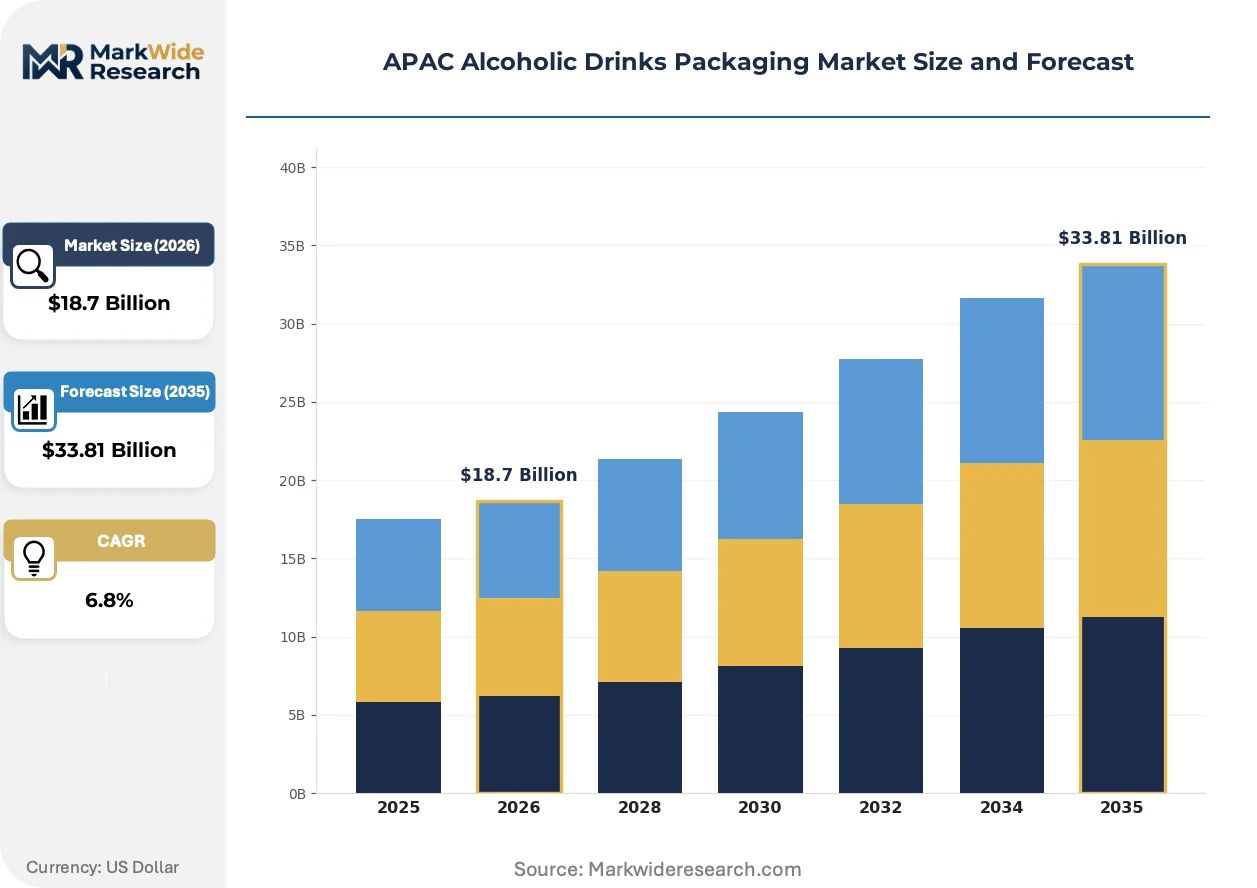
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Paper Product Type: Beer, Wine, Spirits, Cider End User: Retailers, Distributors, Restaurants, Bars |
| Companies Covered | AGI Glaspac, Mondi Group, Hualian Glass Bottle, Berry Global Inc., Gerresheimer AG, Ball Corporation, Amcor Group GmbH, Owens-Illinois Inc., Crown Holdings Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Alcoholic Drinks Packaging Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine acceptable performance thresholds for primary containment across beer, wine, and spirits categories.
Ultralight glass technology is migrating from niche champagne applications to mainstream still wine in Australia and New Zealand. Brown-Forman and Pernod Ricard affiliates in Singapore and Thailand now specify 285g borosilicate-equivalent bottles for premium whiskey exports. This weight reduction is compressing per-unit shipping costs without sacrificing impact resistance during containerized ocean freight.
China's SAMR is enforcing amended GB 4806 food-contact material standards that lower allowable heavy metal migration from decorated glass and ceramic surfaces. Testing laboratories in Shanghai and Guangzhou report 40% failure rates on legacy lead-crystal decanter submissions. Distillers are responding by accelerating laser-etch decoration adoption to replace fired ceramic inks.
Direct-to-retailer procurement consolidation is reshaping how packaging converters quote annual contracts. Major Australian supermarket chains now negotiate consolidated beverage packaging tenders spanning beer, wine, and spirits rather than category-siloed agreements. This pattern concentrates volume with suppliers offering cross-format capability, disadvantaging single-material specialists in Melbourne and Sydney procurement cycles.
APAC Alcoholic Drinks Packaging Market Segmentation
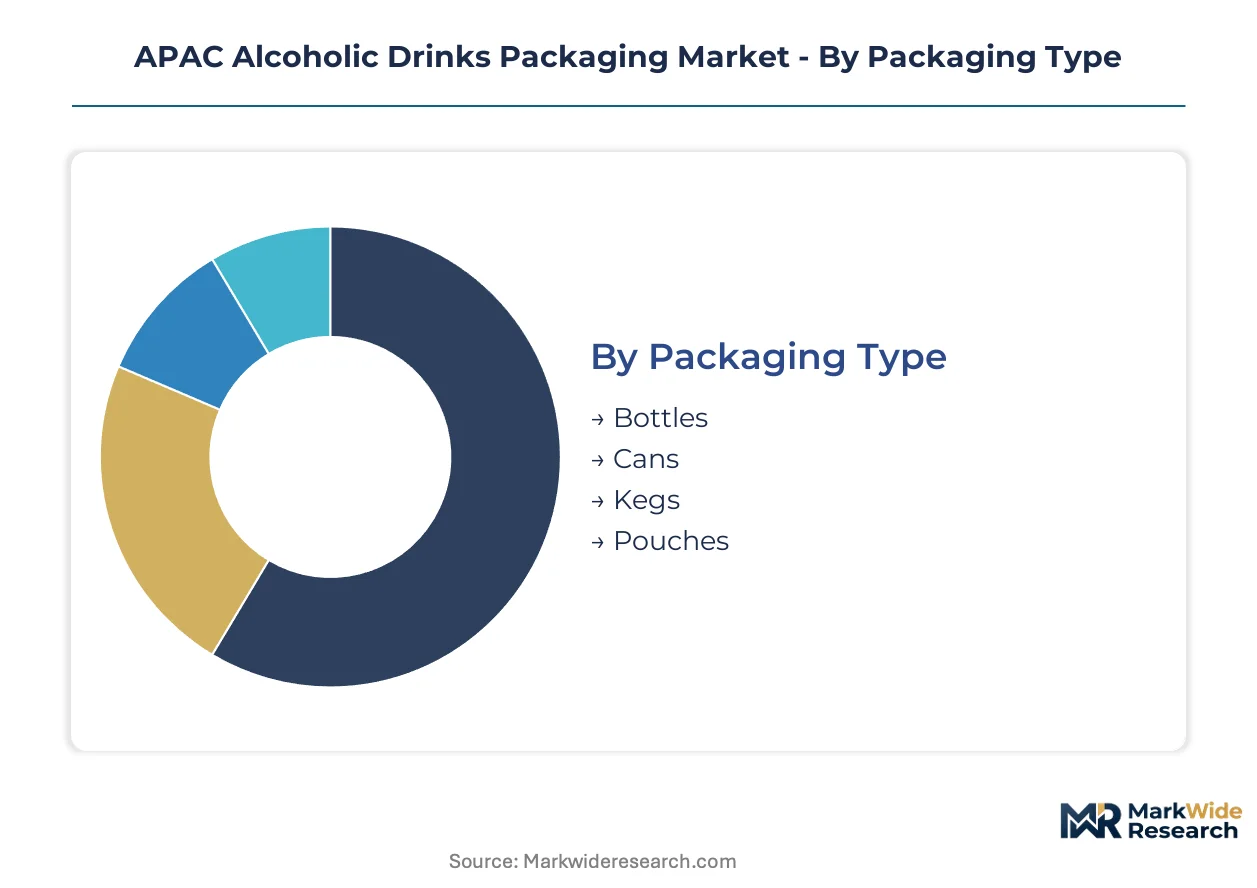
Packaging format selection in APAC alcoholic beverages hinges on carbonation tolerance, thermal stability during distribution, and compliance with national food-contact migration limits. Distinct performance requirements across beer, wine, and spirits categories create divergent material specifications and procurement patterns.
Packaging Type:
Mature formats dominate volume throughput while emerging configurations test niche positioning in urban retail corridors.
- Bottles:Soda-lime and borosilicate glass compositions calibrated for 0.5-4mm wall thickness withstand internal pressures up to 6 bar in sparkling wine applications. Brown-Forman and Pernod Ricard affiliates across Thailand and Vietnam specify sub-400g lightweight variants for 750ml spirits to compress ocean freight costs per case.
- Cans:Two-piece aluminum drawn-and-ironed construction with 202-end diameter specifications enables 330ml and 500ml standard formats. Ball Corporation's continuous casting investments across the region supply breweries prioritizing chill-performance and lightweighting mandates.
- Kegs:Stainless steel 30L and 50L returnable systems serve on-premise draft distribution in Australian and Japanese metropolitan markets.
- Pouches:Spouted flexible laminates with ethylene vinyl alcohol barriers attract craft cider producers in New Zealand seeking shelf differentiation in convenience retail.
Bottles handle the majority of throughput; pouches are expanding most quickly on share.
Material:
Cost tier stratification separates premium-positioned substrates from commodity alternatives in procurement cycles.
- Glass:Float furnace production of soda-lime silica with chrome-based or iron-based colorants dominates wine and spirits containment. China's MEE environmental discharge rules are forcing substitution away from legacy chrome chemistry, requiring furnace requalification at Guangdong and Shandong facilities.
- Aluminum:Continuous cast coil stock with 3104-H19 alloy specification delivers 0.28mm body wall thickness for beverage can bodies. China's GB standards exclude post-consumer scrap above 0.15% iron contamination, constraining domestic circular supply development.
- Plastic:Polyethylene terephthalate barrier bottles for RTD cocktails and alcopops concentrate in Japanese and South Korean convenience channels.
- Paper:Liquid packaging board with polyethylene extrusion layers serves limited bag-in-box wine formats in Australian retail.
Glass commands the premium tier on price; aluminum captures volume scale across beer applications.
Product Type:
Application-driven performance requirements dictate material selection and secondary packaging automation levels.
- Beer:Aluminum can and glass bottle formats with crown cork or aluminum roll-on closure specifications predominate. Southeast Asian breweries retrofit 1990s-era canning lines to accommodate lighter 202-end specifications without starwheel replacement.
- Wine:750ml Bordeaux and Burgundy bottle shapes with punt depth calibrated for sediment settling serve export and domestic markets. Ultralight 285g borosilicate-equivalent technology migrates from champagne to still wine in Australia and New Zealand.
- Spirits:Premium whiskey and vodka brands specify heavy-base flint glass with laser-etch decoration replacing fired ceramic inks under China's amended GB 4806 standards.
- Cider:Craft producers test alternative formats including aluminum cans and flexible pouches for single-serve chilled distribution in urban Australian retail.
Beer generates the highest packaging unit volume; spirits commands the steepest expansion trajectory on value.
End User:
Customer type determines order configuration, secondary packaging requirements, and service level agreements.
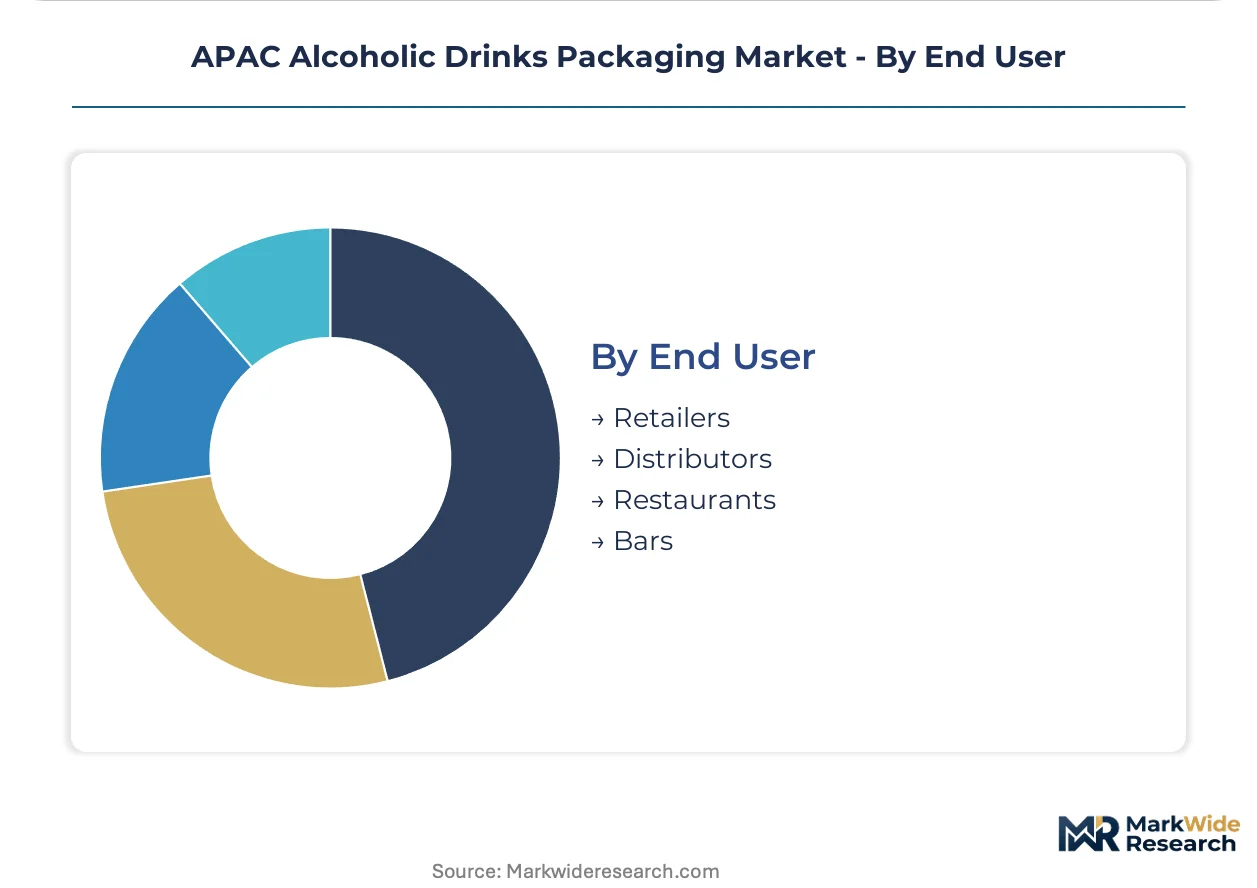
- Retailers:Licensed alcohol retail in Mumbai, Delhi, and Bangalore consolidates into high-throughput format stores requiring shelf-ready shrink-wrapped multi-packs and palletized distribution.
- Distributors:Regional beverage wholesalers manage mixed-format inventory with variable batch sizes and traceability documentation for Japan's METI-tracked recycling system.
- Restaurants:On-premise dining establishments in Singapore and Bangkok specify premium glass presentation formats with customized decoration for table-service positioning.
- Bars:Nightlife venues in Seoul and Sydney prioritize keg draft systems and aluminum can efficiency for high-velocity service environments.
Retailers drive standardization pressure; bars generate the fastest format experimentation cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across APAC alcoholic drinks packaging markets. Indian metropolitan buyers exhibit acute price sensitivity on standard beer bottles, while Japanese premium spirits purchasers absorb double-digit packaging premiums for aesthetic differentiation.
China
Lightweight glass adoption accelerates among Baijiu exporters targeting duty-free channels. SAMR's amended GB 4806 standards enforce stricter heavy metal migration limits, disqualifying legacy lead-crystal decoration. Guangdong province hosts furnace requalification programs as converters substitute iron-based colorants for chrome chemistry under MEE discharge rules.
India
Licensed retail consolidation in Mumbai, Delhi, and Bangalore drives shelf-ready secondary packaging specifications. FSSAI mandates tamper-evidence and label integrity for alcoholic beverages sold through authorized channels. Maharashtra's Nashik wine belt attracts ultralight borosilicate-equivalent bottle trials for export-oriented producers.
Japan
Premium whiskey presentation formats command substantial packaging premiums in domestic and export markets. METI container recycling laws expand deposit-return coverage to aluminum cans for RTD cocktails. Tokyo-Osaka corridor distributors invest in traceability documentation systems for METI-tracked recycling compliance.
Vietnam
Thai and Vietnamese distillers specify sub-400g glass bottles for 750ml spirits to compress ocean freight costs. The country's national standards body aligns food-contact material rules with ASEAN harmonization frameworks. Ho Chi Minh City packaging converters retrofit lines for lighter 202-end aluminum specifications.
Australia
Craft cider producers test spouted flexible pouches for 330ml single-serve chilled distribution. TGA-equivalent state-level food-contact oversight governs barrier material approvals for alcoholic beverages. Melbourne and Sydney procurement cycles consolidate cross-format beverage packaging tenders spanning beer, wine, and spirits categories.
APAC Alcoholic Drinks Packaging Market Competitive Environment
Capability concentration sits with specialized glass molders and aluminum continuous casters; scale advantage sits with diversified flexible packaging networks. The market structures around three tiers: integrated multinationals with regional furnace or casting investments, mid-cap specialists commanding precision blow-mold fabrication, and flexible packaging converters serving high-volume beer producers. Dominant competitive moves include line retrofit partnerships for legacy equipment accommodation and secondary packaging automation upgrades for modern trade expansion.
Among Germany-based precision specialists, Gerresheimer AG occupies a position exemplifying premium spirits glass supply through specialized molding capabilities. Ball Corporation represents the scale-driven aluminum can fabrication archetype with continuous casting investments across the region. Amcor Group GmbH anchors the flexible packaging tier, leveraging regional film footprint to serve high-volume beer producers. These three entities collectively illustrate the capability-scale spectrum defining competitive positioning in APAC alcoholic drinks packaging.
| Leading Market Players |
|---|
| AGI Glaspac |
| Mondi Group |
| Hualian Glass Bottle |
| Berry Global Inc. |
| Gerresheimer AG |
| Ball Corporation |
| Amcor Group GmbH |
| Owens-Illinois Inc. |
| Crown Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source mold fabrication dependency for premium spirits neck finishes concentrates pricing power with Italian and German toolmakers, compressing margins for Southeast Asian converters while simultaneously forcing supply chain reconfiguration toward extended payment term negotiations with secondary equipment vendors.
Pricing Analysis
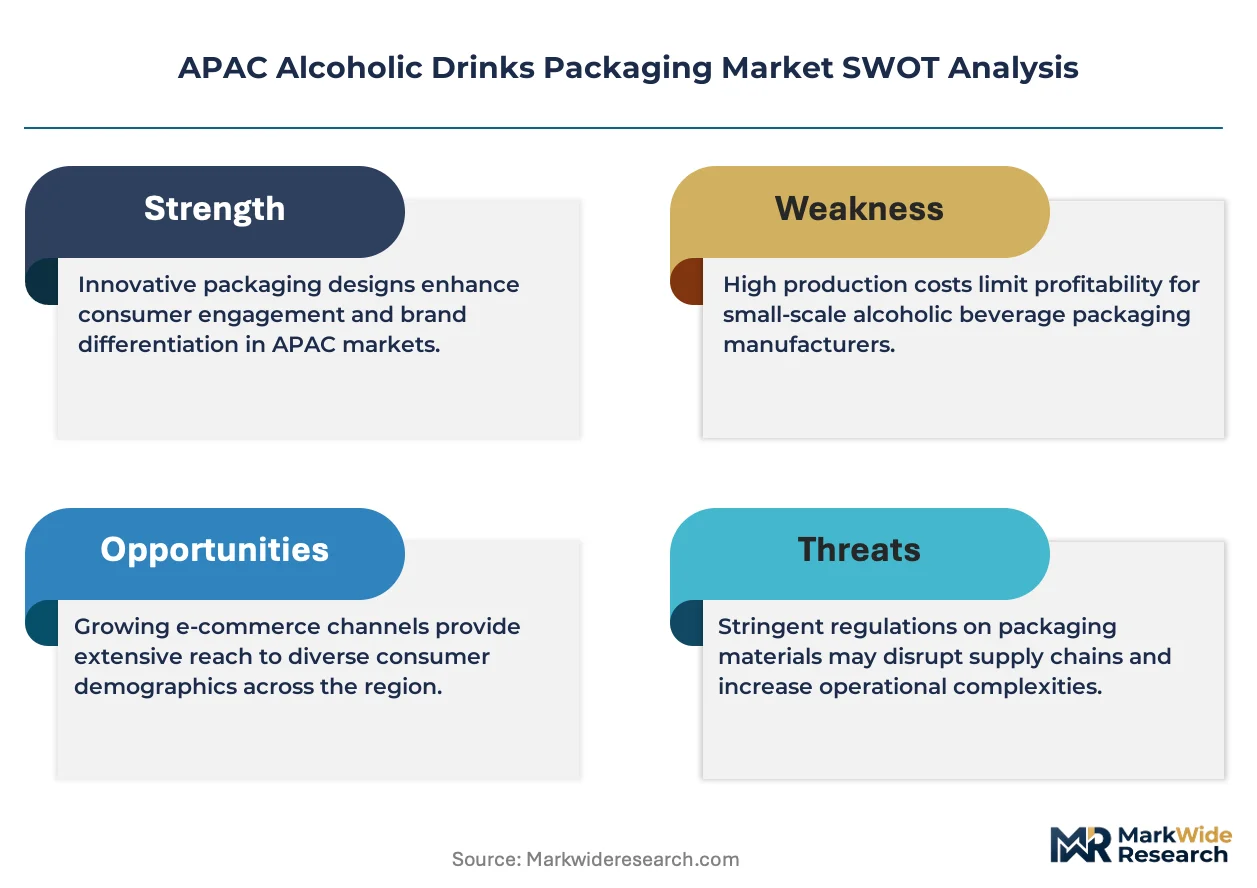
Aftermarket service revenue for packaging line maintenance and retrofit drives lifetime value across converter relationships. Three-tier pricing structure across premium, standard, and economy levels separates laser-etched decoration from fired ceramic inks from unadorned flint glass. Pricing pressure stems from soda-lime silica cost volatility tracking natural gas benchmarks. Indian metropolitan retailers exhibit acute price sensitivity on standard beer bottles; Japanese premium spirits purchasers absorb substantial packaging premiums for aesthetic differentiation.
Supply Chain Analysis
Supplier-financing facilities through extended payment terms anchor working capital management for Vietnamese and Thai distillers sourcing sub-400g lightweight bottles. Manufacturing concentrates in China, Vietnam, and India. Raw material streams draw from soda-lime silica float furnaces, continuous cast aluminum coil, and borosilicate glass feedstock. Single-source vulnerability sits with precision blow-mold tooling. Distribution runs through licensed retail consolidation in Mumbai, Delhi, and Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum can substitution for glass bottles in beer applications threatens incumbent glass converters, requiring active defense through lightweighting technology leadership and secondary packaging automation integration.
For Market Incumbents: Harden furnace requalification capabilities to accommodate iron-based colorant substitution under China's MEE discharge rules. Deepen backward integration into precision mold fabrication to bypass 14-16 week lead times from Italian and German toolmakers. Secure shelf-ready secondary packaging automation contracts with Indian modern trade expansion.
For New Entrants and Emerging Players: Build out spouted flexible pouch production lines targeting craft cider producers in Australian and New Zealand urban retail corridors. Penetrate the RTD cocktail aluminum can segment where Japan's METI deposit-return expansion creates format switching incentives. Lead with digital printing capabilities enabling batch-level traceability for export beer.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified cross-format capability over single-material specialization. Five-to-ten year viability hinges on circular infrastructure ownership and extended producer responsibility compliance systems. Target converters with regional furnace investments and SAMR pre-qualification status. Monitor China's GB 4806 enforcement intensity as inflection indicator for decoration technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Glass Technology Migration | Ultralight 285g borosilicate-equivalent bottles compress freight costs for Brown-Forman and Pernod Ricard exports. |
| Secondary Packaging Automation | Shrink-wrapped multi-pack line retrofits serve Indian Tier-2 city modern trade expansion requirements. |
| Laser-Etch Decoration Adoption | Fired ceramic ink replacement satisfies China's SAMR amended GB 4806 heavy metal migration limits. |
| Continuous Casting Investment | Ball Corporation's regional aluminum coil capacity anchors chill-performance can supply for APAC breweries. |
| Flexible Pouch Format Testing | Spouted 330ml single-serve configurations differentiate craft cider in Australian convenience retail channels. |
Study Parameters
Operator-level perspectives from packaging line engineers, procurement leads at Thai and Vietnamese distillers, furnace operations managers in Guangdong, and modern trade category buyers in Mumbai anchored the qualitative base. Primary interviews combined with secondary validation from SAMR GB standard filings, FSSAI label integrity mandates, METI container recycling law updates, and customs trade data for soda-lime silica and aluminum coil imports. Bottom-up unit economics triangulated against top-down category spend estimates.
Scenario-bracketing framed analytical development across the projection horizon. Segmentation dimensions modeled include packaging format, material substrate, product category, and end-user channel. CAGRs derived from volume trajectory analysis weighted by regional pricing tier composition. Forecast inputs incorporated lightweighting specification adoption curves and deposit-return system expansion timelines.
Sensitivities concentrate around regulatory enforcement intensity, natural gas benchmark volatility, and mold fabrication lead time extensions. Forecasts reflect documented assumptions on material substitution velocity and retail format consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market