
 GCC Flexible Packaging Market | 2026-2036
GCC Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Flexible Packaging Market Intelligence
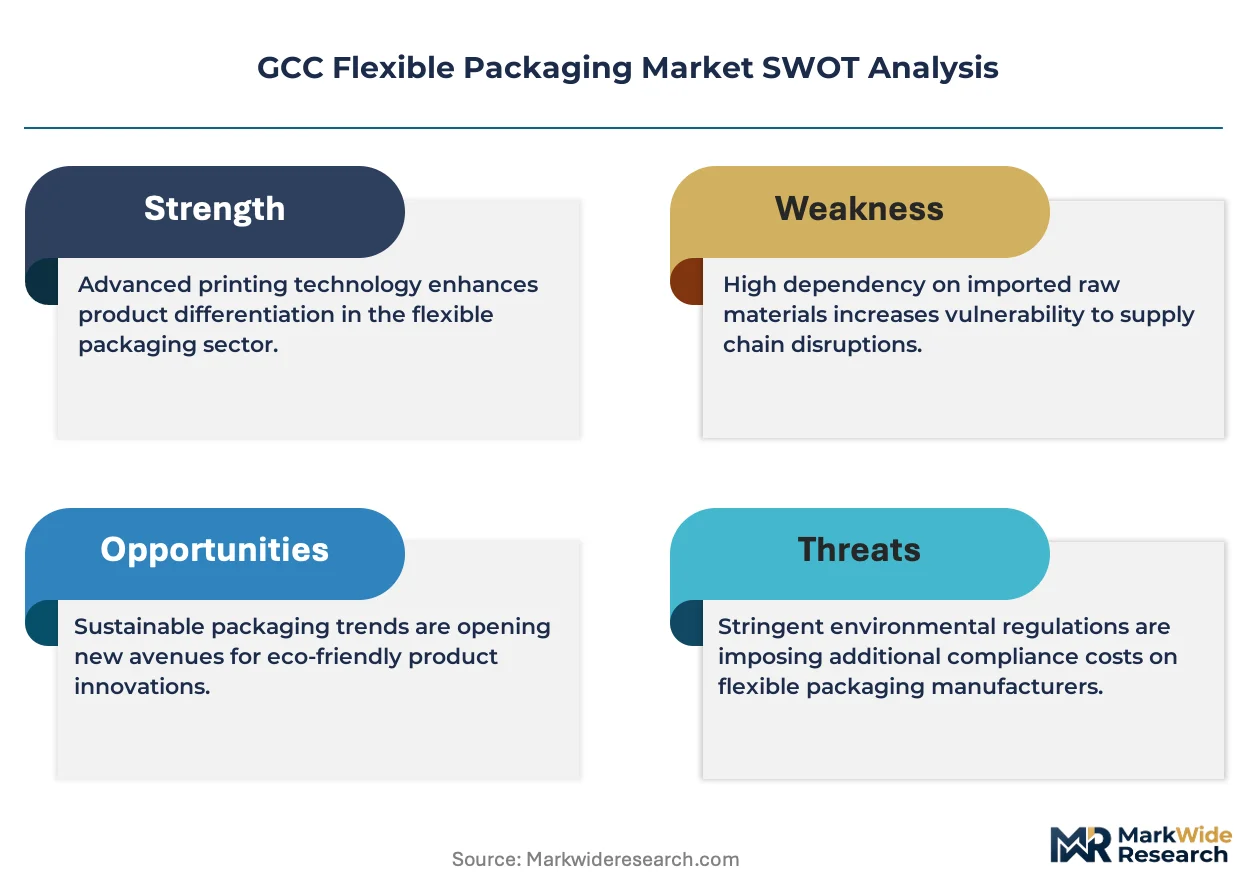
Gulf Standardization Organization (GSO) certification for food-contact materials is redrawing supplier eligibility across the GCC. Huhtamaki leverages its European technical heritage to sustain multi-layer barrier film production from regional hubs. Rotopak anchors domestic supply chains with extensive pouch converting capacity in Saudi Arabia. Amber Packaging Industries differentiates through specialized pharmaceutical-grade cleanroom operations serving Gulf health ministries.
Flexible packaging denotes pliable material structures—typically multi-ply laminates of polyethylene, polypropylene, or aluminum foil between 50-200 microns total caliper—engineered to protect contents from moisture, oxygen, and light while accommodating formed, filled, and sealed distribution formats. Stand-up pouches command premium positioning in beverage and liquid food segments where shelf differentiation and dispensing convenience determine retail placement. Biodegradable material development remains nascent but attracts pilot investments from sustainability-focused FMCG procurement teams seeking alternatives to conventional plastic composites.
SASO enforces migration limits and heavy-metal thresholds for food-contact plastics in Saudi Arabia, while the UAE's Ministry of Industry and Advanced Technology aligns with GSO harmonized standards for cross-border trade facilitation. Compliance with these frameworks determines market access for imported films and locally converted packaging. Stakeholders must monitor evolving extended producer responsibility proposals and bio-based content mandates that Gulf regulators are evaluating for future phased implementation.
Market Dynamics
Multi-layer barrier film specifications from Saudi Arabia's SASO and the UAE's MOHAP are compressing supplier margins while forcing capital redeployment into compliance infrastructure across Jeddah and Dubai Industrial City.
Growth Catalysts
- Ready-to-eat food pouch formats:Saudi and UAE food manufacturers are converting rigid containers to flexible stand-up pouches for ambient and chilled distribution. This shift pulls film demand toward high-barrier laminates with extended shelf-life performance.
- GSO harmonized standards:The Gulf Standardization Organization's unified certification for food-contact materials eliminates redundant testing across Saudi Arabia, UAE, Kuwait, and Qatar. Cross-border trade friction drops for compliant suppliers.
- Pharmaceutical cold-chain expansion:Gulf health ministries are building temperature-controlled distribution networks for biologics and vaccines. Specialized cleanroom flexible packaging with validated barrier properties captures this demand.
Market Restraints
- Ethylene and propylene feedstock volatility:Polyethylene and polypropylene resin prices track naphtha and natural gas liquids from regional petrochemical complexes. Input cost swings compress converter margins without passthrough mechanisms.
- Aluminum foil supply concentration:High-purity foil for multi-layer barrier structures sources predominantly from European and Asian rolling mills. GCC-based converters face extended lead times and currency exposure.
- SASO migration testing timelines:Saudi technical regulations require extended laboratory validation for new film formulations. Product launch cycles stretch by four to six months versus non-regulated markets.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets lack domestic flexible packaging conversion capacity. Exporters from Saudi Arabia's Jeddah corridor and UAE's Dubai Industrial City capture share through established GSO certification.
- Extended producer responsibility pilots:Gulf regulators are evaluating post-consumer film collection and recycling mandates. Early compliance investments position suppliers for preferred procurement status under future frameworks.
- Digital printing convergence with barrier films:HP Indigo and EFI technologies enable short-run, variable-data pouch production. FMCG brands in the UAE deploy this for seasonal and promotional SKUs without plate costs.
Industry Challenges
- Multi-layer film recycling infrastructure:Current mechanical recycling processes cannot separate polyethylene, polypropylene, and aluminum foil laminates. GCC waste management systems lack the specialized equipment for post-industrial scrap recovery.
- Cleanroom certification maintenance:Pharmaceutical-grade flexible packaging requires ISO 14644 compliance with annual revalidation. Facility upgrades and auditor retention consume operational bandwidth for mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Flexible Packaging Market |
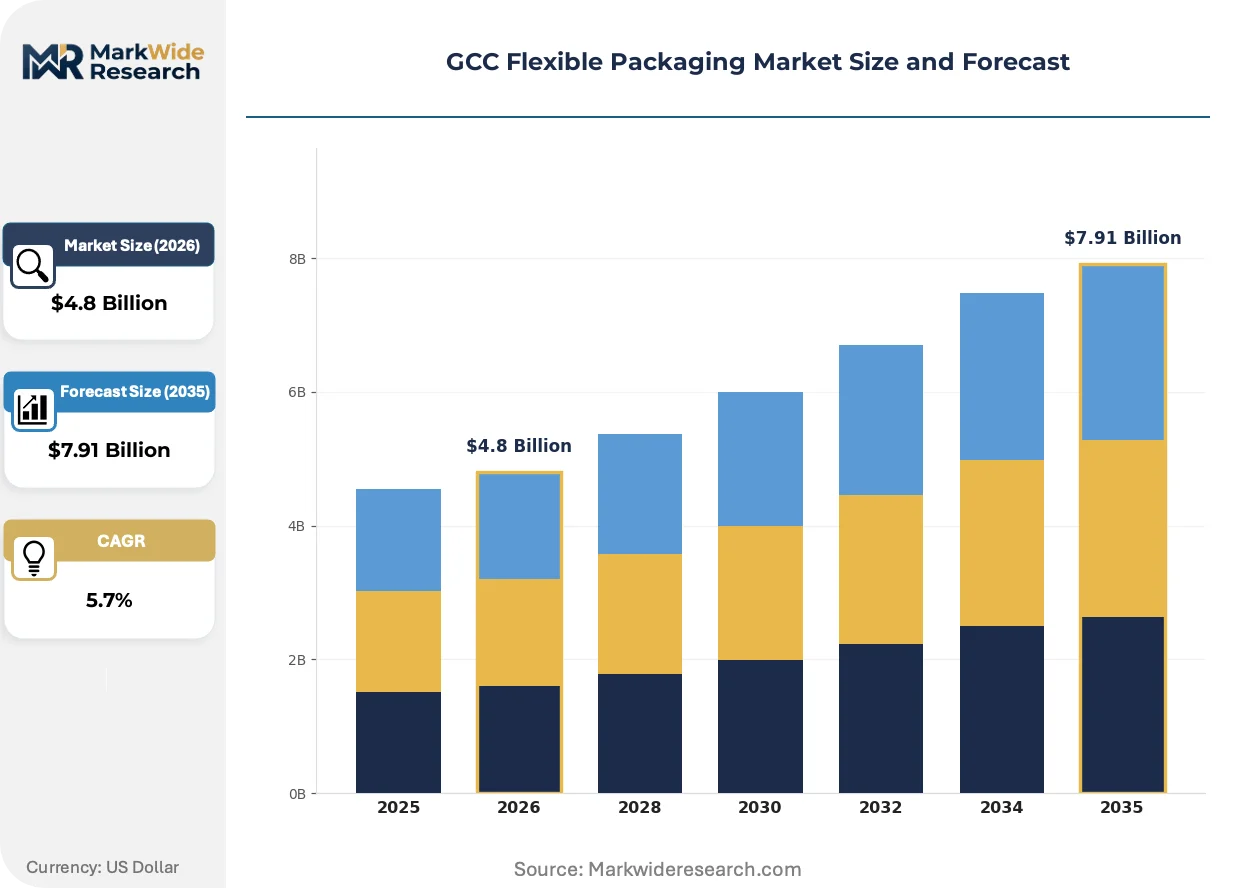
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Lay-Flat Pouches, Bags, Films Material: Polyethylene, Polypropylene, Biodegradable, Plastic Composites End User: Food, Beverage, Pharmaceuticals, Cosmetics Technology: Rotogravure, Flexography, Digital Printing, Lamination |
| Companies Covered | Huhtamaki, Rotopak, ENPI Group, Amber Packaging Industries, Arabian Packaging, Integrated Plastics Packaging, Hotpack Packaging Industries, Napco National, Emirates Printing Press, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Flexible Packaging Market Strategic Shifts & Innovations
Active barrier technologies and digital production methods are compressing batch sizes while extending shelf-life claims, reshaping how GCC converters compete on speed versus scale.
High-barrier transparent films incorporating silicon oxide or aluminum oxide coatings are displacing metallized and foil-based structures in premium snack and confectionery applications. Saudi and UAE brand owners specify these for microwaveable and see-through packaging requirements. The technology enables source reduction claims while maintaining oxygen transmission rates below 0.1 cc per square meter per day.
SASO's 2024 technical regulations for plastic food-contact materials tighten specific migration limits and mandate heavy-metal testing thresholds. Converters must requalify existing film formulations or reformulate adhesive and ink systems. The pharmaceutical and infant nutrition segments face the steepest compliance costs due to the most stringent safety margins.
Brand procurement teams in Dubai and Riyadh now specify minimum recycled content targets in flexible packaging tenders, even without mandatory requirements. This preference shift pushes converters to source post-industrial regrind and certified mass-balance materials. The UAE's FMCG sector leads this behavioral change, with Saudi retailers following six to twelve months behind.
GCC Flexible Packaging Market Segmentation
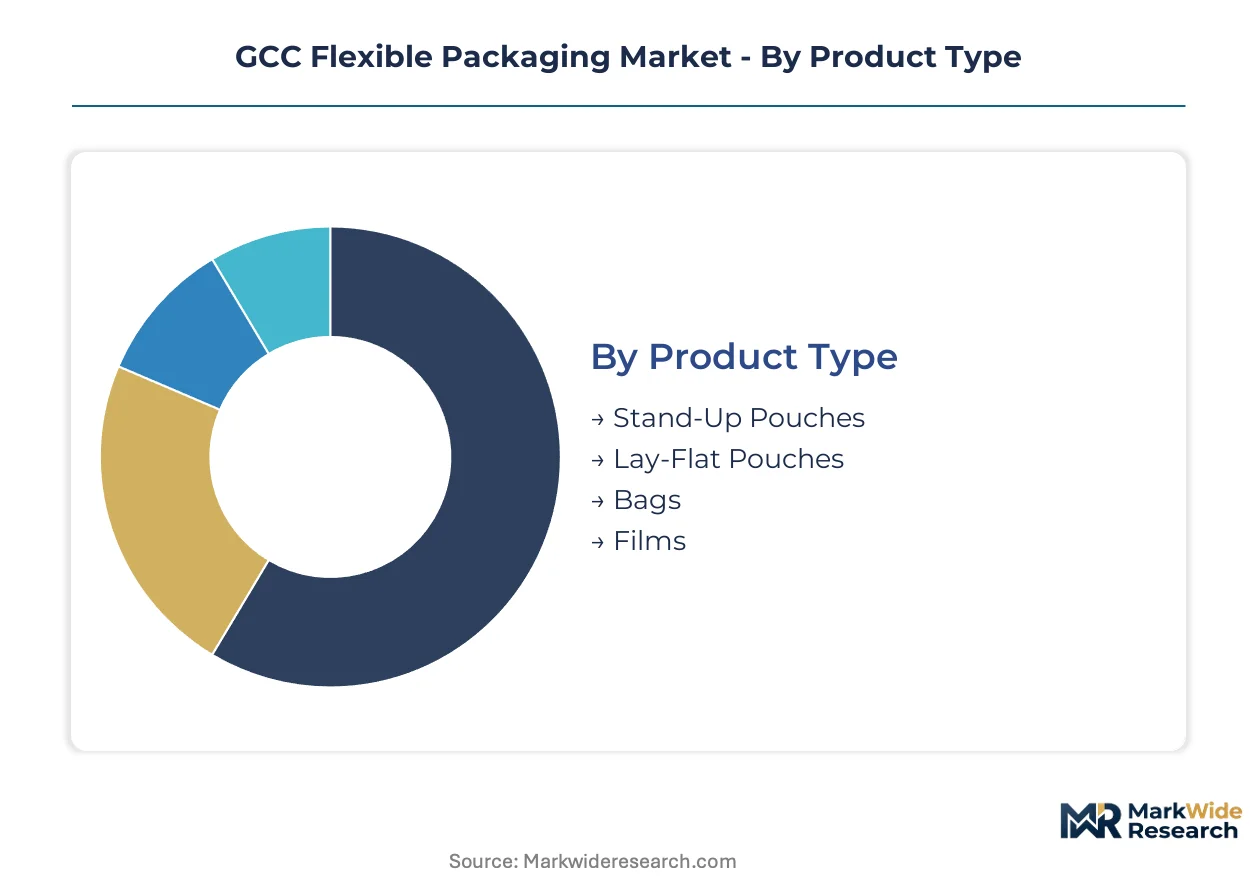
Flexible packaging segmentation in the GCC reflects divergent margin structures across format complexity, material compliance costs, and end-use regulatory intensity. Converters optimize production mix against SASO migration testing timelines and GSO certification requirements that vary sharply by segment.
Product Type:
Highest margin capture sits with formats requiring precision forming and extended shelf-life engineering.
- Stand-Up Pouches:Multi-layer laminates with bottom gusset construction enable vertical shelf display and dispensing functionality. Saudi food manufacturers specify these for ambient ready-to-eat meals where SASO barrier performance standards apply most stringently.
- Lay-Flat Pouches:Three-side-seal or four-side-seal configurations suit portion-controlled and single-serve applications. UAE beverage brands deploy these for liquid concentrates where freight cube efficiency drives procurement decisions against rigid alternatives.
- Bags:Wicketed or loose-fill formats dominate bulk dry goods and frozen distribution. GCC converters run these at highest throughput with lowest changeover burden.
- Films:Rollstock for form-fill-seal equipment serves high-volume automated lines. Jeddah corridor suppliers specialize in printed rollstock for regional dairy and bakery operations.
The dominant share belongs to Stand-Up Pouches, while Lay-Flat Pouches are gaining share fastest on beverage and liquid food conversion.
Material:
Feedstock cost exposure and regulatory compliance burden split margin profiles across polymer families.
- Polyethylene:LDPE and LLDPE grades provide seal integrity and puncture resistance for frozen and chilled distribution. Saudi petrochemical integration gives local converters cost advantage on virgin resin sourcing.
- Polypropylene:BOPP and cast PP films deliver stiffness and optical clarity for snack and confectionery windows. UAE importers face currency exposure on specialty PP grades not produced regionally.
- Biodegradable:PLA and starch-based alternatives attract pilot volumes from sustainability-committed FMCG procurement teams. Performance gaps in barrier properties and heat resistance limit current adoption.
- Plastic Composites:Multi-ply laminates combining PE, PP, and adhesive layers constitute the technical standard for high-barrier applications. SASO migration limits on adhesives and additives drive reformulation costs.
Plastic Composites command volume leadership, with Biodegradable materials climbing fastest on brand-led sustainability tenders.
End User:
Regulatory intensity and validation requirements create tiered pricing power across customer verticals.
- Food:Ambient, chilled, and frozen sub-segments each demand distinct barrier specifications. Saudi Arabia's expanding ready-to-eat production base pulls pouch demand toward retort-compatible structures.
- Beverage:Liquid and semi-liquid formats require fitment integration and drop-test validation. Dubai-based brands specify high-clarity films for premium positioning in retail.
- Pharmaceuticals:Cleanroom manufacturing and batch documentation requirements support premium pricing. Gulf health ministry cold-chain investments expand demand for validated barrier pouches.
- Cosmetics:Sachet and sample formats favor gravure-printed metallized films. UAE duty-free and travel retail channels concentrate volume for this segment.
Food retains the dominant position, though Pharmaceuticals is expanding most quickly on regional healthcare infrastructure investment.
Technology:
Capital intensity and run-length economics determine converter technology mix and customer targeting.
- Rotogravure:Cylinder-based printing delivers highest color consistency and ink density for long-run premium packaging. High setup costs restrict this to stable SKU programs with predictable volumes.
- Flexography:Plate-based printing offers lower tooling burden and faster changeover for mid-volume production. Saudi converters deploy this for private-label food accounts with seasonal variation.
- Digital Printing:Toner and inkjet systems enable short-run variable data without plate costs. UAE FMCG brands use HP Indigo installations for promotional and regional SKU proliferation.
- Lamination:Adhesive and extrusion bonding processes assemble multi-ply structures. Solventless lamination growth responds to SASO volatile organic compound scrutiny.
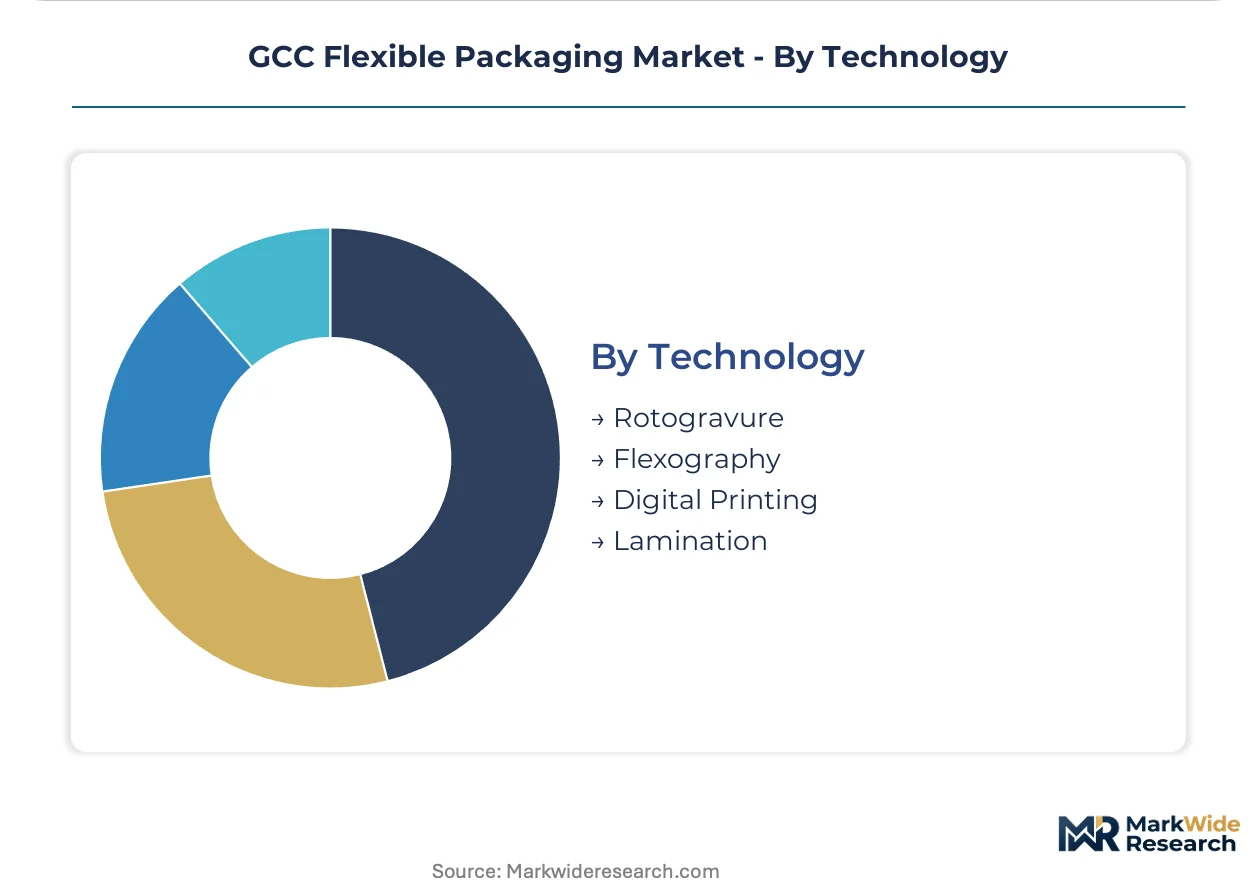
Flexography holds the largest installed base, while Digital Printing is scaling fastest on brand demand for supply chain responsiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GSO harmonized standards and SASO technical regulations are redrawing procurement eligibility across Gulf markets, compressing supplier margins while opening cross-border trade for certified converters.
Saudi Arabia
Ready-to-eat meal manufacturers in Jeddah and Riyadh are expanding retort-compatible pouch capacity for ambient distribution. SASO enforces migration limits and heavy-metal thresholds for food-contact plastics that extend product validation timelines. The Jeddah manufacturing corridor anchors domestic flexible packaging conversion with extensive multi-layer laminate production serving regional food exporters.
United Arab Emirates
Dubai-based beverage brands specify high-clarity films and fitment-integrated pouches for premium retail positioning. MOHAP aligns with GSO standards for cross-border trade facilitation, eliminating redundant testing for compliant suppliers. Dubai Industrial City clusters HP Indigo digital printing installations alongside barrier film lamination lines for FMCG promotional SKUs.
Kuwait
Food importers and distributors drive flexible packaging demand without domestic conversion capacity, creating import dependency. The country's national standards body adopts GSO certification frameworks for food-contact material safety. Kuwait City-based procurement teams source printed pouches and rollstock from Saudi Arabia's Jeddah corridor and UAE exporters.
Qatar
Pharmaceutical cold-chain investments for biologics and vaccines expand demand for validated barrier pouches with cleanroom documentation. The national health regulator applies GSO harmonized standards for medical device and pharmaceutical packaging materials. Doha's logistics hub concentrates temperature-controlled distribution infrastructure requiring specialized flexible packaging formats.
Bahrain
FMCG and cosmetics sectors generate flexible packaging demand through duty-free and travel retail channels. The country's national standards organization implements GSO technical regulations for imported food-contact materials. Manama's commercial districts rely on cross-border supply from Saudi Arabia's Eastern Province converters for pouch and film requirements.
GCC Flexible Packaging Market Key Industry Players
Player mix skews toward regional specialists with GSO certification and multinational converters leveraging European technical heritage. Market structure concentrates around three strategic tiers: petrochemical-integrated film producers, dedicated pouch converters with SASO compliance infrastructure, and pharmaceutical-grade cleanroom specialists. Dominant competitive moves include capacity expansion in Jeddah and Dubai Industrial City clusters, plus strategic partnerships between converters and brand procurement teams for co-developed barrier specifications.
Within the multinational heritage tier, Huhtamaki represents converters leveraging European technical standards for multi-layer barrier production. Among domestic specialists, Rotopak and Amber Packaging Industries exemplify divergent positioning—Rotopak anchors Saudi supply chains with extensive pouch converting infrastructure, while Amber Packaging Industries occupies a position serving Gulf health ministries through pharmaceutical-grade cleanroom operations. These three entities illustrate how certification depth and end-use specialization determine competitive positioning under tightening SASO and GSO frameworks.
| Leading Market Players |
|---|
| Huhtamaki |
| Rotopak |
| ENPI Group |
| Amber Packaging Industries |
| Arabian Packaging |
| Integrated Plastics Packaging |
| Hotpack Packaging Industries |
| Napco National |
| Emirates Printing Press |
| Others |
Cost & Logistics Intelligence
Multi-layer laminate capacity utilization above 85% in Jeddah and Dubai Industrial City clusters compresses converter margins while establishing price floors for compliant supply. Scale economies in SASO-certified production lines concentrate pricing power among petrochemical-integrated film producers and dedicated pouch converters with established GSO infrastructure.
Pricing Analysis
Certification level (GSO/SASO-grade versus non-certified) creates the primary spread across converter tiers. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels tracks validation burden and migration testing timelines. Cost compression in standard-compliant tiers is intensifying because ethylene and propylene feedstock volatility lacks passthrough mechanisms in contract structures. Private-label food manufacturers in Saudi Arabia exhibit highest price sensitivity, while pharmaceutical cold-chain buyers accept premium positioning for validated barrier documentation.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes extend lead times for specialty polypropylene grades and high-purity aluminum foil not produced regionally. Geographic supply concentration centers on Saudi Arabia's petrochemical complexes for polyethylene resin, European and Asian rolling mills for foil, and UAE's Dubai Industrial City for digital printing and lamination capacity. Raw material dependencies rest on naphtha-derived resins, imported BOPP films, and solvent-based adhesives facing SASO volatile organic compound scrutiny. Single-source vulnerability on aluminum foil creates structural risk. Distribution runs through Jeddah corridor exporters serving Kuwait and Bahrain import dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rigid container substitution threatens flexible packaging volume in premium beverage segments where glass and aluminum cans reclaim shelf positioning. Incumbents must defend pouch-based format gains through barrier performance differentiation and regulatory compliance depth.
For Market Incumbents: Fortify GSO certification moats by accelerating solventless lamination capacity additions in Dubai Industrial City and Jeddah corridors. Secure backward integration into polyethylene resin sourcing through petrochemical partnerships. Defend against rigid container resurgence by co-developing retort-compatible structures with Saudi ready-to-eat meal manufacturers.
For New Entrants and Emerging Players: Anchor in Kuwait and Bahrain underpenetration where domestic conversion absence creates import dependency on Saudi and UAE supply. Target pharmaceutical cleanroom flexible packaging in Qatar's expanding cold-chain infrastructure. Deploy digital printing partnerships with UAE FMCG brands for promotional SKU proliferation without plate cost barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with validated barrier documentation and SASO compliance infrastructure over commodity rollstock suppliers. Long-term viability hinges on extended producer responsibility readiness and bio-based content sourcing capabilities. Acquisition target archetype: mid-scale Saudi or UAE converters with GSO certification and pharmaceutical-grade cleanroom operations. Signal to watch: Gulf regulator announcements on post-consumer film collection mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Solventless Lamination Capacity Expansion | SASO volatile organic compound scrutiny favors adhesive systems eliminating solvent-based processes. |
| Digital Printing Integration | HP Indigo installations in Dubai Industrial City enable short-run promotional SKU responsiveness for FMCG brands. |
| Pharmaceutical Cleanroom Certification | ISO 14644 compliance opens Gulf health ministry cold-chain contracts for biologics distribution. |
| Backward Resin Integration | Petrochemical partnerships secure polyethylene supply cost advantage against import-dependent competitors. |
| Extended Producer Responsibility Pilot Participation | Early compliance investments position suppliers for preferred procurement under future Gulf recycling mandates. |
Research Approach
A spread of perspectives from flexible packaging plant managers, FMCG procurement leads, Gulf health ministry supply officers, and petrochemical distribution specialists converged on the working assumptions. Primary interviews with Saudi and UAE converter operations directors, Dubai-based brand category managers, and Kuwaiti food importer logistics heads combined with secondary validation. Secondary sources included SASO technical regulation filings, GSO harmonized standard documentation, GCC customs trade data, and petrochemical complex capacity disclosures. Bottom-up unit economics from individual converter facilities triangulated against top-down demand aggregation from end-use sector consumption patterns.
Segmentation dimensions modeled span product type (stand-up pouch, lay-flat pouch, bag, film), material family (polyethylene, polypropylene, biodegradable, plastic composite), end-use vertical (food, beverage, pharmaceutical, cosmetics), and production technology (rotogravure, flexography, digital printing, lamination). CAGRs derived from historical trajectory analysis and adoption curve positioning across the projection horizon. Industry-specific forecast inputs incorporated SASO migration testing timeline impacts on product launch cycles and GSO certification penetration rates by country.
Material uncertainties — ethylene and propylene feedstock volatility, aluminum foil supply disruption, Gulf regulator timing on extended producer responsibility implementation — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification adoption curves and substitution elasticity between flexible and rigid formats. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market