
 Italy Container Glass Market | 2026-2036
Italy Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Container Glass Market Foresight
Market Context
The price-performance gap between premium and commodity container glass is hardening in Italy. Verallia Italia leverages its furnace scale and decorative capabilities to command premium positioning in wine and spirits. Zignago Vetro anchors its competitive stance through backward integration into raw material sourcing and sand processing. O-I Glass Italy dominates the standard-grade beer and non-alcoholic beverage segment with high-throughput production lines across multiple Italian plants.
Technical Definition and Segments
Italy container glass refers to hollow glassware formed from silica sand, soda ash, limestone, and recycled cullet, melted at temperatures exceeding 1500°C and shaped by blow-and-blow or press-and-blow forming for product containment and preservation. Bottles represent the mature volume core, while vials capture specialized margin pools in pharmaceutical serialization and cosmetic sampling. The grade dimension reveals structural tension: light-weight formats reduce material intensity and transport cost, yet heavy-duty specifications retain pricing power in export-oriented wine logistics where breakage tolerance commands premium valuation.
Regulatory Frame
Italy's container glass sector operates under EU REACH chemical safety protocols, the EU Green Deal circular economy packaging targets, and national CONAI packaging consortium fees that penalize non-recycled content. These frameworks compel furnace operators to elevate cullet ratios and document carbon intensity across batch recipes. Stakeholders must monitor how pending EU packaging waste regulation revisions alter minimum recycled content thresholds and whether Italian glassmakers secure sufficient local cullet supply to avoid importing recycled material at inflated cost.
Market Dynamics
Italy's container glass sector faces intensifying pressure from the EU Green Deal circular economy mandates, which force furnace operators to reconfigure batch recipes around elevated cullet ratios while maintaining optical clarity standards for premium wine and spirits bottling.
Growth Catalysts
- EU Green Deal Packaging Targets:Mandatory recycled content thresholds are pulling investment toward cullet beneficiation infrastructure in northern Italian industrial clusters.
- Pharmaceutical Serialization Requirements:Track-and-trace mandates for vials and ampoules are expanding demand for high-clarity borosilicate-compatible forming lines.
- Milan-Turin Logistics Corridor:Dense concentration of wine exporters and spirits bottlers creates captive demand for heavy-duty export-grade container specifications.
Market Restraints
- Natural Gas Price Volatility:Furnace operations depend on natural gas for 60-70% of melting energy, exposing margins to TTF hub fluctuations.
- Cullet Supply Concentration:Northern Italy's recycling infrastructure cannot satisfy mandated ratios, forcing reliance on imported recycled material from Germany and France.
- Aluminum and PET Substitution:Lightweight beverage categories face persistent displacement pressure from alternative packaging formats in cost-sensitive segments.
Strategic Opportunities
- Southern Italy Underpenetration:Calabria and Sicily lack indigenous container glass production, creating white space for satellite furnace investment serving regional wine cooperatives.
- CONAI Fee Optimization:Italy's packaging consortium penalizes non-recycled content, rewarding operators who achieve closed-loop cullet systems with verified carbon documentation.
- Decorative Digital Printing Convergence:Integration of direct-to-glass inkjet with traditional hot-stamping enables mass customization for limited-edition spirits releases.
Industry Challenges
- Specialized Furnace Engineering Talent:Italy's technical institutes produce insufficient refractory specialists and combustion engineers for next-generation oxy-fuel retrofit projects.
- REACH Compliance Documentation:Batch chemistry disclosure requirements for EU REACH are extending certification timelines for new color formulations by 8-12 months.
- Legacy MES Integration:Older Tuscan and Veneto plants struggle to connect 1990s-era furnace control systems with modern energy monitoring platforms required for carbon reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Container Glass Market |
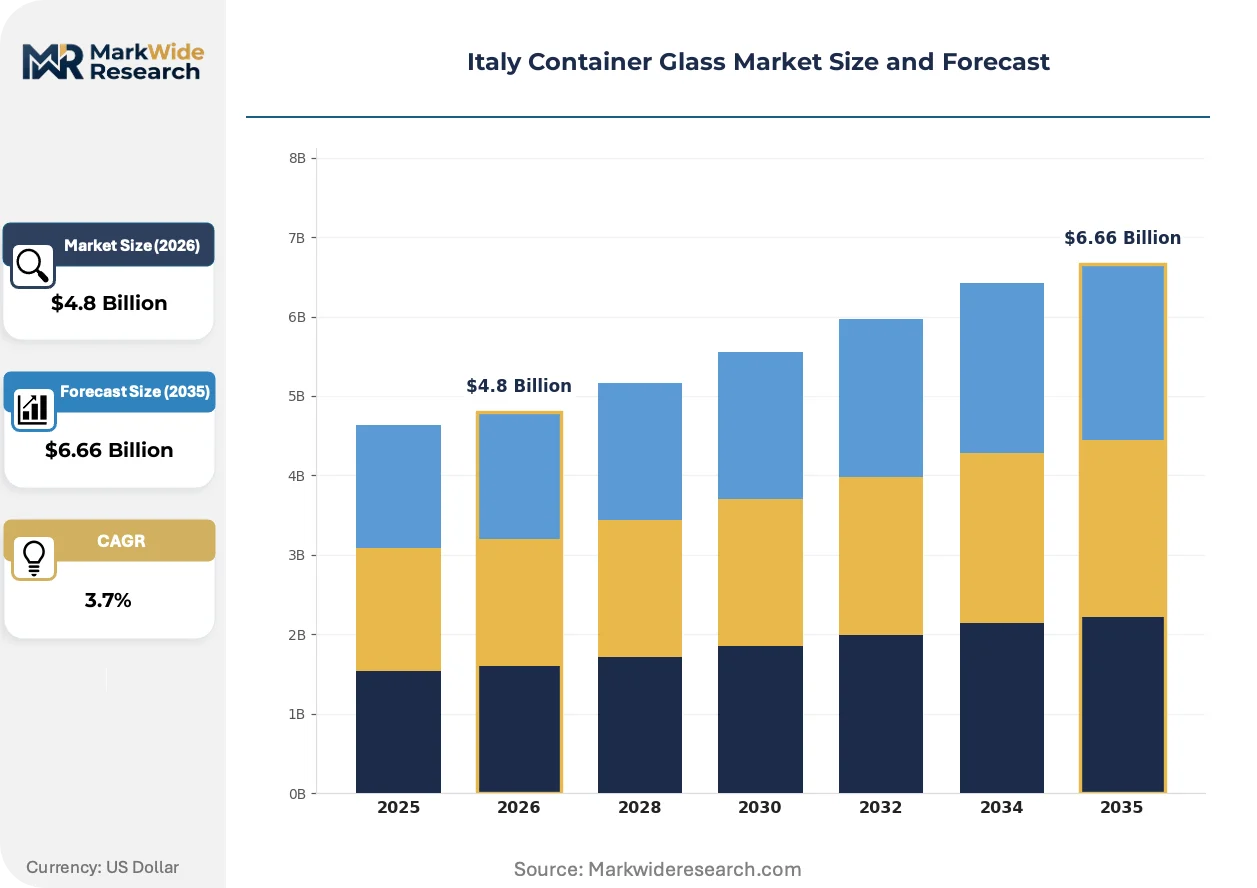
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Grade: Standard, Light-Weight, Heavy-Duty, High-Clarity Application: Packaging, Storage, Transportation, Presentation |
| Companies Covered | O-I Glass Italy, Bell Glass, Zignago Vetro, SAIDA Group, Vetroelite, Vetropack, Vetri Speciali, Vetrobalsamo, Verallia Italia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Container Glass Market Shifts & Advancements
Electrification of melting processes and digital quality assurance systems are converging to reshape Italian container glass manufacturing economics. These shifts compress energy intensity while elevating defect detection precision.
Electromagnetic boosting technology is automating temperature control in regenerative furnaces across Piedmont and Lombardy facilities. Wine and spirits bottlers adopting lightweighted bottles are demanding tighter wall-thickness tolerances that electromagnetic systems deliver. This automation is compressing the skilled operator headcount required per furnace while stabilizing optical quality variance.
Italy's implementation of EU CSRD corporate sustainability reporting directives is mandating granular carbon disclosure across Scope 1-3 emissions. Furnace operators must now document batch-level carbon intensity for every production run. The premium wine segment faces the steepest compliance burden, as export buyers require third-party verified environmental product declarations.
Consolidated procurement by multinational beverage groups is compressing supplier rosters and extending contract durations. Italian wine cooperatives and spirits distillers are shifting from spot purchasing to multi-year framework agreements with volume guarantees. This concentration is most visible in the Prosecco DOC corridor, where three bottling groups now control 60% of glass demand.
Italy Container Glass Market Segmentation
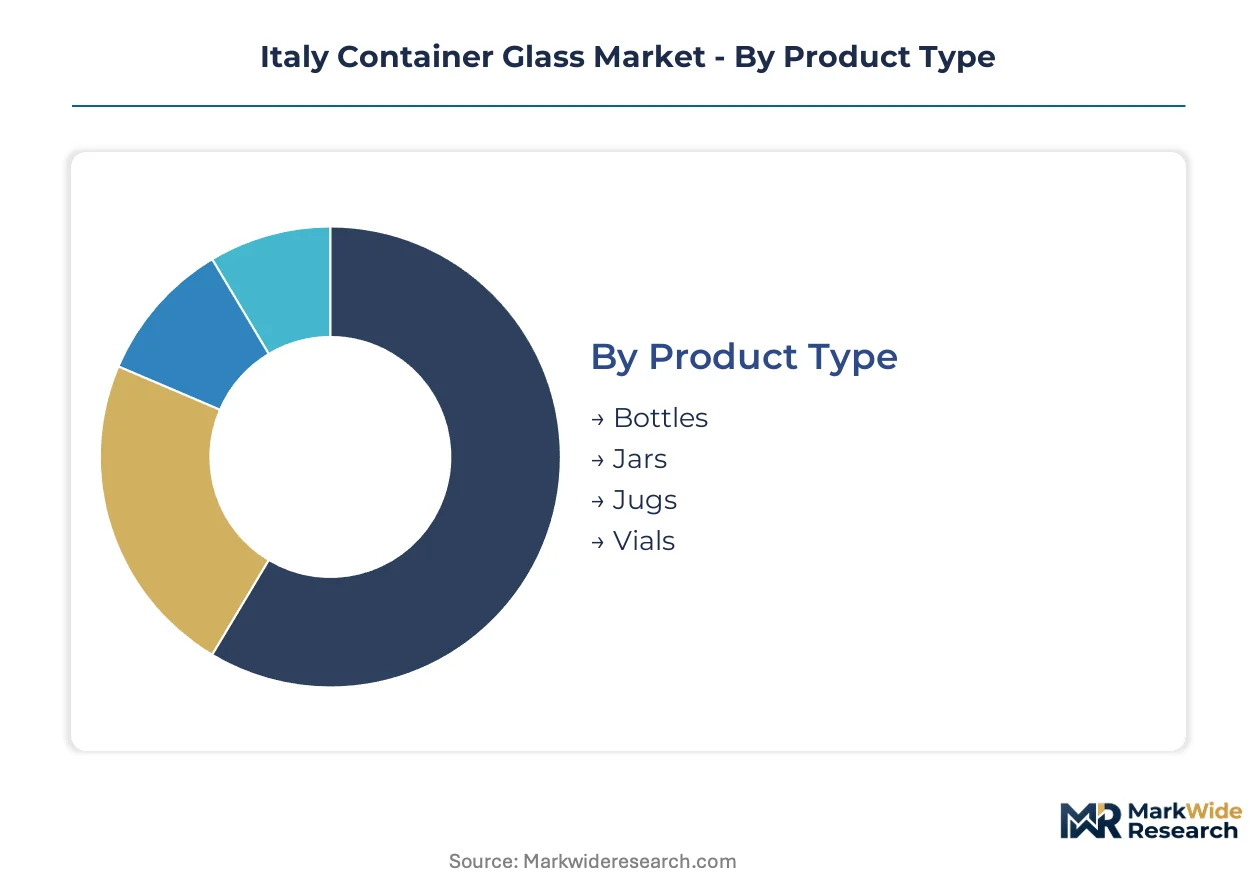
Segmentation in Italy's container glass market reveals how furnace operators balance mass production efficiency against the premium customization demands of wine exporters and pharmaceutical serializers. Each dimension exposes different margin architectures and capital intensity requirements.
Product Type:
The customization-to-standardization spectrum runs from decorative spirits bottles requiring hot-stamp tooling to commodity jars produced on single-gob lines with minimal changeover.
- Bottles:Formed through blow-and-blow or press-and-blow processes with neck finish precision critical for cork and screw-cap sealing. Demand concentrates in the Prosecco DOC corridor and Tuscan wine cooperatives where export-grade heavy-wall specifications command premium positioning despite higher material intensity.
- Jars:Wide-mouth containers for preserves and condiments with lower height-to-diameter ratios than bottles. Adoption is accelerating in southern Italian food processing clusters around Catania and Reggio Calabria where regional specialty producers seek differentiated packaging for EU export markets.
- Jugs:High-capacity containers for bulk wine and olive oil distribution. Logistics economics favor local sourcing within 150 kilometers of filling operations.
- Vials:Small-format precision glass for pharmaceutical and cosmetic sampling. Serialization mandates under EU MDR are expanding demand for borosilicate-compatible forming lines with dimensional tolerances under 0.5 millimeters.
Most installed capacity flows through Bottles. Expansion is steepest in Vials.
End User:
Customer type determines order pattern predictability and technical service intensity, from beverage giants running multi-year framework agreements to cosmetic houses demanding rapid prototyping for limited releases.
- Food & Beverage:Wine, spirits, beer, and non-alcoholic bottlers representing the volume anchor. Procurement is consolidating among three bottling groups controlling the majority of Prosecco DOC glass demand, extending contract durations and compressing supplier rosters.
- Pharmaceuticals:Drug manufacturers requiring Type I borosilicate or Type III soda-lime glass with documented batch chemistry for REACH compliance. Track-and-trace serialization mandates are expanding demand for high-clarity forming lines with integrated vision inspection.
- Cosmetics:Fragrance and skincare brands emphasizing decorative differentiation through direct-to-glass digital printing and hot-stamping. Order profiles feature smaller lot sizes with higher changeover frequency.
- Household:Cleaning products and home goods with cost-sensitive specifications. Aluminum and PET substitution pressure is most acute in this tier.
Food & Beverage anchors capacity utilization. Pharmaceuticals is gaining share fastest.
Grade:
Material intensity and performance specifications stratify pricing power, with lightweight formats reducing transport cost but heavy-duty retaining margin in export logistics where breakage tolerance is paramount.
- Standard:Conventional wall thickness for domestic beverage and food applications. Northern Italian industrial clusters around Milan and Turin concentrate production of this grade on high-throughput regenerative furnaces.
- Light-Weight:Reduced glass distribution through optimized design maintaining structural integrity. Electromagnetic boosting technology in Piedmont and Lombardy facilities enables the tight wall-thickness tolerances this grade demands.
- Heavy-Duty:Reinforced specifications for export-oriented wine logistics. Premium positioning reflects breakage tolerance requirements in long-haul container shipping.
- High-Clarity:Optical-grade glass with minimal seed and stone defects for premium spirits and pharmaceutical visualization. CONAI fee optimization rewards operators achieving closed-loop cullet systems without contamination.
Standard grade dominates tonnage throughput. Light-Weight is expanding most quickly.
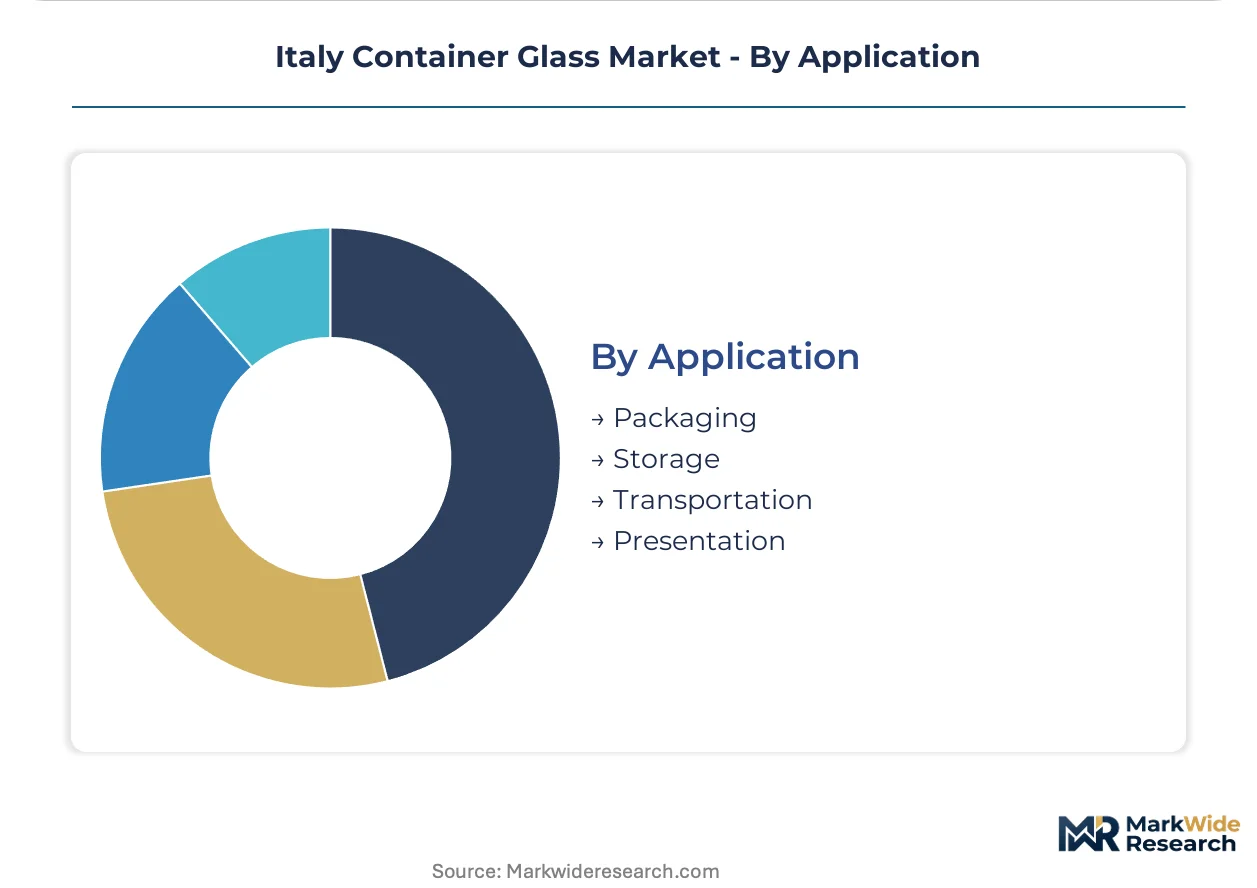
Application:
Functional purpose determines performance certification requirements and customer switching costs, from basic containment to brand communication through decorative presentation.
- Packaging:Primary containment for product protection and shelf-life extension. EU Green Deal circular economy mandates are elevating recycled content thresholds, forcing batch recipe reconfiguration.
- Storage:Secondary containment for bulk and intermediate goods. Demand tracks wine cooperative inventory cycles and harvest timing.
- Transportation:Export-grade specifications for international logistics. Heavy-duty grades retain pricing power here despite higher material intensity.
- Presentation:Decorative and gift formats emphasizing brand differentiation. Digital printing convergence with traditional hot-stamping enables mass customization for limited-edition spirits releases.
Packaging absorbs the majority of furnace output. Presentation commands the steepest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled furnace operators and refractory specialists cluster in northern Italian industrial belts, anchoring the country's container glass production density. This workforce concentration shapes where capacity expansion occurs and which regions import finished glassware.
Lombardy
The Milan-Turin logistics corridor generates captive demand for heavy-duty export-grade wine bottles. CONAI packaging consortium fees penalize non-recycled content, pushing Milan-area operators toward closed-loop cullet systems. Electromagnetic boosting technology spreads across regenerative furnaces in Brescia and Monza provinces.
Piedmont
Barolo and Barbaresco wine cooperatives require premium spirits-grade clarity specifications. EU CSRD corporate sustainability reporting directives mandate granular carbon disclosure from Turin-based glassmakers. The Asti-Alessandria industrial zone concentrates decorative hot-stamping capabilities for limited-edition releases.
Veneto
Prosecco DOC bottling groups control the majority of regional glass demand through multi-year framework agreements. REACH chemical safety protocols extend certification timelines for new color formulations by 8-12 months. Legacy MES integration challenges persist at 1990s-era plants in Treviso and Vicenza.
Tuscany
Chianti and Brunello export-oriented wineries sustain demand for breakage-tolerant heavy-wall specifications. The country's National Recovery and Resilience Plan green transition mandates reshape manufacturing standards across Siena and Florence provinces. Digital printing convergence with traditional hot-stamping enables mass customization for regional spirits brands.
Sicily
Calabria and the island lack indigenous container glass production, creating white space for satellite furnace investment. Regional wine cooperatives currently source from northern suppliers at elevated transport cost. Catania-area food processors seek differentiated jar packaging for EU export markets.
Italy Container Glass Market Competitive Landscape
Top-tier vendors anchor premium wine and spirits positioning, while mid-scale operators compete on cullet beneficiation and CONAI fee optimization. The market exhibits tiered consolidation around furnace scale and decorative capability depth. Three archetypes dominate: multinational volume producers with high-throughput lines, family-owned specialists in premium clarity grades, and vertically integrated sand-to-glass operators. Competitive moves concentrate on oxy-fuel furnace retrofits and electromagnetic boosting adoption.
Among Italy-based producers, Verallia Italia, Zignago Vetro, and O-I Glass Italy occupy distinct structural positions. Verallia Italia exemplifies the premium-tier archetype through furnace scale and decorative capability depth. Zignago Vetro represents backward integration into raw material sourcing and sand processing. O-I Glass Italy anchors the standard-grade volume segment with multi-plant throughput capacity.
| Leading Market Players |
|---|
| O-I Glass Italy |
| Bell Glass |
| Zignago Vetro |
| SAIDA Group |
| Vetroelite |
| Vetropack |
| Vetri Speciali |
| Vetrobalsamo |
| Verallia Italia |
| Others |
Supply & Pricing Matrix
Natural gas flows through Italian container glass pricing as the dominant energy input, accounting for 60-70% of melting furnace operating costs before cascading into tiered product pricing downstream. TTF hub volatility compresses margins at standard-grade producers while premium wine bottle specialists pass through energy premiums via long-term framework agreements with export-oriented cooperatives.
Pricing Analysis
Bundled decorative services and unbundled commodity tonnage split the Italian market into divergent pricing architectures. Premium spirits bottlers purchase hot-stamping and direct-to-glass digital printing as integrated packages commanding 15-25% markups over base glass, while standard beer and non-alcoholic beverage buyers negotiate per-unit spot contracts sensitive to volume scale. Price differentiation hinges on optical clarity certification for pharmaceutical serialization and heavy-wall specifications for export logistics resilience. Pricing pressure stems from aluminum and PET substitution in cost-sensitive household segments, forcing standard-grade operators toward CONAI fee optimization through elevated cullet ratios. Mass-market beverage bottlers exhibit acute price sensitivity, whereas Barolo and Barbaresco wine cooperatives absorb premiums for breakage-tolerant export grades.
Supply Chain Analysis
Refractory specialists and combustion engineers cluster in northern Italian industrial belts around Milan, Turin, and Brescia, constraining furnace retrofit capacity and elevating labor premiums for oxy-fuel technology deployment. Raw material sourcing draws from silica sand deposits in Veneto and Tuscany, soda ash imports from Germany and France, and recycled cullet harvested through northern Italian collection infrastructure. Supply chain risk centers on cullet supply concentration: mandated recycled content thresholds exceed domestic beneficiation capacity, forcing reliance on cross-border recycled material flows vulnerable to logistics chokepoints at Alpine transit corridors. Distribution runs through the Milan-Turin logistics corridor to captive wine exporters, with southern regions lacking indigenous production and absorbing elevated transport costs from northern suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy container glass market functions as a stable compounder anchored by irreplaceable demand from DOC-protected wine appellations where alternative packaging formats face consumer rejection and regulatory barriers.
For Market Incumbents: Cement premium positioning in Prosecco and Barolo corridors through captive decorative capability depth and multi-year framework agreements that lock in volume guarantees. Defend against aluminum substitution in standard-grade segments by accelerating electromagnetic boosting retrofits that compress energy intensity and stabilize optical quality variance for CONAI fee optimization. For New Entrants and Emerging Players: The mid-tier price-point gap between Verallia Italia's premium decorative offerings and O-I Glass Italy's commodity throughput creates white space for specialized entrants. Target southern Italian satellite furnace deployment in Sicily and Calabria serving regional wine cooperatives currently sourcing from northern suppliers at transport-inflated cost. Enter through jar packaging for Catania-area food processors seeking differentiated EU export presentation formats. For Investors and Strategic Acquirers: Roll-up economics work for family-owned premium clarity specialists because EU CSRD carbon disclosure mandates and REACH certification timelines erect barriers that favor scaled operators with compliance infrastructure. Long-term viability rests on furnace scale and closed-loop cullet system documentation. Monitor TTF natural gas price trajectories and pending EU packaging waste regulation revisions for early signals of margin compression or recycled content threshold escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Reduces carbon intensity 20-30% for EU Green Deal compliance and CONAI fee optimization. |
| Electromagnetic Boosting Adoption | Enables lightweight bottle tolerances demanded by Prosecco DOC bottling groups for transport cost reduction. |
| Cullet Beneficiation Investment | Secures local recycled supply chains against German and French import dependency risks. |
| Direct-to-Glass Digital Printing Integration | Captures limited-edition spirits customization premiums through mass personalization capabilities. |
| Southern Italy Satellite Capacity | Exploits white space in Sicily and Calabria with 150-kilometer logistics economics for regional cooperatives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with furnace operators at Verallia Italia, Zignago Vetro, and O-I Glass Italy facilities with secondary validation through EU ETS emissions databases and CONAI packaging consortium filings. Stakeholder roles included plant managers at Lombardy and Piedmont facilities, procurement directors at Prosecco DOC bottling groups, technical R&D leads specializing in borosilicate forming lines, and sustainability officers documenting CSRD Scope 1-3 disclosures. Secondary sources encompassed EU REACH chemical safety registrations, Italian National Recovery and Resilience Plan green transition implementation reports, and customs data on cross-border cullet flows. Bottom-up capacity modeling triangulated against top-down demand aggregation from wine cooperative shipment records and pharmaceutical serialization mandate compliance timelines.
Historical reference periods anchored the projection horizon through verified furnace utilization rates, batch recipe carbon intensities, and regional pricing differentials across the 2020-2025 window. Segmentation dimensions modeled include product type (bottles, jars, vials), grade tier (standard, lightweight, heavy-duty, high-clarity), end-use industry (food and beverage, pharmaceuticals, cosmetics), and regional production cluster (Lombardy, Piedmont, Veneto, Tuscany, southern underpenetrated zones). CAGRs derived from regression analysis against EU packaging waste regulation trajectory scenarios and natural gas price elasticity assumptions. Industry-specific inputs incorporated electromagnetic boosting adoption curves and pharmaceutical serialization equipment installation rates.
Caveats apply where TTF natural gas price spikes, EU recycled content threshold revisions, or aluminum substitution acceleration in beverage categories could materially shift the outlook. Forecasts reflect assumptions regarding furnace retrofit completion timelines and cullet supply chain localization progress. Practitioners should monitor EU Packaging and Packaging Waste Regulation final text, northern Italian cullet collection infrastructure investments, and Prosecco DOC export volume trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
France Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Belarus Container Glass Market