
 Global Concrete Bonding Agents Market | 2026-2036
Global Concrete Bonding Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Bonding Agents Market Intelligence
Expanded production capacity in Southeast Asian nations like Vietnam and Indonesia is reshaping the supply landscape for concrete bonding agents. Sika AG leverages its extensive distribution network to capture repair and restoration projects across multiple regions. In parallel, BASF SE differentiates through its advanced polymer chemistry for high-performance applications. Mapei S.p.A. competes on a broad product portfolio tailored for both commercial builders and residential developers.
Concrete bonding agents are polymer-based formulations that enhance adhesion between hardened concrete and freshly placed concrete or repair mortars. These materials, often featuring epoxy or acrylic chemistry, create a durable, monolithic bond that prevents delamination. Epoxy-based agents command a premium in structural strengthening applications due to their superior bond strength and chemical resistance. Acrylic-based variants lead in volume for general repair and restoration work, valued for their versatility and ease of use.
Regulatory frameworks including the EU's REACH, US EPA standards on volatile organic compounds, and China's GB standards for building materials are influential. These rules mandate lower environmental impact and higher safety profiles for chemical admixtures used in construction. Consequently, manufacturers must balance achieving compliance with maintaining the performance integrity required by infrastructure developers and specialty contractors for critical applications.
Market Dynamics
The market's central dynamic is the tension between the construction industry's demand for high-strength, durable bonding solutions for infrastructure repair and the simultaneous regulatory pressure to reduce the environmental and health impact of chemical-based building materials.
Growth Catalysts
- Infrastructure Renewal Programs:Government-led initiatives, such as India's National Infrastructure Pipeline and extensive bridge repair projects in the United States, create sustained demand for bonding agents in large-scale restoration and strengthening applications.
- Advanced Repair Materials:The development of specialized epoxy and hybrid polymer agents with superior adhesion and chemical resistance enables more complex structural repairs, expanding the addressable market beyond simple concrete patching.
- Urbanization in Developing Economies:Rapid construction of high-rise commercial and residential buildings, particularly in Southeast Asian cities, drives high-volume demand for versatile and easy-to-use acrylic-based bonding agents for general construction and finishing work.
Market Restraints
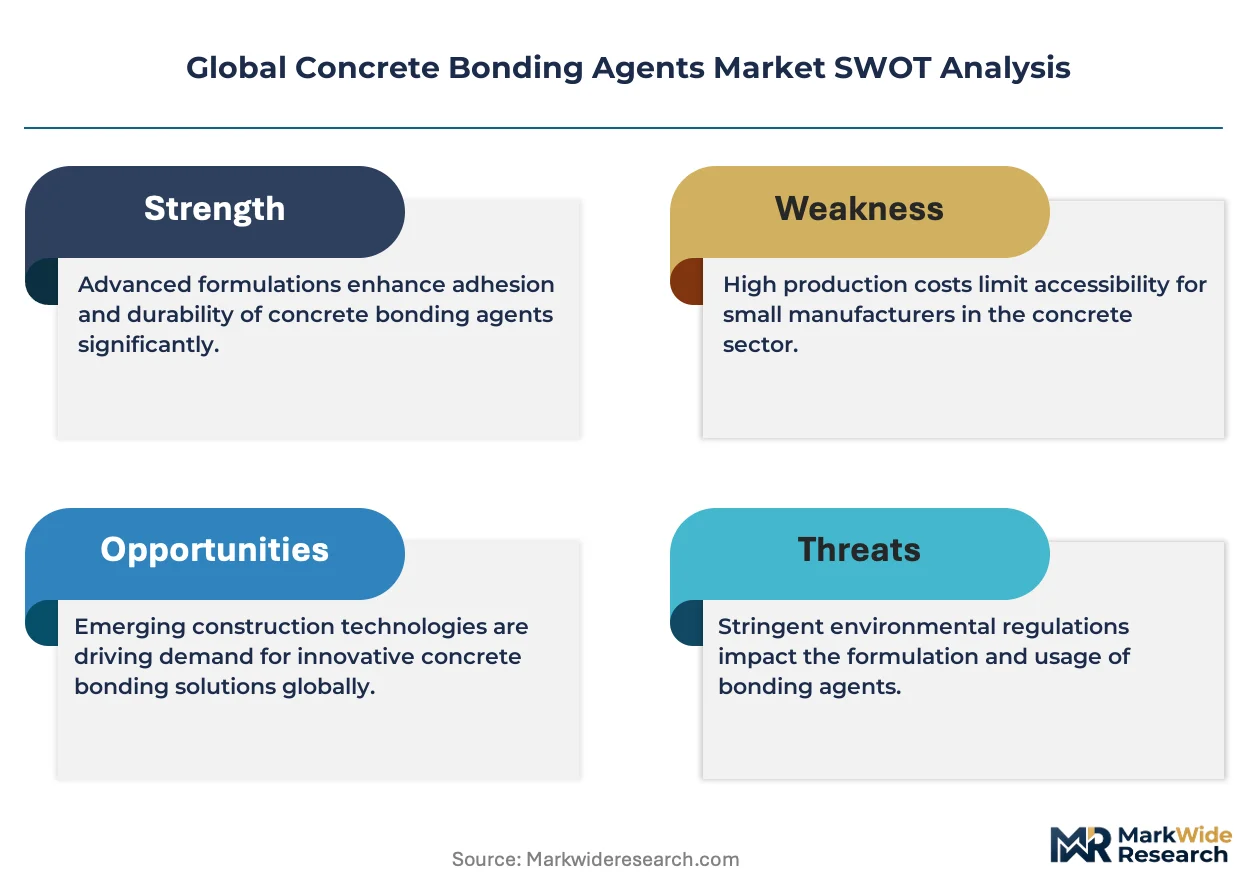
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key petrochemical feedstocks, such as epoxy resins and acrylic monomers, which can compress manufacturer margins and lead to price instability for end-users.
- Application Sensitivity:The performance of high-strength epoxy-based agents is highly dependent on correct surface preparation, mixing ratios, and ambient temperature, creating a risk of bond failure if applied by untrained labor.
- Substitution from Integrated Mortars:Advances in polymer-modified cementitious mortars that offer built-in bonding properties pose a substitution threat in non-structural repair applications, potentially reducing demand for standalone bonding agents.
Strategic Opportunities
- Bio-Based Formulations:Developing bonding agents from bio-derived polymers and recycled feedstocks presents an opportunity to meet demand from green building projects and appeal to specifiers focused on sustainability and LEED certification.
- Seismic Retrofitting Mandates:New or updated building codes in earthquake-prone regions like Turkey, Japan, and parts of the United States create a high-value niche for specialized bonding agents designed for structural reinforcement and seismic upgrades.
- Expansion in Latin America:Underpenetrated markets in countries like Brazil and Mexico offer growth potential as major infrastructure and industrial construction projects increase the need for reliable concrete repair and bonding solutions.
Industry Challenges
- Divergent Regulatory Compliance:Manufacturers face significant cost and complexity in formulating products that simultaneously comply with different regional chemical regulations, such as the EU's REACH, US EPA VOC limits, and China's GB standards.
- Shortage of Skilled Applicators:A persistent lack of properly trained contractors who can handle the technical demands of two-component epoxy systems limits the adoption of these high-performance products and can lead to project failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Bonding Agents Market |
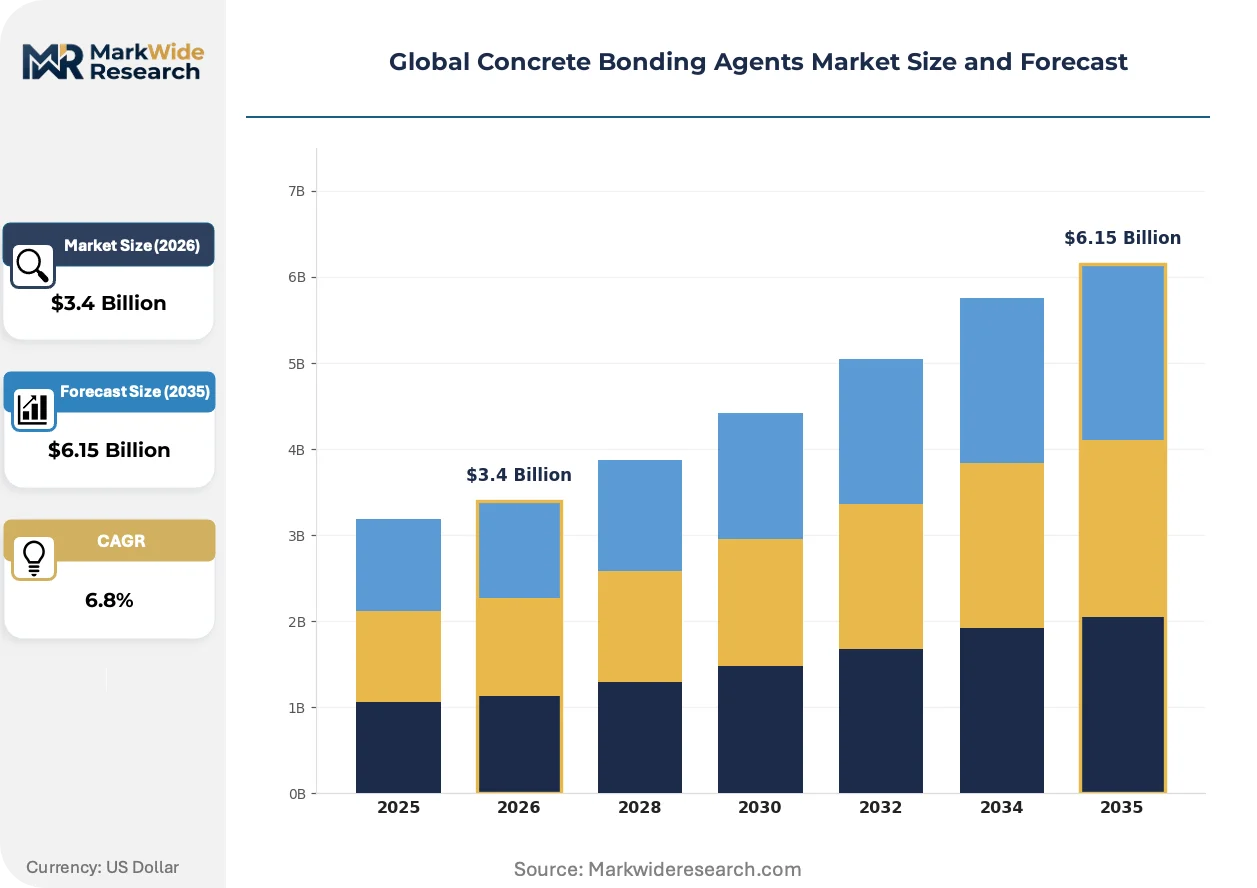
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy-Based, Acrylic-Based, Latex-Based, Styrene-Butadiene, Polyurethane-Based Application: Repair & Restoration, Floor Toppings, Concrete Overlays, Mortar Bonding, Structural Strengthening End User: Construction Contractors, Infrastructure Developers, Commercial Builders, Residential Developers, Specialty Contractors Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms, Industrial Suppliers |
| Companies Covered | Sika AG, BASF SE, Fosroc International Ltd., Saint-Gobain Weber S.A., Mapei S.p.A., The Euclid Chemical Company, LafargeHolcim, GCP Applied Technologies Inc., Dow Construction Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Bonding Agents Market Strategic Shifts & Innovations
Product development is increasingly focused on creating low-VOC and water-based formulations that meet stringent environmental regulations without sacrificing the bond strength and durability required for critical infrastructure applications. This push towards sustainable performance is a defining theme.
Digital simulation software is a key technological advance in material science. Structural engineers and specialty contractors are adopting this software to model and predict the long-term performance of a bonded concrete joint under specific environmental and load conditions. This technology is virtualizing parts of the material selection and testing process, reducing reliance on physical mock-ups and accelerating the approval of advanced polymer systems for critical repairs.
The European Union's Construction Products Regulation (CPR) is a significant regulatory driver. It compels manufacturers to provide a Declaration of Performance (DoP) with CE marking, detailing standardized data on essential characteristics like bond strength and reaction to fire. This affects all bonding agents sold within the EU, pushing manufacturers globally to invest in rigorous testing and documentation to access the European market, especially for structural-grade products.
A notable shift in purchasing behavior involves asset owners specifying performance outcomes rather than just products. For major infrastructure projects, procurement is moving away from a simple cost-per-liter basis towards requiring guarantees on service life and bond durability. This trend is most evident in public-private partnership (P3) contracts for transportation infrastructure in Canada and Australia, favoring suppliers who can provide engineering support and performance data.
Global Concrete Bonding Agents Market Segmentation
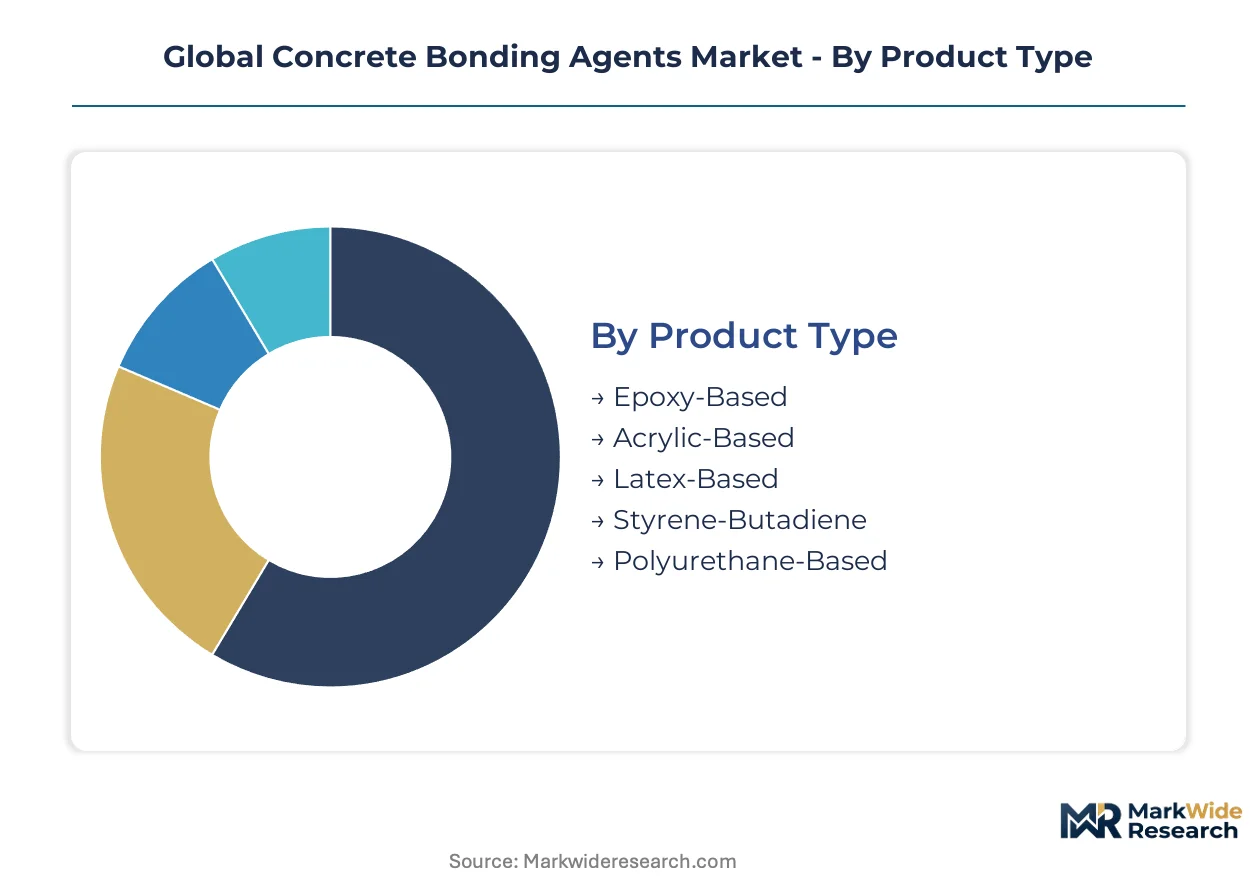
The concrete bonding agents market segments reflect distinct material chemistries, application requirements, and end-user purchasing behaviors. Understanding these categorizations is essential for manufacturers to tailor product development and market strategies effectively.
Product Type:
Segments within product type exhibit varied cycle times, reflecting material durability and application demands across the construction sector.
- Epoxy-Based:These two-component systems provide superior bond strength and chemical resistance for critical structural applications, often requiring precise mixing and curing conditions. Demand concentrates in seismic retrofitting projects across Japan and California, driven by stringent building codes for structural integrity.
- Acrylic-Based:Acrylic-based agents are water-borne polymer emulsions, valued for their versatility, ease of application, and cost-effectiveness in general construction. Volume demand is high in urban development programs within India, supporting general repair and finish work in commercial and residential buildings.
- Latex-Based:These formulations offer good adhesion and flexibility, often used for bonding fresh concrete to existing surfaces in non-structural repairs.
- Styrene-Butadiene:Styrene-butadiene rubber (SBR) based agents enhance bond strength and waterproofing, finding use in overlays and patching compounds.
- Polyurethane-Based:Polyurethane-based agents provide excellent flexibility and chemical resistance, suitable for applications requiring movement accommodation or exposure to harsh environments.
Acrylic-Based bonding agents dominate the installed base. Epoxy-Based formulations are where expansion concentrates.
Application:
Application segments differentiate by the performance requirements and structural integrity demanded by various construction tasks.
- Repair & Restoration:This segment involves using bonding agents to repair deteriorated concrete structures, including patching, crack filling, and surface rehabilitation. Extensive infrastructure renewal programs in the United States create significant demand for these materials to extend asset lifespans.
- Structural Strengthening:These applications utilize high-performance bonding agents to enhance the load-bearing capacity and durability of existing concrete elements, crucial for seismic upgrades or design modifications. Projects in earthquake-prone regions like Turkey frequently specify these advanced agents.
- Floor Toppings:Bonding agents ensure durable adhesion of decorative or protective floor toppings to concrete substrates, preventing delamination in commercial and industrial settings.
- Concrete Overlays:These materials facilitate the bonding of thin concrete layers for resurfacing or aesthetic purposes, common in architectural concrete applications.
- Mortar Bonding:Bonding agents improve the adhesion of repair mortars to concrete, preventing separation and ensuring the integrity of the patched area.
Repair & Restoration applications drive the largest volume. Structural Strengthening shows the steepest expansion trajectory.
End User:
End-user categories vary significantly in their procurement scale and technical specification needs for concrete bonding agents.
- Infrastructure Developers:These entities manage large-scale public works projects like bridges, highways, and dams, requiring high-performance, durable bonding agents for repair and new construction. National infrastructure initiatives in Canada stimulate substantial procurement from this group.
- Construction Contractors:General construction contractors utilize bonding agents across a broad spectrum of projects, from commercial buildings to residential developments, prioritizing versatility and ease of use. Their purchasing patterns are influenced by regional building activity and project pipelines.
- Commercial Builders:This segment focuses on non-residential structures, including offices, retail spaces, and industrial facilities, where bonding agents are used for flooring, repairs, and structural elements.
- Residential Developers:Residential developers procure bonding agents for housing projects, primarily for general repairs, floor preparation, and non-structural bonding tasks.
- Specialty Contractors:These contractors focus on niche applications such as seismic retrofitting, waterproofing, or specific restoration projects, often requiring highly specialized and high-performance bonding solutions.
Infrastructure Developers command high-value projects. Residential Developers represent a growing customer base.
Distribution Channel:
Distribution channels for concrete bonding agents reflect a mix of direct manufacturer relationships and broad market access strategies.
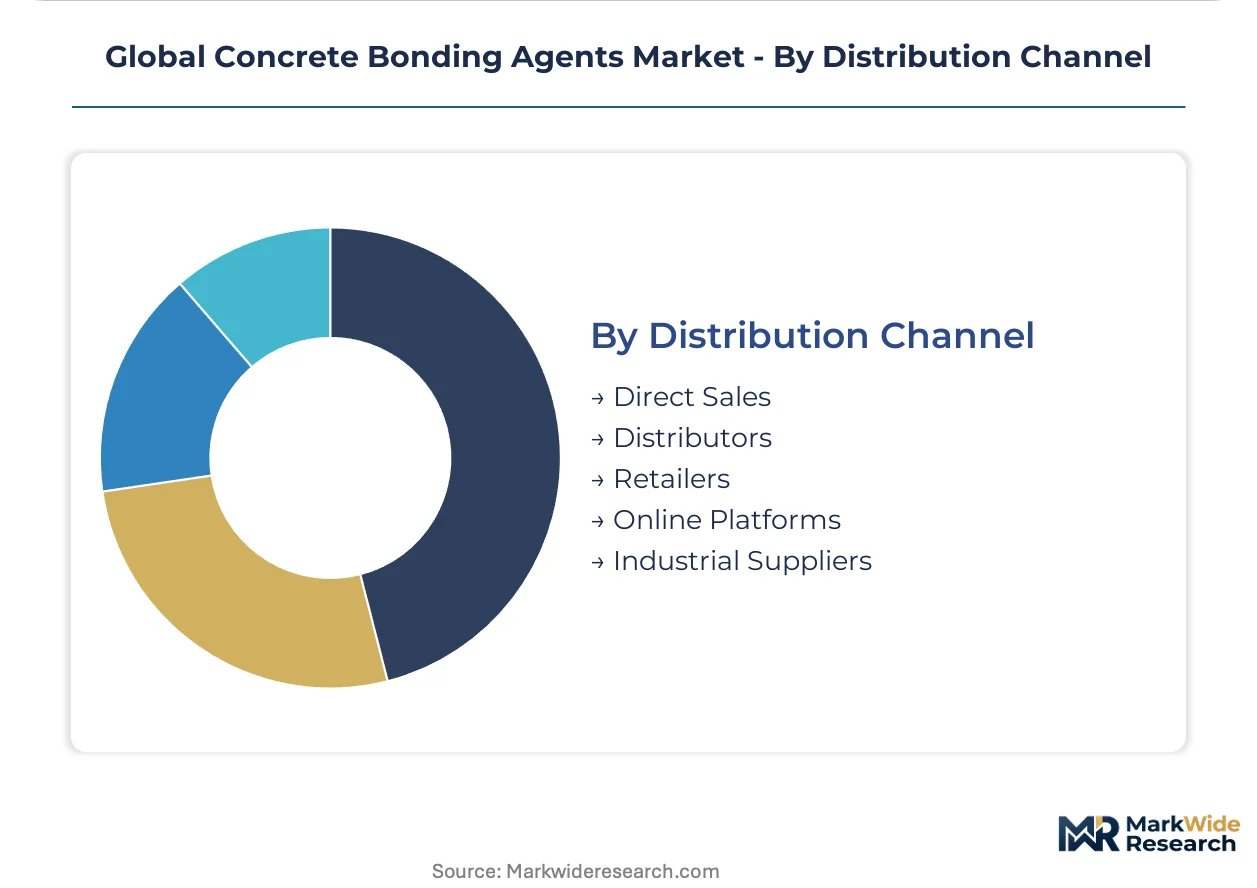
- Direct Sales:Manufacturers engage directly with large infrastructure developers and specialty contractors for high-volume or technically demanding projects, providing specialized support and customized solutions. This channel is critical for complex structural strengthening applications.
- Distributors:Distributors serve as intermediaries, providing regional warehousing, logistics, and technical support to a wide range of contractors and smaller builders. Their extensive networks are crucial for reaching diverse construction sites across Europe.
- Retailers:Retail channels cater to smaller contractors and DIY enthusiasts, offering readily available, general-purpose bonding agents for minor repairs and home improvement projects.
- Online Platforms:E-commerce platforms facilitate convenient purchasing of various bonding agents, particularly for standard products, appealing to buyers seeking competitive pricing and quick delivery.
- Industrial Suppliers:These suppliers provide a focused range of construction chemicals, including bonding agents, to industrial clients and large-scale construction sites, often with bulk purchasing options.
Distributors manage broad geographic reach. Online Platforms are gaining share for smaller purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA standards on volatile organic compounds significantly influence product development and market dynamics for concrete bonding agents across North America. Regional demand patterns for these construction materials are shaped by diverse regulatory landscapes and varying infrastructure investment priorities in key economies.
United States
Extensive bridge repair projects and ongoing infrastructure renewal programs drive substantial demand for high-performance bonding agents across the United States. US EPA regulations on VOC emissions compel manufacturers to develop compliant, low-VOC formulations for construction chemicals. Major urban centers like New York City and Los Angeles exhibit high demand for structural strengthening agents in seismic retrofitting and historic building preservation.
India
India's National Infrastructure Pipeline and rapid urbanization programs create sustained demand for versatile acrylic-based bonding agents in new construction and repair. The Bureau of Indian Standards (BIS) establishes quality and performance benchmarks for construction materials, influencing product specifications. Metropolitan areas such as Mumbai and Delhi are experiencing significant growth in commercial and residential building, fueling high-volume procurement.
Germany
Germany's focus on sustainable construction practices and high-quality infrastructure maintenance generates consistent demand for advanced epoxy-based bonding agents. The EU's REACH regulation mandates rigorous testing and registration for chemical substances, ensuring environmental and safety compliance for products sold in the German market. Industrial clusters in Bavaria and North Rhine-Westphalia frequently specify specialized bonding solutions for complex repair and structural upgrades.
China
China's large-scale infrastructure development, including high-speed rail and urban expansion, sustains demand for both structural and general-purpose bonding agents. China's GB standards for building materials enforce strict performance and environmental criteria for chemical admixtures. Major economic zones like the Yangtze River Delta concentrate significant construction activity, requiring diverse bonding solutions for various project types.
Brazil
Major infrastructure projects and a growing industrial construction sector in Brazil are increasing the need for reliable concrete repair and bonding solutions. ANVISA, the national health surveillance agency, regulates chemical products, impacting the formulation and approval of construction chemicals. The metropolitan areas of São Paulo and Rio de Janeiro are focal points for commercial and residential development, driving demand for bonding agents.
Global Concrete Bonding Agents Market Key Industry Players
Vertically integrated chemical giants and specialized construction material manufacturers split the market for concrete bonding agents. The competitive structure features a blend of global players with extensive portfolios and regional specialists focused on niche applications or specific geographies. Dominant competitive moves include strategic acquisitions to expand product lines and continuous investment in advanced polymer chemistry for high-performance solutions.
Global chemical conglomerates, such as Sika AG and BASF SE, leverage their broad research capabilities and extensive distribution networks to capture large-scale infrastructure projects across multiple regions. Mapei S.p.A. occupies a position as a comprehensive solutions provider, offering a wide array of products tailored for both commercial builders and residential developers. These companies frequently differentiate through advanced polymer chemistry, enabling high-performance applications that meet stringent regulatory and technical specifications.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Fosroc International Ltd. |
| Saint-Gobain Weber S.A. |
| Mapei S.p.A. |
| The Euclid Chemical Company |
| LafargeHolcim |
| GCP Applied Technologies Inc. |
| Dow Construction Chemicals |
| Others |
Cost & Logistics Intelligence
Commodity volatility in petrochemical feedstocks like epoxy resins and acrylic monomers directly dictates pricing tier spreads and shapes the supply chain for concrete bonding agents. This sensitivity impacts manufacturer margins and end-user costs across regions.
Pricing Analysis
Geographic price spreads for concrete bonding agents reflect regional regulatory compliance costs and local competitive intensity. The market operates on a tiered pricing structure, differentiating based on performance grade (e.g., structural epoxy versus general-purpose acrylic) and volume scale. Raw material price volatility creates downward pricing pressure, particularly for acrylic-based variants. Residential developers exhibit the highest price sensitivity, while infrastructure developers prioritize performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital across the concrete bonding agents value chain. Supply concentrates in Southeast Asian nations for base chemical production and in Europe for advanced polymer chemistry. The industry relies heavily on petrochemical feedstocks like epoxy resins and acrylic monomers. Divergent regional chemical regulations pose a structural risk, complicating cross-border supply. Distribution runs through a dual model, combining direct sales for large infrastructure projects and extensive distributor networks for general construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete bonding agents market necessitates a robust substitution defense strategy, particularly against advanced polymer-modified cementitious mortars that offer built-in bonding properties. Incumbents must proactively innovate to maintain product relevance and market share.
For Market Incumbents: Build a regulatory compliance moat through continuous investment in low-VOC and bio-based formulations. This mitigates the threat from stringent environmental regulations and emerging substitute materials. Deepen vertical integration into specialized polymer chemistry to control critical raw material quality and cost. Invest in applicator training programs to ensure proper use of high-performance epoxy systems, reducing project failures.
For New Entrants and Emerging Players: Underpenetration in Latin American markets like Brazil and Mexico presents a significant white-space opportunity. Target the growing industrial construction sector with versatile acrylic-based bonding agents for general repair and finishing work. A focused digital marketing strategy, emphasizing ease of use and local availability, can accelerate market entry. Partner with regional distributors to leverage existing networks and technical support capabilities.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized polymer chemistry providers with strong R&D pipelines. Long-term viability for the next decade centers on sustainable formulations and high-performance structural solutions. Acquisition targets should include mid-sized firms possessing proprietary bio-based polymer technologies or strong market positions in seismic retrofitting. The signal to watch is the adoption rate of digital simulation software for material selection in critical infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Reduces logistics costs and enhances supply resilience for high-volume acrylic agents in rapidly urbanizing regions like India. |
| Green Formulation Development | Meets stringent EU REACH and US EPA VOC regulations, appealing to specifiers focused on LEED certification and sustainable construction. |
| Advanced Polymer R&D Investment | Develops next-generation epoxy systems for complex structural strengthening, expanding addressable market in earthquake-prone regions. |
| Applicator Training Programs | Mitigates risk of bond failure for high-performance products, increasing adoption and customer satisfaction among specialty contractors. |
| Strategic Partnerships with Infrastructure Developers | Secures long-term contracts and influences product specifications for large-scale repair and restoration projects, ensuring consistent demand. |
Research Approach
A spread of perspectives from infrastructure developers, specialty contractors, chemical engineers, and construction contractors converged on the working assumptions for the concrete bonding agents market. Primary interviews with industry stakeholders were triangulated with extensive secondary validation. Secondary data sources included EU REACH documents, US EPA reports, Bureau of Indian Standards publications, and construction industry association reports. This approach ensured robust bottom-up and top-down data synthesis.
Demand-supply-balance principles underpinned the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, application, end user, distribution channel, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected infrastructure spending commitments. Urbanization rates in developing economies served as a key forecast input.
Practitioners should monitor raw material price shocks, new building code mandates, and shifts in sustainable construction policies for early signals. Forecasts reflect assumptions regarding infrastructure investment stability and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market