
 Italy Sealants Market | 2026-2036
Italy Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Sealants Market Foresight
The EU Green Deal is restructuring demand patterns across Italy's sealants sector by mandating lower embodied carbon in building envelope materials. MAPEI S.p.A. leverages its vertically integrated manufacturing base in Milan to sustain cost advantages in silicone and polyurethane formulations. Sika AG anchors its position through specialized distribution partnerships with large infrastructure contractors. Henkel AG & Co. KGaA competes on adhesive-sealant hybrid technologies for automotive OEM supply chains.
Italy sealants comprise polymeric compounds—silicone, polyurethane, acrylic, and epoxy formulations—that cure to flexible or rigid bonds, typically achieving elongation at break of 200-800% for construction-grade silicones and tensile strengths of 0.3-1.5 MPa depending on chemistry. Their primary purpose spans waterproofing joints, absorbing structural movement, and providing thermal or acoustic barriers across built assets. Silicone formulations dominate volume in construction applications where weathering resistance and UV stability command premium positioning, while polyurethane growth concentrates in automotive underbody sealing where vibration damping requirements intensify. Epoxy segments occupy narrower industrial maintenance niches characterized by high bond strength and chemical resistance specifications.
Italy's sealants market operates under REACH chemical registration requirements, CE marking for construction products under the Construction Products Regulation, and EU F-Gas Regulation constraints on blowing agents in certain polyurethane systems. BIS standards for imported raw materials and Italy's own UNI technical standards further shape product compliance costs and formulation choices. Stakeholders must monitor evolving EU taxonomy criteria for sustainable construction materials, as green building certification thresholds will progressively filter acceptable chemistries and supplier qualifications.
Market Dynamics
The EU Green Deal's embodied carbon mandates are compressing specification windows for Italian construction materials, forcing reformulation cycles that favor suppliers with captive silicone monomer production.
Growth Catalysts
- REACH-compliant low-VOC silicone:Northern Italian contractors now specify sub-50g/L formulations for commercial envelope retrofits, creating pull-through demand from Lombardy's glazing sector.
- Automotive underbody sealing:Polyurethane foam-in-place systems are capturing share from mechanical gaskets as EV platforms prioritize acoustic dampening and battery pack ingress protection.
- Milan energy-efficiency mandates:The city's 2030 building performance targets require thermal bridge remediation, expanding specification of high-elongation construction sealants in commercial facades.
Market Restraints
- Silicone monomer supply concentration:Italian formulators depend on German and Chinese upstream suppliers, exposing margin compression during feedstock volatility cycles.
- F-Gas Regulation constraints:EU restrictions on HFC blowing agents in certain polyurethane systems force reformulation investments without immediate cost recovery mechanisms.
- Acrylic substitution in interior applications:Lower-cost water-based acrylics are displacing silicone in non-weathering joint sealing, compressing addressable volume in residential finishing.
Strategic Opportunities
- Southern Italy commercial stock:Naples and Bari lag Milan's retrofit penetration, offering whitespace for high-performance envelope systems as EU taxonomy alignment spreads.
- Adhesive-sealant hybrid convergence:Automotive OEMs are consolidating bonding and sealing specifications, rewarding suppliers with dual-chemistry formulation capabilities.
- UNI 11300 certification tailwinds:Italy's national energy performance standard creates specification pull for certified low-thermal-conductivity sealant systems in public procurement.
Industry Challenges
- Formulation chemist scarcity:Italy's specialized polymer science talent pool concentrates in Milan and Turin, constraining R&D expansion for mid-tier competitors.
- CE marking timeline compression:Construction Products Regulation testing protocols for novel bio-based formulations extend commercialization cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Sealants Market |
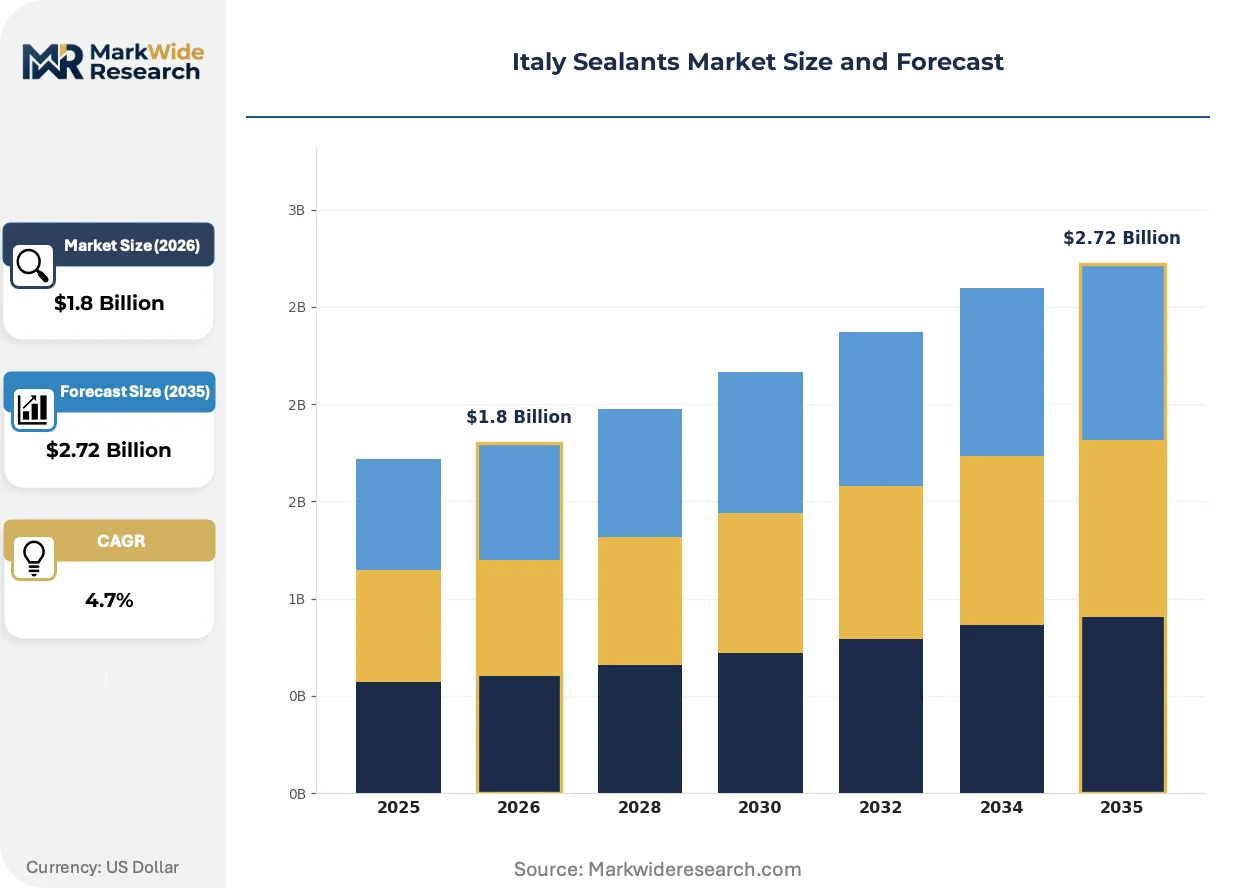
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Epoxy Application: Construction, Automotive, Electronics, Packaging End User: Contractors, Manufacturers, Retailers, Distributors Distribution Channel: Online, Retail Outlets, Wholesalers, Direct Sales |
| Companies Covered | MAPEI S.p.A., Sika AG, Henkel AG & Co. KGaA, 3M, Soudal Holding N.V., Dow, NPT Srl, RPM International Inc., Torggler S.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Sealants Market Shifts & Advancements
Italian sealant producers are converging on chemistry platforms that satisfy multiple performance certifications simultaneously, collapsing the traditional trade-off between weathering resistance and application speed.
Hybrid silicone-polyurethane formulations are unifying the load-bearing capacity of polyurethanes with the UV stability of silicones, enabling single-product specifications for dynamic joints in curtain walling. Lombardy-based glazing contractors have accelerated adoption of these systems for high-rise commercial projects, compressing the historical two-product approach into unified application protocols that reduce labor callbacks.
EU F-Gas Regulation phase-down schedules are forcing polyurethane producers toward hydro-olefin or water-blown alternatives, raising processing complexity for Italian formulators serving automotive underbody applications. The regulation's 2027 step-down targets are accelerating capital deployment into alternative blowing agent infrastructure, with Piedmont-based suppliers front-loading compliance investments to capture stranded competitor volume.
Specification authority is migrating from general contractors to facade engineering consultants, fragmenting procurement decisions across Milan's commercial retrofit pipeline. Engineering-led selection processes prioritize documented elongation performance over brand recognition, compressing historical distributor relationships and rewarding technical documentation capabilities. This shift concentrates specification influence among consultants certified to UNI 11578 facade system standards.
Italy Sealants Market Segmentation
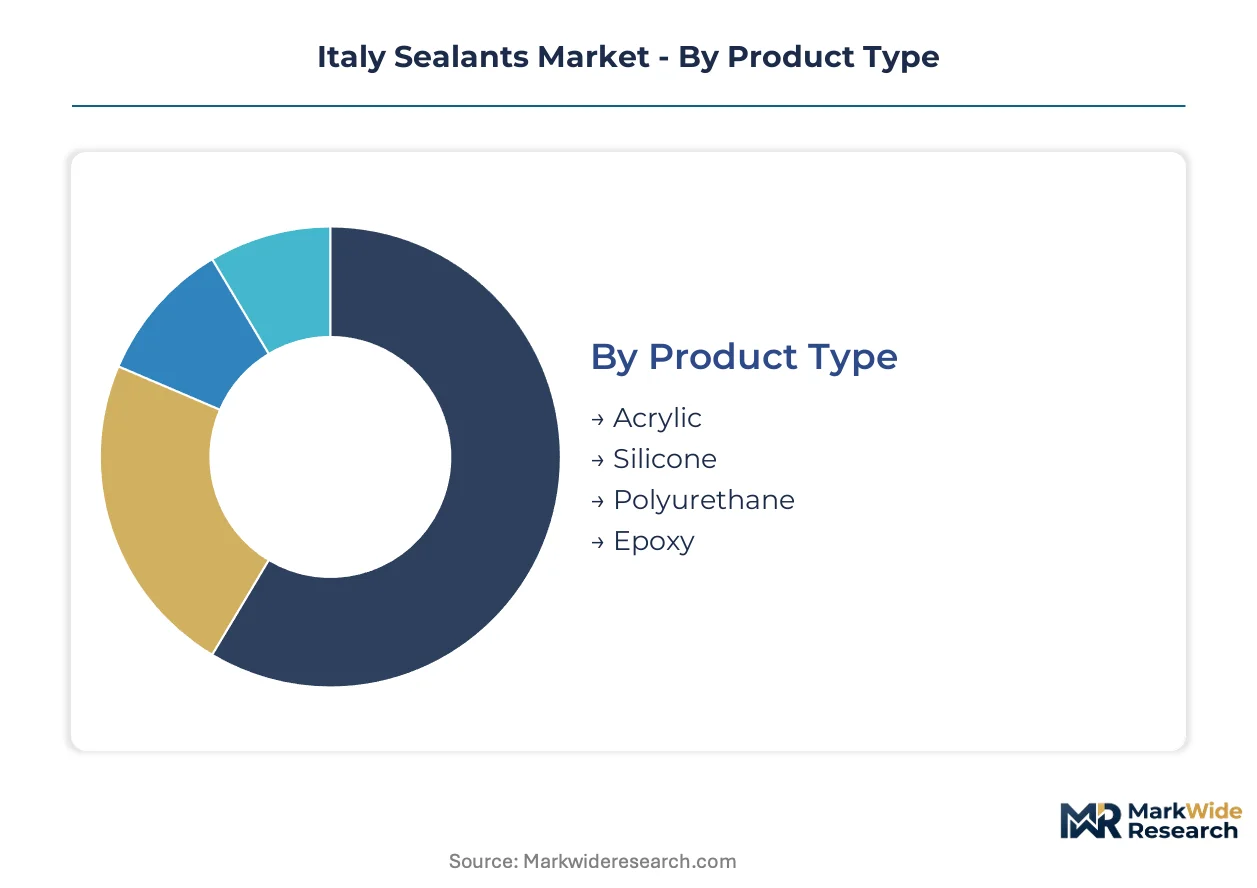
Segmentation in Italy's sealants market reveals how chemistry choices, application requirements, and procurement pathways fragment into distinct competitive arenas. Each dimension carries its own margin structure, compliance burden, and specification authority.
Product Type:
Supply concentration among monomer producers dictates which chemistries Italian formulators can scale economically.
- Silicone:Formulated from siloxane polymers with UV-stable cross-linking, these systems achieve elongation at break exceeding 500% for dynamic building joints. Lombardy's commercial facade retrofits specify high-modulus grades under Milan's energy-efficiency mandates, though dependence on German and Chinese monomer suppliers exposes margin volatility.
- Polyurethane:Isocyanate-cured systems deliver load-bearing capacity and acoustic dampening for automotive underbody sealing. EV platform manufacturers specify foam-in-place formulations for battery pack ingress protection, driving specification upgrades as F-Gas Regulation constraints force blowing agent transitions.
- Acrylic:Water-based emulsions serve interior joint sealing where weathering resistance is unnecessary. Lower material costs displace silicone in residential finishing, compressing addressable volume for premium formulations.
- Epoxy:High-strength thermosets occupy industrial maintenance niches requiring chemical resistance and rigid bond lines. UNI-certified applications in public infrastructure specify these systems for structural anchoring.
Silicone absorbs the bulk of installed capacity; polyurethane is expanding most quickly.
Application:
End-use diversification across sectors fragments specification authority and compliance pathways.
- Construction:Building envelope waterproofing and thermal bridge remediation dominate volume, with Lombardy contractors driving demand for REACH-compliant low-VOC formulations under EU Green Deal mandates.
- Automotive:Underbody sealing and battery pack protection specifications consolidate bonding and sealing functions, rewarding suppliers with hybrid chemistry capabilities as EV platforms proliferate.
- Electronics:Potting and encapsulation applications require precise viscosity control and thermal conductivity, serving industrial equipment manufacturers in Turin and Milan.
- Packaging:Flexible film lamination and carton sealing utilize hot-melt and pressure-sensitive systems, with food-contact compliance under EU framework regulation shaping formulation choices.
Construction commands the largest share of current demand; automotive applications are climbing the fastest.
End User:
Procurement sophistication varies sharply across buyer categories, filtering product positioning and service requirements.
- Contractors:Northern Italian glazing and envelope specialists specify certified systems for commercial retrofits, with UNI 11300 energy performance standards creating procurement filters in public tenders.
- Manufacturers:Automotive OEMs and industrial equipment producers integrate sealants into assembly processes, prioritizing documented elongation performance and batch consistency over distributor relationships.
- Retailers:Hardware and home improvement channels serve residential DIY and small contractor demand, stocking standard-grade acrylics and silicones with compressed margin structures.
- Distributors:Specialized construction chemical distributors maintain technical inventory and application support for mid-tier contractors, though facade engineering consultants are fragmenting their specification influence.
Contractors absorb the bulk of high-performance volume; manufacturers are gaining specification authority fastest.
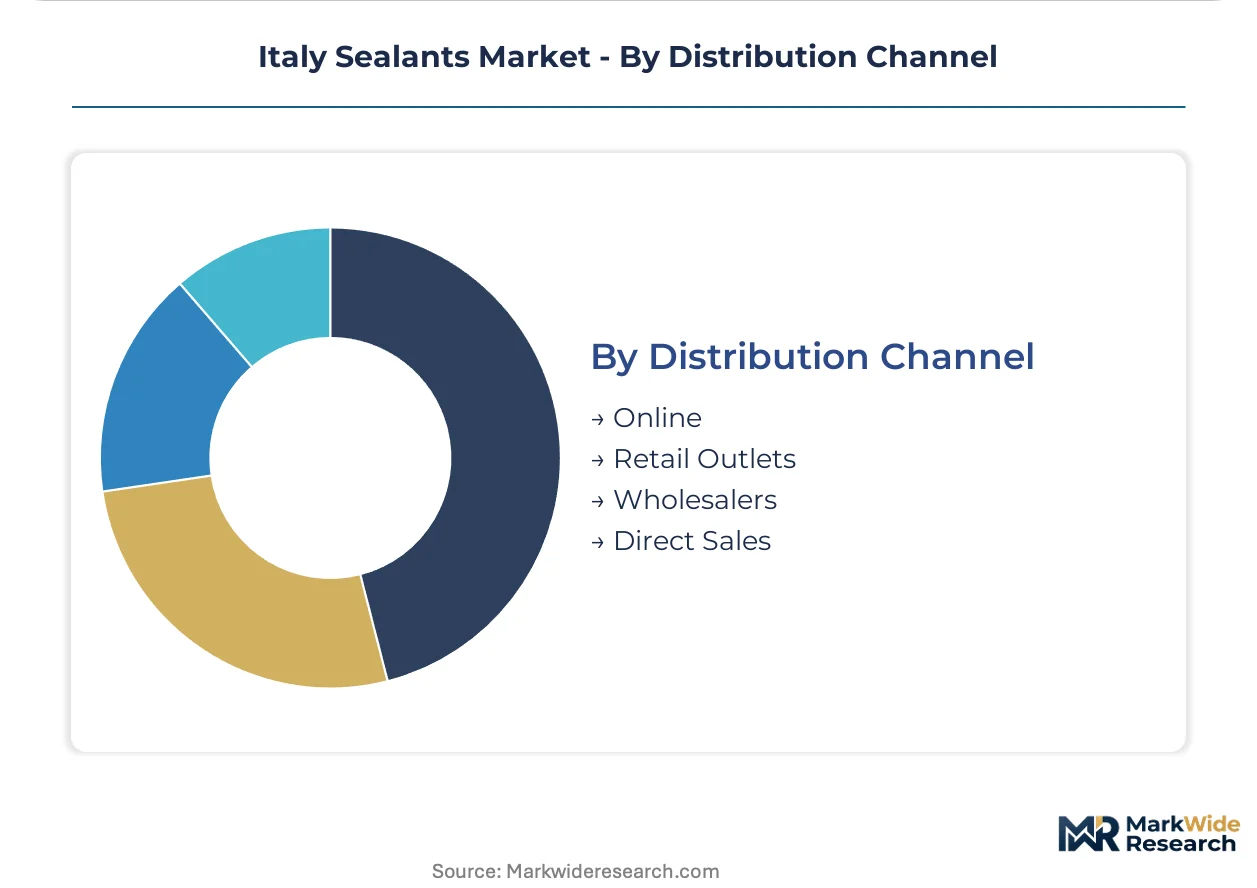
Distribution Channel:
Channel economics reflect the technical complexity of sealant selection and the urgency of construction timelines.
- Online:E-commerce platforms capture standard-grade residential demand, though technical documentation limitations constrain penetration in certified commercial applications.
- Retail Outlets:Physical hardware stores serve emergency procurement and small-project needs, with Lombardy and Veneto chains maintaining regional inventory depth.
- Wholesalers:Construction-focused distributors aggregate volume across multiple brands, offering credit terms and logistics coordination for large contractors.
- Direct Sales:Formulator-owned technical sales forces serve automotive OEMs and major infrastructure contractors, bypassing distributor margins for specification-intensive accounts.
Wholesalers handle the bulk of construction volume; direct sales channels are expanding most quickly in automotive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors Italy's sealants demand through its commercial retrofit pipeline and facade engineering cluster, with procurement patterns radiating outward to adjacent industrial regions.
Lombardy
Milan's 2030 energy-efficiency mandates drive specification of high-elongation silicone formulations for curtain walling retrofits. The EU Green Deal's embodied carbon thresholds filter acceptable chemistries in public tenders. Engineering consultants certified to UNI 11578 standards concentrate specification authority in the Porta Nuova and CityLife districts.
Piedmont
Turin's automotive manufacturing base generates polyurethane foam-in-place demand for EV battery pack ingress protection. F-Gas Regulation phase-down schedules force blowing agent transitions by 2027. Suppliers in the Chivasso industrial corridor front-load compliance investments to capture stranded competitor volume.
Veneto
Padua and Verona glazing contractors specify REACH-compliant low-VOC silicones for commercial envelope projects. The region's logistics infrastructure supports just-in-time delivery to Alpine construction sites. Venetian distributors maintain technical inventory depth for mid-tier contractors bidding on EU taxonomy-aligned developments.
Emilia-Romagna
Bologna's packaging machinery manufacturers integrate hot-melt sealants into automated carton sealing lines. Food-contact compliance under EU framework regulation shapes formulation choices for export-oriented equipment builders. The Modena automotive supply chain pulls adhesive-sealant hybrid specifications from Tier-1 seating and trim suppliers.
Lazio
Rome's public infrastructure procurement applies UNI 11300 energy performance standards to sealant specifications in school and hospital retrofits. Lazio-based contractors lag Lombardy's retrofit penetration, offering whitespace for certified low-thermal-conductivity systems as EU taxonomy alignment spreads southward.
Italy Sealants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth, with chemistry integration capabilities separating tier positions. The vendor base clusters around three strategic archetypes: vertically integrated monomer producers, specialized construction chemical formulators, and adhesive-sealant hybrid technology developers. M&A activity concentrates on captive silicone monomer access, while portfolio diversification targets automotive OEM consolidation of bonding and sealing specifications.
Within the construction chemical tier, MAPEI S.p.A. and Sika AG occupy positions anchored by Milan-based manufacturing infrastructure and specialized distribution partnerships respectively. Henkel AG & Co. KGaA represents the adhesive-sealant hybrid archetype, serving automotive supply chain consolidation trends. These three entities exemplify how geographic proximity to Lombardy's specification authority and chemistry breadth determine competitive positioning in Italy's procurement landscape.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| Sika AG |
| Henkel AG & Co. KGaA |
| 3M |
| Soudal Holding N.V. |
| Dow |
| NPT Srl |
| RPM International Inc. |
| Torggler S.r.l. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between UNI 11300-certified systems and standard-grade alternatives manifests in both margin capture and upstream sourcing configurations. Premium formulations command value-based positioning through documented elongation performance, while commodity tiers compete on monomer cost pass-through efficiency.
Pricing Analysis
Outcome-based pricing anchors the Italian sealants market, with facade engineering consultants specifying systems based on documented thermal bridge remediation performance. Three-tier pricing structure across certified premium, standard construction-grade, and economy interior tiers differentiates by UNI compliance depth and monomer purity grades. Cost compression in standard-grade silicone intensifies as German and Chinese monomer suppliers exert feedstock leverage. Retail DIY channels exhibit highest price sensitivity; automotive OEMs demonstrate lowest sensitivity due to battery pack ingress protection requirements.
Supply Chain Analysis
Dual-sourcing requirements from Milan-based facade engineering consultants mandate qualified backup suppliers for critical envelope projects. Italian formulators draw from German, Chinese, and domestic monomer production for siloxane polymers, while isocyanate feedstocks for polyurethane systems rest on Belgian and Dutch chemical complexes. Single-source vulnerability concentrates in specialty blowing agents facing F-Gas Regulation phase-down constraints. Distribution runs through construction-focused wholesalers with technical inventory depth, though direct sales channels expand fastest in automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian sealants operate as a supply-constrained market where captive silicone monomer access props pricing power for integrated formulators.
For Market Incumbents: Acquire captive monomer production capacity or offtake agreements with German suppliers to defend margin position against feedstock volatility. Secure UNI 11578 consultant certification programs to lock specification authority as engineering-led procurement fragments distributor relationships.
For New Entrants and Emerging Players: Begin with adhesive-sealant hybrid formulations targeting Turin automotive Tier-1 suppliers consolidating bonding and sealing specifications. Southern Italy commercial retrofit whitespace in Naples and Bari offers lowest competitive density for certified low-VOC systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to construction chemical majors seeking Lombardy manufacturing footprint. Five-to-ten year viability favors formulators with backward integration into monomer supply or dual-chemistry R&D capabilities. Monitor F-Gas Regulation 2027 compliance timelines as inflection indicator for stranded competitor volume capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive siloxane production insulates MAPEI from German supplier price volatility. |
| UNI 11300 Certification Program | Certified low-thermal-conductivity systems unlock public procurement in Rome infrastructure. |
| Hybrid Chemistry R&D Investment | Silicone-polyurethane unification captures curtain walling retrofit demand from Milan consultants. |
| Alternative Blowing Agent Transition | Hydro-olefin conversion ahead of F-Gas 2027 targets captures stranded Piedmont competitor volume. |
| Southern Italy Distribution Partnership | Technical inventory depth in Naples addresses EU taxonomy alignment spreading southward. |
Research Methodology
Multi-period observation of Milan energy-efficiency mandate compliance rates and Lombardy commercial retrofit permitting volumes anchored the trend analysis, supplemented by interviews with facade engineering consultants, construction chemical procurement leads at major contractors, automotive Tier-1 supplier quality directors, and specialized distributor technical sales managers. Secondary validation drew from REACH registration databases, UNI technical standard publications, EU Construction Products Regulation guidance documents, and Italian customs trade flow records. Bottom-up project pipeline enumeration triangulated against top-down chemical industry association consumption estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework across the analysis window. Chemistry-specific elongation performance tiers, certification depth levels, and regional procurement sophistication gradients informed volume allocation. CAGRs derived from regression against historical retrofit penetration curves and automotive EV platform rollout schedules, with sensitivity testing against monomer price volatility scenarios and regulatory compliance timeline shifts.
Underlying measurement precision varies by segment; construction-grade silicone volumes carry tighter precision than emerging adhesive-sealant hybrid categories due to established UNI reporting requirements. Forecasts reflect assumptions on EU Green Deal implementation pace and F-Gas Regulation enforcement consistency. Deviation in German monomer supply availability or Milan retrofit subsidy continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Leather Glue Market