
 Water-Borne Latex Paints Market | 2026-2036
Water-Borne Latex Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Latex Paints Market Outlook
Water-borne latex formulation chemistry is fragmenting as manufacturers replace traditional acrylic binders with hybrid polyurethane-acrylic systems to meet stricter volatile organic compound ceilings. BASF SE leverages its polymer dispersion portfolio to anchor supply relationships with large European decorators. PPG Industries Inc competes through controlled distribution networks in North American home improvement retail. Asian Paints Limited dominates India's water-borne interior segment through localized shade-matching infrastructure.
Water-borne latex paints are aqueous coating systems where synthetic polymer particles, primarily acrylic or vinyl acetate copolymers, are dispersed in water with pigment and additives, curing through coalescence as water evaporates to form a continuous protective film at temperatures above 5°C. Interior Paints generate the largest revenue pool due to shorter repaint cycles in residential stock, while Specialty Paints targeting antimicrobial and self-cleaning substrates capture the fastest expansion as healthcare and food-processing facilities upgrade hygiene protocols. The Automotive application remains comparatively underdeveloped for water-borne latex, with solvent-borne systems still controlling OEM clear-coat specifications.
The EPA regulates architectural coating VOC content under 40 CFR Part 59, forcing reformulation away from residual solvent carriers, while REACH restricts specific coalescing aids and biocides in European formulations. China's MEE enforces GB standards for indoor air quality that cascade into paint procurement specifications for public buildings. Stakeholders must monitor divergence between regional chemical restriction lists when designing unified product platforms.
Market Dynamics
Hybrid polyurethane-acrylic binder systems are forcing wholesale reformulation across the water-borne latex paints sector as manufacturers race to meet tightening VOC ceilings in multiple jurisdictions simultaneously.
Growth Catalysts
- EPA 40 CFR Part 59:Low-VOC mandates in the United States compel architectural coating reformulation, accelerating water-borne latex substitution for solvent-borne alkyd systems in residential repaint.
- Antimicrobial specialty substrates:Healthcare and food-processing facilities upgrade hygiene protocols, driving demand for functionalized interior paints with certified pathogen resistance.
- China's tier-one cities:Green building code tightening in Beijing, Shanghai, and Shenzhen redirects public procurement toward certified low-emission coating systems.
Market Restraints
- Titanium dioxide supply concentration:Pigment feedstock availability fluctuates with Chinese export quotas, compressing margin stability for mid-tier formulators.
- Cold-climate curing limitation:Water-borne latex film formation requires temperatures above 5°C, excluding unheated construction sites in northern climates during winter months.
- Solvent-borne OEM clear-coats:Automotive finishing specifications retain solvent systems for gloss retention and chemical resistance, blocking water-borne penetration in this high-value segment.
Strategic Opportunities
- India's interior segment:Localized shade-matching infrastructure investments open pathways for premium water-borne latex expansion in tier-two and tier-three urban clusters.
- Self-cleaning photocatalytic technology:Titanium dioxide nanomaterial integration with standard acrylic dispersions creates differentiated exterior facade offerings for commercial real estate.
- EU Green Deal renovation wave:Building energy retrofit mandates cascade into repaint volume acceleration across residential and commercial building stocks.
Industry Challenges
- Coalescing aid substitution:REACH-restricted glycol ether replacements require R&D timeline extension and performance validation cycles before commercial rollout.
- Biocide-free preservation:Eliminating isothiazolinone biocides demands packaging and supply chain reconfiguration to prevent in-can microbial contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Latex Paints Market |
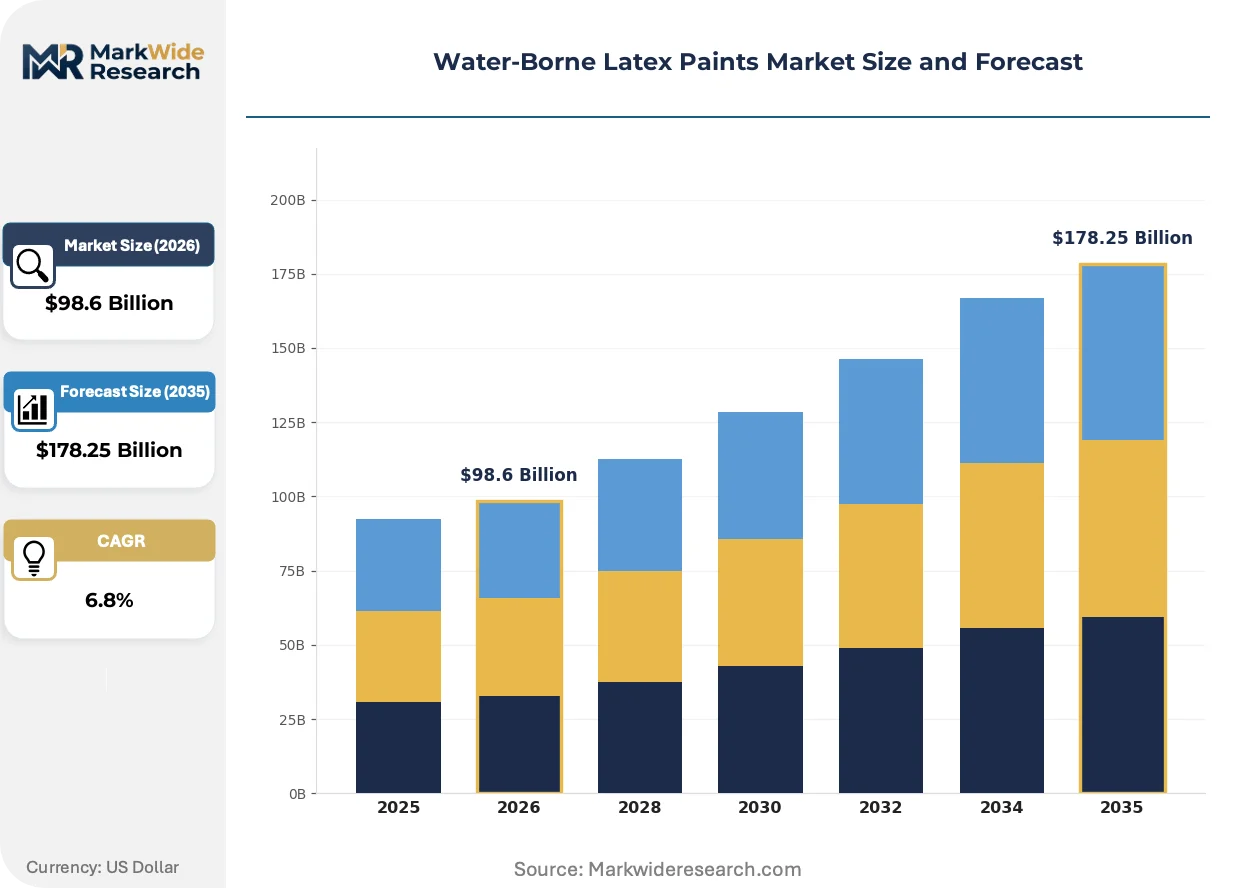
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paints, Exterior Paints, Specialty Paints, Primers Application: Residential, Commercial, Industrial, Automotive Packaging Type: Cans, Buckets, Pails, Drums End User: Contractors, DIY Enthusiasts, Manufacturers, Retailers |
| Companies Covered | AkzoNobel N.V, BASF SE, PPG Industries Inc, The Sherwin-Williams Company, Arkema Group, Nippon Paint Holdings Co. Ltd, Asian Paints Limited, RPM International Inc, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Latex Paints Market Strategic Shifts
Digital color-matching platforms and on-demand tinting systems are compressing traditional distribution hierarchies while enabling mass customization at point-of-sale across retail and professional channels.
Hybrid polyurethane-acrylic dispersion chemistry is virtualizing the performance gap between water-borne latex and solvent-borne coatings. Industrial maintenance contractors in marine and infrastructure sectors now specify these systems for corrosion protection previously reserved for epoxy-urethane solvent platforms. The technology is virtualizing application constraints that historically segmented the protective coatings market by substrate complexity.
REACH authorization requirements for specific coalescing aids and biocides are forcing molecular redesign of European formulations. ECHA's candidate list expansion triggers supply chain audits and alternative substance qualification timelines. Decorative paint manufacturers serving the German and French markets now maintain parallel formulation portfolios to manage regulatory divergence.
Professional painting contractors are consolidating purchasing through integrated supply platforms that bundle coating procurement with application equipment and training certification. Large facility maintenance departments in US commercial real estate now contract directly with manufacturer-certified applicator networks, bypassing traditional distributor intermediaries. This channel restructuring concentrates volume with formulators maintaining captive certification programs.
Water-Borne Latex Paints Market Segmentation
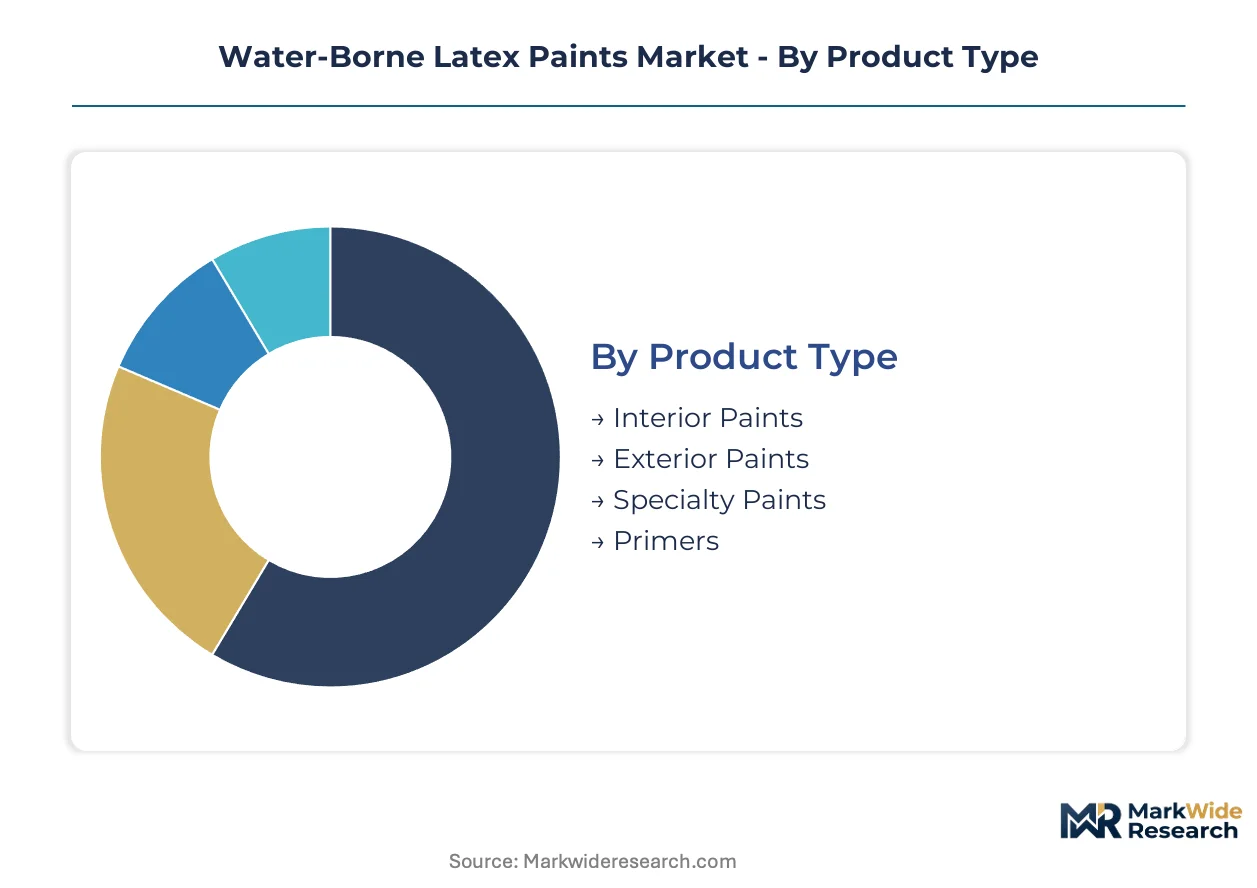
Segmentation in water-borne latex paints reveals distinct service intensity profiles across product tiers. Interior and specialty formulations demand intensive shade-matching support and applicator training, while bulk exterior and primer categories operate through self-service retail channels with minimal technical assistance.
Product Type:
After-sales-service intensity varies sharply across this category, with premium interior lines requiring dedicated color consultancy while commodity primers flow through cash-and-carry distribution.
- Interior Paints:Acrylic and vinyl acetate copolymer dispersions formulated for residential wall and ceiling applications. Demand concentrates in China's tier-one cities where green building codes tighten fastest, driven by shorter repaint cycles in high-turnover residential stock.
- Specialty Paints:Functionalized formulations incorporating antimicrobial additives or photocatalytic titanium dioxide nanomaterials. Healthcare and food-processing facilities in Southeast Asia upgrade hygiene protocols, accelerating certified pathogen-resistant system procurement.
- Exterior Paints:Weather-resistant acrylic dispersions with enhanced UV stability for facade protection.
- Primers:Sealer formulations preparing substrates for topcoat adhesion in new construction and renovation.
Interior Paints holds the largest share; momentum sits with Specialty Paints.
Application:
Cost tier differentiation separates specification-driven professional segments from price-sensitive consumer markets across residential, commercial, and industrial end-uses.
- Residential:Interior and exterior coating systems for single-family homes, apartments, and multi-unit dwellings. Volume expansion in Southeast Asian construction markets drives formulation localization, with Indonesian and Vietnamese developers specifying low-VOC systems for new stock.
- Commercial:Office, retail, and hospitality interior finishes requiring rapid return-to-service properties. Facility maintenance departments in US commercial real estate now contract directly with manufacturer-certified applicator networks, bypassing traditional distributor intermediaries.
- Industrial:Protective coatings for manufacturing facilities, warehouses, and infrastructure assets.
- Automotive:OEM and refinishing applications where water-borne penetration remains limited by solvent-borne clear-coat specifications.
Residential commands the dominant volume position; Commercial climbs the fastest on retrofit acceleration.
Packaging Type:
Volume scale determines logistics configuration, with retail cans serving fragmented DIY demand and bulk drums capturing concentrated contractor procurement.
- Cans:Standard 1-liter and 4-liter metal containers for retail shelf presence and homeowner purchase.
- Buckets:10-20 liter plastic pails for professional contractor jobsites.
- Pails:Intermediate 5-10 liter containers bridging retail and trade channels.
- Drums:200-liter bulk packaging for large-scale commercial and industrial projects with direct manufacturer delivery.
Cans generate the highest unit volume; Drums deliver the steepest expansion trajectory on professional channel consolidation.
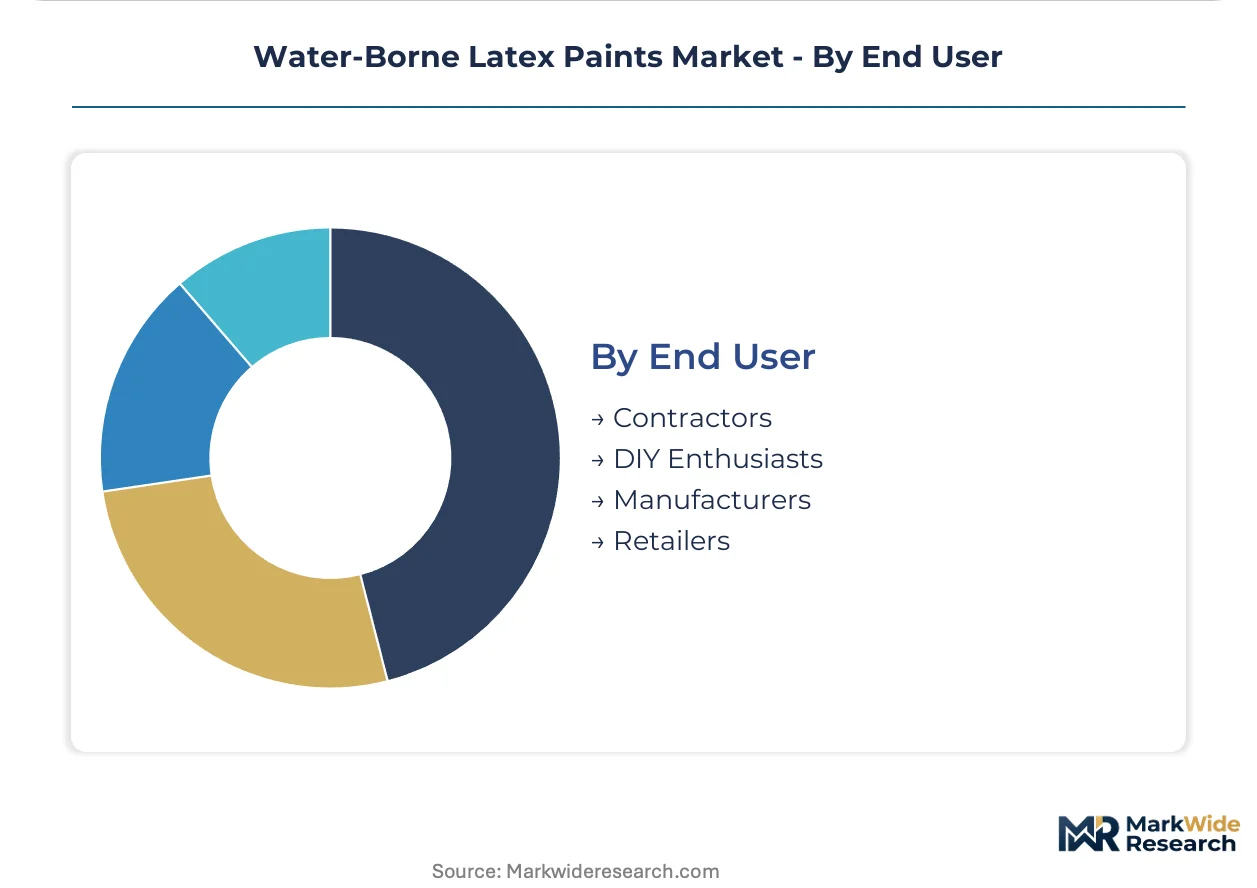
End User:
Customer type segmentation aligns procurement behavior with technical support requirements, from specification-influencing contractors to price-comparison DIY purchasers.
- Contractors:Professional painting firms and facility maintenance crews purchasing through integrated supply platforms. Large European decorators anchor supply relationships with polymer dispersion manufacturers, consolidating volume through bundled equipment and certification programs.
- DIY Enthusiasts:Homeowner consumers selecting pre-tinted or point-of-sale customized products. Digital color-matching platforms and on-demand tinting systems compress traditional distribution hierarchies while enabling mass customization at retail.
- Manufacturers:Industrial finishers and OEM coating applicators with specification authority.
- Retailers:Home improvement chains and independent paint stores curating assortments for local market conditions.
Contractors represent the largest revenue pool; DIY Enthusiasts gain share fastest on platform-enabled customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional contractors and facility maintenance departments concentrate procurement in urban construction corridors where green building codes and low-VOC mandates reshape formulation demand. Regional divergence in chemical restrictions forces parallel product portfolios across major markets.
United States
Residential repaint volume concentrates in Sun Belt metropolitan areas with shorter construction seasons. EPA 40 CFR Part 59 mandates accelerate water-borne latex substitution for solvent-borne alkyd systems in architectural coatings. Facility maintenance departments in US commercial real estate contract directly with manufacturer-certified applicator networks, bypassing traditional distributor intermediaries.
China
Tier-one cities Beijing, Shanghai, and Shenzhen drive specification-grade interior paint procurement as green building codes tighten fastest. MEE enforces GB standards for indoor air quality that cascade into paint procurement specifications for public buildings. Yangtze River Delta manufacturing clusters localize formulation production for Southeast Asian export markets.
Germany
Large European decorators anchor supply relationships with polymer dispersion manufacturers through bundled equipment and certification programs. REACH authorization requirements for specific coalescing aids and biocides force molecular redesign of formulations. ECHA's candidate list expansion triggers supply chain audits and alternative substance qualification timelines across German and French markets.
India
Localized shade-matching infrastructure investments open pathways for premium water-borne latex expansion in tier-two and tier-three urban clusters. BIS standards for architectural coatings create compliance benchmarks for domestic and imported formulations. Maharashtra and Gujarat industrial corridors concentrate manufacturing capacity serving interior segment demand acceleration.
Indonesia
Residential construction volume expansion drives formulation localization for new stock development. Developers specify low-VOC systems for multi-unit dwellings in Jakarta and Surabaya metropolitan areas. Southeast Asian construction markets redirect procurement toward certified low-emission coating systems as regional building codes harmonize.
Water-Borne Latex Paints Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive polymer dispersion portfolios, regional coating specialists with localized shade-matching infrastructure, and automotive-industrial crossover players with specification-grade technology. Dominant competitive moves include geographic expansion through distribution network acquisition and portfolio diversification into antimicrobial and self-cleaning functionalized formulations.
Within the integrated chemical tier, BASF SE and Arkema Group represent archetypes of polymer dispersion manufacturers anchoring supply relationships through bundled equipment programs. PPG Industries Inc occupies a position among North American channel-controlling players competing through controlled distribution networks in home improvement retail. Asian Paints Limited exemplifies regional specialists dominating interior segments through infrastructure investments in tier-two and tier-three urban clusters.
| Leading Market Players |
|---|
| AkzoNobel N.V |
| BASF SE |
| PPG Industries Inc |
| The Sherwin-Williams Company |
| Arkema Group |
| Nippon Paint Holdings Co. Ltd |
| Asian Paints Limited |
| RPM International Inc |
| Axalta Coating Systems |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's titanium dioxide pigment sector compresses margin stability for mid-tier formulators while simultaneously anchoring raw material indexation clauses in long-term supply agreements. This utilization dynamic forces suppliers toward volume-based pricing postures and buyers toward consolidated procurement platforms that extract scale discounts.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate procurement between large European decorators and polymer dispersion manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC formulations from commodity interior lines and contractor-grade bulk primers. Pricing pressure stems from REACH-mandated coalescing aid substitutions that extend R&D validation timelines before commercial rollout. DIY enthusiasts exhibit highest price sensitivity through retail channel price comparison, while facility maintenance departments in US commercial real estate prioritize certified applicator networks over unit cost.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian construction markets dominates supply chain risk assessment for water-borne latex formulators. Manufacturing concentrates in China's Yangtze River Delta, Germany's industrial corridors, and India's Maharashtra-Gujarat belt. Raw material dependencies center on titanium dioxide pigment, acrylic monomer feedstocks, and polyurethane prepolymer intermediates. Single-source vulnerability persists for photocatalytic titanium dioxide nanomaterials used in self-cleaning specialty formulations. Distribution runs through integrated supply platforms bundling coating procurement with application equipment and training certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital color-matching platforms and on-demand tinting systems are compressing traditional distribution hierarchies, creating platform-economics inflection points where interoperability between manufacturer tinting databases and retail point-of-sale systems determines market access.
For Market Incumbents: Harden supply relationships with large European decorators through bundled equipment programs that anchor polymer dispersion offtake against emerging hybrid polyurethane-acrylic specialists. Deepen backward integration into titanium dioxide sourcing to defend margin position against Chinese export quota volatility. Prioritize certification investments for antimicrobial and self-cleaning formulations ahead of healthcare facility upgrade cycles. For New Entrants and Emerging Players: Build out localized shade-matching infrastructure in India's tier-two and tier-three urban clusters where Asian Paints Limited's density advantages thin. Target Indonesia's residential construction volume expansion with low-VOC formulation platforms specified by Jakarta and Surabaya developers. Pursue direct contracting relationships with facility maintenance departments in US commercial real estate that bypass traditional distributor intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid polyurethane-acrylic binder R&D and REACH-compliant coalescing aid qualification timelines. Long-term viability favors formulators with parallel formulation portfolios managing regulatory divergence between European and Asian chemical restriction lists. Acquisition target archetype: regional specialists with captive certification programs and integrated supply platform relationships. Monitor ECHA candidate list expansion velocity as inflection indicator for alternative substance qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Captive pigment supply insulates margin stability against Chinese export quota fluctuations. |
| Hybrid Polyurethane-Acrylic R&D Scale-Up | Virtualizes performance gap with solvent-borne coatings in marine and infrastructure corrosion protection. |
| Certified Applicator Network Expansion | Captures professional contractor volume consolidating through integrated supply platforms in US commercial real estate. |
| Photocatalytic Nanomaterial Integration | Creates differentiated exterior facade offerings for commercial real estate self-cleaning specifications. |
| Parallel Formulation Portfolio Maintenance | Manages regulatory divergence between REACH-restricted European and GB-standard Chinese chemical lists. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports across the water-borne latex paints sector. Primary interviews engaged plant managers at polymer dispersion facilities, procurement leads at downstream OEM coating operations, distribution channel partners in home improvement retail, and technical R&D directors managing REACH-compliant formulation redesign. Bottom-up volume estimates derived from tinting system deployment rates and top-down validation against architectural coating consumption statistics ensured cross-method consistency.
Forecast inputs include raw material price trajectory assumptions, regulatory timeline projections for coalescing aid substitutions, and construction sector capacity utilization across residential and commercial end-uses. Segmentation dimensions modeled encompass product type tier, application end-use, packaging format scale, and regional regulatory cluster. CAGRs were derived from slope analysis of historical volume trends adjusted for green building code adoption curves and low-VOC mandate enforcement schedules.
Stress conditions across titanium dioxide supply disruption, REACH authorization timeline extension, and Southeast Asian construction demand deceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hybrid binder technology adoption rates and biocide-free preservation system commercialization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Primer Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Bio-Based and Low VOC Paints Market