
 Malaysia Adhesives Market | 2026-2036
Malaysia Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Adhesives Market Foresight
Asset-light contract manufacturing arrangements are proliferating among mid-sized Malaysian adhesive distributors, which is reconfiguring capital requirements for market entry and eroding traditional inventory-heavy business models. Henkel AG & Co. KGaA leverages its global formulation libraries to anchor premium water-based lines in Penang's electronics belt. 3M sustains technology leadership through specialized structural bonding solutions for automotive lightweighting programs. Sika AG dominates construction-grade polyurethane segments through direct contractor relationships and on-site technical service teams.
Adhesives are non-metallic substances applied to surfaces that bond materials through mechanical interlocking, chemical reaction, or physical curing, typically achieving shear strengths from 0.1 to 40 MPa depending on resin chemistry and substrate preparation. Their primary industrial purpose is to replace mechanical fasteners, reduce assembly weight, and enable joining of dissimilar materials in manufacturing workflows. Water-based technology leads volume in Malaysia due to regulatory pressure on solvent emissions, yet reactive systems capture disproportionate margin pools in electronics and medical device applications. Polyurethane products are expanding fastest in construction and automotive assembly, where gap-filling properties and environmental resistance justify premium positioning over PVA alternatives.
The Department of Environment enforces Environmental Quality Regulations that restrict solvent content in industrial coatings and adhesives, compelling reformulation investments and reshaping raw material sourcing toward bio-based feedstocks. BIS-equivalent product certification through SIRIM QAS International governs construction adhesive acceptance for government infrastructure contracts, creating a compliance threshold that filters non-certified imports. The Ministry of International Trade and Industry coordinates PLI-aligned incentives for domestic chemical specialty manufacturing, indirectly subsidizing local adhesive blending capacity expansion. Stakeholders must monitor how impending carbon border adjustments in key export destinations reshape the cost calculus of Malaysia-based adhesive production versus regional competitors.
Market Dynamics
Water-based adhesive reformulation is compressing solvent-dependent capacity while electronics miniaturization in Penang and Selangor pulls specialty reactive systems into premium procurement cycles.
Growth Catalysts
- Department of Environment VOC limits:Regulatory pressure on solvent emissions accelerates water-based technology adoption across packaging converters in the Klang Valley industrial corridor.
- Electronics miniaturization:Penang's semiconductor assembly operations demand high-precision underfill and die-attach adhesives for component shrinking.
- SIRIM QAS certification mandates:Government infrastructure contracts require BIS-equivalent product validation, filtering substandard imports and elevating compliant domestic blenders.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with regional naphtha pricing, squeezing margin predictability for formulators serving construction and automotive tiers.
- Singapore-sourced specialty monomer concentration:Malaysia's reliance on cross-border supply for high-purity acrylates and isocyanates exposes blenders to port congestion and customs friction.
- Hot-melt substitution in corrugated packaging:EVA-based hot-melt systems displace water-based alternatives in high-speed box sealing applications where instant bond strength outweighs sustainability positioning.
Strategic Opportunities
- Johor Bahru logistics corridor:Proximity to Singapore's biotech and medical device manufacturing creates demand for ISO 10993-compliant medical-grade adhesives currently underpenetrated versus electronics and construction.
- PLI-aligned domestic blending incentives:Ministry of International Trade and Industry production-linked subsidies reduce capital recovery periods for specialty chemical manufacturing capacity.
- Bio-based feedstock convergence:Palm oil derivative chemistry intersects with water-based polyurethane development, offering Malaysia-origin formulators distinct feedstock access versus regional competitors.
Industry Challenges
- Formulation chemist scarcity:Local universities produce insufficient polymer science graduates with industrial adhesive compounding experience, forcing employers to recruit from Thailand and Singapore.
- SIRIM certification timeline compression:Government contract bidding windows often exceed product testing and validation cycles, disadvantaging smaller blenders against established certificate holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Adhesives Market |
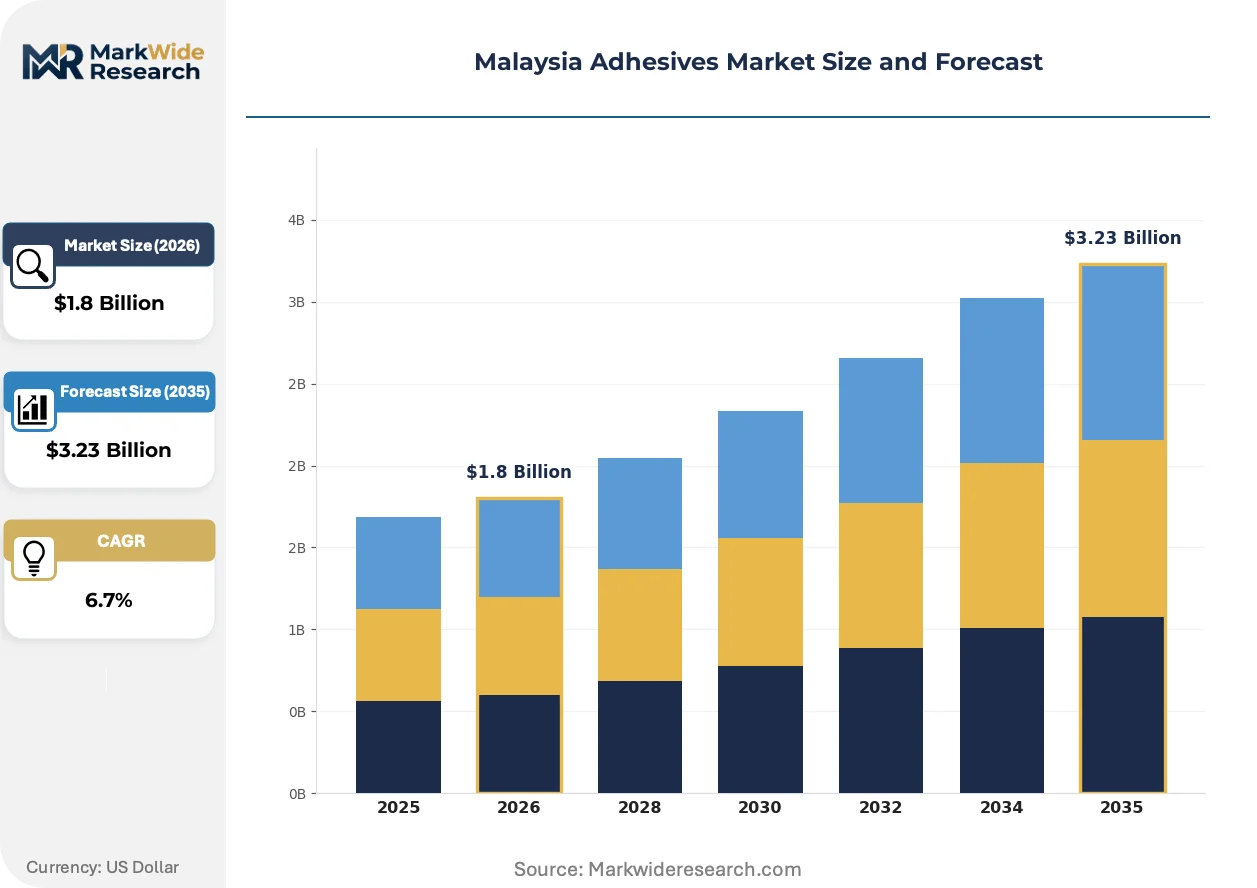
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVA, Epoxy, Polyurethane, Silicone Application: Construction, Automotive, Electronics, Packaging Technology: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Manufacturers, Contractors, Retailers, Hobbyists |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, H.B. Fuller Company, Arkema Group, Mohm Chemical Sdn. Bhd., AICA Adtek Sdn. Bhd., Vital Technical Sdn Bhd, Bostik, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Adhesives Market Shifts & Advancements
Digital twin-enabled formulation development is collapsing R&D cycle times while regulatory chemistry restrictions and buyer procurement centralization simultaneously reshape competitive requirements.
UV-LED curable adhesive platforms is virtualizing traditional thermal curing infrastructure in Penang electronics assembly. Smartphone and wearable manufacturers accelerate adoption for temperature-sensitive component bonding. The technology compresses line footprint requirements and eliminates oven energy consumption, enabling cleanroom layout reconfiguration that thermal systems cannot accommodate.
REACH-aligned substance restrictions are propagating through Malaysia's export-oriented supply chains even without direct EU jurisdiction. Electronics assemblers serving European OEMs preemptively exclude SVHC-candidate chemistries from approved vendor lists. This regulatory shadowing forces domestic formulators to maintain dual product portfolios: REACH-compliant for export accounts and cost-optimized for domestic-only business.
Consolidated procurement through regional category managers is displacing plant-level adhesive sourcing autonomy. Automotive tier-one suppliers in Selangor now mandate global contract pricing with local logistics fulfillment, compressing distributor margins and favoring blenders with direct multinational relationships. The shift is most visible in body-in-white structural bonding programs where volume concentration justifies dedicated technical service staffing.
Malaysia Adhesives Market Segmentation
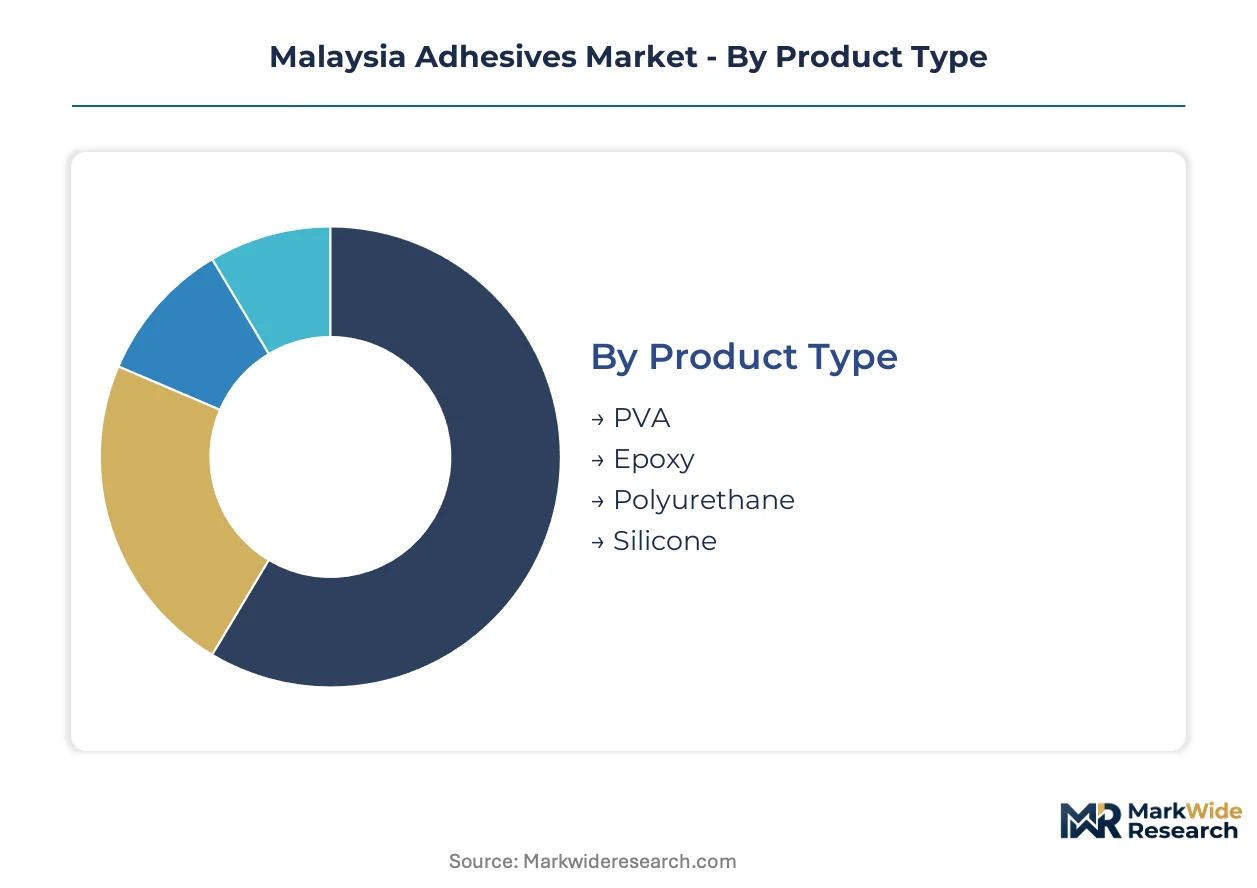
Segmentation in Malaysia's adhesives market reveals how formulation chemistry, application intensity, and technical service requirements concentrate margin pools. Procurement patterns diverge sharply between commodity packaging buyers and electronics assemblers demanding precision bonding with on-site engineering support.
Product Type:
After-sales-service intensity varies dramatically across resin chemistries, with structural systems demanding formulation troubleshooting while commodity grades operate on transactional replenishment.
- Polyurethane:Two-component systems cure through isocyanate-hydroxyl reaction, delivering gap-filling capability and environmental resistance. Construction contractors in Selangor's industrial corridor specify these for structural glazing and panel bonding where on-site viscosity adjustment prevents application failures. The chemistry commands premium positioning over alternatives due to cure-time customization and substrate versatility.
- Epoxy:Thermosetting resins achieve high shear strength through cationic or amine curing mechanisms. Electronics manufacturers in Penang utilize low-shrinkage grades for die-attach and underfill applications where thermal cycling resistance determines component reliability. Technical service teams from major suppliers maintain permanent presence at key semiconductor assembly sites.
- PVA:Polyvinyl acetate emulsions serve woodworking and paper packaging applications with minimal technical support requirements.
- Silicone:Room-temperature-vulcanizing systems dominate weathersealing and high-temperature gasketing where flexibility retention matters.
Polyurethane holds the largest share; momentum sits with epoxy as miniaturization accelerates.
Application:
Cost tier stratification separates specification-driven procurement from price-sensitive spot buying across Malaysia's industrial base.
- Electronics:Miniaturized component assembly in Penang and the Klang Valley demands sub-micron precision dispensing with thermal management properties. Smartphone and wearable manufacturers specify underfill adhesives for flip-chip protection, while die-attach materials must survive lead-free solder reflow temperatures. SIRIM QAS certification requirements filter suppliers capable of supporting export-oriented production.
- Construction:Infrastructure and commercial building applications span structural glazing, flooring installation, and waterproofing membranes. Direct contractor relationships determine specification authority, with Sika AG and similar suppliers embedding technical teams at major project sites to ensure proper substrate preparation and cure monitoring.
- Automotive:Body-in-white structural bonding and interior trim attachment in Selangor's tier-one supplier cluster.
- Packaging:Corrugated box sealing and flexible lamination where water-based systems face hot-melt substitution pressure.
Construction captures the greatest volume; electronics climbs the fastest on value-per-kilogram metrics.
Technology:
Volume concentration favors water-based platforms, yet margin accrues to reactive systems serving precision manufacturing.
- Water-Based:Acrylic and PVA emulsions dominate packaging and woodworking applications through low-cost, low-VOC positioning. Department of Environment regulations on solvent emissions have compressed solvent-dependent capacity, accelerating reformulation investment among domestic blenders. The technology leads procurement tonnage but faces margin pressure from hot-melt substitution in high-speed corrugated lines.
- Reactive:Epoxy, polyurethane, and cyanoacrylate systems cure through chemical reaction rather than solvent evaporation. Medical device manufacturers in Johor Bahru's logistics corridor specify ISO 10993-compliant grades where biocompatibility testing creates qualification barriers for new entrants. UV-LED curable variants are displacing thermal curing in Penang electronics cleanrooms.
- Solvent-Based:Declining share under regulatory pressure, retained only where rapid tack development or specific substrate compatibility demands organic carrier systems.
- Hot Melt:EVA and polyolefin systems deliver instant bond strength for high-speed packaging automation.
Water-based technology commands broadest adoption; reactive systems gain share fastest in premium applications.
End User:
Customer type determines channel structure, with manufacturers demanding direct technical partnership while retailers and hobbyists flow through distribution.
- Manufacturers:Electronics assemblers, automotive tier-ones, and packaging converters purchase through annual contracts with technical service riders. Henkel AG and 3M maintain direct sales organizations serving Penang semiconductor fabs and Selangor automotive clusters, embedding application engineers at customer sites. Consolidated procurement through regional category managers is compressing distributor margins.
- Contractors:Construction applicators specify products for structural glazing and flooring installation where warranty support and on-site troubleshooting determine supplier selection.
- Retailers:Hardware stores and building material distributors serve maintenance-repair-operations demand with limited technical content.
- Hobbyists:Consumer craft and DIY segments represent minimal volume with commodity positioning.
Manufacturers represent the dominant value pool; contractor specification authority is expanding with infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Ministry of International Trade and Industry coordinates PLI-aligned incentives for domestic chemical specialty manufacturing, indirectly subsidizing local adhesive blending capacity expansion across key industrial corridors.
Selangor
Automotive tier-one suppliers and packaging converters cluster in Selangor's industrial corridor, driving specification-grade adhesive procurement. The Department of Environment enforces Environmental Quality Regulations that restrict solvent content, compelling reformulation investments among Klang Valley blenders. Shah Alam and Port Klang host the densest concentration of water-based adhesive production facilities serving export-oriented manufacturers.
Penang
Semiconductor assembly operations in Penang demand high-precision underfill and die-attach adhesives for component miniaturization. SIRIM QAS International certification governs construction adhesive acceptance for government infrastructure contracts, creating compliance thresholds for local formulators. Bayan Lepas and Kulim host electronics manufacturers specifying UV-LED curable systems for temperature-sensitive bonding applications.
Johor
Proximity to Singapore's biotech and medical device manufacturing creates demand for ISO 10993-compliant medical-grade adhesives currently underpenetrated versus electronics segments. The Iskandar Malaysia development corridor attracts specialty chemical investments targeting cross-border supply chains. Pasir Gudang and Johor Bahru logistics hubs position blenders to serve Singapore-origin pharmaceutical contract manufacturers.
Sarawak
Timber processing and plywood manufacturing in Sarawak sustain PVA adhesive demand for woodworking applications with minimal technical service requirements. The state's renewable energy infrastructure supports energy-intensive hot-melt production for regional packaging markets. Miri and Sibu host wood-product clusters where adhesive procurement operates on price-sensitive spot buying rather than annual contracts.
Malaysia Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's adhesive market, creating a tiered structure where global formulators anchor premium segments and domestic blenders capture commoditized volume. The vendor base concentrates around three strategic archetypes: multinational technology leaders with direct technical service organizations, regional distributors with asset-light contract manufacturing arrangements, and domestic blenders leveraging palm oil derivative feedstock access. Competitive moves center on formulation licensing partnerships and backward integration into bio-based raw material sourcing.
Among technology leaders, Henkel AG & Co. KGaA, 3M, and Sika AG occupy positions representing distinct competitive vectors. Henkel exemplifies the premium water-based formulation archetype through global library leverage. 3M represents specialized structural bonding capabilities serving precision manufacturing requirements. Sika anchors construction-grade polyurethane positioning through technical service intensity. These three entities collectively illustrate how multinational presence, direct sales organizations, and embedded application engineering differentiate premium-tier positioning from distributor-dependent domestic competitors.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| H.B. Fuller Company |
| Arkema Group |
| Mohm Chemical Sdn. Bhd. |
| AICA Adtek Sdn. Bhd. |
| Vital Technical Sdn Bhd |
| Bostik |
| Others |
Supply & Pricing Matrix
Overcapacity in Shah Alam's water-based adhesive production corridor is compressing supplier margins while simultaneously concentrating pricing power among SIRIM-certified formulators serving government infrastructure contracts. This utilization asymmetry between commodity-grade capacity and specification-grade scarcity reshapes how buyers negotiate annual contracts versus spot purchases.
Pricing Analysis
Certification level creates the primary spread between SIRIM QAS-validated construction grades and uncertified alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy spot-buy levels dominates procurement. Cost compression in packaging-grade water-based segments is intensifying because hot-melt substitution eliminates drying-time advantages. Electronics assemblers in Penang show least price sensitivity due to die-attach reliability requirements, while corrugated converters in Selangor operate on thin margins with maximum price elasticity.
Supply Chain Analysis
Contract manufacturing concentration among asset-light Malaysian distributors and Singapore-origin specialty monomer suppliers holds adhesive blending capacity. Malaysia draws from Singapore for high-purity acrylates and isocyanates, China for epoxy resin intermediates, and domestic palm oil derivatives for bio-based polyurethane feedstocks. Single-source vulnerability runs through cross-border isocyanate supply subject to port congestion. Distribution runs through direct technical service teams for electronics and automotive tiers, with distributor networks serving retail and contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's adhesives market functions as a defensive-moat story anchored in regulatory entrenchment. SIRIM certification requirements and Department of Environment VOC compliance create switching costs that protect incumbent positions from import substitution.
For Market Incumbents: Entrench through backward integration into palm oil derivative feedstocks and embedded technical service teams at Penang semiconductor fabs. The threat of Singapore-sourced specialty monomer supply disruption demands captive raw material buffers. Certification investment in ISO 10993 medical-grade capacity represents the priority lever for Johor Bahru corridor expansion. For New Entrants and Emerging Players: Mid-market medical device contract manufacturers in Johor's Iskandar corridor represent the most penetrable entry point given current underpenetration versus electronics and construction. Bio-based polyurethane development leveraging Malaysia-origin palm chemistry offers distinct feedstock access versus regional competitors. A go-to-market angle anchored in REACH-aligned substance restrictions for export-oriented electronics assemblers bypasses direct SIRIM timeline disadvantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light contract manufacturing arrangements, compressing traditional inventory-heavy valuation multiples. Long-term viability across the analysis window favors blenders with direct multinational relationships and dual product portfolios. Acquisition target archetypes include domestic formulators with SIRIM certificate holdings and Singapore-cross-border logistics capabilities. The signal to watch is carbon border adjustment implementation timing in key export destinations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Palm oil derivative chemistry access differentiates Malaysia-origin formulators from regional competitors. |
| SIRIM QAS Certification Investment | Government infrastructure contract eligibility filters non-certified imports and elevates compliant domestic blenders. |
| UV-LED Curable Platform Development | Penang electronics cleanrooms demand temperature-sensitive bonding that thermal curing cannot accommodate. |
| Embedded Technical Service Expansion | Automotive tier-one suppliers in Selangor mandate global contract pricing with local application engineering support. |
| Johor Bahru Medical-Grade Capacity Buildout | ISO 10993-compliant adhesive demand from Singapore-origin pharmaceutical contract manufacturers remains underpenetrated. |
Research Methodology
A spread of perspectives from adhesive formulators, procurement leads at electronics and automotive OEMs, distribution channel partners, and Department of Environment regulatory officers converged on the working assumptions. Primary interviews combined with secondary validation against customs and trade data, SIRIM QAS certification records, SEC filings of multinational suppliers, and Malaysian Ministry of International Trade and Industry incentive disclosures. Bottom-up segment sizing and top-down macroeconomic cross-checks anchored volume and value estimates.
Demand-supply balance modeling across resin chemistry, application intensity, technology platform, and end-user type structured the projection framework. Segmentation dimensions included formulation grade tier, end-use industry cluster, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines throughout the forecast period. Industry-specific inputs encompassed Department of Environment regulatory enforcement schedules and PLI-aligned incentive disbursement patterns.
Practitioners should monitor petrochemical feedstock volatility, SIRIM certification timeline compression, and carbon border adjustment developments in European export destinations for early signals. Forecasts reflect assumptions about regulatory enforcement continuity and cross-border specialty monomer supply stability. Cross-checking against Malaysian customs import data for epoxy and polyurethane resin categories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Asia-Pacific Electronics Adhesives Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
North America Electronics Adhesives Market