
 South America Polyurethane (PU) Hot-Melt Adhesives Market | 2026-2036
South America Polyurethane (PU) Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyurethane (PU) Hot-Melt Adhesives Market Analytics
Automotive OEMs are unwinding legacy solvent-based bonding commitments in favor of reactive hot-melt systems. H.B. Fuller Company leverages its regional compounding network to supply tailored viscosity grades for Brazilian assembly lines. Henkel AG & Co. KGaA anchors its position through direct technical service partnerships with São Paulo-based tier-one suppliers. Sika AG competes by specializing in high-performance grades that tolerate the humidity cycles common across the continent.
South America Polyurethane (PU) Hot-Melt Adhesives are thermoplastic or reactive systems formulated with isocyanate-terminated prepolymers that cure through atmospheric moisture or substrate moisture, achieving bond strengths from 2 to 15 MPa depending on open time and substrate porosity. These adhesives serve primarily as structural bonding agents where rapid set speed, green strength, and resistance to plasticizer migration outperform conventional EVA or polyolefin alternatives. The furniture application segment dominates current volume consumption due to edgebanding and membrane pressing demand across Brazilian and Argentine wood processing clusters. High-performance product types capture the deepest margin pools as aerospace and electronics end users impose qualification barriers that limit supplier participation. Water-resistant formulations are gaining fastest in construction end uses where Brazilian coastal humidity and Colombian rainfall patterns degrade standard-grade bonds.
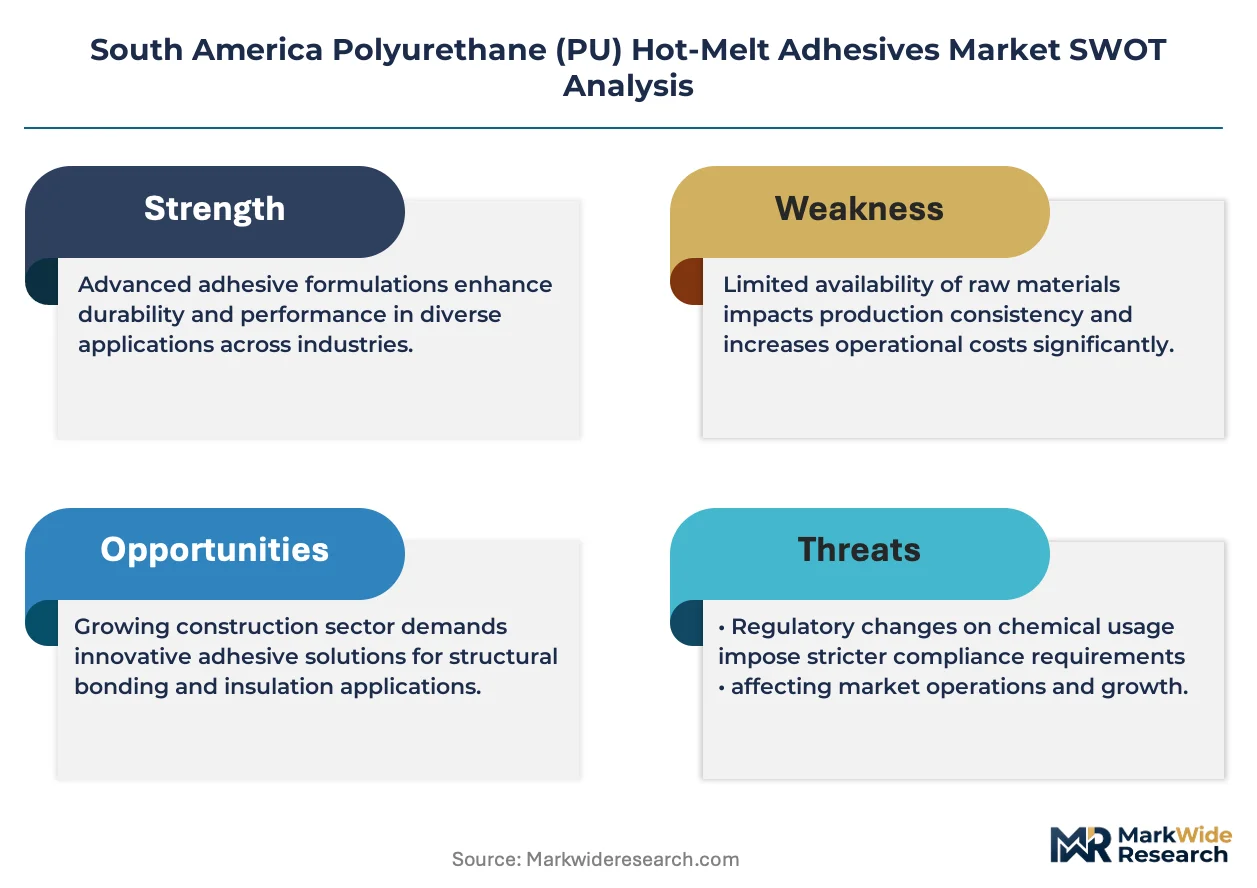
Brazil's ANVISA monitors chemical substance registrations for adhesive components used in consumer goods and medical device packaging, while Argentina's national chemical regulator enforces hazard communication standards aligned with Mercosur resolutions. Colombia's Ministry of Environment imposes volatile organic compound thresholds on industrial adhesive applications in Bogotá and Medellín airsheds. Stakeholders must track how evolving Mercosur technical regulations harmonize with EU REACH substance restrictions, as this alignment determines which imported raw material streams remain permissible.
Market Dynamics
Automotive OEMs across Brazil's southern corridor are dismantling solvent-based bonding lines in favor of reactive moisture-cure systems, compressing qualification timelines and forcing reformulation investments from adhesive suppliers serving São Paulo and Curitiba assembly plants.
Growth Catalysts
- REACH-aligned Mercosur harmonization:Brazil's ANVISA and Argentina's chemical regulator are synchronizing substance restrictions with EU standards, opening import pathways for European raw material streams previously blocked by technical barriers.
- Edgebanding automation in furniture clusters:Brazilian wood processors in Bento Gonçalves and Erechim are retrofitting membrane pressing lines with PUR hot-melt applicators to achieve seamless finishes on high-gloss laminates.
- Humidity-tolerant formulation advances:Sika AG and regional compounders are deploying isocyanate-terminated prepolymers engineered for Colombian rainfall cycles and Brazilian coastal moisture, expanding addressable construction applications.
Market Restraints
- MDI price volatility:Diphenylmethane diisocyanate feedstock costs fluctuate with Asian petrochemical output, squeezing margin stability for Brazilian formulators lacking long-term supply contracts.
- Import dependency for specialty polyols:South American producers rely on German and Chinese suppliers for high-performance polyether intermediates, exposing formulation pipelines to freight rate spikes and currency mismatches.
- Cure speed limitations in low-humidity environments:Atmospheric moisture-cure chemistry performs poorly in Argentina's Mendoza province and Chile's Atacama-adjacent industrial zones, restricting geographic penetration of standard-grade products.
Strategic Opportunities
- Colombian construction sector expansion:Bogotá and Medellín infrastructure projects are specifying water-resistant structural bonding for prefabricated concrete elements, creating first-mover advantages for suppliers with humidity-validated formulations.
- Dual-cure hybrid systems:Convergence of UV-initiated and moisture-cure chemistries enables instant handling strength followed by full structural cure, opening electronics assembly applications in Brazilian consumer device manufacturing.
- Direct technical service models:Bypassing traditional distributor networks to embed application engineers at São Paulo tier-one automotive suppliers accelerates qualification cycles and captures specification authority.
Industry Challenges
- Polyurethane chemist scarcity:Brazilian universities produce limited isocyanate formulation specialists, forcing adhesive producers to recruit from petrochemical or coatings sectors and retrain for hot-melt rheology requirements.
- ANVISA registration timelines:New chemical substance notifications for adhesive components used in medical device packaging face 18-24 month review periods, delaying product launches for healthcare-focused formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyurethane (PU) Hot-Melt Adhesives Market |
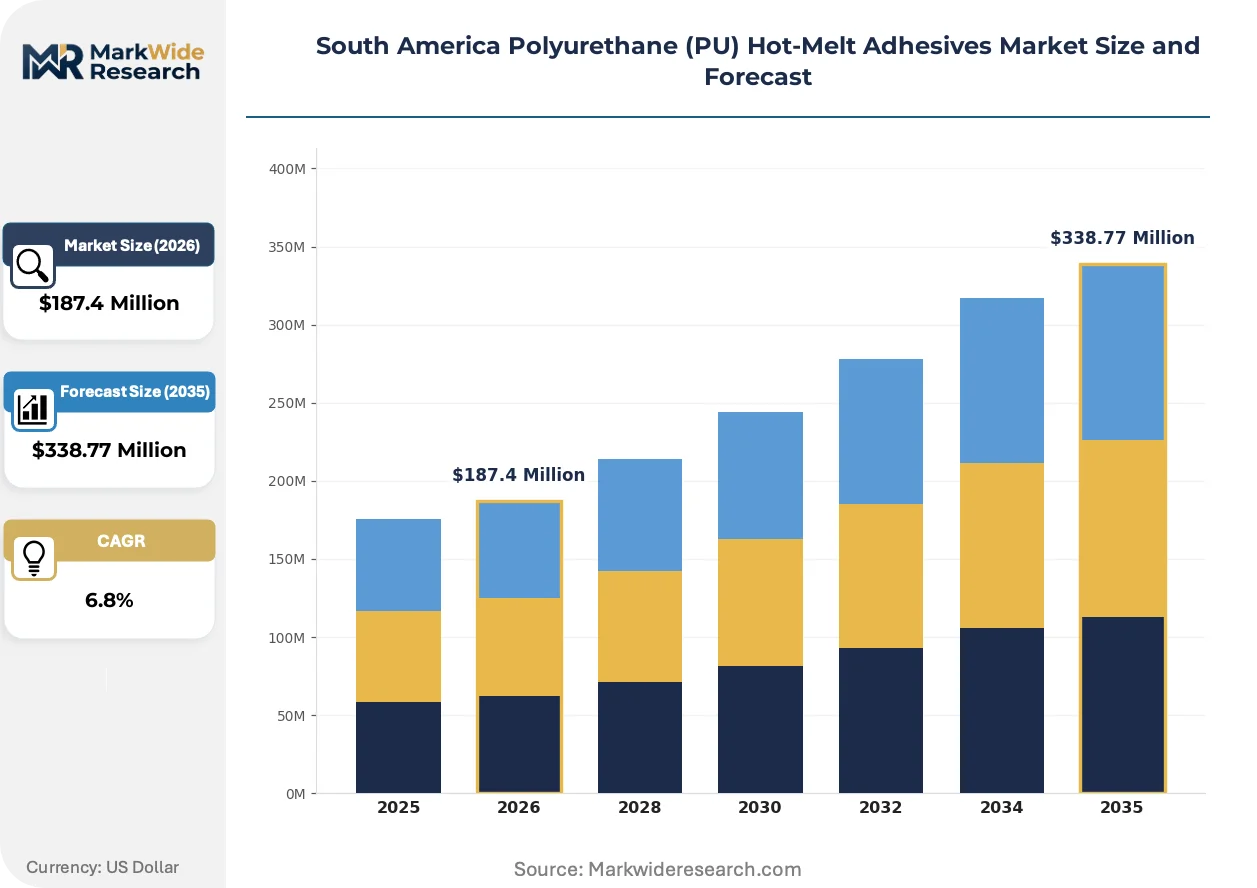
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Furniture, Packaging, Textiles, Automotive Product Type: Low Temperature, High Performance, Expandable, Water-Resistant End User: Manufacturing, Construction, Aerospace, Electronics Form: Granules, Sheets, Strips, Rods |
| Companies Covered | 3M, Arkema Group, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Bostik S.A., Jowat AG, Dow Inc., Huntsman Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyurethane (PU) Hot-Melt Adhesives Market Evolving Landscape
Moisture-cure polyurethane chemistry is undergoing rapid refinement as humidity-specific formulations displace one-size-fits-all products, while regulatory convergence and procurement centralization reshape how specifications travel from OEMs to compounders.
Low-viscosity reactive hot-melt systems are miniaturizing dispensing equipment footprints for automotive interior trim applications. Tier-one suppliers in São Paulo are adopting compact robotic applicators that reduce line changeover times from hours to minutes. This equipment compression is miniaturizing capital barriers for mid-size Brazilian furniture producers seeking automated edgebanding.
Argentina's chemical regulator is enforcing hazard communication standards aligned with Mercosur resolutions that mirror EU REACH annexes. Industrial adhesive formulators must now submit extended safety data sheets for isocyanate-containing products. Brazilian exporters to Mercosur partners face accelerated compliance costs but gain streamlined market access across the customs union.
Consolidated procurement desks at major Brazilian automotive OEMs are unbundling adhesive specification from general chemical purchasing. Technical teams now retain direct supplier relationships while procurement handles commercial terms. This bifurcation concentrates volume with qualified compounders and marginalizes distributors lacking application engineering capabilities, most visible in Curitiba and São Bernardo do Campo assembly corridors.
South America Polyurethane (PU) Hot-Melt Adhesives Market Segmentation
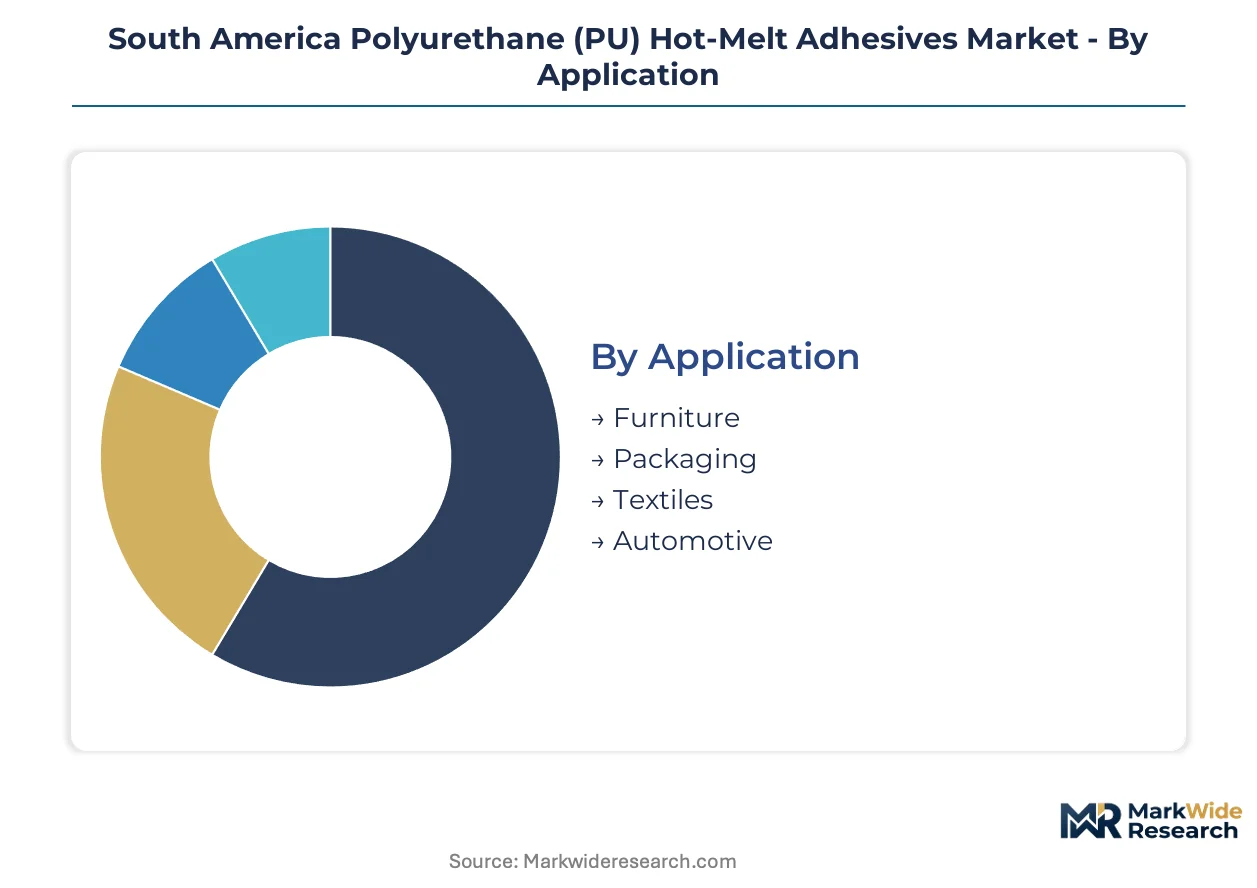
Segmentation in the South America PU hot-melt adhesives market reveals how formulation chemistry, physical form, and end-use specifications create distinct procurement channels. Brazilian furniture clusters and Argentine automotive corridors drive divergent product requirements that reshape supplier priorities across the continent.
Application:
Furniture demand concentrates in domestic Brazilian manufacturing zones, while automotive applications serve both local assembly and export component supply chains.
- Furniture:Edgebanding and membrane pressing operations in Bento Gonçalves and Erechim wood processing clusters consume reactive PUR systems for seamless high-gloss laminate finishes. Brazilian furniture OEMs specify low-viscosity grades compatible with automated applicator lines.
- Automotive:Reactive moisture-cure systems bond interior trim components across São Paulo and Curitiba assembly plants. Tier-one suppliers demand rapid green strength development to compress line cycle times.
- Packaging:Medical device and consumer goods packaging in São Paulo state triggers ANVISA registration requirements for isocyanate-containing adhesives.
- Textiles:Lamination applications for sportswear and technical fabrics concentrate in southern Brazil's textile belt near Blumenau.
Furniture commands the established base. The steepest expansion runs through Automotive.
Product Type:
Cost tier differentiation separates commodity formulations from qualification-intensive specialty grades that capture margin premiums.
- High Performance:Aerospace and electronics end users impose qualification barriers that limit supplier participation to compounders with validated batch consistency. These grades tolerate thermal cycling and plasticizer migration in Colombian avionics assembly.
- Water-Resistant:Formulations engineered for Colombian rainfall patterns and Brazilian coastal humidity expand construction addressability. Sika AG and regional compounders deploy isocyanate-terminated prepolymers optimized for moisture-cure reliability in saturated environments.
- Low Temperature:Reduced application temperature grades protect heat-sensitive substrates in Argentine furniture membrane pressing.
- Expandable:Foaming characteristics fill gaps in prefabricated concrete element bonding for Bogotá infrastructure projects.
High Performance captures margin concentration. Water-Resistant formulations are climbing the fastest.
End User:
Customer type determines specification authority, with centralized procurement at automotive OEMs contrasting fragmented purchasing across construction subcontractors.
- Manufacturing:Furniture and automotive production lines in Brazil's southern corridor specify reactive hot-melt systems for structural bonding where rapid set speed outperforms EVA alternatives.
- Construction:Prefabricated concrete element assembly in Colombian infrastructure projects demands validated humidity tolerance.
- Aerospace:Qualification-intensive segment with limited supplier pools serving maintenance and assembly operations.
- Electronics:Brazilian consumer device manufacturing explores dual-cure hybrid systems combining UV-initiated and moisture-cure chemistries.
Manufacturing anchors procurement volumes. Electronics shows the steepest expansion trajectory.
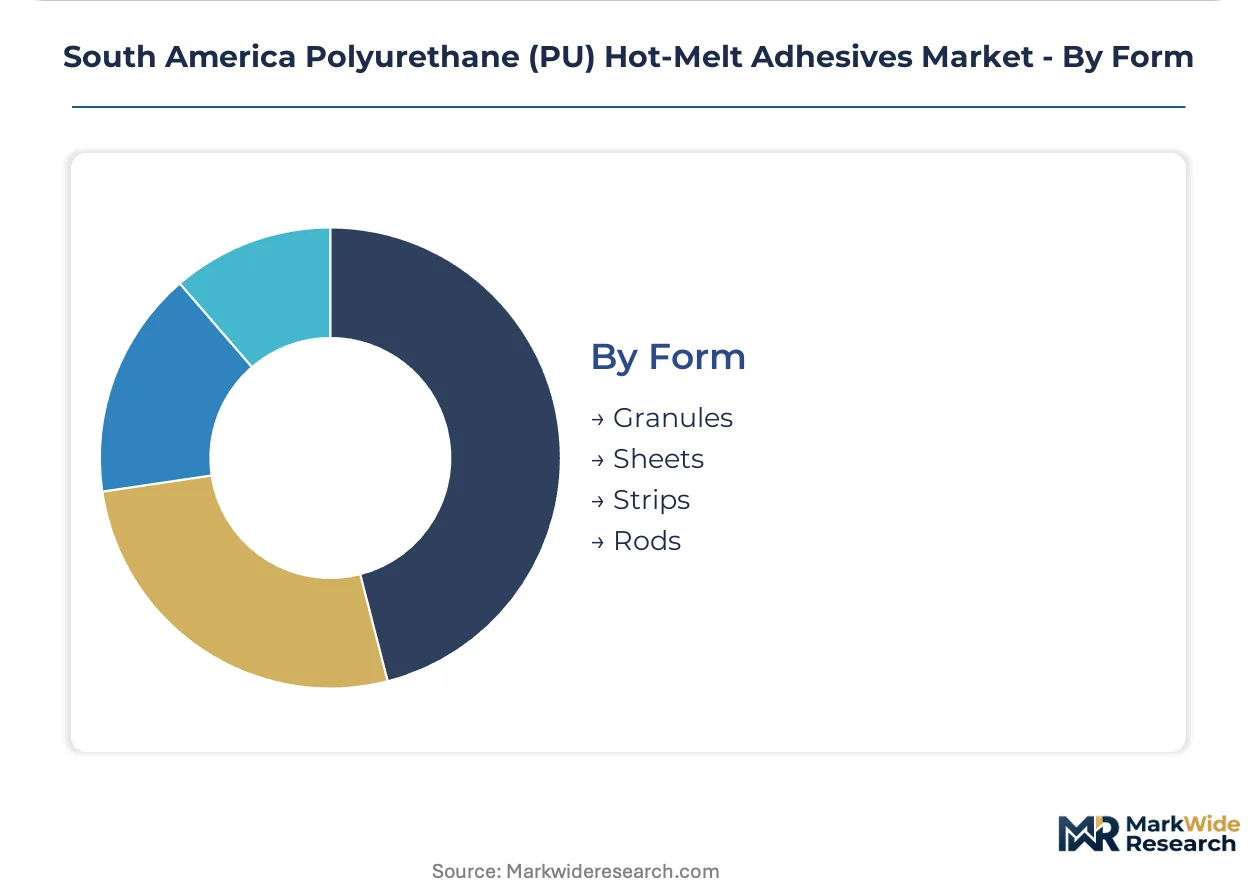
Form:
Physical configuration shapes equipment compatibility and handling logistics across distinct application environments.
- Granules:Standard bulk form for automated feed systems in high-volume Brazilian furniture edgebanding operations.
- Sheets:Flat configuration supports membrane pressing applications requiring uniform thermal distribution.
- Strips:Pre-measured segments simplify manual application in construction field conditions.
- Rods:Cylindrical form factors feed specialized dispensing equipment for automotive interior trim assembly.
Granules dominate industrial automation. Rods are gaining share fastest in automotive specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters along Brazil's southern manufacturing corridor, with raw material import dependencies shaping competitive positioning across Mercosur member states. Argentine chemical regulations and Colombian environmental enforcement create divergent compliance pathways for adhesive suppliers.
Brazil
Furniture edgebanding automation and automotive interior bonding drive consumption volumes in São Paulo and Curitiba assembly corridors. ANVISA chemical substance registrations impose 18-24 month review timelines for medical device packaging adhesives. Bento Gonçalves wood processing clusters specify low-viscosity reactive PUR systems for high-gloss laminate membrane pressing.
Argentina
Automotive tier-one suppliers in Córdoba and Buenos Aires provinces demand rapid green strength development for trim component bonding lines. The national chemical regulator enforces hazard communication standards aligned with Mercosur resolutions mirroring EU REACH annexes. Mendoza province's low-humidity conditions restrict standard moisture-cure chemistry penetration.
Colombia
Bogotá and Medellín infrastructure projects specify water-resistant structural bonding for prefabricated concrete elements. The Ministry of Environment imposes volatile organic compound thresholds on industrial adhesive applications in capital region airsheds. Coastal humidity patterns and Andean rainfall cycles validate Sika AG humidity-tolerant formulation deployments.
Chile
Atacama-adjacent industrial zones present cure speed limitations for atmospheric moisture-cure chemistry. Construction sector procurement concentrates in Santiago metropolitan area for building envelope applications. Northern mining equipment maintenance generates demand for high-performance grades tolerating thermal cycling.
Peru
Lima-based furniture manufacturers import reactive hot-melt systems through Brazilian distributor networks. Environmental enforcement for industrial chemical applications remains less stringent than Colombian or Brazilian standards. Coastal humidity exposure drives specification of water-resistant formulations for woodworking exports.
South America Polyurethane (PU) Hot-Melt Adhesives Market Competitive Landscape
Concentration sits with multinational chemical conglomerates possessing integrated polyol supply chains and established Mercosur regulatory compliance infrastructure. Three structural archetypes dominate: European specialty chemical houses with direct technical service models, North American adhesive formulators leveraging regional compounding networks, and diversified materials science corporations with construction sector anchoring. Competitive moves center on qualification acceleration through embedded application engineering and backward integration into isocyanate precursor sourcing.
Among European-based specialty chemical houses, Henkel AG & Co. KGaA and Sika AG exemplify divergent positioning strategies within the regional market. H.B. Fuller Company represents the North American formulator archetype with distributed compounding capabilities. Bostik S.A. occupies a position bridging construction sector specification authority with furniture industry penetration.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Bostik S.A. |
| Jowat AG |
| Dow Inc. |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Brazilian compounding facilities shapes both supply concentration and price floors, as underloaded plants in São Paulo state struggle to amortize fixed costs against MDI feedstock volatility. This scale dynamic compresses margins for mid-tier formulators while anchoring premium pricing for suppliers with captive polyol sourcing.
Pricing Analysis
Volume-discount tiering structures separate high-performance aerospace grades from commodity furniture formulations. Three-tier pricing stratifies across qualification-intensive specialty, water-resistant construction, and standard EVA-replacement tiers. Price differentiation hinges on certification grade for ANVISA medical packaging and volume scale for automotive procurement desks. Cost compression in standard grades intensifies as Chinese polyol exporters undercut European suppliers on landed cost.
Supply Chain Analysis
Inventory lead times for German and Chinese polyether intermediates stretch formulation pipelines across the continent. Raw material sourcing draws from German specialty polyol producers, Chinese petrochemical exporters, and domestic Brazilian MDI distributors. Single-source vulnerability concentrates in high-performance polyether streams. Distribution runs through São Paulo-based technical distributors and direct embedded service models at tier-one automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through automotive production recovery as Brazilian OEMs restock bonding inventories after supply chain destocking. The cyclical upswing favors suppliers with qualified moisture-cure formulations and established ANVISA registration pathways.
For Market Incumbents: Shield specification authority at São Paulo automotive tier-ones by embedding application engineers and accelerating dual-cure hybrid qualification timelines. Backward integration into isocyanate precursor sourcing defends margin position against MDI volatility. Prioritize ANVISA registration maintenance for medical packaging adhesives to block entrant access. For New Entrants and Emerging Players: ANVISA fast-track partnerships with established Brazilian formulators unlock medical device packaging penetration where registration timelines deter direct entry. Colombian construction water-resistant formulations present the most penetrable white space, with Bogotá infrastructure projects validating humidity-tolerant chemistry. Lead with direct technical service rather than distributor relationships to compress qualification cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with embedded automotive service contracts and multi-year OEM supply agreements. Long-term viability over the medium-term horizon rests on regulatory compliance infrastructure and backward integration depth. Acquisition targets should demonstrate validated batch consistency for aerospace qualification and established Mercosur chemical registration capabilities. Monitor MDI contract pricing as the inflection signal for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Sourcing | Captive supply of high-performance polyethers insulates Brazilian formulators from Asian freight volatility. |
| ANVISA Registration Acceleration | Fast-tracked chemical notifications unlock medical device packaging demand in São Paulo manufacturing zones. |
| Dual-Cure Hybrid System Launch | UV-moisture convergence opens electronics assembly applications for Brazilian consumer device manufacturers. |
| Direct Technical Service Expansion | Embedded application engineers at Curitiba tier-ones capture specification authority from distributor networks. |
| Humidity-Validated Formulation Deployment | Colombian coastal and Andean rainfall testing expands construction addressability for Sika AG and regional compounders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including adhesive formulators, automotive tier-one procurement leads, furniture production engineers, and ANVISA regulatory consultants. Secondary validation drew from Brazilian customs trade data, ANVISA chemical substance registries, SEC filings of multinational adhesive suppliers, and Mercosur technical regulation harmonization documents. Bottom-up volume estimates triangulated against top-down market sizing across application segments.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type tiers, end-use industries, and regional production clusters. CAGRs were derived from trend extrapolation of automotive production forecasts, furniture automation adoption curves, and construction infrastructure pipelines. Industry-specific inputs incorporated MDI price elasticity assumptions and ANVISA registration timeline distributions.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and continued Mercosur-REACH alignment assumptions; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market