
 Restorative Materials and Bonding Agents Market | 2026-2036
Restorative Materials and Bonding Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Restorative Materials and Bonding Agents Market Analytics
Cosmetic dentistry demand is realigning procurement priorities across dental practices. Ivoclar Vivadent leverages its ceramics specialization to command premium positioning in anterior restorations. 3M anchors the adhesive segment through proprietary etch-and-rinse and self-etch chemistry platforms. GC Corporation differentiates via glass ionomer formulations that release fluoride ions for caries-prone patient populations.
Restorative materials and bonding agents comprise synthetic resin matrices, filler particles, and adhesive monomers that rebuild tooth structure lost to caries, trauma, or wear, with bond strengths typically measured in megapascals to enamel and dentin substrates. Composite resins dominate value capture due to aesthetic tunability and direct-placement economics, while glass ionomer retains share in pediatric and geriatric applications where moisture tolerance outweighs polishability requirements. Dental laboratories represent a concentrated margin pool as outsourcing of crown, bridge, and veneer fabrication accelerates among general practitioners seeking production scale.
FDA 510(k) clearance pathways govern permanent restorative materials in the United States, while the EU Medical Device Regulation mandates notified body involvement for Class IIa and above dental devices, elevating documentation burdens for adhesive systems claiming durable clinical performance. ISO 10993 biocompatibility testing series provides the toxicological backbone accepted across both jurisdictions. Stakeholders must monitor evolving reimbursement codes for adhesive procedures as payors scrutinize long-term clinical evidence against restoration replacement rates.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines for adhesive systems while simultaneously elevating biocompatibility documentation burdens. This regulatory pressure is forcing manufacturers to restructure R&D budgets toward toxicological testing infrastructure.
Growth Catalysts
- India's National Oral Health Program:Government health schemes in India are broadening access to preventive and restorative oral care, expanding patient volumes for adhesive protocols in public dental clinics.
- ISO 10993-5 cytotoxicity testing harmonization:Standardized biocompatibility frameworks reduce regulatory friction for manufacturers seeking multi-jurisdiction clearance.
- Fluoride-releasing glass ionomer chemistry:Moisture-tolerant formulations address pediatric and geriatric patient populations where traditional resin bonding fails.
Market Restraints
- Silica nanofiller supply concentration:Specialty filler particle production clusters in East Asian chemical processing hubs, creating input vulnerability for composite resin manufacturers.
- MDR notified body bottleneck:EU Medical Device Regulation implementation has strained certification capacity, extending adhesive system approval timelines by twelve to eighteen months.
- Amalgam substitution ceiling:Mercury-containing restoration bans in Nordic jurisdictions have largely run their course, limiting further regulatory-driven material switching.
Strategic Opportunities
- Brazil's SUS dental expansion:Brazil's unified health system is scaling restorative procedure coverage, creating volume opportunity for economy-tier bonding agents.
- Digital workflow integration:Chairside CAD/CAM systems are converging with self-adhesive resin cements, enabling same-day indirect restoration protocols.
- Bioceramic sealer chemistry:Mineral trioxide aggregate and calcium silicate formulations open endodontic applications beyond traditional coronal restorations.
Industry Challenges
- Adhesive protocol standardization:Etch-and-rinse versus self-etch technique selection requires chairside judgment that resists algorithmic simplification, complicating training programs.
- ISO 10993-10 sensitization testing backlog:Delayed irritancy and sensitization study completion stalls product launches for novel monomer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restorative Materials and Bonding Agents Market |
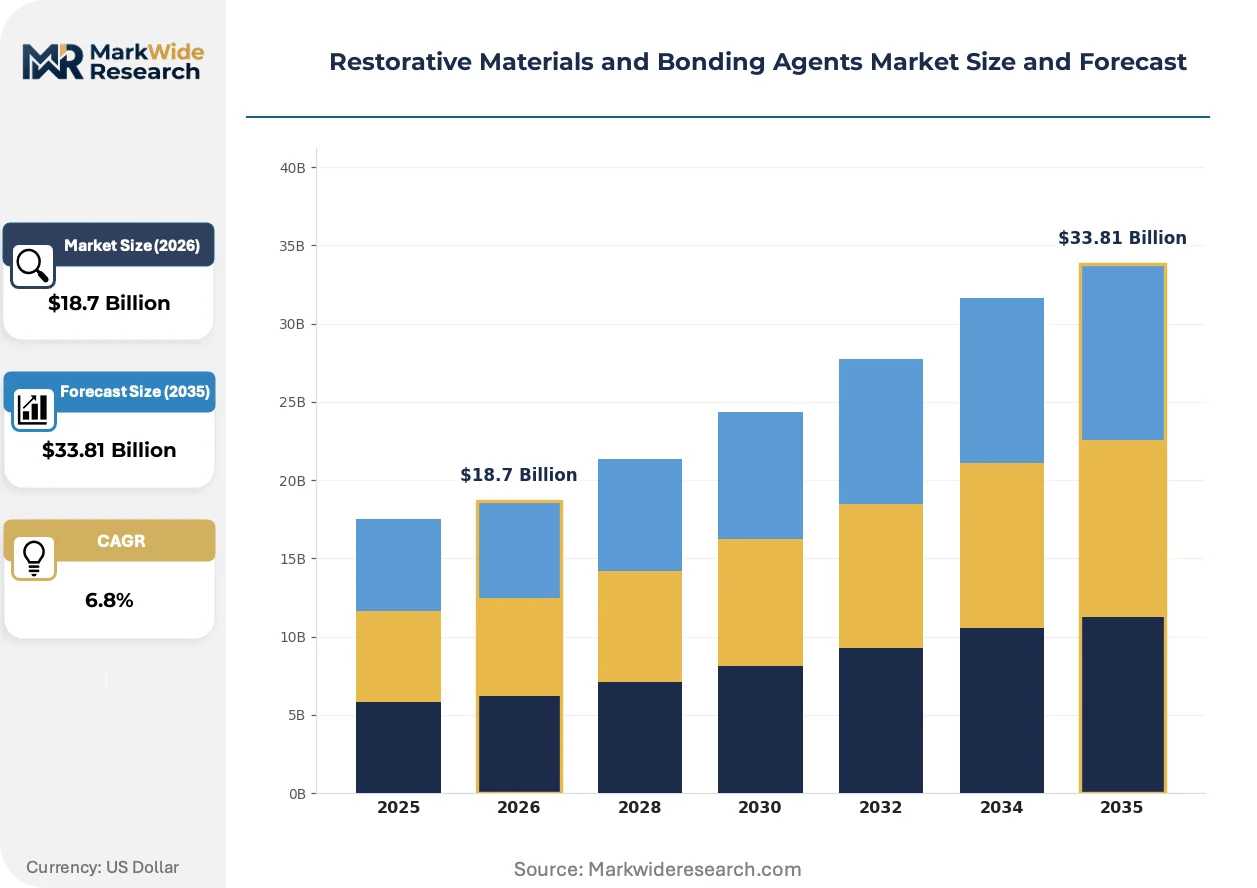
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resins, Glass Ionomer, Resin Ionomer, Ceramics Application: Dental Restorations, Adhesion, Core Build-Up, Provisional Restorations End User: Dentists, Dental Clinics, Hospitals, Dental Laboratories Distribution Channel: Direct Sales, Online Sales, Distributors, Training Centers |
| Companies Covered | Ivoclar Vivadent, Kuraray Noritake Dental, 3M, GC Corporation, BISCO, Dentsply Sirona, VOCO GmbH, Shofu Dental, Kerr Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restorative Materials and Bonding Agents Market Evolving Landscape
Automation of adhesive application protocols is compressing technique sensitivity while machine vision systems enable real-time bond quality verification. These developments are reducing operator-dependent variability in clinical outcomes.
Universal adhesive monomer chemistry is automating the transition between etch-and-rinse and self-etch protocols through pH-adjustable formulations. General dental practitioners in North American group practices are adopting these systems to simplify inventory management. The technology is automating reduction in technique errors that previously drove premature restoration failure and replacement cycles.
The EU Medical Device Regulation's clinical evidence requirements for Class IIa devices are mandating post-market surveillance systems for permanent restorative materials. Manufacturers must now maintain clinical registries tracking restoration longevity across diverse patient populations. Adhesive systems claiming durable performance face the steepest documentation burdens, with notified bodies demanding five-year follow-up data for novel chemistries.
Buyer consolidation among dental service organizations is compressing supplier negotiation cycles and unbundling technical service from material procurement. Large DSOs in the United States are implementing direct-to-manufacturer purchasing agreements that displace traditional distributor relationships. This pattern concentrates volume with fewer adhesive suppliers capable of meeting enterprise-level logistics and standardization requirements.
Restorative Materials and Bonding Agents Market Segmentation
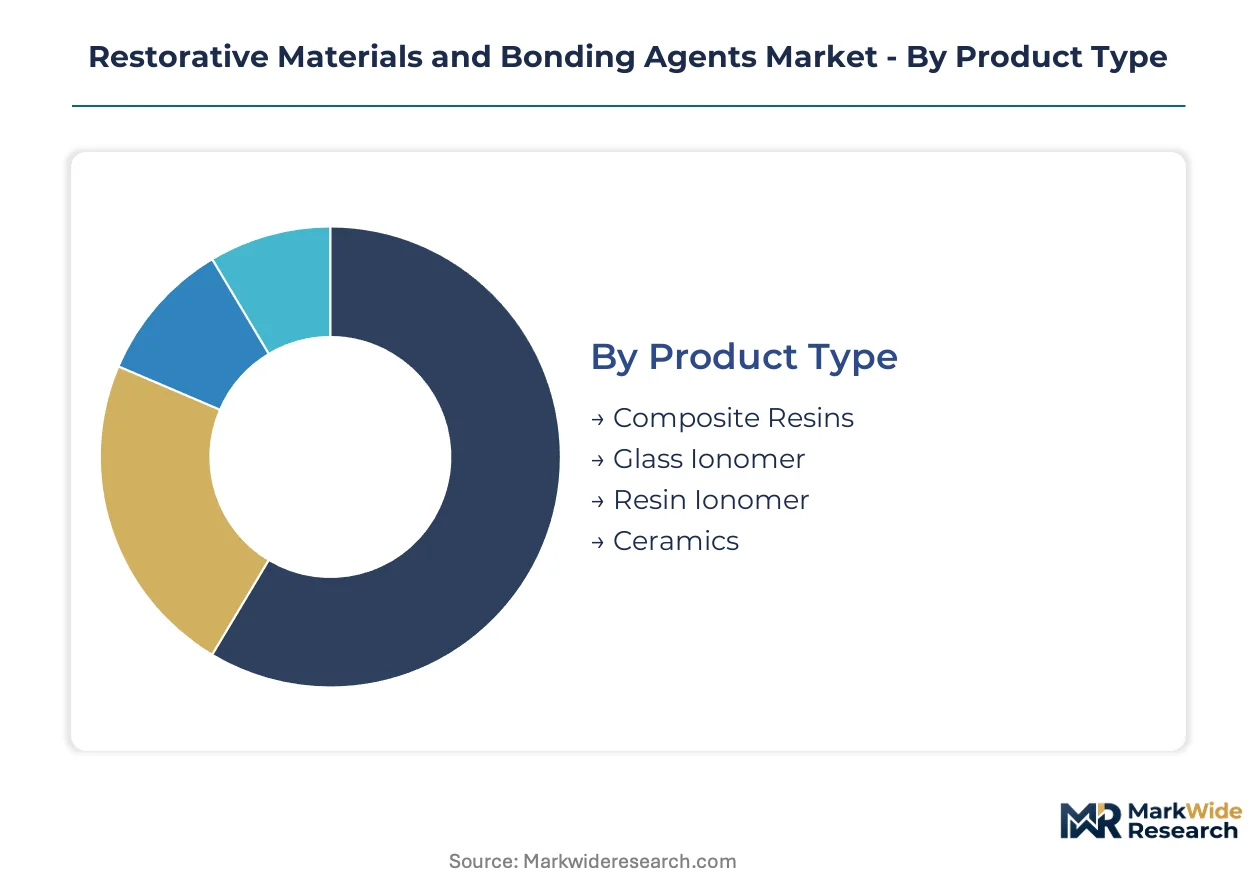
Segmentation in restorative materials and bonding agents reveals distinct upgrade cycles across product categories. Replacement timelines for resin-based systems run shorter than ceramic restorations, while application-specific formulations command premium positioning in high-aesthetic procedures.
Product Type:
Upgrade cycles vary dramatically by material class, with direct-placement composites replacing faster than laboratory-fabricated indirect restorations.
- Composite Resins:Bis-GMA and urethane dimethacrylate matrices loaded with silica or zirconia filler particles enable shade-matched direct restorations. Demand clusters in North American group dental practices where chairside economics favor single-visit protocols over laboratory outsourcing.
- Glass Ionomer:Polyalkenoate cements release fluoride ions through acid-base reaction with fluoroaluminosilicate glass. India's National Oral Health Program is expanding public clinic procurement of these moisture-tolerant formulations for pediatric caries management in rural settings.
- Resin Ionomer:Hybrid chemistry combines resin photopolymerization with glass ionomer fluoride release for dual-cure applications.
- Ceramics:Feldspathic, leucite-reinforced, and zirconia-based systems serve indirect restoration fabrication via milling or pressing.
Volume placements concentrate in Composite Resins; the faster expansion belongs to Ceramics.
Application:
Cost tier differentiation separates routine adhesive procedures from complex core build-ups requiring specialized mechanical properties.
- Dental Restorations:Coronal reconstruction of caries-damaged tooth structure using direct or indirect materials. Brazilian SUS dental expansion is scaling economy-tier composite procurement for posterior restorations in public health clinics.
- Adhesion:Enamel and dentin bonding protocols using etch-and-rinse, self-etch, or universal adhesive systems. EU MDR clinical evidence requirements are extending approval timelines for novel monomer formulations claiming durable bond strengths.
- Core Build-Up:Foundation materials replacing lost tooth structure to support crowns and fixed prostheses.
- Provisional Restorations:Temporary crowns, bridges, and veneers fabricated from acrylic or bis-acryl composites.
Procedure volume peaks in Dental Restorations; steepest expansion trajectory runs through Adhesion.
End User:
Customer type determines margin capture, with dental laboratories extracting value from fabrication expertise while clinics compete on chairside throughput.
- Dentists:Independent practitioners and associates performing direct restorations and simple adhesive protocols. Buyer consolidation among US dental service organizations is compressing supplier negotiation cycles and unbundling technical service from material procurement.
- Dental Clinics:Multi-chair facilities with centralized inventory and standardized technique protocols. ISO 10993-5 cytotoxicity testing harmonization is reducing regulatory friction for manufacturers seeking multi-jurisdiction clearance across clinic networks.
- Hospitals:Academic medical centers and trauma facilities handling complex restorative cases.
- Dental Laboratories:Outsourced fabrication hubs for crowns, bridges, and implant-supported restorations.
Procurement volume concentrates in Dental Clinics; margin expansion favors Dental Laboratories.
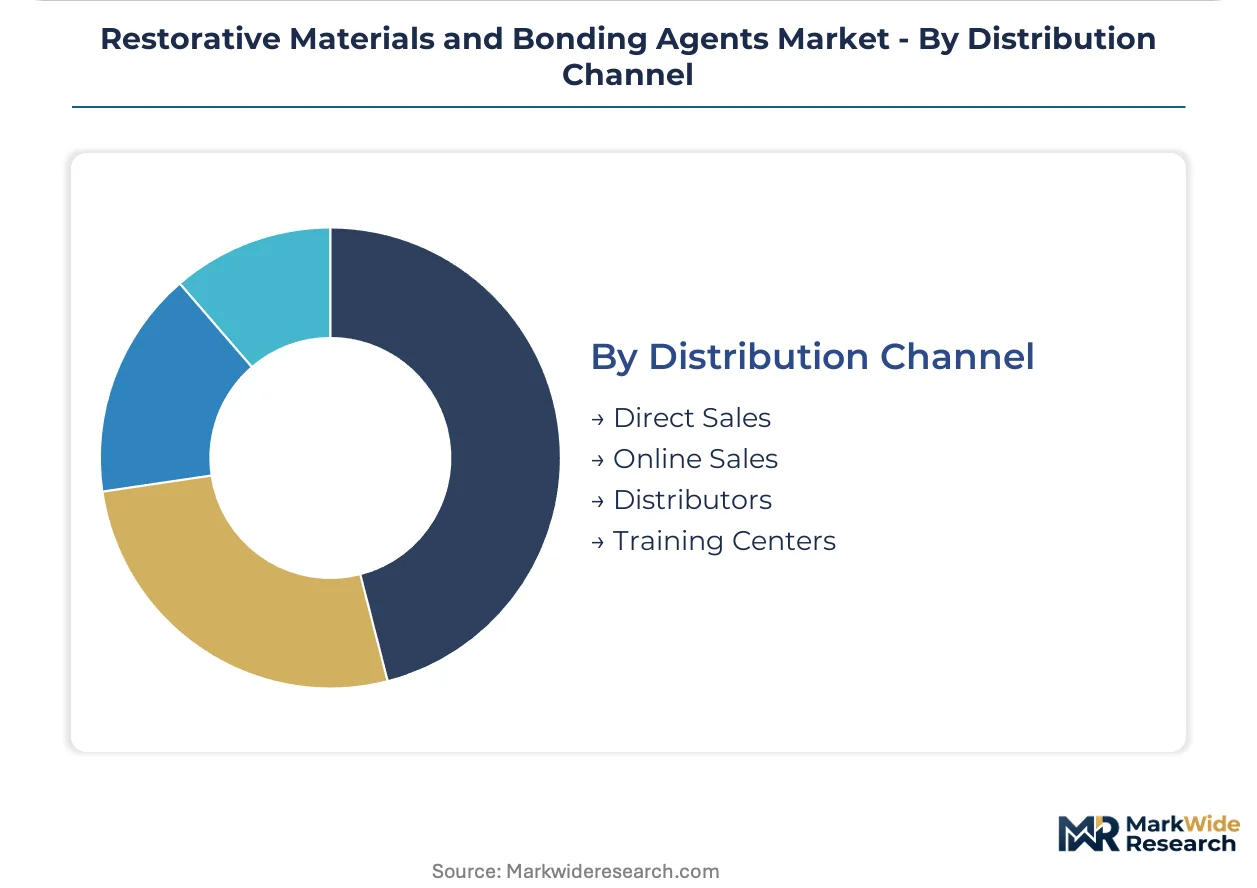
Distribution Channel:
Supply concentration in East Asian chemical processing hubs shapes channel economics for filler particle-dependent composite manufacturers.
- Direct Sales:Manufacturer-to-practice relationships for high-volume dental service organizations. Large DSOs in the United States are implementing direct-to-manufacturer purchasing agreements that displace traditional distributor relationships.
- Online Sales:E-commerce platforms serving small practices and rural clinics with fragmented ordering patterns. India's expanding digital payment infrastructure is accelerating platform adoption for bonding agent replenishment in tier-2 and tier-3 cities.
- Distributors:Regional wholesalers maintaining local inventory and technical service capabilities.
- Training Centers:Educational institutions bundling material procurement with continuing education credits.
Transaction volume flows through Distributors; channel growth is climbing the fastest in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Oral Health Program and Brazil's SUS dental expansion are concentrating public procurement volumes in designated special economic zones for medical device distribution. These government-backed schemes are reshaping regional demand patterns for adhesive restorative protocols.
United States
FDA 510(k) clearance pathways govern permanent restorative materials, with dental service organizations consolidating procurement through direct-to-manufacturer agreements. Large DSOs in Texas and Florida are displacing traditional distributor relationships. The Greater Boston cluster anchors biocompatibility testing infrastructure serving multi-jurisdiction regulatory submissions.
Germany
EU Medical Device Regulation implementation has strained notified body certification capacity, extending adhesive system approval timelines. The Baden-Württemberg region hosts specialized toxicological testing laboratories supporting MDR documentation. Stuttgart-based research clusters are automating post-market surveillance systems for Class IIa dental devices.
India
The National Oral Health Program is broadening access to preventive and restorative oral care in public dental clinics. BIS standards alignment with ISO 10993 reduces regulatory friction for imported bonding agents. Maharashtra's Mumbai-Pune corridor concentrates dental clinic network expansion and tier-2 city digital payment infrastructure for online material replenishment.
Brazil
Brazil's unified health system is scaling restorative procedure coverage, creating volume opportunity for economy-tier bonding agents. ANVISA regulates permanent implantable materials under harmonized Mercosur frameworks. São Paulo's industrial districts anchor composite resin manufacturing serving Latin American distribution channels.
Japan
PMDA oversees dental device approvals with emphasis on clinical evidence for novel monomer formulations. METI initiatives support digital workflow integration in group dental practices. The Osaka-Kobe manufacturing belt concentrates glass ionomer production for moisture-tolerant pediatric applications across East Asian markets.
Restorative Materials and Bonding Agents Market Competitive Landscape
Top-tier vendors anchor premium ceramic and adhesive chemistry segments, while mid-tier specialists occupy fluoride-releasing and economy-composite niches. The vendor base organizes around three strategic archetypes: integrated dental conglomerates with laboratory-to-clinic portfolios, regional specialists in ionomer or resin matrices, and materials-science platforms leveraging chemical processing scale. Dominant competitive moves include vertical integration into filler particle supply and strategic partnerships with chairside CAD/CAM system manufacturers.
Within the premium ceramics and adhesive systems tier, Ivoclar Vivadent and 3M exemplify divergent specialization strategies. The Liechtenstein-based Ivoclar Vivadent occupies a position in anterior restoration aesthetics, while the Minnesota-based 3M anchors universal adhesive chemistry platforms. GC Corporation, a Tokyo-based Co., Ltd., represents the fluoride-releasing formulation archetype targeting caries-prone patient populations.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| Kuraray Noritake Dental |
| 3M |
| GC Corporation |
| BISCO |
| Dentsply Sirona |
| VOCO GmbH |
| Shofu Dental |
| Kerr Dental |
| Others |
Value Network & Pricing Analysis
Dental service organization procurement concentration in the United States is compressing supplier margins and forcing tiered pricing structures that separate enterprise contract rates from spot purchases for independent practices. Brazil's SUS dental expansion and India's National Oral Health Program are anchoring economy-tier pricing floors for glass ionomer and economy composite categories across public procurement channels.
Pricing Analysis
Short lead-time premiums for ISO 10993-certified adhesive systems command 15-25% markups over standard inventory cycles in EU markets strained by MDR notified body bottlenecks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy-tier composites is intensifying because Brazilian and Indian government tenders prioritize unit cost over technical service bundling. Public dental clinics in emerging economies exhibit highest price sensitivity, while US-based DSOs trade price for supply security and standardization guarantees.
Supply Chain Analysis
Direct-to-DSO channels handle hyperscale buyer demand in North America, while regional distributors maintain technical service relationships with fragmented independent practices. Specialty filler particle production clusters in Japan, Germany, and South Korea, creating input vulnerability for composite resin manufacturers dependent on silica and zirconia nanofillers. Raw material sourcing draws from East Asian chemical processing hubs for adhesive monomers and fluoroaluminosilicate glass precursors. Single-source vulnerability concentrates in zirconia filler supply for high-aesthetic anterior restorations. Distribution runs through authorized dental distributors in Europe and direct manufacturer relationships in consolidated US markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR documentation burdens and DSO procurement concentration are forcing mid-tier adhesive suppliers toward acquisition or exit. Manufacturers lacking toxicological testing infrastructure face unsustainable compliance costs.
For Market Incumbents: Lock in post-market surveillance capabilities and captive filler particle supply to defend against supply disruption and regulatory documentation demands. Backward integration into zirconia nanofiller production reduces exposure to East Asian supply concentration. CE marking pathway acceleration through Stuttgart-based toxicological testing partnerships preserves approval timeline advantages over resource-constrained competitors. For New Entrants and Emerging Players: Rural Indian dental clinics represent the most penetrable buyer archetype, underserved by existing distribution networks despite National Oral Health Program volume expansion. Tier-2 and tier-3 Brazilian municipalities under the SUS dental program offer comparable white-space opportunity for economy-tier glass ionomer formulations. Digital platform go-to-market angles leveraging India's expanding payment infrastructure bypass traditional distributor cost structures. For Investors and Strategic Acquirers: The window for entry favors mid-tier adhesive specialists with existing ISO 10993 testing infrastructure and established notified body relationships. Long-term viability hinges on five-year clinical registry maintenance capabilities mandated by EU MDR Class IIa requirements. Watch for MDR approval timeline normalization as the signal indicating consolidation pressure easing and valuation recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Stuttgart toxicology clusters reduce MDR approval delays for novel monomer formulations. |
| Backward Integration into Filler Supply | Captive zirconia nanofiller production insulates margin from East Asian supply volatility. |
| Digital Platform Distribution Launch | India's tier-2 payment infrastructure enables direct clinic replenishment bypassing distributors. |
| Post-Market Surveillance System Buildout | Five-year clinical registries satisfy EU MDR Class IIa evidence requirements for durable claims. |
| Hospital System Partnership Development | Academic medical center contracts anchor high-complexity core build-up material volumes. |
Research Methodology
Multi-period observation of adhesive system approval timelines, DSO procurement contract structures, and government tender patterns anchored the trend analysis, supplemented by interviews with dental materials R&D directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at notified bodies. Secondary validation drew from FDA 510(k) clearance databases, EUDAMED MDR registration filings, ANVISA Mercosur harmonization notices, and BIS standards alignment documents. Bottom-up volume modeling across product categories triangulated against top-down macro healthcare expenditure projections.
Input-output matrices mapped composite resin, glass ionomer, and ceramic demand to end-user segments, application types, and geographic regulatory clusters across the projection horizon. Segmentation dimensions included material chemistry class, procedure complexity tier, buyer consolidation level, and reimbursement code eligibility. CAGRs were derived from regression analysis of historical placement volumes against dental workforce expansion and public health program budget trajectories. Forecast inputs incorporated silica nanofiller supply elasticity and MDR notified body capacity constraints.
Revisions become necessary when EU MDR implementation delays extend beyond modeled timelines, when Brazilian or Indian government health program budgets face austerity adjustments, or when novel bioceramic chemistries displace traditional resin bonding protocols. Periodic stress-testing of base assumptions against regulatory filing backlogs and raw material spot price movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market