
 South America Concrete Admixtures Market | 2026-2036
South America Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
South America Concrete Admixtures Market Analytics
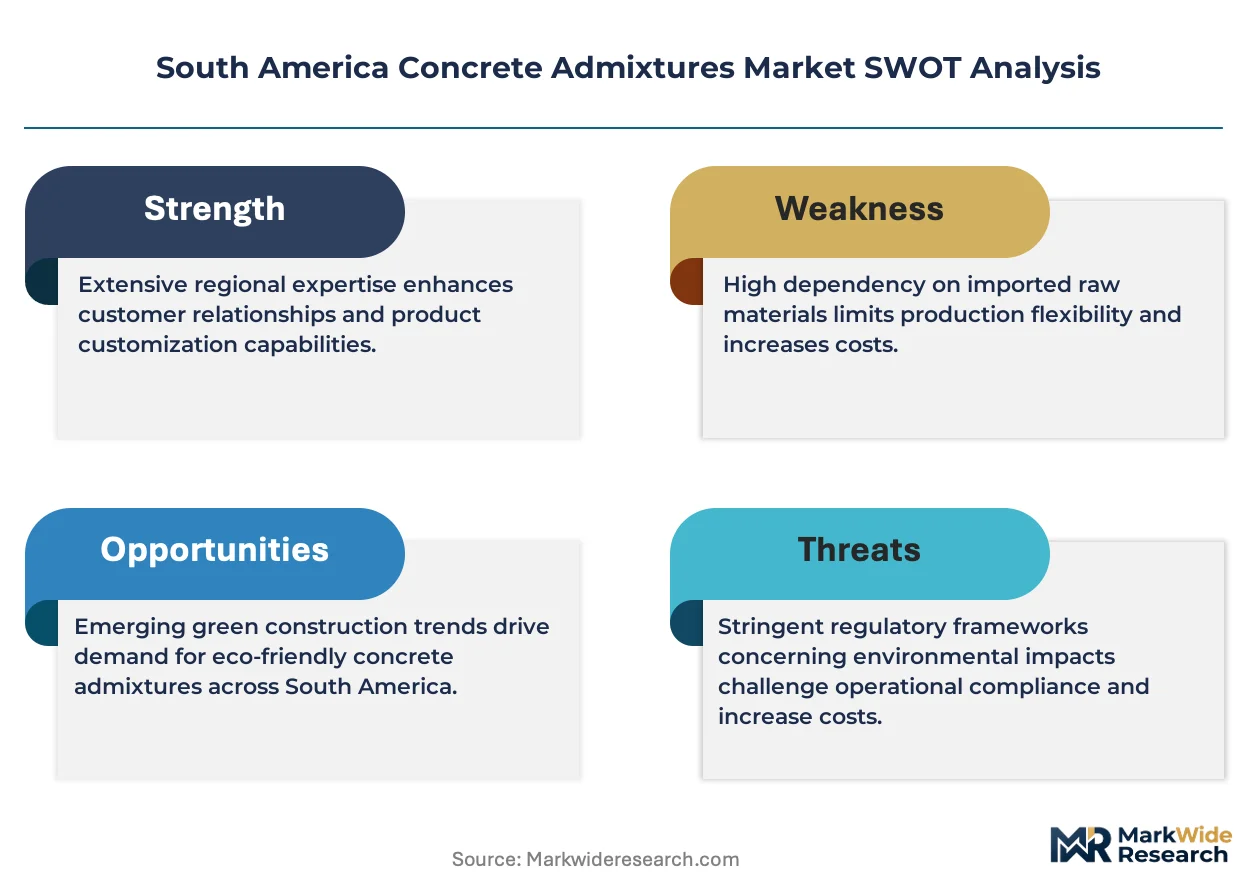
Brazil's updated national construction code is broadening the cost-of-entry calculus for admixture suppliers by mandating performance-grade certifications for structural concrete applications. Sika AG leverages its regional blending network to sustain specification-grade supply across Brazilian infrastructure corridors. BASF SE anchors its position through backward integration into polycarboxylate ether polymers, controlling raw material quality and batch consistency. GCP Applied Technologies Inc. differentiates via proprietary shrinkage-reducing chemistries that compete on durability warranties for coastal and humid-zone projects.
Concrete admixtures comprise chemical formulations—typically lignosulfonates, naphthalene sulfonates, polycarboxylate ethers, or specialty corrosion inhibitors—dosed at 0.5% to 5% by weight of cementitious content to modify rheology, set time, or hardened-state performance in fresh and cured concrete. Their primary industrial purpose centers on enabling high-strength, low-permeability concrete placements under variable ambient conditions while reducing water-to-cement ratios without sacrificing workability. Superplasticizers command the dominant share of product-type value pools due to their indispensability in self-consolidating and high-performance concrete specifications across Brazilian and Colombian megaprojects. Ready-mixed technology leads volume throughput where batch-plant quality control offsets site-mix variability, though specialty products capture disproportionate margins in precast segments demanding accelerated curing cycles.
ANVISA oversees chemical safety registrations for construction additives in Brazil, while Colombia's national infrastructure agency enforces conformity assessment protocols for materials used in public works contracts. Argentina's IRAM standards and Peru's technical building codes create overlapping compliance layers that shape product formulation strategies and cross-border certification costs. Stakeholders must monitor pending harmonization between Mercosur technical regulations and Chilean NCh standards, as alignment would compress time-to-market for multi-country suppliers while potentially elevating testing burdens for single-market operators.
Market Dynamics
Brazil's updated national construction code is compressing specification timelines by mandating performance-grade certifications for all structural concrete applications, forcing admixture suppliers to accelerate batch-plant quality upgrades or exit the market.
Growth Catalysts
- ANVISA chemical safety registrations:Brazil's tightened additive oversight is elevating specification standards across São Paulo's infrastructure corridor, filtering out low-grade imports and concentrating procurement among certified domestic blenders.
- Green building certifications:LEED and equivalent standards in Colombia and Peru are elevating demand for low-carbon concrete formulations that rely on polycarboxylate ether superplasticizers to maintain workability at reduced cement content.
- Precast concrete acceleration:Brazil's housing deficit programs are driving specification of rapid-curing admixtures in factory-cast wall and floor systems, compressing production cycle times by half versus conventional cast-in-place methods.
Market Restraints
- Petrochemical feedstock volatility:Naphthalene and polycarboxylate ether raw material costs fluctuate with Brazilian refinery output and import parity pricing, compressing margin predictability for regional compounders lacking backward integration.
- Cross-border certification costs:Argentina's IRAM standards and Peru's technical building codes create overlapping compliance layers that duplicate testing burdens for single-market operators attempting multi-country expansion.
- Portland cement substitution:Fly ash and ground granulated blast-furnace slag displacement of clinker in low-carbon concrete reduces total cementitious content, mechanically lowering admixture dosing volumes per cubic meter placed.
Strategic Opportunities
- Peru's infrastructure agency protocols:The country's national building code harmonization process is opening specification windows for foreign suppliers that pre-certify to emerging technical standards ahead of final promulgation.
- Self-consolidating concrete in Colombia:Bogotá's tunnel and metro expansion projects are specifying fluid, non-vibrated placements that demand high-range water reducers at dosage rates triple conventional superplasticizer applications.
- Corrosion inhibitor convergence:Coastal projects across Brazil's northeastern states are specifying calcium nitrite and organic inhibitor blends for marine exposure, creating premium formulation segments distinct from commodity plasticizers.
Industry Challenges
- Batch-plant technician certification:Brazil's construction code mandates trained personnel for admixture dosing verification, but vocational programs have not scaled to meet demand across Minas Gerais and Rio de Janeiro states.
- Legacy quality control system integration:Family-owned ready-mix operations throughout Colombia's interior lack automated dosing verification, forcing manual reconciliation that slows specification-grade product adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Concrete Admixtures Market |
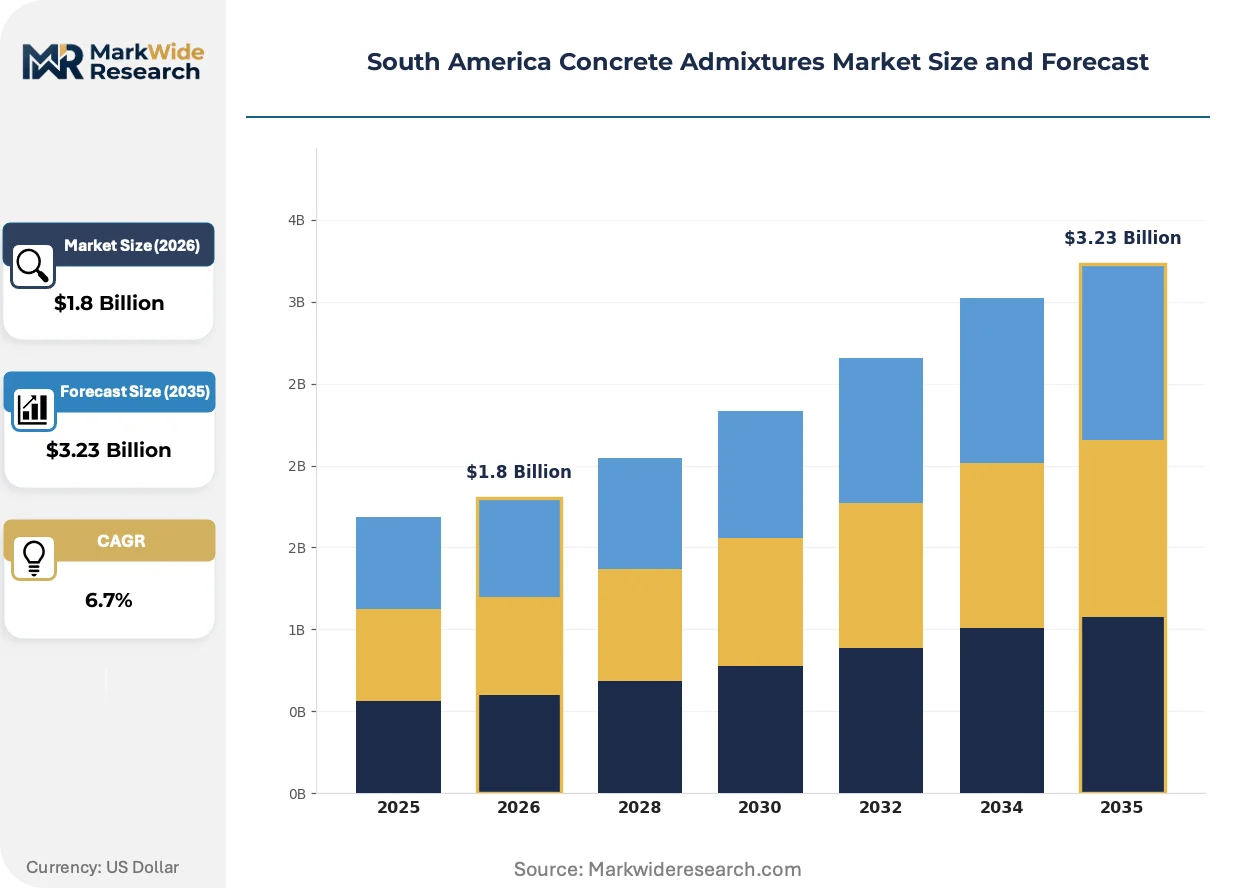
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Retainers, Superplasticizers, Air Entertainment Agents, Set Retarders Technology: Ready-Mixed, Precast, Site-Mixed, Specialty Products End User: Residential Construction, Commercial Construction, Infrastructure Projects, Industrial Applications Delivery Mode: Bulk Delivery, Bagged Delivery, On-Site Mixing, Pre-Packaged Solutions |
| Companies Covered | GCP Applied Technologies Inc., RPM International Inc., Sika AG, Loma Negra Compañía Industrial Argentina S.A., Kryton International Inc., BASF SE, MAPEI S.p.A., Votorantim Cimentos S.A., CEMEX S.A.B. de C.V., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Concrete Admixtures Market Evolving Landscape
Formulation chemistry is pivoting toward multifunctional admixtures that combine rheology control with durability enhancement, compressing the traditional product segmentation between plasticizers and specialty inhibitors.
Polycarboxylate ether polymer architecture is converging with nano-silica dispersion technology to produce single-dose admixtures that simultaneously reduce water demand and refine pore structure. Brazilian precast manufacturers are specifying these hybrid formulations for accelerated curing cycles in wall panel production. The convergence is compressing procurement decisions by collapsing separate superplasticizer and densifier purchase orders into unified supply agreements.
Colombia's national infrastructure agency is enforcing conformity assessment protocols that mandate third-party batch certification for all materials entering public works contracts. The industrial consequence is a bifurcation between certified compounders eligible for state tenders and uncertified suppliers restricted to private residential work. Ready-mix concrete producers in Bogotá and Medellín are responding by consolidating supplier relationships to reduce audit surface area.
Specification-grade procurement is consolidating around engineering-procurement-construction firms that bundle admixture selection with structural warranty obligations. Traditional distributor networks in Brazil's interior states are losing volume to direct manufacturer relationships with national construction groups. The shift is most visible in São Paulo's commercial high-rise segment, where contractor-led value engineering sessions now precede rather than follow admixture specification.
South America Concrete Admixtures Market Segmentation
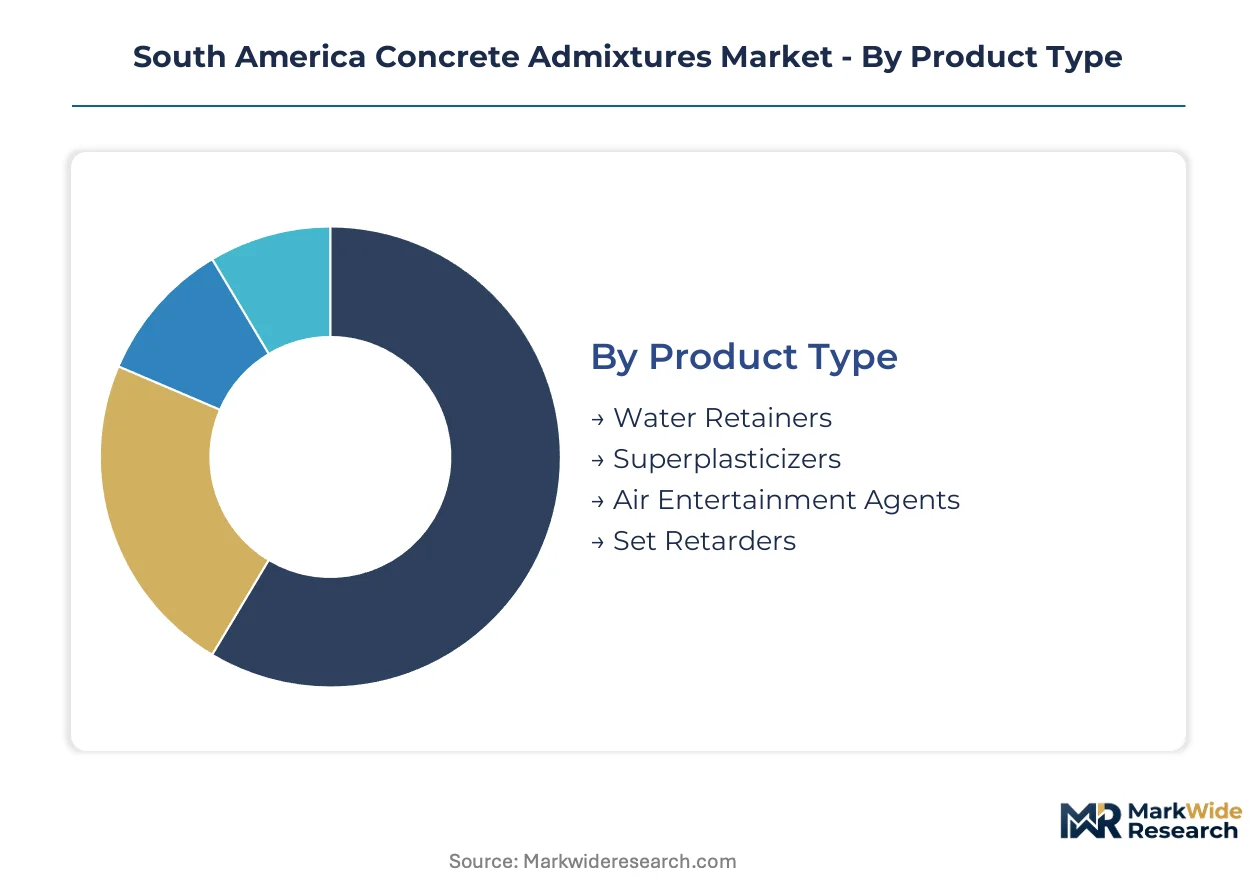
Admixture procurement in South America fragments across formulation chemistry, placement technology, and project scale. Each segmentation axis carries distinct margin profiles and certification burdens that reshape supplier strategies across Brazil, Colombia, and Peru.
Product Type:
Capital intensity peaks with superplasticizer manufacturing, where polycarboxylate ether polymerization demands dedicated reactor infrastructure and quality-control laboratories.
- Superplasticizers:Polycarboxylate ether and naphthalene sulfonate formulations enable high-range water reduction for self-consolidating concrete. Demand concentrates in São Paulo's commercial high-rise corridor, where ANVISA-mandated performance certifications filter out low-grade imports.
- Water Retainers:Cellulose ether and synthetic polymer blends reduce segregation in pumped concrete and elevated placements. Colombian infrastructure projects in Bogotá's tunnel networks specify these additives for vertical transport distances exceeding 200 meters.
- Air Entertainment Agents:Vinsol resin and synthetic surfactant formulations stabilize freeze-thaw resistance in Andean altitude construction.
- Set Retarders:Hydroxycarboxylic acid and lignosulfonate blends extend workability windows in Brazil's tropical heat zones.
Most installed capacity flows through Superplasticizers. Expansion is steepest in Water Retainers as pumped concrete specifications spread beyond coastal metros.
Technology:
Volume throughput and margin capture diverge sharply between automated batch-plant operations and labor-intensive site mixing.
- Ready-Mixed:Centralized batch-plant production with automated dosing systems dominates São Paulo and Rio de Janeiro metropolitan zones. Brazil's updated construction code mandates trained technician certification for dosing verification, elevating compliance costs for family-owned operators in Minas Gerais.
- Precast:Factory-cast wall and floor systems in Brazil's housing deficit programs specify rapid-curing admixtures that compress production cycles. Colombian precast manufacturers are consolidating supplier relationships to reduce audit surface area under national infrastructure agency protocols.
- Site-Mixed:Manual batching persists in Peru's informal construction sector and Colombia's interior ready-mix operations lacking automated dosing verification.
- Specialty Products:Corrosion inhibitors and shrinkage reducers command premium pricing for marine exposure and coastal humidity zones across Brazil's northeastern states.
Ready-Mixed technology anchors volume throughput. Precast is climbing the fastest as factory-cast methods displace conventional cast-in-place construction.
End User:
Project scale and specification rigor create tiered procurement patterns across residential, commercial, and public works segments.
- Infrastructure Projects:Brazilian federal highway and hydroelectric programs specify performance-grade admixtures with third-party batch certification. Peru's national building code harmonization is opening specification windows for foreign suppliers that pre-certify to emerging technical standards.
- Commercial Construction:Engineering-procurement-construction firms in São Paulo bundle admixture selection with structural warranty obligations, displacing traditional distributor networks.
- Residential Construction:Green building certifications in Colombia and Peru are elevating demand for low-carbon concrete formulations that reduce cement content through polycarboxylate ether superplasticizers.
- Industrial Applications:Mining sector concrete specifications in Chile and Peru demand sulfate-resistant formulations for aggressive groundwater exposure.
Infrastructure Projects command the dominant specification-grade volume. Commercial Construction is expanding most quickly as contractor-led value engineering consolidates procurement decisions.
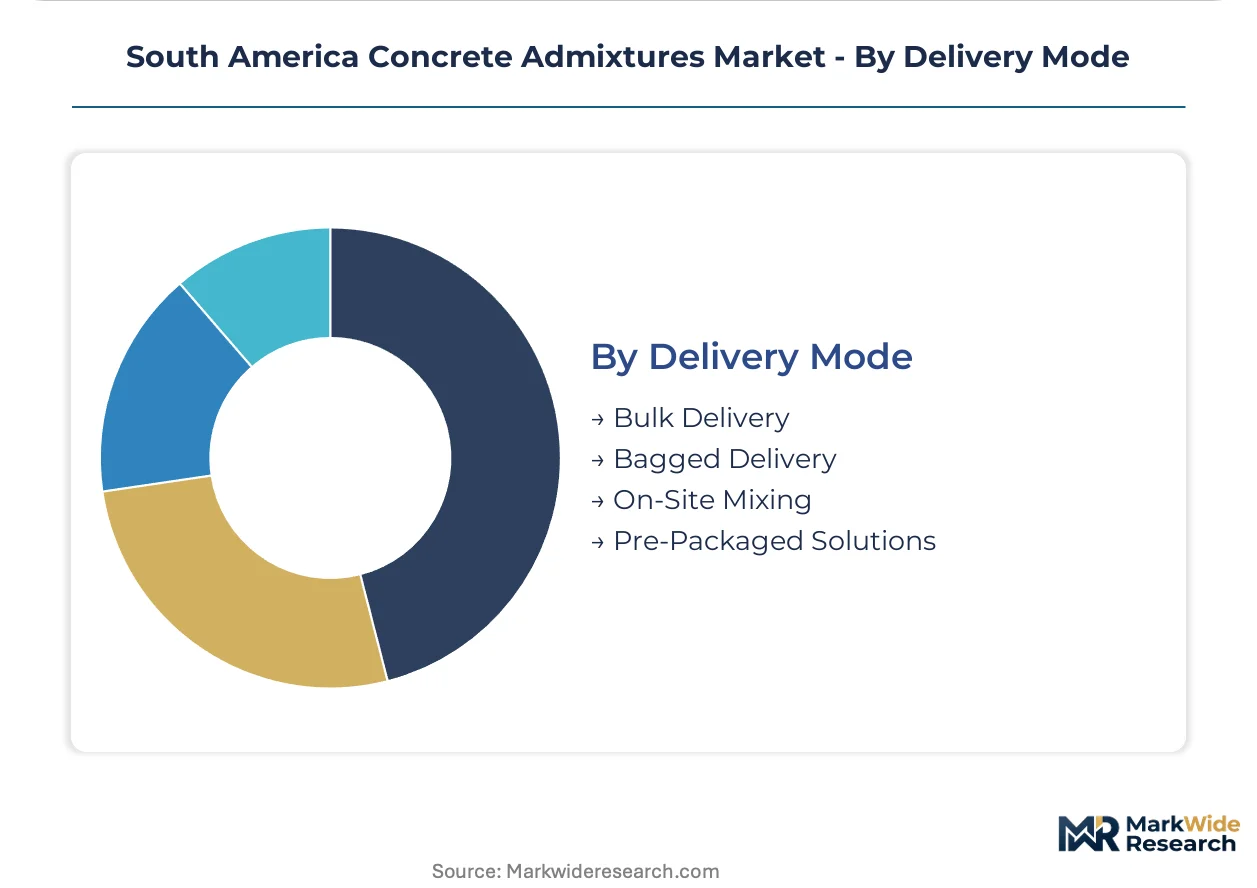
Delivery Mode:
Logistics configuration directly shapes working capital requirements and customer switching costs across the supply chain.
- Bulk Delivery:Tanker truck shipments from regional blending facilities serve ready-mix producers with continuous consumption patterns. Sika AG leverages this network across Brazilian infrastructure corridors to sustain specification-grade supply.
- Bagged Delivery:25-kilogram sacks reach small contractors and remote job sites where batch volumes are unpredictable.
- On-Site Mixing:Mobile blending units deploy to megaproject sites in Peru and Colombia where transportation infrastructure limits central plant access.
- Pre-Packaged Solutions:Single-dose pouches combine superplasticizer and densifier functions for precast manufacturers seeking procurement simplification.
Bulk Delivery carries the heaviest infrastructure investment. Pre-Packaged Solutions are gaining share fastest as hybrid formulations collapse separate purchase orders into unified supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized admixture formulation talent clusters around São Paulo's industrial corridor, anchoring regional technical capability. Brazilian chemical engineers and construction material scientists concentrate in the southeastern states where specification-grade blending facilities operate at scale.
Brazil
Federal highway programs and hydroelectric dam construction drive specification-grade admixture procurement across the southeastern corridor. ANVISA chemical safety registrations filter out low-grade imports, elevating certified domestic blenders. São Paulo, Rio de Janeiro, and Minas Gerais states concentrate batch-plant infrastructure where trained technician certification is now mandatory.
Colombia
Bogotá's metro and tunnel expansion projects specify high-range water reducers for fluid, non-vibrated concrete placements. The national infrastructure agency enforces third-party batch certification for all public works materials. Ready-mix producers in Bogotá and Medellín consolidate supplier relationships to reduce audit burden under conformity assessment protocols.
Peru
National building code harmonization is opening specification windows for foreign suppliers that pre-certify to emerging technical standards. Mining sector concrete specifications demand sulfate-resistant formulations for aggressive groundwater exposure. Lima and coastal infrastructure corridors concentrate procurement decisions for infrastructure agency contracts.
Argentina
IRAM standards create overlapping compliance layers that duplicate testing burdens for multi-country suppliers attempting market entry. Precast concrete manufacturers in Buenos Aires province specify rapid-curing admixtures for housing deficit programs. The industrial corridor between Buenos Aires and Rosario anchors domestic blending capacity.
Chile
Mining sector specifications in the northern desert regions drive demand for durability-enhancing formulations. Pending harmonization between Mercosur technical regulations and Chilean NCh standards would compress time-to-market for regional suppliers. Santiago's commercial construction sector concentrates specification-grade procurement decisions.
South America Concrete Admixtures Market Competitive Landscape
The competitive structure tilts toward multinational chemical conglomerates with backward integration into polymer feedstocks. Regional blending specialists and construction material distributors occupy secondary tiers beneath integrated manufacturers. Three archetypes dominate: polymer producers controlling raw material quality, regional compounders with specification-grade certification networks, and precast-focused rapid-curing specialists. Capacity expansion and certification pre-positioning constitute the dominant competitive moves as regulatory timelines compress.
Among the multinational tier, Sika AG, BASF SE, and GCP Applied Technologies Inc. represent distinct strategic positions. Sika AG exemplifies the regional blending network archetype with infrastructure corridor coverage. BASF SE occupies the integrated polymer producer position through captive supply of polycarboxylate ether raw materials. GCP Applied Technologies Inc. represents the specialty formulation segment with differentiated durability chemistries. These three anchors illustrate how competitive positioning fragments across supply chain control points rather than converging on a single winning model.
| Leading Market Players |
|---|
| GCP Applied Technologies Inc. |
| RPM International Inc. |
| Sika AG |
| Loma Negra Compañía Industrial Argentina S.A. |
| Kryton International Inc. |
| BASF SE |
| MAPEI S.p.A. |
| Votorantim Cimentos S.A. |
| CEMEX S.A.B. de C.V. |
| Others |
Value Network & Pricing Analysis
Federal highway procurement programs across Brazil's southeastern corridor anchor pricing power for specification-grade admixture suppliers, compressing negotiations into long-term contract structures that penalize spot-market variability. Bundled engineering warranties and third-party batch certification costs flow through to buyers as non-negotiable line items, while unbundled commodity plasticizers compete on per-liter spot pricing in informal construction segments.
Pricing Analysis
Bundled service contracts dominate specification-grade procurement, with admixture supply tied to structural performance warranties and ANVISA-mandated certification documentation. Price differentiation rests on certification tier and volume scale, with certified domestic blenders commanding premiums over uncertified imports. Cost compression in commodity plasticizers intensifies because naphthalene and polycarboxylate ether feedstock costs fluctuate with Brazilian refinery output. Small residential contractors exhibit highest price sensitivity, while infrastructure agencies prioritize specification compliance over unit cost.
Supply Chain Analysis
Certification gating through ANVISA registrations and Colombia's national infrastructure agency protocols concentrates supply among qualified compounders with laboratory and reactor infrastructure. Production gravity centers on Brazil, with secondary blending capacity in Argentina and Colombia. Raw material dependencies draw from naphthalene sulfonate precursors, polycarboxylate ether polymers, and specialty corrosion inhibitor chemistries. Single-source vulnerability runs through petrochemical feedstock supply tied to Brazilian refinery economics. Distribution runs through bulk tanker networks serving ready-mix batch plants, with pre-packaged solutions penetrating precast factory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border regulatory arbitrage between Brazil's stringent ANVISA protocols and Peru's harmonizing building code creates cost-efficient pre-certification pathways for suppliers willing to front-load compliance investment. The differential in testing burden and timeline compression rewards early movers who establish multi-country certification ahead of formal regulatory alignment.
For Market Incumbents: Acquire regional blending facilities with existing ANVISA certification networks to consolidate specification-grade capacity. Backward integration into polycarboxylate ether polymer production defends margin position against naphthalene feedstock volatility. Channel control through direct relationships with engineering-procurement-construction firms displaces vulnerable distributor networks in São Paulo's commercial high-rise segment. For New Entrants and Emerging Players: Peru's national building code harmonization opens a window for foreign suppliers that pre-certify to emerging technical standards ahead of final promulgation. Target precast concrete acceleration segments in Brazil's housing deficit programs, where rapid-curing admixture demand outpaces certified domestic supply. A technical partnership with established regional compounders accelerates market access while compliance infrastructure scales. For Investors and Strategic Acquirers: Specialty chemical conglomerates with construction sector portfolios are the most active acquirer in this space, seeking specification-grade certification assets. The five-to-ten year viability window favors targets with backward integration into polymer feedstocks and multi-country regulatory clearance. Watch for Mercosur-Chile NCh standard harmonization announcements as the inflection signal for compressed cross-border expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | BASF SE's captive polycarboxylate ether supply secures batch consistency against import parity volatility. |
| Regional Blending Network Expansion | Sika AG's corridor coverage sustains specification-grade delivery across Minas Geras infrastructure zones. |
| Hybrid Formulation Development | Nano-silica dispersion convergence collapses separate superplasticizer and densifier procurement decisions. |
| Third-Party Certification Pre-Positioning | Peru's harmonization process rewards suppliers with advance technical standard compliance. |
| Direct EPC Channel Relationships | Contractor-led value engineering in São Paulo displaces traditional distributor intermediaries. |
Research Methodology
Coverage spans Brazil, Colombia, Peru, Argentina, and Chile, with primary inputs from each market's construction chemicals sector. Plant managers at ready-mix batch facilities, procurement leads at national infrastructure agencies, technical R&D directors at admixture compounders, and channel partners in construction material distribution provided structured interviews. Secondary validation drew from ANVISA chemical safety registries, Colombian national infrastructure agency conformity protocols, customs and trade data for naphthalene and polycarboxylate ether imports, and SEC filings for multinational chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across product type, technology, and end-use segmentation.
Rate-of-change decomposition anchored the analytical framework, with growth drivers assessed across formulation chemistry evolution, regulatory timeline compression, and infrastructure project pipeline expansion. Segmentation dimensions modeled include product type tier, placement technology, project scale category, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points and feedstock cost cycle positioning. Industry-specific inputs incorporated ANVISA registration backlog timelines, precast factory capacity expansion announcements, and Mercosur technical regulation harmonization status.
Revisions become necessary when petrochemical feedstock cost cycles shift dramatically, regulatory harmonization timelines accelerate or stall, or infrastructure procurement program budgets face material adjustment. Forecasts reflect assumptions regarding certification barrier persistence, polymer architecture innovation adoption curves, and contractor consolidation trends. A model refresh is warranted upon material change in Brazil's national construction code enforcement intensity or Peru's building code harmonization promulgation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Volatile Corrosion Inhibitors Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Ammonium Phosphatide Market
Additives
Dishwashing Additives Market
Additives
Paint Additives Market
Additives
Potting Mix Additives Market
Additives
Global Cement Additives Market
Additives
Potassium Nitrate Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Glyceryl Caprylate Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Metallic Stearate Market
Additives
Engine Oil Additive Market
Additives
Global Mold Release Agents Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Refinery Fuel Additives Market