
 Wood Preservation Chemicals Market | 2026-2036
Wood Preservation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Preservation Chemicals Market Intelligence
Multi-source procurement among treated-wood producers is hardening as supply-chain resilience replaces cost minimization. BASF SE leverages its integrated copper-amine chemistry platform to secure feedstock reliability across multiple continents. Koppers Performance Chemicals anchors North American rail-tie treatment through captive creosote distillation and regional terminal networks. Lanxess AG differentiates via borate-based systems that target residential builders seeking alternatives to traditional copper formulations.
Wood preservation chemicals are formulations containing biocidal active ingredients—copper azole, alkaline copper quaternary, or disodium octaborate tetrahydrate—applied to lumber through pressure-vacuum impregnation to extend service life against fungal decay and insect attack. The treatment process typically forces solutions into cell structures under 150 psi, achieving retention thresholds measured in pounds per cubic foot for above-ground or ground-contact use. Copper-based products dominate volume due to established building-code acceptance and contractor familiarity, while borate-based alternatives capture margin in interior framing and remedial applications where human contact risk governs selection. Organic solvent carriers retain niche share in specialty millwork and export timber requiring rapid drying cycles.
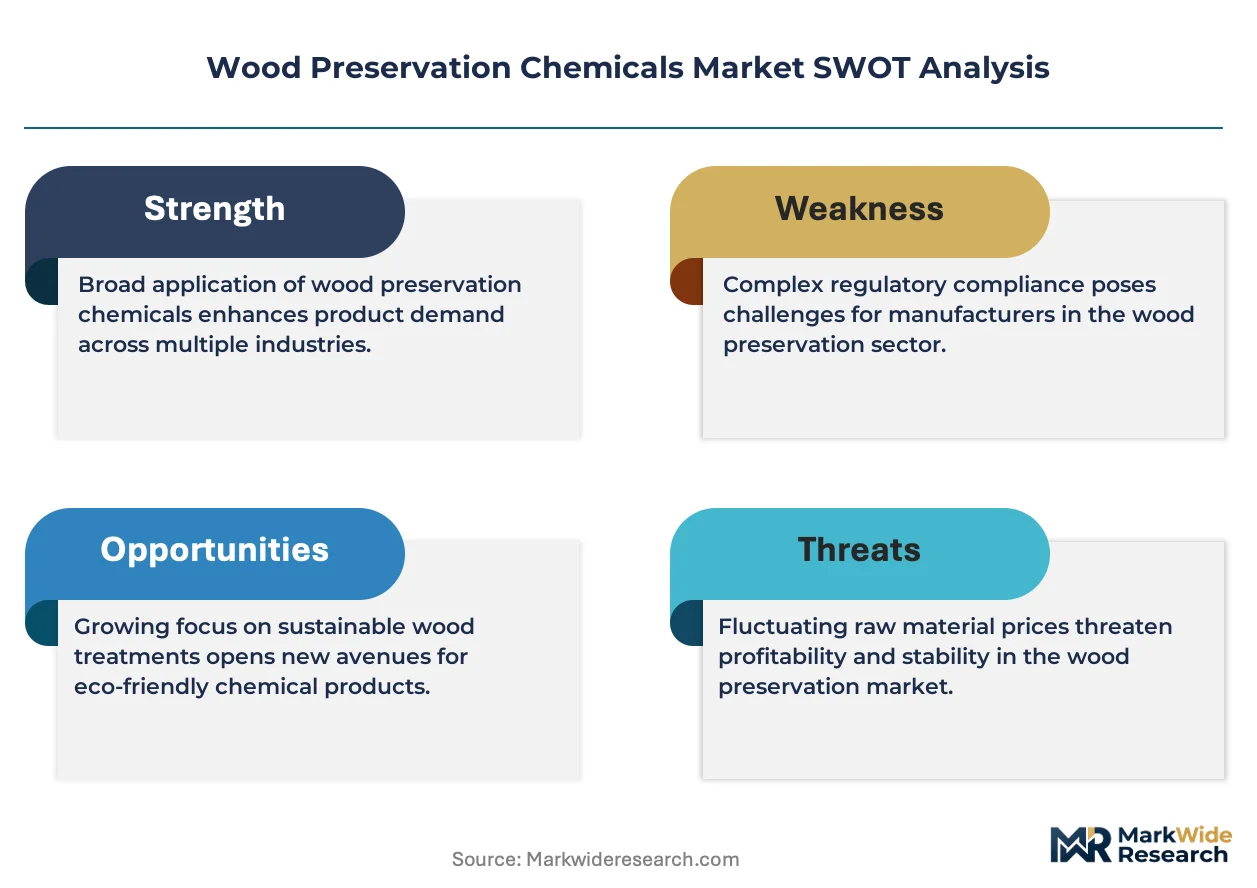
The EPA regulates wood preservative pesticides under FIFRA, requiring efficacy data and environmental fate studies that extend registration timelines and favor incumbents with regulatory affairs capacity. REACH restrictions in Europe limit certain chromium and arsenic compounds, redirecting formulation investment toward copper-amine and micronized particulate systems. OSHA workplace exposure standards for treatment plant operators influence automation spending and chemical handling infrastructure design. Stakeholders must track how building-code adoption of mass timber and cross-laminated lumber creates parallel demand for in-factory treatment chemicals versus field-applied solutions.
Market Dynamics
The EPA's reregistration review of copper-based wood preservatives is compressing formulation timelines and forcing active-ingredient substitution toward lower-leaching copper-amine and micronized particulate systems before 2027 compliance deadlines.
Growth Catalysts
- Infrastructure Renewal Programs:United States federal highway and bridge rehabilitation mandates are accelerating rail-tie and timber-piling replacement cycles, sustaining chemical offtake through 2030.
- REACH Phase-Out Directives:European chromium and arsenic compound restrictions are redirecting formulation investment toward copper-amine systems, expanding addressable market for compliant suppliers.
- Mass Timber Building Codes:Cross-laminated lumber and glue-laminated timber adoption in commercial construction is creating parallel demand for in-factory treatment chemicals versus field-applied solutions.
Market Restraints
- Copper Price Volatility:Fluctuations in copper sulfate and copper carbonate feedstock costs compress margin visibility for formulators locked into annual supply contracts.
- Concentrated Creosote Supply:North American rail-tie treatment depends on captive distillation capacity concentrated among three regional operators, creating single-source vulnerability.
- Leaching Performance Trade-offs:Lower-copper alternatives sacrifice ground-contact durability, limiting substitution in structural foundation and marine piling applications.
Strategic Opportunities
- Interior Framing Penetration:Borate-based systems targeting residential builders in moisture-prone US Southeast and Pacific Northwest submarkets offer margin expansion above commodity copper formulations.
- Remedial Treatment Services:In-situ borate injection for existing deck and fence infrastructure addresses the 40-million-home US housing stock aged beyond original treatment life.
- Export Timber Certification:ISPM-15 heat-treatment alternatives using organic solvent carriers capture specialty millwork shipments requiring rapid drying cycles to Asian and Middle Eastern destinations.
Industry Challenges
- Pressure-Vessel Certification Delays:ASME and National Board inspection backlogs extend treatment plant commissioning timelines, constraining capacity expansion for independent treaters.
- Active-Ingredient Handling Expertise:Copper-amine chemistry requires specialized process engineering talent scarce outside legacy agricultural chemical and pharmaceutical manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Preservation Chemicals Market |
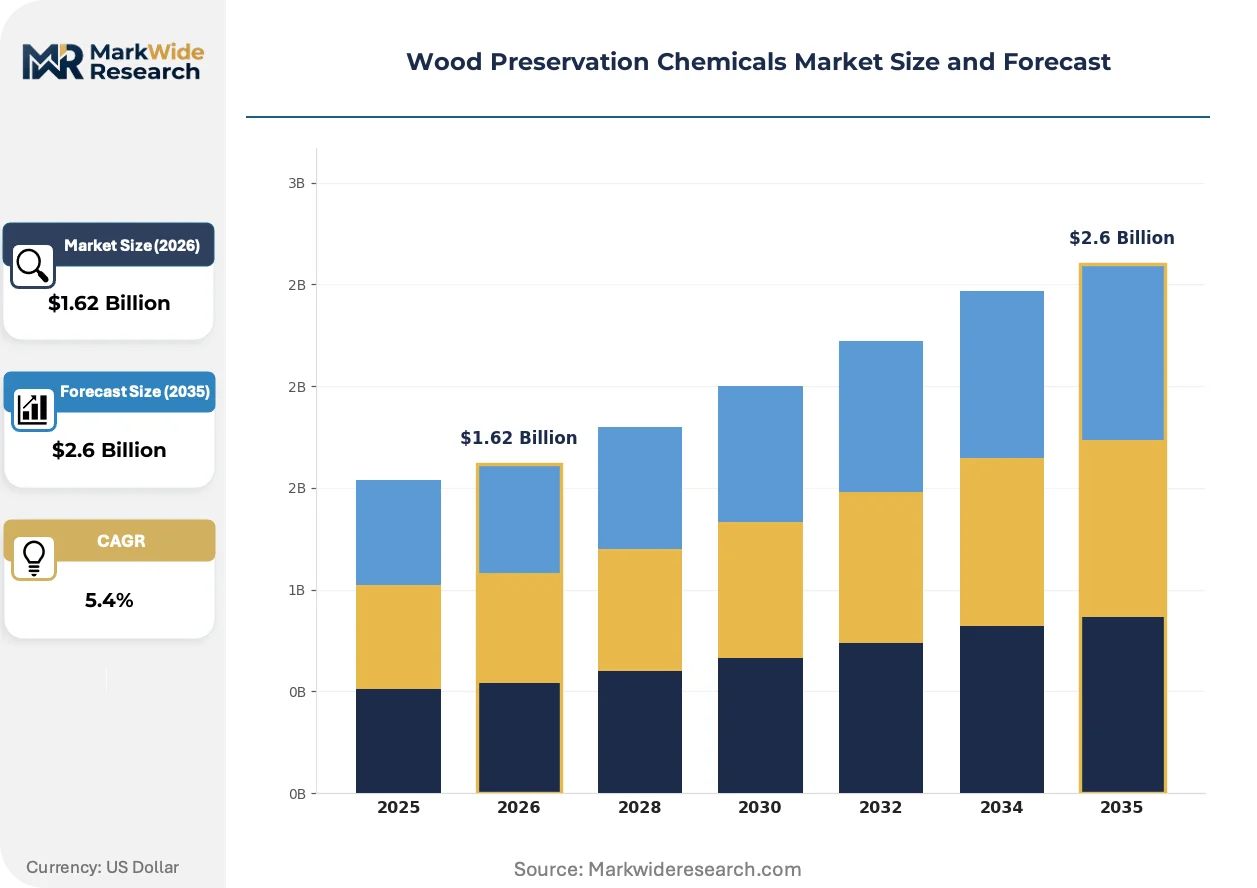
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-Based, Borate-Based, Organic Solvents, Biocides Application: Residential, Commercial, Agricultural, Industrial Form: Liquid, Gel, Foam, Powder End User: Contractors, Manufacturers, DIY Users, Distributors |
| Companies Covered | BASF SE, Kurt Obermeier GmbH & Co. KG, Koppers Performance Chemicals, KMG Chemicals Inc., RUTGERS Organics GmbH, Lanxess AG, Viance LLC, Janssen Preservation and Material Protection, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Preservation Chemicals Market Strategic Shifts & Innovations
Formulation science and treatment automation are converging to reduce chemical retention variance and labor exposure while regulatory pressure accelerates active-ingredient substitution cycles.
Micronized copper particulate systems are automating retention uniformity in pressure-vacuum impregnation cycles. Regional treaters in the US Southeast and Pacific Northwest are retrofitting existing cylinder infrastructure to accommodate sub-micron dispersion chemistry. This automation is compressing re-treatment rates and warranty claim exposure for above-ground decking applications.
REACH authorization procedures for chromium trioxide and arsenic-based wood preservatives are eliminating legacy preservative options from EU-27 supply chains. Formulators are redirecting R&D expenditure toward copper-ethanolamine complexes and quaternary ammonium compound blends. Marine piling and utility pole segments in Northern Europe are absorbing the steepest cost increases as they transition from chromated copper arsenate.
Multi-source chemical procurement is displacing single-supplier relationships among integrated treated-wood producers. Large North American lumber treaters are qualifying secondary copper-amine formulators and captive borate distributors to reduce concentration risk. This pattern is most visible in the United States, where housing start volatility and EPA registration uncertainty have hardened supply-chain resilience priorities above unit cost minimization.
Wood Preservation Chemicals Market Segmentation
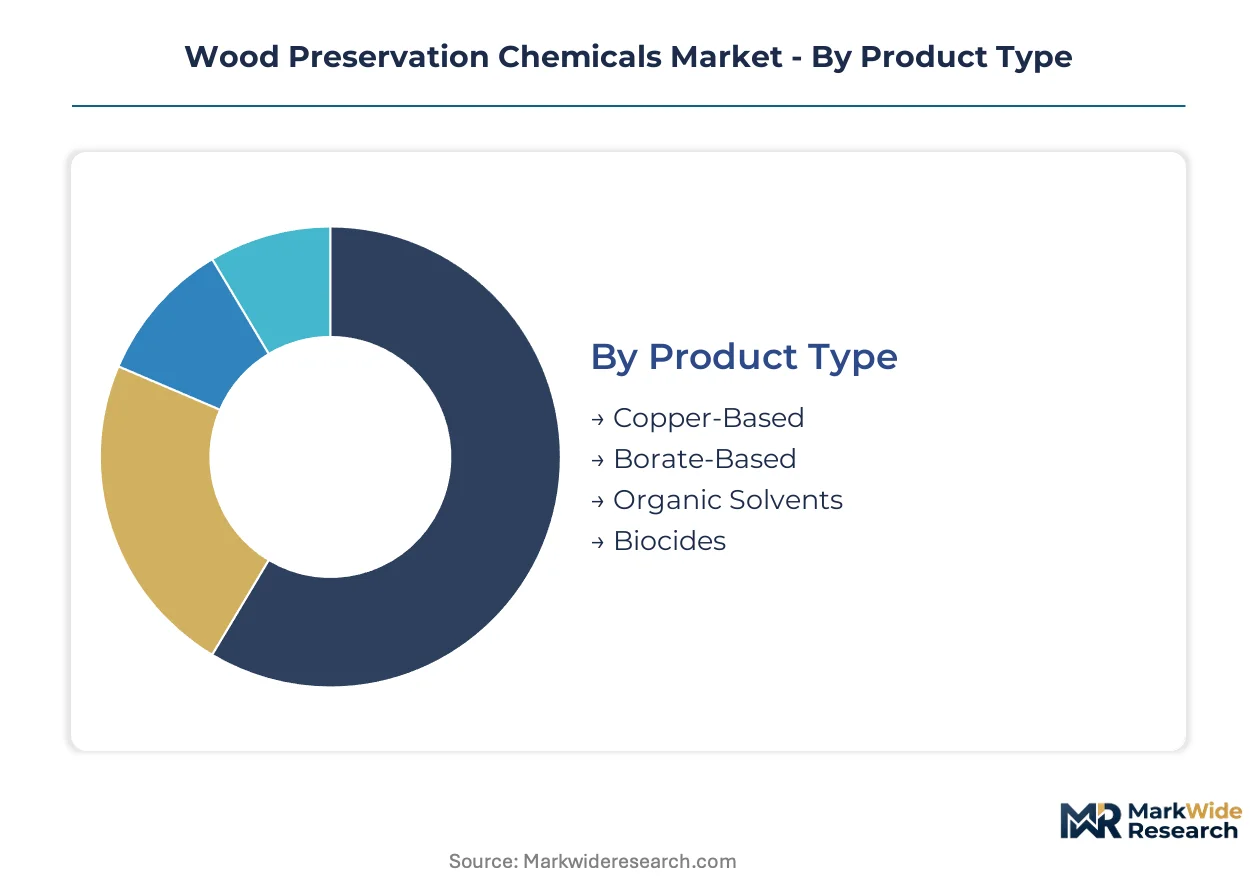
Wood preservation chemical buyers select formulations through layered technical filters. Active-ingredient chemistry, application environment, and end-user capability each narrow the specification funnel before procurement decisions finalize.
Product Type:
Capital intensity varies sharply across chemistries, with copper-amine systems requiring pressure-vessel infrastructure and borate lines demanding climate-controlled storage.
- Copper-Based:Formulations deploy copper azole or alkaline copper quaternary complexes dissolved in ethanolamine carriers. United States residential decking contractors specify these for ground-contact lumber after EPA reregistration tightened leaching standards. Treatment plants must maintain 150 psi pressure vessels and copper-sulfate feedstock security.
- Borate-Based:Disodium octaborate tetrahydrate systems penetrate wood via diffusion rather than pressure impregnation. Pacific Northwest interior framing contractors favor these for moisture-prone crawl spaces where human contact risk governs selection. Lower equipment barriers attract regional treaters without cylinder infrastructure.
- Organic Solvents:Hydrocarbon carriers enable rapid drying cycles for specialty millwork exports.
- Biocides:Synthetic organic actives target insect-specific threats in remedial applications.
Most installed capacity flows through copper-based systems. Expansion is steepest in borate-based alternatives.
Application:
Volume concentration tracks construction cycle intensity, with infrastructure mandates sustaining offtake through public procurement channels.
- Residential:Outdoor decking, fencing, and structural framing absorb the majority of treated lumber volume. United States housing starts in the Southeast and Mountain West drive specification toward above-ground retention standards. Single-family builders prioritize warranty-backed treatment certifications.
- Commercial:Mass timber projects specify in-factory treatment for cross-laminated and glue-laminated members. Pacific Northwest and Nordic commercial developers specify these for carbon-accounting advantages.
- Agricultural:Vineyard posts and greenhouse framing require ground-contact durability in high-moisture soil.
- Industrial:Rail ties, utility poles, and marine pilings demand maximum retention thresholds.
Residential applications anchor current volume. Commercial mass timber is gaining share fastest.
Form:
Physical state determines equipment compatibility and labor exposure profiles across treatment plant footprints.
- Liquid:Aqueous solutions dominate pressure-vacuum impregnation cycles at integrated treaters. United States regional treaters in the Southeast retrofit cylinders for micronized copper dispersion. Liquid handling requires OSHA-compliant containment and automated metering systems.
- Gel:Viscous formulations enable brush-applied remedial treatment of existing deck infrastructure. DIY users and specialty contractors specify these for in-situ decay arrest without plant processing.
- Foam:Expanding carriers fill voids in utility pole internal decay zones.
- Powder:Dry concentrates reduce shipping weight for field-mixing at remote infrastructure sites.
Liquid forms command the majority of plant throughput. Gel applications are expanding most quickly.
End User:
Procurement sophistication separates volume buyers with analytical testing capabilities from price-sensitive spot purchasers.
- Contractors:Production homebuilders and commercial framing crews specify retention-grade lumber through distributor relationships. United States national builders qualify multiple treaters to hedge against EPA registration delays. Volume contracts include quality-audit clauses and just-in-time delivery terms.
- Manufacturers:Integrated treated-wood producers operate captive pressure-treatment facilities for branded lumber lines. These entities source active ingredients directly and control formulation recipes.
- DIY Users:Retail consumers purchase over-the-counter brush-on preservatives for fence maintenance.
- Distributors:Regional lumber yards stock treated inventory and influence specification through contractor relationships.
Manufacturers and contractors concentrate procurement volume. Distributor influence is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast treatment corridor spanning Georgia, Alabama, and the Carolinas concentrates North American wood preservation capacity. Regional treaters retrofit pressure vessels for micronized copper systems. Housing starts and infrastructure renewal programs sustain chemical offtake through distributor networks.
United States
Federal highway rehabilitation mandates accelerate rail-tie replacement cycles. EPA reregistration reviews under FIFRA compress formulation timelines toward lower-leaching alternatives. The Pacific Northwest cluster around Portland and Seattle drives borate-based specification for moisture-prone residential framing.
Germany
Commercial mass timber projects in Bavaria and Baden-Württemberg absorb copper-amine formulations for cross-laminated members. REACH authorization procedures eliminate chromium trioxide from supply chains. The Rhine-Ruhr industrial corridor hosts reformulation R&D for compliant preservative systems.
China
Export timber certification requirements under ISPM-15 redirect treatment chemical demand toward rapid-drying solvent carriers. GB standards and MEE environmental regulations tighten leaching thresholds. The Yangtze River Delta millwork cluster near Shanghai processes specialty lumber for Asian and Middle Eastern destinations.
Canada
Pacific Northwest housing construction in British Columbia sustains treated lumber demand for outdoor decking. Health Canada and PMMA regulate preservative registration with efficacy data requirements. Ontario's Great Lakes manufacturing belt supplies pressure-treatment equipment to North American regional treaters.
Australia
Termite-prone construction in Queensland and New South Wales drives ground-contact retention specifications. TGA and state-level environmental regulators monitor copper leaching into watersheds. The Sydney-Melbourne corridor concentrates distribution infrastructure for borate and copper-based systems.
Wood Preservation Chemicals Market Key Industry Players
Global majors compete with regional champions across formulation chemistry and feedstock security. The market structures around integrated chemical conglomerates, captive treatment operators, and specialized borate distributors. Three archetypes dominate: copper-amine formulators with multi-continent supply networks, creosote distillers with regional terminal infrastructure, and borate specialists targeting residential alternatives. Competitive moves concentrate on multi-source procurement qualification and pressure-vessel automation retrofits.
Within the integrated chemical tier, BASF SE and Lanxess AG exemplify formulators with captive copper-amine platforms spanning regulatory jurisdictions. Koppers Performance Chemicals anchors the North American rail-tie segment through captive distillation capacity. These three occupy positions defined by feedstock security and treatment plant operator relationships rather than product differentiation alone.
| Leading Market Players |
|---|
| BASF SE |
| Kurt Obermeier GmbH & Co. KG |
| Koppers Performance Chemicals |
| KMG Chemicals Inc. |
| RUTGERS Organics GmbH |
| Lanxess AG |
| Viance LLC |
| Janssen Preservation and Material Protection |
| Lonza Group AG |
| Others |
Cost & Logistics Intelligence
Retention-grade bifurcation between ground-contact and above-ground lumber specifications manifests in both chemical procurement premiums and pressure-vessel infrastructure requirements across North American treaters. EPA reregistration timelines for copper-based systems compress formulation substitution cycles, forcing distributors to qualify secondary copper-amine suppliers while regional treaters absorb ASME certification backlogs.
Pricing Analysis
Copper sulfate and copper carbonate feedstock volatility passes through to formulator margins via annual supply contracts that lack price-adjustment clauses. Three-tier pricing structure across micronized copper, standard copper-amine, and borate-based systems reflects retention-performance differentiation and EPA compliance certification tiers. Pricing pressure stems from concentrated creosote distillation capacity among three North American operators. DIY retail channels exhibit highest price sensitivity; integrated treated-wood manufacturers demonstrate lowest sensitivity due to captive formulation control.
Supply Chain Analysis
Copper-amine chemistry supply rests on Chilean copper mining output, US Gulf Coast ethanolamine production, and German specialty additive manufacturing. Critical inputs include copper sulfate monohydrate, quaternary ammonium compounds, and micronized particulate dispersants. Single-source vulnerability concentrates in North American creosote distillation terminals serving rail-tie treaters. Distribution runs through regional lumber treaters with captive pressure-vessel infrastructure, qualified chemical formulators, and big-box retail channels for consumer brush-on products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wood preservation chemicals constitute a late-cycle quality story as US housing stock ages beyond original treatment life and commercial mass timber codes mandate factory-applied specifications. The demand shift toward lower-leaching micronized copper systems rewards formulators with EPA registration capacity and multi-source feedstock security.
For Market Incumbents: Hedge copper price exposure through backward integration into copper-amine feedstock partnerships or long-term offtake agreements with Chilean mining operations. Diversify formulation portfolios toward borate-based systems before REACH-style restrictions expand to North American jurisdictions. Defensive capacity expansion should concentrate in the US Southeast treatment corridor where housing starts volatility demands supply-chain resilience above unit cost minimization. For New Entrants and Emerging Players: Enter via remedial treatment services targeting the 40-million-home US housing stock with in-situ borate injection technologies that bypass pressure-vessel capital requirements. The most penetrable white space sits in Pacific Northwest interior framing applications where moisture-prone crawl spaces favor diffusion-based borate systems over copper-amine pressure impregnation. A direct contractor-channel go-to-market model bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA registration expertise concentrates among legacy agricultural chemical and pharmaceutical manufacturing regions. Long-term viability favors formulators with captive copper-amine platforms spanning multiple regulatory jurisdictions. Target acquisition archetypes include regional borate distributors with climate-controlled storage infrastructure and established contractor relationships. The signal to watch is ASME pressure-vessel inspection backlog resolution, which would unlock independent treater capacity expansion and chemical offtake acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Feedstock | Captive copper-amine supply secures margin visibility against Chilean mining volatility. |
| Micronized Copper Formulation Retrofit | ASME-certified pressure-vessel automation reduces retention variance for EPA compliance. |
| Borate Distribution Network Expansion | Pacific Northwest climate-controlled terminals capture interior framing specification shifts. |
| Remedial Treatment Service Launch | In-situ injection capabilities address aging US housing stock without plant infrastructure. |
| Multi-Source Procurement Qualification | Secondary copper-amine supplier validation hardens supply-chain resilience for housing volatility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pressure-treatment plant managers, chemical procurement leads at integrated lumber treaters, EPA regulatory affairs specialists, and regional distribution channel partners. Secondary validation drew from USITC trade data, American Wood Protection Association technical bulletins, SEC 10-K filings of listed chemical conglomerates, and EPA FIFRA registration databases. Bottom-up treatment plant capacity modeling and top-down construction spending forecasts were triangulated against chemical offtake trends.
Segment-weighting approaches applied chemistry-specific retention standards, end-use construction cycle intensity, and regional housing start correlations across the analysis window. Active-ingredient chemistry, application environment, and end-user procurement sophistication anchored the segmentation model. CAGRs derived from regression analysis of historical chemical consumption against lagged construction permits and infrastructure appropriations. Industry-specific forecast inputs included ASME pressure-vessel certification timelines and EPA reregistration review schedules.
The model holds under stable copper commodity pricing and incremental EPA compliance deadlines; deviation in accelerated chromium-arsenic phase-outs or termite-pressure zone reclassification would shift formulation demand curves. A small set of named triggers warrants ongoing watch: copper sulfate spot price spikes, ASME inspection backlog resolution, and mass timber building code adoption velocity in commercial construction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethanolamine Market
Chemicals
Nonaisoprenol Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Hexachloroethane Market
Chemicals
Calcium Borate Market
Chemicals
Cyclopentylamine Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Resorcinol Market
Chemicals
India Methanol Market
Chemicals
Myclobutanil Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Africa Mining Chemicals Market