
 North America Hot Melt Adhesives Market | 2026-2036
North America Hot Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hot Melt Adhesives Market Analysis
Polyurethane reactive hot melt chemistry is consolidating share from conventional solvent-based systems in automotive interior lamination. H.B. Fuller Company anchors its position through captive supply of specialty polyols and regional compounding infrastructure. Henkel AG & Co. KGaA differentiates via high-temperature performance grades targeting powertrain applications. Dow Inc. leverages its upstream ethylene integration to control feedstock costs across the EVA segment.
North America hot melt adhesives are thermoplastic formulations applied in molten state that solidify on cooling to form bonds, typically operating between 120°C and 200°C with open times ranging from seconds to minutes depending on substrate and formulation chemistry. These adhesives serve primary industrial functions in packaging sealing, automotive trim attachment, furniture edgebanding, and construction panel lamination where fast processing speed and immediate handling strength prove critical. Ethylene vinyl acetate maintains volume leadership in corrugated box sealing and bookbinding applications where cost sensitivity dominates procurement patterns. Polyurethane reactive technology captures the fastest expansion trajectory as manufacturers seek structural bonding capability combined with moisture-cure crosslinking for durability. Styrene block copolymer formulations occupy established positions in pressure-sensitive hygiene product assembly where elasticity and soft hand feel command premium positioning.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants restrict solvent adhesive use in major source facilities, directly expanding addressable market for zero-VOC hot melt alternatives. OSHA workplace exposure limits for isocyanates in polyurethane systems shape product handling requirements and personal protective equipment protocols across manufacturing plants. The Consumer Product Safety Commission's evolving framework for formaldehyde emissions in composite wood products indirectly drives specification of certified low-emission hot melt edgebanding adhesives in furniture production. Stakeholders must monitor how California Air Resources Board amendments to its Suggested Control Measure for aerosol coatings and adhesives may cascade into broader North American formulation standards.
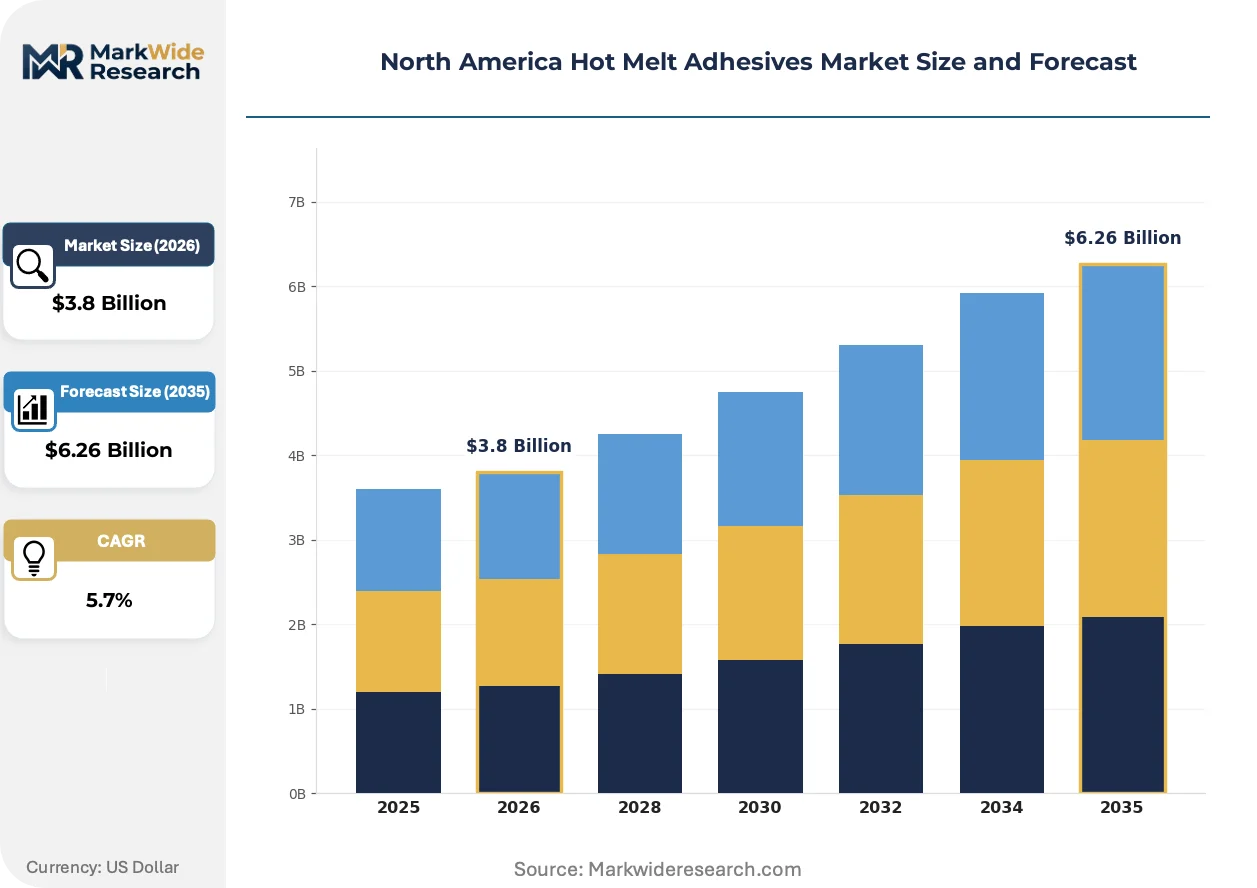
Market Dynamics
Polyurethane reactive chemistry is compressing adoption cycles across automotive and furniture bonding applications, forcing incumbent ethylene vinyl acetate suppliers to defend position through formulation speed rather than cost alone.
Growth Catalysts
- Automotive lightweighting mandates:Michigan and Ohio assembly corridors specify structural hot melt bonding for multi-material chassis joints, displacing mechanical fasteners in electric vehicle platforms.
- EPA NESHAP enforcement:The National Emission Standards for Hazardous Air Pollutants restrict solvent adhesive use in major source facilities, expanding addressable demand for zero-VOC alternatives in packaging lamination.
- Furniture cluster expansion:North Carolina and Tennessee manufacturers are scaling hot melt coating capacity for edgebanding and panel lamination, pulling regional supply chain investment.
Market Restraints
- Feedstock cost volatility:Ethylene and propylene price swings compress margin stability for EVA and polyolefin formulation houses serving corrugated packaging.
- Isocyanate handling infrastructure:OSHA workplace exposure limits for reactive polyurethane systems require capital-intensive ventilation and PPE protocols that deter mid-scale entrants.
- Performance ceiling in high-heat applications:Conventional hot melt formulations soften above 80°C, limiting penetration into underhood automotive and industrial oven segments where epoxy and acrylic alternatives retain dominance.
Strategic Opportunities
- Mexico automotive supplier integration:Querétaro and Guanajuato assembly plants lack localized hot melt compounding capacity, creating white space for regional production investment.
- California CARB amendments:Proposed Suggested Control Measure revisions for aerosol coatings and adhesives may cascade into broader North American low-emission standards, favoring certified formulation suppliers.
- Hybrid PUR-EVA convergence:Moisture-cure polyurethane segments are blending with conventional hot melt processing speeds, opening appliance and electronics housing applications previously reserved for two-part systems.
Industry Challenges
- Formulation chemist scarcity:Polyol reactivity tuning and rheology control expertise concentrates among aging technical workforces in Midwest industrial corridors.
- Multi-standard certification timelines:Furniture producers must synchronize EPA composite wood product certifications with CARB Phase 2 and evolving CPSC formaldehyde frameworks, elongating qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hot Melt Adhesives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, Styrene Block Copolymer, Ethylene Vinyl Acetate, Polyurethane Application: Packaging, Automotive, Construction, Furniture Technology: Hot Melt Extrusion, Hot Melt Coating, Hot Melt Spray, Reactive Hot Melt End User: Manufacturing, Retail, Healthcare, Logistics |
| Companies Covered | 3M Company, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Arkema, Dow Inc., Jowat SE, Bostik, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hot Melt Adhesives Market Emerging Trajectories
Formulation chemistry is bifurcating between commodity speed and structural durability, with processing equipment manufacturers racing to bridge the gap through precision temperature control and automated dispensing integration.
Polyurethane reactive hot melt technology is consolidating share from solvent-based systems in automotive interior lamination and structural bonding applications. Tier 1 suppliers serving Detroit Three platforms specify moisture-cure grades for headliner and door panel assembly where immediate handling strength must combine with long-term heat resistance. This chemistry is consolidating the competitive set around suppliers with captive polyol production and regional compounding infrastructure.
The EPA's evolving National Emission Standards for Hazardous Air Pollutants restrict solvent adhesive use in major source facilities across the United States. Industrial consequence includes forced conversion of packaging lamination and furniture coating lines to zero-VOC alternatives, compressing qualification timelines from 18 months to 6 months in competitive bids. Corrugated box sealing and bookbinding applications in the US Southeast are most affected, with converters accelerating hot melt equipment retrofits to maintain major source operating permits.
Buyer concentration among national packaging converters is compressing supplier negotiation cycles and unbundling technical service from material pricing. Regional distributors serving independent box plants are losing share to direct mill relationships as procurement centralizes at headquarters level. This pattern is most visible in the US Midwest, where consolidated corrugated producers specify national hot melt supply agreements with embedded application engineering support.
North America Hot Melt Adhesives Market Segmentation
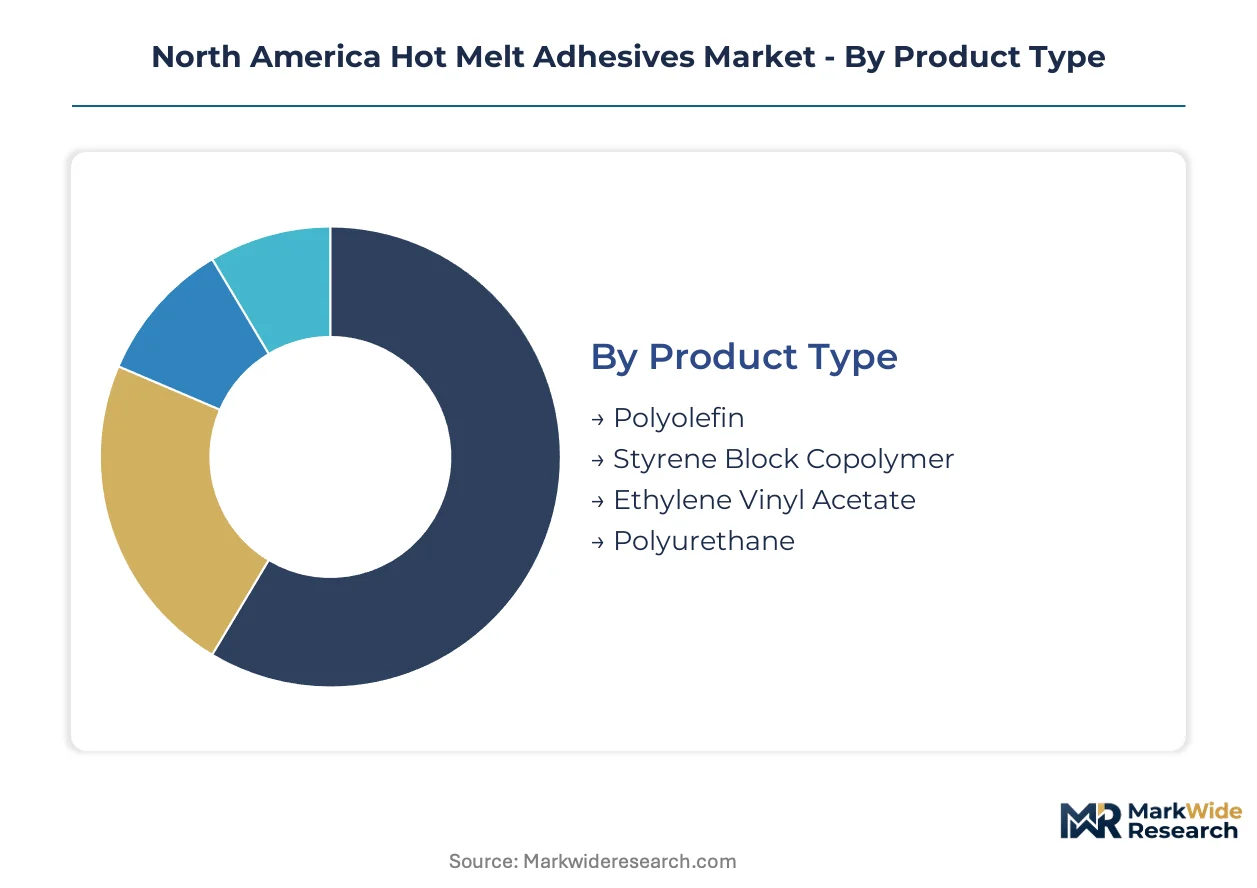
Segmentation in North America hot melt adhesives reveals how chemistry selection, application requirements, and processing technology interlock to determine supplier positioning and margin capture across distinct industrial workflows.
Product Type:
Polyurethane reactive systems embed into structural bonding workflows requiring crosslinked durability, while commodity thermoplastics serve standalone sealing functions where speed dominates specification.
- Ethylene Vinyl Acetate:Copolymer formulations balance melt flow index with open time for high-speed corrugated box sealing and bookbinding operations. Demand concentrates in US Midwest packaging corridors where national converters specify cost-optimized grades for automated case erectors and folder-gluers.
- Polyurethane:Moisture-cure reactive chemistry delivers structural bonding with heat resistance exceeding conventional hot melts. Michigan and Ohio automotive assembly plants specify these grades for multi-material chassis joints in electric vehicle platforms where mechanical fastener elimination reduces weight.
- Polyolefin:Metallocene-catalyzed grades offer narrow molecular weight distribution for clean machining in woodworking equipment. North Carolina furniture manufacturers deploy these formulations for edgebanding applications requiring thermal stability during panel processing.
- Styrene Block Copolymer:Elastic recovery and soft hand feel characterize these formulations for hygiene product assembly and pressure-sensitive applications. Tennessee medical supply producers specify SBC-based hot melts for diaper and sanitary product construction.
Volume placements concentrate in Ethylene Vinyl Acetate; the faster expansion belongs to Polyurethane.
Application:
Application segmentation tracks how end-use performance thresholds shape formulation specification, with automotive and furniture demanding engineered grades while packaging tolerates commodity chemistry.
- Packaging:Corrugated sealing, folding carton assembly, and flexible lamination dominate material consumption. US Southeast converters retrofit solvent-based lines to hot melt systems under EPA NESHAP compliance pressure, accelerating equipment investment cycles.
- Automotive:Interior trim attachment, headliner lamination, and structural bonding applications specify moisture-cure polyurethane grades. Detroit Three platforms require immediate handling strength combined with long-term durability under thermal cycling.
- Furniture:Edgebanding, panel lamination, and veneer splicing operations in North Carolina and Tennessee manufacturing clusters pull regional supply chain investment toward localized compounding capacity.
- Construction:Flooring installation, insulation bonding, and panel assembly applications favor polyolefin and EVA formulations where cost sensitivity limits polyurethane penetration. California building code evolution around low-VOC materials shapes specification trends.
Packaging commands the largest volume footprint; automotive applications are climbing the fastest as lightweighting mandates deepen penetration.
Technology:
Technology selection determines capital equipment requirements and processing latitude, with reactive systems demanding precision environmental control while conventional extrusion tolerates broader operating windows.
- Hot Melt Extrusion:Standard bead and slot-die application methods serve high-volume packaging and woodworking operations. Equipment manufacturers integrate precision temperature control and automated dispensing to reduce operator intervention.
- Reactive Hot Melt:Moisture-cure polyurethane systems require nitrogen blanketing and humidity-controlled dispensing to manage pot life and cure kinetics. Automotive Tier 1 suppliers in Michigan deploy these systems for structural bonding with crosslinked durability.
- Hot Melt Coating:Roll and curtain coating methods serve furniture panel lamination and textile backing applications. Tennessee manufacturers scale coating capacity for edgebanding operations serving residential furniture production.
- Hot Melt Spray:Spiral and fiberized spray technologies enable non-contact application for irregular substrates and heat-sensitive materials. Healthcare product assembly in the US Southeast specifies spray systems for hygiene article construction.
Extrusion technology retains the widest installed base; reactive systems are gaining share fastest as automotive specification tightens.
End User:
End user segmentation captures how procurement centralization and technical service requirements fragment the supplier landscape across manufacturing, retail, healthcare, and logistics channels.
- Manufacturing:Automotive OEMs, furniture producers, and appliance manufacturers specify direct mill relationships with embedded application engineering. National packaging converters centralize procurement at headquarters level, compressing regional distributor margins.
- Logistics:Warehousing and distribution operations consume hot melts for case sealing, pallet stabilization, and temporary holding applications. E-commerce fulfillment centers in the US Southeast drive demand for high-tack formulations with broad temperature performance.
- Retail:Point-of-sale display assembly and in-store signage mounting require low-temperature formulations compatible with heat-sensitive substrates. Big-box retailers specify certified low-emission adhesives for private-label product packaging.
- Healthcare:Medical device assembly, drug delivery system construction, and sterile packaging applications demand biocompatible grades with extractables and leachables documentation. FDA regulatory compliance shapes supplier qualification timelines.
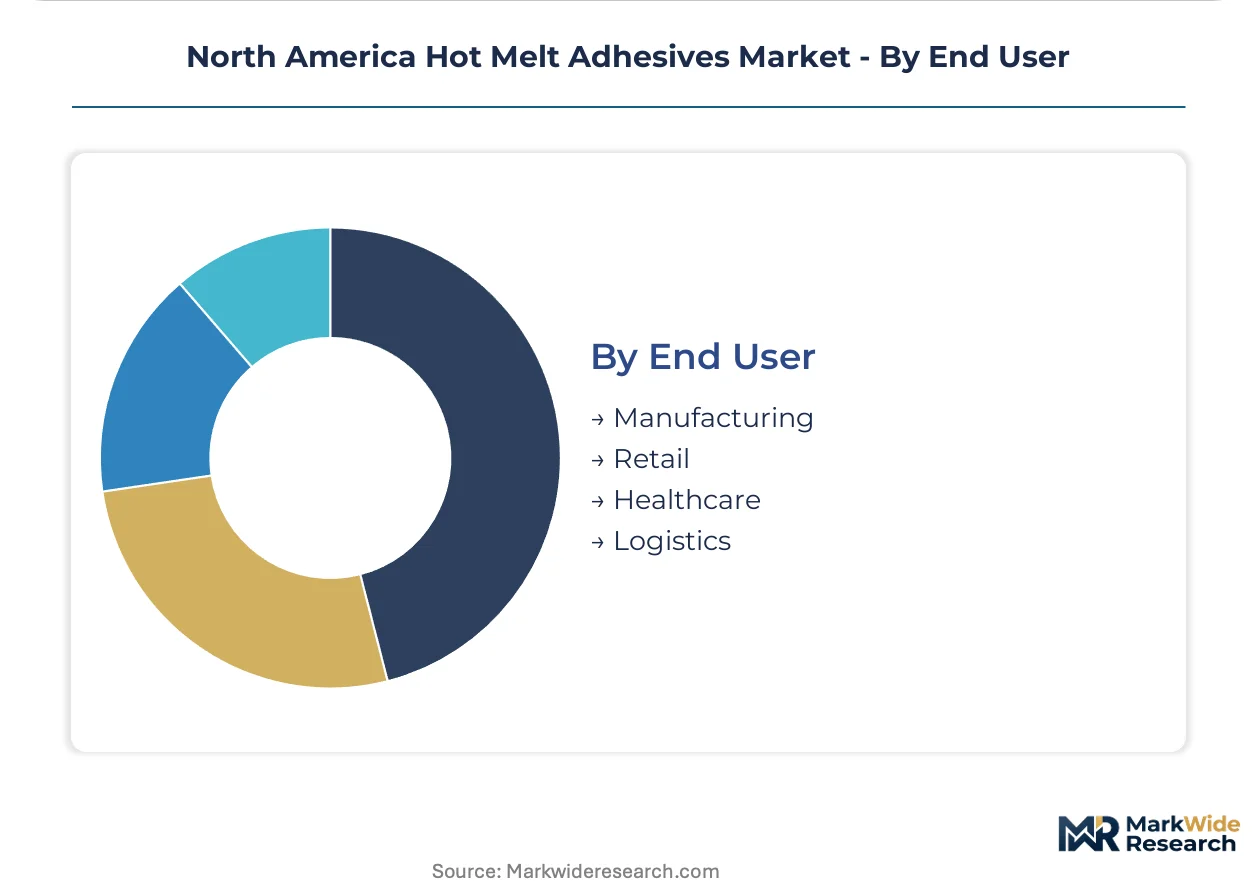
Manufacturing absorbs the dominant volume share; healthcare end uses are expanding most quickly as device assembly migrates toward adhesive bonding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hot melt adhesives concentrates in automotive assembly corridors and furniture manufacturing clusters, with regulatory pressure from EPA emission standards reshaping regional supply chain investments across North America.
United States
Michigan and Ohio automotive plants specify moisture-cure polyurethane grades for electric vehicle chassis bonding, eliminating mechanical fasteners under lightweighting mandates. EPA National Emission Standards for Hazardous Air Pollutants restrict solvent adhesive use in major source facilities, accelerating converter line retrofits. North Carolina and Tennessee furniture clusters are expanding regional hot melt compounding capacity for edgebanding operations.
Canada
Ontario automotive suppliers serving Detroit Three platforms import specialty reactive hot melts for interior trim lamination, creating cross-border logistics dependencies. Health Canada and Environment and Climate Change Canada administer chemical management regulations under the Canadian Environmental Protection Act, influencing adhesive formulation standards. Quebec construction materials producers specify low-temperature polyolefin grades for flooring installation in climate-variable conditions.
Mexico
Querétaro and Guanajuato automotive assembly plants lack localized hot melt compounding infrastructure, forcing reliance on US-sourced supply chains with extended lead times. Mexico's Secretariat of Environment and Natural Resources implements emissions regulations that increasingly align with US EPA frameworks. Baja California electronics assembly operations consume pressure-sensitive hot melts for device housing construction serving export markets.
North America Hot Melt Adhesives Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation chemistry expertise concentrating among established suppliers possessing captive raw material access. The market structure reflects tiered competition between integrated chemical producers, regional compounders, and application-focused distributors. Strategic archetypes include upstream-integrated resin suppliers, specialty formulation houses with technical service capabilities, and logistics-optimized distributors serving fragmented end users. Capacity expansion and backward integration into polyol production represent dominant competitive moves as margin pressure intensifies.
Among US-based diversified manufacturers, 3M Company and Dow Inc. occupy positions reflecting scale advantages in raw material procurement and application engineering infrastructure. H.B. Fuller Company exemplifies the specialty formulation archetype through regional compounding presence and captive polyol supply chains. European-headquartered competitors Henkel AG & Co. KGaA and Sika AG represent technology-driven positioning focused on high-performance grades for structural bonding applications.
| Leading Market Players |
|---|
| 3M Company |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema |
| Dow Inc. |
| Jowat SE |
| Bostik |
| Avery Dennison Corporation |
| Others |
Supply Flow & Price Mechanics
Formulation chemist expertise concentrated in Midwest industrial corridors creates labor-cost differentials that widen pricing-tier spreads between commodity EVA grades and engineered polyurethane systems.
Pricing Analysis
Volume placements in EVA corrugated sealing operate on thin margins while polyurethane structural grades capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates moisture-cure automotive specifications from packaging-grade copolymers and generic woodworking formulations. Price differentiation hinges on certification grade and captive polyol supply. Cost compression in EVA packaging tiers is intensifying because ethylene feedstock volatility compresses formulation house margins. National packaging converters exhibit highest price sensitivity; automotive Tier 1 suppliers prioritize performance over unit cost.
Supply Chain Analysis
Workforce availability for reactive polyurethane compounding concentrates in Michigan, Ohio, and Texas Gulf Coast petrochemical corridors. Supply draws from US ethylene crackers, Canadian specialty polyol producers, and Mexican automotive assembly demand. Raw material dependencies include ethylene, vinyl acetate monomer, and isocyanate precursors. Single-source vulnerability in isocyanate feedstocks exposes formulators to force majeure disruptions. Distribution runs through direct mill relationships with national converters and regional distributors serving independent furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock cost volatility and formulation chemist scarcity are compressing weaker compounders toward exit, creating consolidation opportunities for integrated players with captive raw material access.
For Market Incumbents: Anticipate margin compression in EVA packaging grades by securing captive ethylene supply through Gulf Coast pipeline access or long-term offtake agreements with integrated petrochemical producers. Accelerate polyurethane reactive capacity additions in Southeast automotive corridors before Tier 1 suppliers finalize qualification cycles. EPA NESHAP enforcement timelines create urgency for zero-VOC certification investment. For New Entrants and Emerging Players: E-commerce direct sourcing platforms offer route-to-market bypass for specialty woodworking formulations targeting independent North Carolina furniture manufacturers. White space exists in Mexico's Querétaro automotive corridor where localized compounding infrastructure remains underdeveloped. Focus initial penetration on low-temperature polyolefin grades for climate-variable flooring installation in Quebec construction markets. For Investors and Strategic Acquirers: The window for entry favors mid-scale polyurethane compounders with established automotive qualifications and regional distribution networks. Long-term viability centers on backward integration into polyol production and cross-border logistics capabilities serving US-Canada-Mexico manufacturing clusters. Watch EPA enforcement intensity in Southeast packaging corridors as inflection indicator for accelerated EVA-to-PUR conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive supply of specialty polyols insulates margin stability from isocyanate feedstock volatility. |
| Regional Compounding Capacity Expansion | Localized production in Tennessee and North Carolina reduces delivery costs for furniture cluster customers. |
| Zero-VOC Certification Investment | EPA NESHAP compliance accelerates qualification timelines for packaging lamination converters. |
| Automotive Tier 1 Technical Partnership | Embedded application engineering secures multi-year supply agreements for EV platform bonding. |
| Cross-Border Logistics Infrastructure | Mexico automotive corridor supply chains reduce lead times for Querétaro assembly plants. |
Methodological Framework
Independent corroboration across primary interviews with formulation chemists, automotive procurement directors, and furniture manufacturing plant managers underwrites the qualitative findings. Secondary validation draws from EPA enforcement databases, ACC chemical production reports, and customs trade data. Bottom-up triangulation of regional compounding capacity overlays top-down demand modeling from end-use industry production indices.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include chemistry type, application workflow, processing technology, and regional manufacturing cluster. CAGRs derive from regression analysis against automotive production forecasts and packaging converter capital expenditure patterns. Forecast inputs incorporate electric vehicle platform penetration rates and EPA compliance timeline assumptions.
The model holds under stable feedstock cost regimes; deviation in ethylene price volatility or isocyanate supply disruptions would shift margin distribution across formulation tiers. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Polysulfide Sealants Market