
 APAC Polyurethane Hot-Melt Adhesives Market | 2026-2036
APAC Polyurethane Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Polyurethane Hot-Melt Adhesives Market Insights
Market Context with Strategic Players
High-performance specification tiers is rotating the competitive landscape toward moisture-cure and reactive formulations with superior heat resistance. Henkel AG & Co. KGaA leverages its adhesive technology leadership to dominate automotive interior bonding applications across East Asian OEM supply chains. H.B. Fuller Company anchors its position through backward integration into polymer resin production, securing formulation consistency for specialty grades. Dow differentiates via its polyurethane raw material expertise, extending captive polyol supply into tailored hot-melt systems for electronics manufacturers.
Technical Definition and Structural Segments
APAC polyurethane hot-melt adhesives are thermoplastic or reactive systems formulated with isocyanate-terminated prepolymers that cure via atmospheric moisture to form irreversible urethane bonds, typically applied at temperatures between 120°C and 150°C to bond dissimilar substrates in automated industrial assembly. Reactively hot-melt adhesives command the strongest margin pools due to their superior durability in demanding automotive and electronics applications where standard adhesives fail under thermal cycling. Pressure-sensitive adhesives sustain the fastest volume expansion through electronics miniaturization trends in South Korean and Taiwanese component manufacturing. Furniture applications remain the most mature segment, with bulk supply delivery modes dominating procurement patterns among Chinese flat-pack producers.
Regulatory Framework and Forward Outlook
China's MEE enforces progressively stricter VOC content limits under evolving GB standards, compelling reformulation toward low-emission polyurethane systems that maintain bond strength. Japan's METI oversees chemical substance reporting through its industrial standards framework, while South Korea's MFDS regulates adhesive contact applications in consumer goods, creating multi-layered compliance requirements for cross-border suppliers. REACH-equivalent substance restrictions are proliferating across ASEAN member states, reshaping raw material sourcing strategies. Stakeholders must monitor regulatory divergence between national chemical registries to determine whether centralized formulation platforms or country-specific product lines offer superior risk-adjusted returns.
Market Dynamics
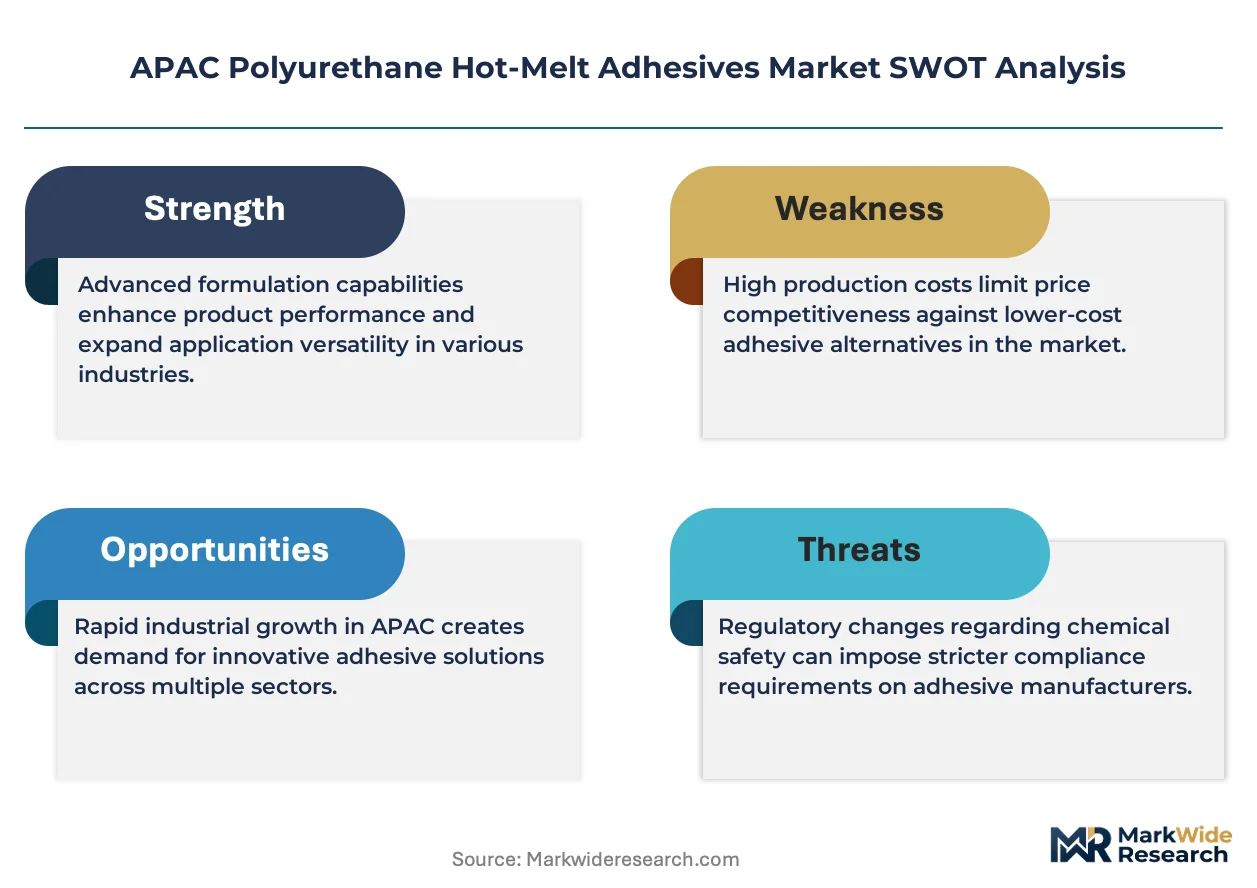
China's MEE is enforcing progressively stricter GB standards on VOC emissions, forcing reformulation of polyurethane hot-melt adhesives toward low-emission systems while maintaining bond performance in high-temperature automotive and electronics applications.
Growth Catalysts
- Automotive lightweighting mandates:East Asian OEMs are specifying reactive polyurethane hot-melt adhesives to replace mechanical fasteners in interior assemblies, reducing vehicle weight while improving NVH performance.
- GB 33372-2020 VOC limits:China's national standard on adhesive VOC content is accelerating adoption of moisture-cure polyurethane systems that emit significantly less formaldehyde and benzene during curing.
- Taiwanese electronics clustering:Precision bonding demand from semiconductor packaging and display module manufacturers in Hsinchu Science Park is pulling high-purity reactive formulations.
Market Restraints
- Isocyanate price volatility:MDI and TDI feedstock costs fluctuate with crude oil derivatives and regional chemical plant operating rates, compressing margin predictability for formulated adhesive producers.
- Raw material concentration in East China:Polyol and isocyanate production clusters in Jiangsu and Zhejiang provinces create geographic supply risk for formulators dependent on just-in-time resin delivery.
- Cure time limitations:Standard hot-melt systems require 24-72 hours for full moisture-cure strength development, creating throughput bottlenecks versus instant-bonding alternatives in high-speed furniture lines.
Strategic Opportunities
- Vietnamese manufacturing expansion:Electronics assembly relocation from China to Bac Ninh and Hai Phong industrial zones is creating demand for localized adhesive supply with technical service support.
- Battery pack thermal management bonding:Electric vehicle battery module assembly requires thermally conductive polyurethane adhesives that maintain structural integrity across -40°C to 150°C cycling.
- Japan's carbon neutrality roadmap:METI incentives for low-carbon manufacturing processes are opening procurement channels for bio-based polyol formulations in automotive Tier-1 supply chains.
Industry Challenges
- Formulation chemist scarcity:Expertise in balancing isocyanate index, catalyst selection, and moisture-cure kinetics for specific substrate combinations remains concentrated among senior technical staff at established suppliers.
- Multi-registry substance compliance:Cross-border suppliers must simultaneously track China's IECSC inventory, Japan's CSCL, South Korea's K-REACH, and emerging ASEAN chemical regulations for identical raw material portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Polyurethane Hot-Melt Adhesives Market |
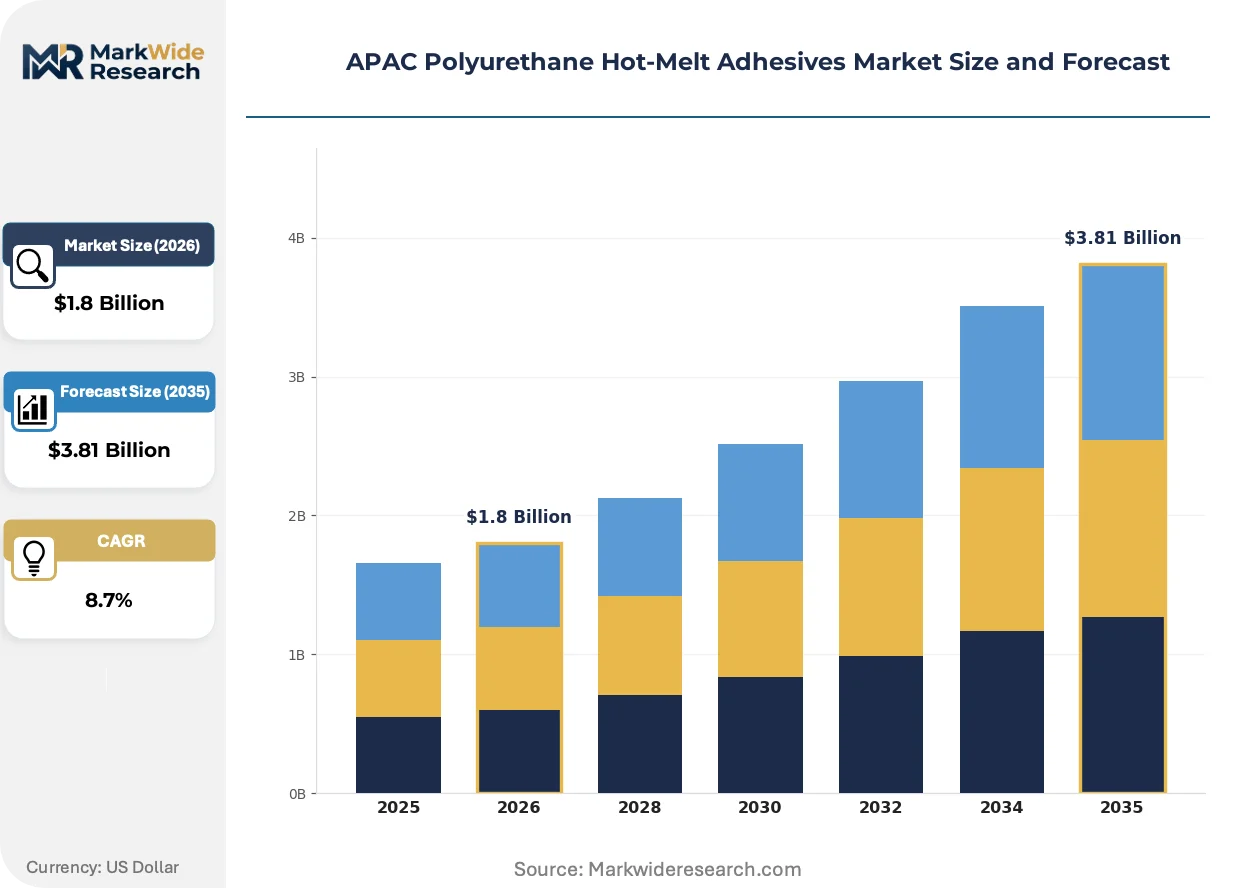
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Adhesives, Reactively Hot-Melt Adhesives, Pressure-Sensitive Adhesives, Specialty Adhesives Application: Furniture, Packaging, Automotive Interiors, Electronics End User: Manufacturers, Retailers, Distributors, Contractors Delivery Mode: Bulk Supply, Canisters, Cartridges, Pails |
| Companies Covered | Arkema Group, Huntsman Corporation, Henkel AG & Co. KGaA, Jowat SE, Dow, H.B. Fuller Company, Sika AG, Pidilite Industries Ltd, 3M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Polyurethane Hot-Melt Adhesives Market Trends and Innovations
Reactive polyurethane chemistry is advancing along three vectors: faster cure kinetics, bio-based feedstock incorporation, and precision application automation. These developments are compressing process cycle times while expanding addressable substrate combinations.
Silane-modified polyurethane prepolymers are miniaturizing cure time requirements for electronics applications. South Korean display manufacturers are specifying these systems for foldable OLED module bonding. This technology is miniaturizing the gap between hot-melt application and handling strength, enabling inline quality testing that was previously impossible with 24-hour cure schedules.
China's evolving GB standards on adhesive VOC emissions are forcing systematic raw material substitution. Formulators are replacing aromatic isocyanates with aliphatic alternatives and petroleum-derived polyols with castor oil-based equivalents. Automotive interior suppliers in Shanghai and Guangdong are qualifying these reformulated systems ahead of anticipated 2025 enforcement tightening.
Japanese electronics assemblers are consolidating adhesive procurement through direct technical partnerships with formulators rather than distributor intermediaries. This disintermediation is compressing pricing transparency and accelerating joint development cycles for application-specific grades. The shift is most visible in precision camera module and sensor packaging lines in Kyushu and Tohoku manufacturing corridors.
APAC Polyurethane Hot-Melt Adhesives Market Segmentation
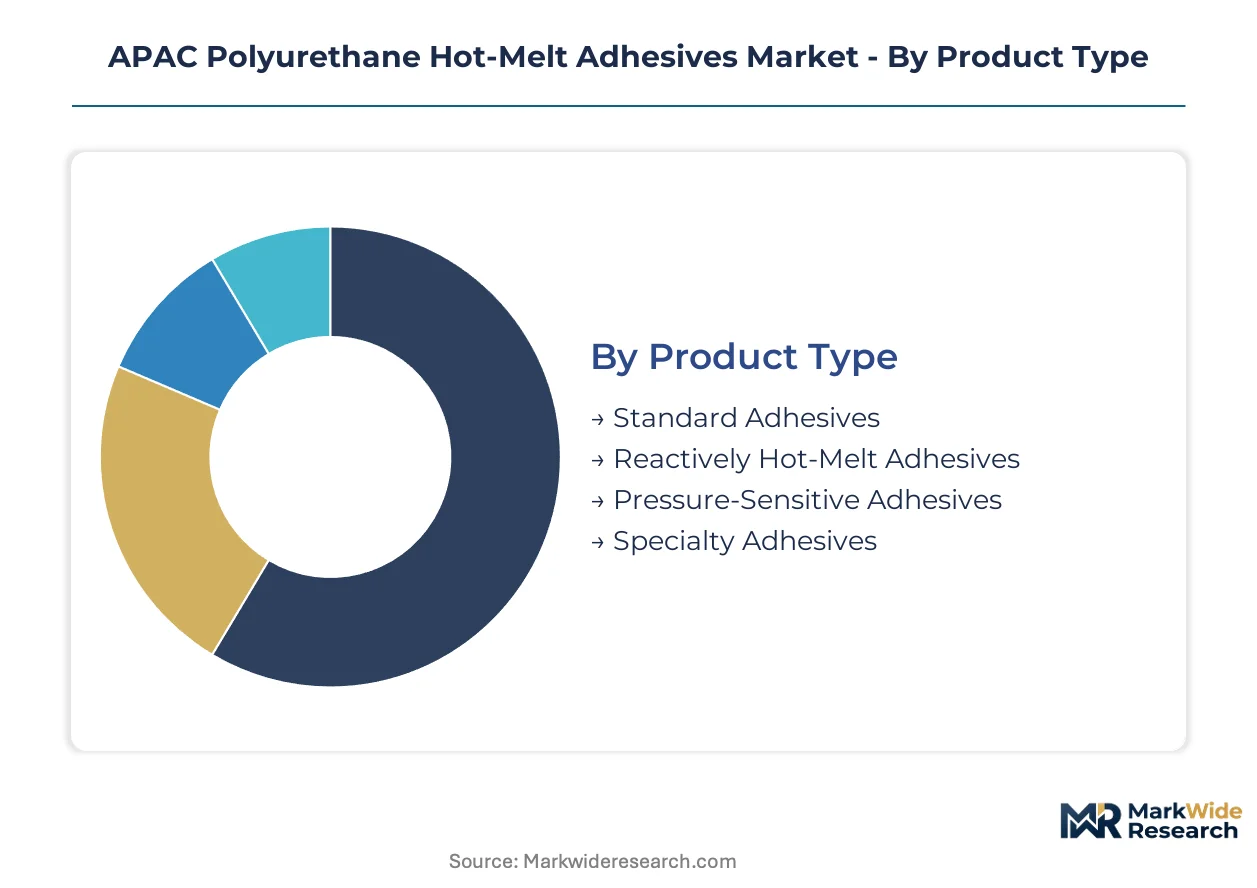
Segmentation in the APAC polyurethane hot-melt adhesives market reveals how formulation chemistry, application requirements, and procurement logistics create distinct competitive battlegrounds. Each dimension carries different margin profiles and substitution vulnerabilities that shape supplier positioning across East Asian manufacturing corridors.
Product Type:
Substitution pressure from cyanoacrylates and UV-cure acrylics weighs most heavily on commodity-grade formulations, while reactive chemistries defend position through irreversible bond performance.
- Standard Adhesives:Conventional thermoplastic polyurethane systems applied without subsequent moisture cure. Furniture manufacturers in Zhejiang province specify these for flat-pack assembly where bond strength requirements remain moderate and cost sensitivity dominates procurement decisions.
- Reactively Hot-Melt Adhesives:Isocyanate-terminated prepolymers that crosslink with atmospheric moisture post-application to form permanent urethane networks. Automotive interior suppliers in Shanghai and Guangdong are qualifying these systems ahead of anticipated GB 33372-2020 enforcement tightening for VOC compliance.
- Pressure-Sensitive Adhesives:Tack-retaining formulations for temporary positioning and repositionable bonding. South Korean display manufacturers drive specification for foldable OLED module assembly.
- Specialty Adhesives:Custom-engineered grades for extreme temperature cycling or chemically aggressive environments. Electric vehicle battery pack assemblers source thermally conductive variants for module structural bonding.
Standard adhesives retain volume leadership; reactively hot-melt adhesives hold the steepest expansion curve.
Application:
Cost tier stratification separates high-specification automotive and electronics bonding from price-competitive furniture and packaging segments.
- Furniture:Mature demand center for bulk adhesive consumption in panel lamination and edge banding. Chinese flat-pack producers in the eastern manufacturing corridor dominate procurement volume through consolidated supplier contracts.
- Packaging:High-speed carton sealing and case erection applications favor rapid-setting formulations with short open times. Southeast Asian corrugated board manufacturers are expanding capacity in Vietnam and Indonesia.
- Automotive Interiors:NVH-critical bonding of headliners, door panels, and instrument clusters. East Asian OEMs specify reactive systems to replace mechanical fasteners under lightweighting mandates.
- Electronics:Precision bonding for semiconductor packaging, display modules, and camera components. Taiwanese manufacturers in Hsinchu Science Park pull high-purity formulations with stringent ionic contamination limits.
Furniture commands the largest installed base; automotive interiors are climbing the fastest.
End User:
Procurement sophistication varies sharply across customer types, with direct manufacturers capturing technical partnership opportunities that distributors and retailers cannot replicate.
- Manufacturers:Industrial assemblers with in-house application equipment and formulation specification authority. Japanese electronics assemblers in Kyushu and Tohoku corridors are consolidating procurement through direct technical partnerships with formulators.
- Retailers:Consumer-facing channels for DIY repair and small-scale bonding applications. Urban hardware chains in Chinese tier-one cities stock cartridge formats for household furniture repair.
- Distributors:Intermediary stocking points serving fragmented regional manufacturing bases. Vietnamese electronics assembly zones in Bac Ninh and Hai Phong create demand for localized inventory holding with technical service support.
- Contractors:Installation and field-service operators requiring portable application formats. Commercial flooring and interior fit-out specialists across Southeast Asia specify pail and cartridge delivery.
Manufacturers retain volume leadership; distributors hold the steepest expansion curve.
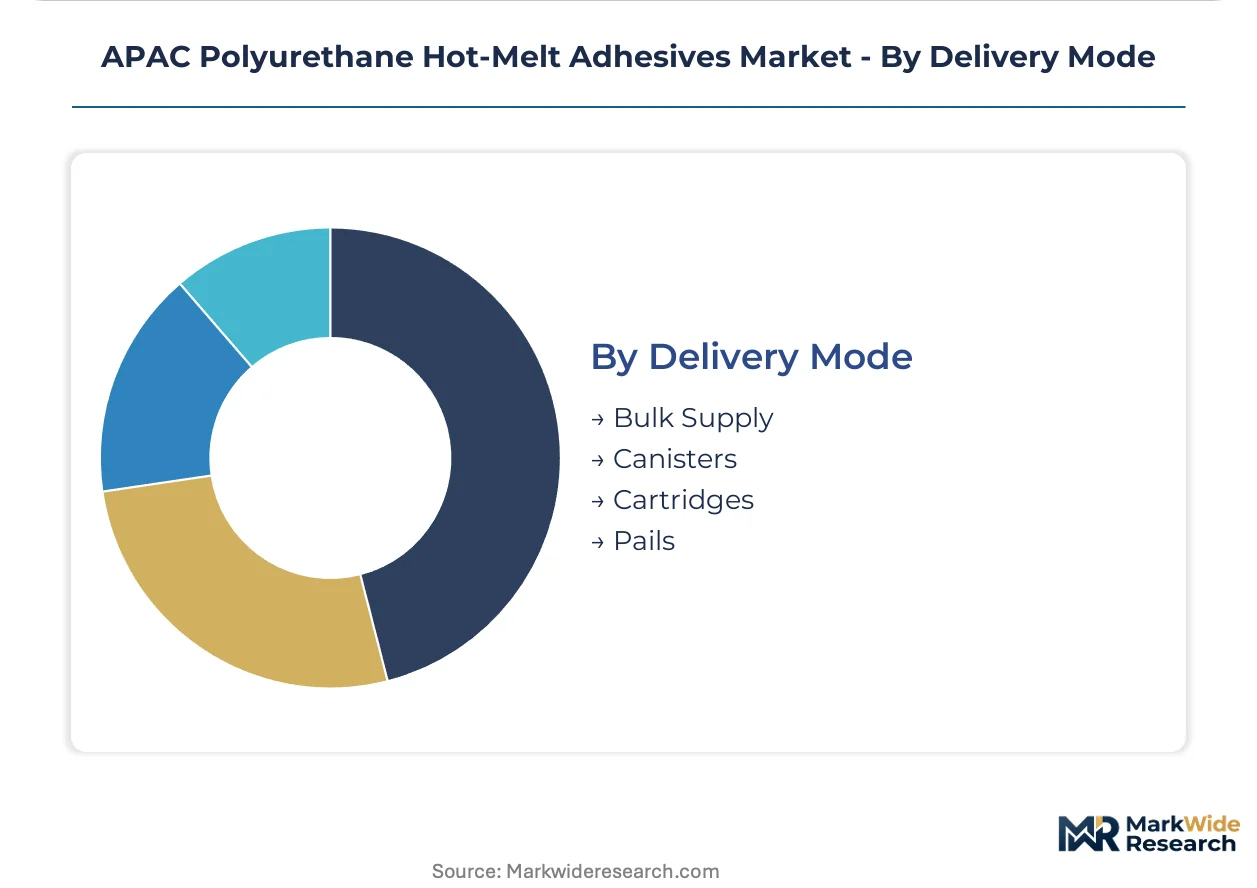
Delivery Mode:
Supply concentration in East China polyol and isocyanate production clusters shapes geographic availability and logistics economics for each packaging format.
- Bulk Supply:Tanker or tote delivery for high-volume continuous production lines. Furniture producers with dedicated adhesive storage and heated pumping systems achieve lowest unit economics through this mode.
- Canisters:Pressurized cylinders for portable hot-melt application equipment. Field contractors and mid-scale assemblers across ASEAN manufacturing zones favor this format for operational flexibility.
- Cartridges:Pre-measured single-component containers for precision dispensing systems. Electronics miniaturization trends in Taiwanese and South Korean component manufacturing drive specification for clean, controlled application.
- Pails:Intermediate bulk containers for batch processing and manual application. Small and mid-sized manufacturers without bulk handling infrastructure standardize on this delivery mode.
Bulk supply retains volume leadership; cartridges hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors generate net adhesive imports while Southeast Asian expansion zones tilt toward supply localization. China's eastern seaboard dominates formulation output, with Vietnam and Indonesia emerging as demand sinks for cross-border supply.
China
Automotive lightweighting mandates and electronics miniaturization pull reactive formulations into Shanghai and Guangdong assembly plants. MEE enforcement of GB 33372-2020 VOC limits compels systematic raw material substitution toward aliphatic isocyanates. The Yangtze River Delta polyol production cluster anchors captive supply for regional formulators.
Japan
METI carbon neutrality incentives open procurement channels for bio-based polyol grades in automotive Tier-1 supply chains. CSCL substance reporting requirements add compliance layers for imported raw materials. Kyushu and Tohoku manufacturing corridors consolidate adhesive procurement through direct technical partnerships with formulators.
South Korea
MFDS regulations on adhesive contact applications in consumer goods create qualification barriers for cross-border suppliers. Foldable OLED module bonding in display manufacturing pulls silane-modified polyurethane specifications. Hsinchu Science Park precision demand extends influence across the Korea Strait procurement ecosystem.
Vietnam
Electronics assembly relocation from China to Bac Ninh and Hai Phong industrial zones creates localized adhesive demand with technical service requirements. Emerging chemical registration frameworks lag behind formulation complexity, creating temporary regulatory arbitrage opportunities. Northern manufacturing provinces attract distributor inventory holding investment.
Taiwan
Semiconductor packaging and camera module assembly in Hsinchu Science Park specify high-purity reactive formulations with stringent ionic contamination limits. Domestic formulators compete with Japanese and Korean suppliers for precision electronics contracts. The island's advanced packaging ecosystem sustains premium-grade procurement volumes.
APAC Polyurethane Hot-Melt Adhesives Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers, creating a bifurcated structure where scale-driven commodity supply sits alongside application-engineered premium positioning. The vendor base organizes around raw material access, technical service depth, and regulatory compliance infrastructure. Three archetypes dominate: integrated chemical conglomerates with captive polyol supply, adhesive specialists with backward integration into resin production, and regional formulators serving fragmented industrial clusters. Competitive moves concentrate on geographic expansion into Vietnamese manufacturing zones and portfolio diversification toward battery thermal management grades.
Within the integrated chemical tier, Dow and Huntsman Corporation exemplify upstream control strategies that extend captive polyol supply into tailored hot-melt systems. Henkel AG & Co. KGaA occupies a position bridging formulation technology leadership with automotive OEM supply chain penetration across East Asia. H.B. Fuller Company anchors the specialist fabricator archetype through in-house resin production that secures consistency for moisture-cure grades. These three represent distinct competitive vectors: raw material integration, application engineering depth, and supply reliability assurance.
| Leading Market Players |
|---|
| Arkema Group |
| Huntsman Corporation |
| Henkel AG & Co. KGaA |
| Jowat SE |
| Dow |
| H.B. Fuller Company |
| Sika AG |
| Pidilite Industries Ltd |
| 3M |
| Others |
Pricing and Supply Chain Analysis
GB 33372-2020 VOC compliance gates both supplier qualification and price differentiation simultaneously, as automotive OEMs in Shanghai and Guangdong pay premiums for certified low-emission formulations while uncertified competitors face exclusion from Tier-1 procurement lists.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and volume scale, with GB 33372-2020-compliant reactive systems commanding premiums over conventional thermoplastic grades. Cost compression in standard furniture adhesives is intensifying because Chinese flat-pack producers consolidate procurement through annual tenders. Small electronics assemblers in Taiwan and South Korea exhibit lowest price sensitivity due to ionic contamination requirements that override cost considerations.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo trade lanes elevates inbound logistics costs for polyol and isocyanate feedstocks sourced from Jiangsu and Zhejiang production clusters. Geographic supply concentration centers on China, South Korea, and Japan, with raw material dependencies on MDI, TDI, and specialty polyols. Single-source vulnerability from MDI plant concentration in East China creates structural risk for formulated adhesive producers. Distribution runs through distributor networks with technical service capabilities in Vietnamese electronics zones and direct partnerships with Japanese automotive Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive polyurethane chemistry is becoming a platform-economics inflection as automotive OEMs standardize moisture-cure specifications across East Asian supply chains, creating interoperability lock-in that favors early movers with qualified formulations.
For Market Incumbents: Shield formulation expertise through captive resin production and accelerated bio-based polyol qualification ahead of Japan METI carbon neutrality procurement channels. Consolidate technical service teams in Vietnamese manufacturing corridors to preempt emerging entrant technical partnerships. Deepen backward integration into aliphatic isocyanate supply as aromatic alternatives face GB standard phase-out. For New Entrants and Emerging Players: Differentiate on silane-modified cure kinetics for foldable OLED applications where South Korean display manufacturers seek application-specific grades. Target Vietnamese electronics assembly relocation zones with localized inventory holding and Mandarin-speaking technical support. Pursue direct procurement relationships with Japanese camera module assemblers disintermediating distributor channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across reactive formulation capacity as multi-registry compliance infrastructure becomes mandatory. Long-term viability favors specialists with captive polyol supply and established automotive qualification records. Acquisition target archetype: regional formulators with GB 33372-2020 certification and existing OEM supply chain access. Monitor Japan METI bio-based procurement incentive announcements as inflection indicator for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Henkel and H.B. Fuller secure formulation consistency for moisture-cure automotive grades. |
| GB 33372-2020 Certification Investment | Qualification ahead of 2025 enforcement tightening opens Shanghai and Guangdong OEM procurement channels. |
| Vietnamese Technical Service Expansion | Localized support captures electronics assembly relocation from China to Bac Ninh and Hai Phong zones. |
| Silane-Modified Prepolymer Development | South Korean display manufacturers specify these systems for foldable OLED module bonding applications. |
| Bio-Based Polyol Formulation Partnership | METI carbon neutrality incentives create procurement channels in Japanese automotive Tier-1 supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across adhesive formulators, automotive Tier-1 procurement managers, electronics assembly engineers, and distribution channel partners. Secondary validation drew from customs trade data, China MEE regulatory filings, Japan METI industrial standards documentation, and South Korea MFDS substance registration records. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity disclosures and regional chemical industry reports.
Across the analysis window, forecasts segmented by product type, application, end user, and delivery mode were constructed using historical growth trajectory analysis adjusted for regulatory inflection points. CAGRs were derived from weighted average growth rates across segment-specific demand drivers including automotive lightweighting mandates, electronics miniaturization trends, and VOC compliance enforcement timelines. Industry-specific inputs incorporated MDI-TDI feedstock price correlation models and regional chemical plant operating rate assumptions.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of GB 33372-2020, accelerated ASEAN chemical registration harmonization, or stable crude oil derivative pricing would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation schedules and OEM specification migration timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
India Adhesives Market