
 South Korea Adhesives Market | 2026-2036
South Korea Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Adhesives Market Analytics
Platform licensing for specialty adhesive formulations is reshaping margin distribution between raw material suppliers and compounders. Henkel AG & Co. KGaA leverages its European technical heritage to dominate automotive structural bonding applications. KCC Corporation anchors domestic construction sector supply through extensive Korean distribution infrastructure. LG Chem competes on petrochemical backward integration, securing captive resin streams for acrylic and epoxy output.
Adhesives are non-metallic substances applied to surfaces that develop structural cohesion through chemical curing, physical drying, or cooling solidification, typically achieving lap-shear strengths from two to over forty megapascals depending on chemistry. These materials bond dissimilar substrates in assemblies where mechanical fastening introduces stress concentration or weight penalties. Water-based acrylic formulations lead volume in Korean packaging applications due to regulatory pressure on volatile organic compound emissions, while reactive epoxy systems capture the highest per-kilogram margins in electronics and aerospace-grade bonding. Hot melt adhesives sustain growth in e-commerce fulfillment operations where rapid set speeds enable automated carton sealing at throughput rates exceeding one hundred units per minute.
MFDS oversees chemical substance registration under K-REACH, compelling adhesive manufacturers to disclose hazardous component thresholds and submit toxicity dossiers for imported raw materials. KISHA enforces workplace exposure limits for solvent-based formulations, pushing industrial users toward water-based and hot melt alternatives in high-volume manufacturing settings. KS certification requirements for construction adhesives create compliance barriers for unqualified imports while privileging domestic compounders with established testing relationships. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-based content mandates as Korean trade policy tightens alignment with EU Green Deal benchmarks.
Market Dynamics
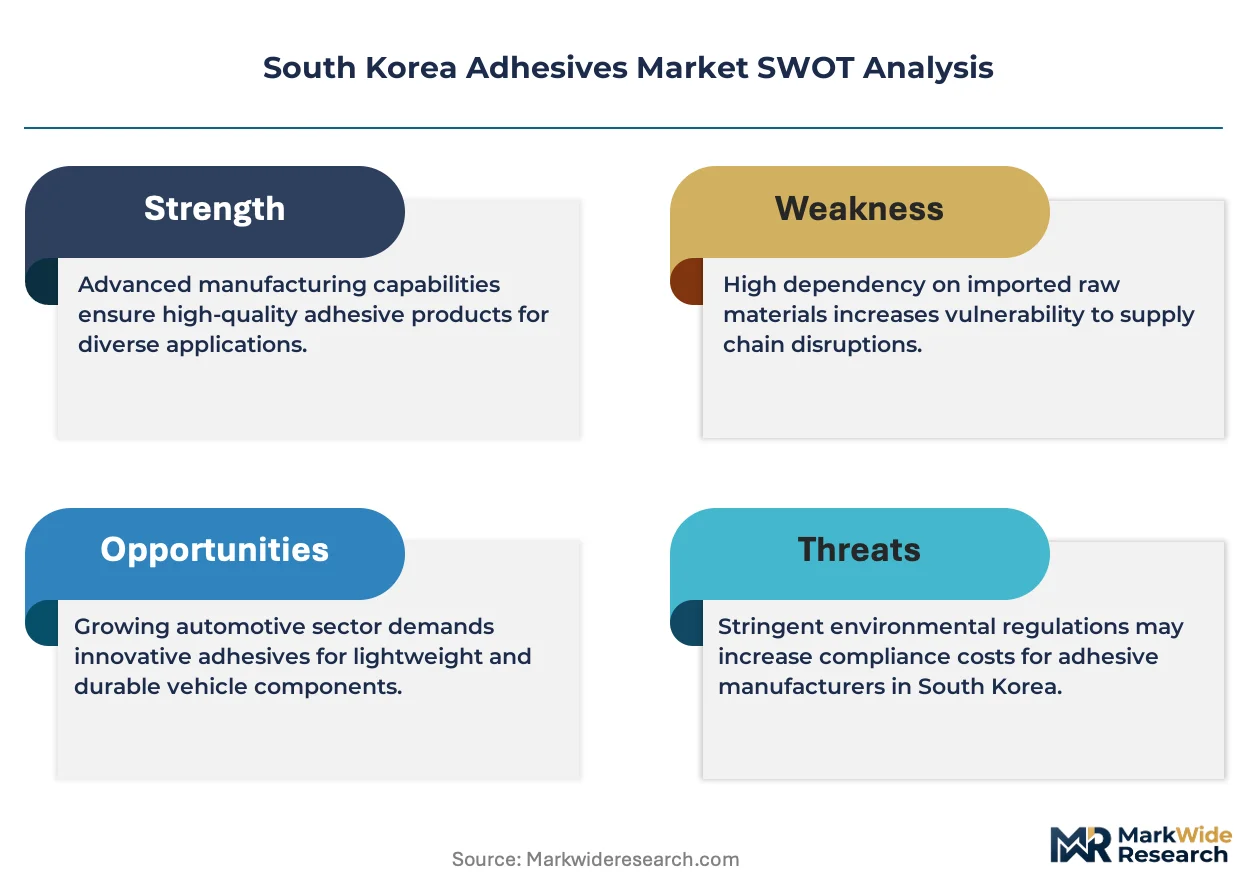
MFDS chemical disclosure mandates under K-REACH are forcing reformulation cycles across Korean adhesive compounders, compressing product development timelines while elevating compliance costs for imported raw material streams.
Growth Catalysts
- Electronics miniaturization:Smartphone and semiconductor manufacturers in Seoul metropolitan clusters consume ultra-thin bonding films for flexible circuit assembly. Die-attach adhesives with thermal conductivity above three watts per meter-kelvin now anchor specification sheets.
- K-REACH phase-in:Mandatory pre-registration of existing chemical substances creates first-mover advantages for domestic compounders with established toxicity dossiers. Early compliance secures supply continuity for automotive OEMs in Ulsan.
- EV battery pack assembly:Structural bonding of pouch and prismatic cells drives demand for flame-retardant polyurethane systems. Pyeongtaek and Gwangju battery plants specify adhesives with UL 94 V-0 ratings and dielectric strength exceeding twenty kilovolts per millimeter.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and epoxy resin prices fluctuate with naphtha cracking margins in Yeosu and Daesan complexes. Compounders lack pricing power to pass through input spikes to construction sector buyers.
- Import dependence for specialty curing agents:Aliphatic amine hardeners and anhydride accelerators concentrate among German and Japanese suppliers. Korean formulators face extended lead times and currency exposure on critical additives.
- Solvent-based formulation phase-out:KISHA workplace exposure limits for toluene and xylene are rendering obsolete conventional contact cements in footwear and furniture manufacturing. Water-based alternatives suffer from slower set speeds and reduced initial tack.
Strategic Opportunities
- Bio-based content mandates:Korean government green procurement guidelines now specify minimum renewable carbon percentages for public infrastructure projects. Polyols derived from castor oil and dimer fatty acids qualify for preferential bidding.
- Underpenetrated Jeolla region:Construction adhesive consumption per capita in Gwangju and Jeonju lags Seoul by forty percent. Local distribution partnerships with regional building material wholesalers unlock volume growth.
- UV-LED curing convergence:Furniture manufacturers in Gyeongsang Province adopt low-temperature photoinitiated systems to bond heat-sensitive substrates. Cationic epoxy formulations cure in under five seconds at three hundred ninety-five nanometer wavelengths.
Industry Challenges
- Formulation chemist scarcity:Korean universities produce insufficient polymer science graduates with industrial adhesive experience. Compounders compete with battery and display sectors for identical talent pools.
- KS certification timeline compression:Construction adhesive approvals now require six-month aging studies under accelerated humidity conditions. Unqualified imports face eighteen-month market entry delays.
- Legacy equipment retrofit costs:Water-based adhesive transitions demand stainless steel storage tanks and nitrogen-blanketing systems. Small and mid-sized packaging converters defer capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Adhesives Market |
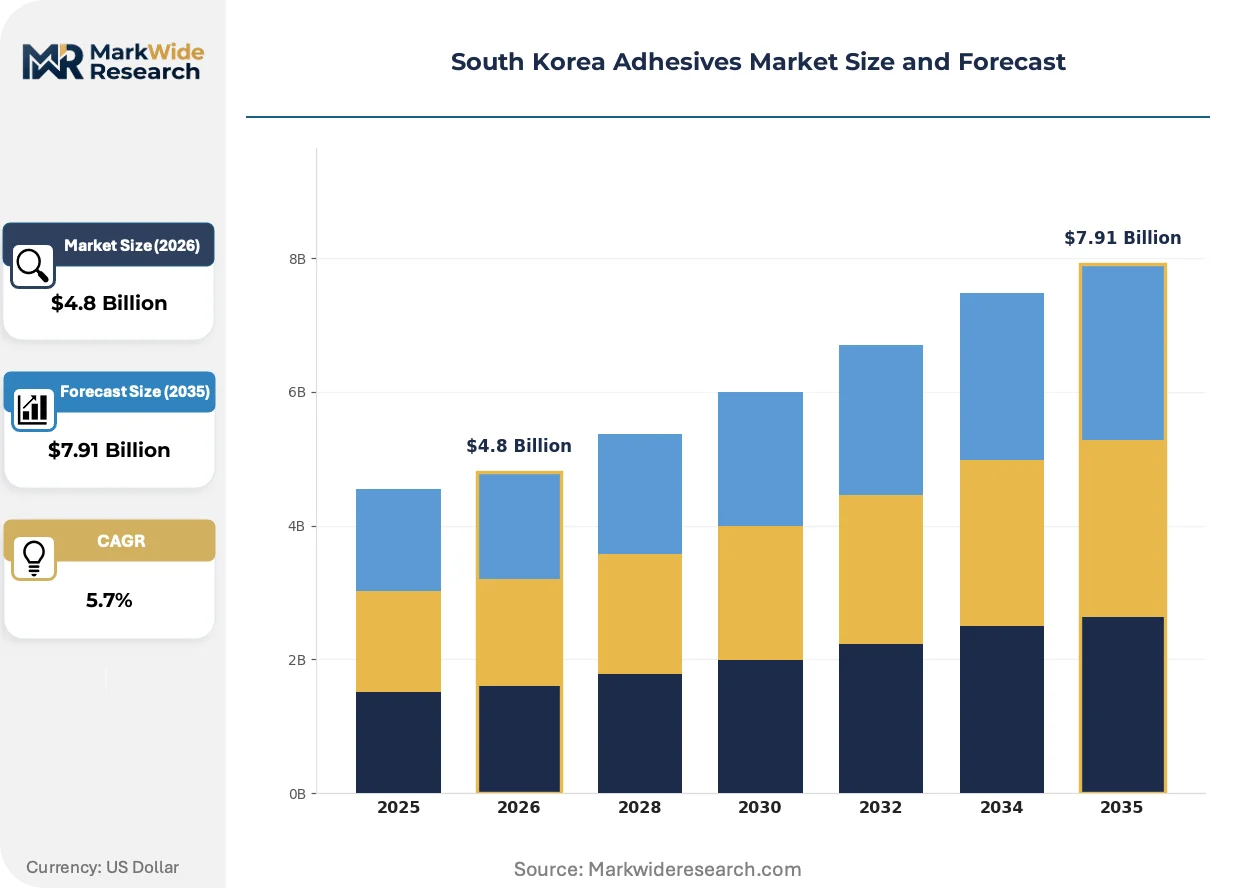
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
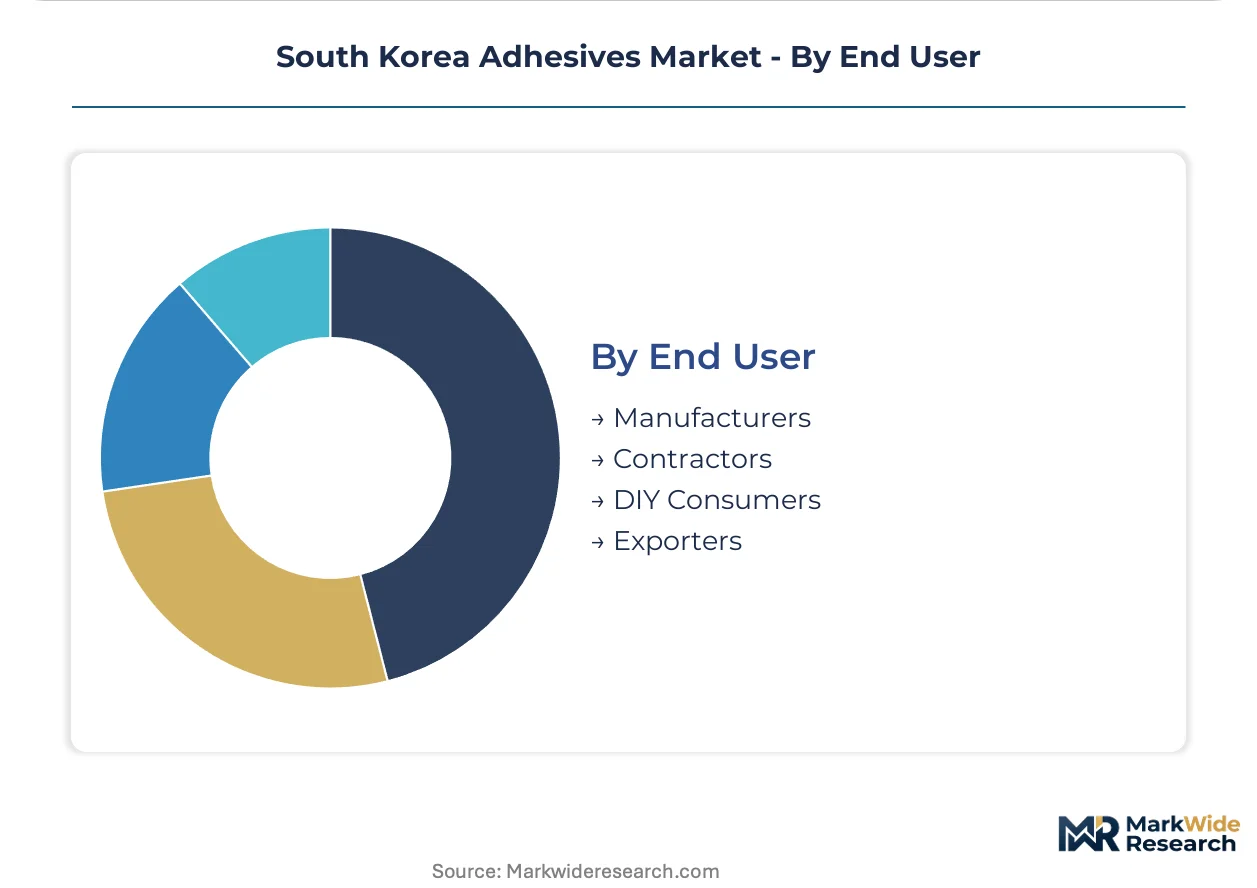
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Industry Vertical: Construction, Automotive, Electronics, Packaging Formulation: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Manufacturers, Contractors, DIY Consumers, Exporters |
| Companies Covered | 3M, BURIM CHEMICAL CO., LTD, Henkel AG & Co. KGaA, OKONG Corp., Unitech Co., Ltd, KCC Corporation, Samil Co. Ltd., Aekyung Chemical Co. Ltd., LG Chem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Adhesives Market Evolving Landscape
Active materials research is collapsing traditional performance trade-offs between cure speed, thermal stability, and environmental compliance in Korean adhesive applications.
Two-part silicone thermal interface materials with thermal conductivity exceeding six watts per meter-kelvin are rendering obsolete conventional epoxy-based potting compounds in power electronics. Battery module assemblers in Gwangju and Ulsan specify these materials for cell-to-pack bonding where operating temperatures exceed one hundred fifty degrees Celsius. The shift compresses supplier margins on legacy epoxy formulations while elevating compounders with in-house silicone synthesis capability.
MFDS enforcement of K-REACH substance evaluation for polymers above one ton annual volume is tightening disclosure requirements for imported prepolymers. Industrial users must now document safe-use scenarios and exposure controls for adhesive components in manufacturing settings. Electronics assembly operations in Gyeonggi Province are responding by consolidating supplier bases to reduce registration burden and audit complexity.
Specification-driven procurement now dominates Korean automotive Tier-1 purchasing, with OEMs mandating full material disclosure and carbon footprint documentation. Direct contracting between Hyundai Motor Group and specialty chemical suppliers is displacing traditional distributor relationships for structural bonding applications. The pattern concentrates most visibly in Ulsan and Asan manufacturing complexes where just-in-time adhesive delivery synchronizes with vehicle assembly sequences.
South Korea Adhesives Market Segmentation
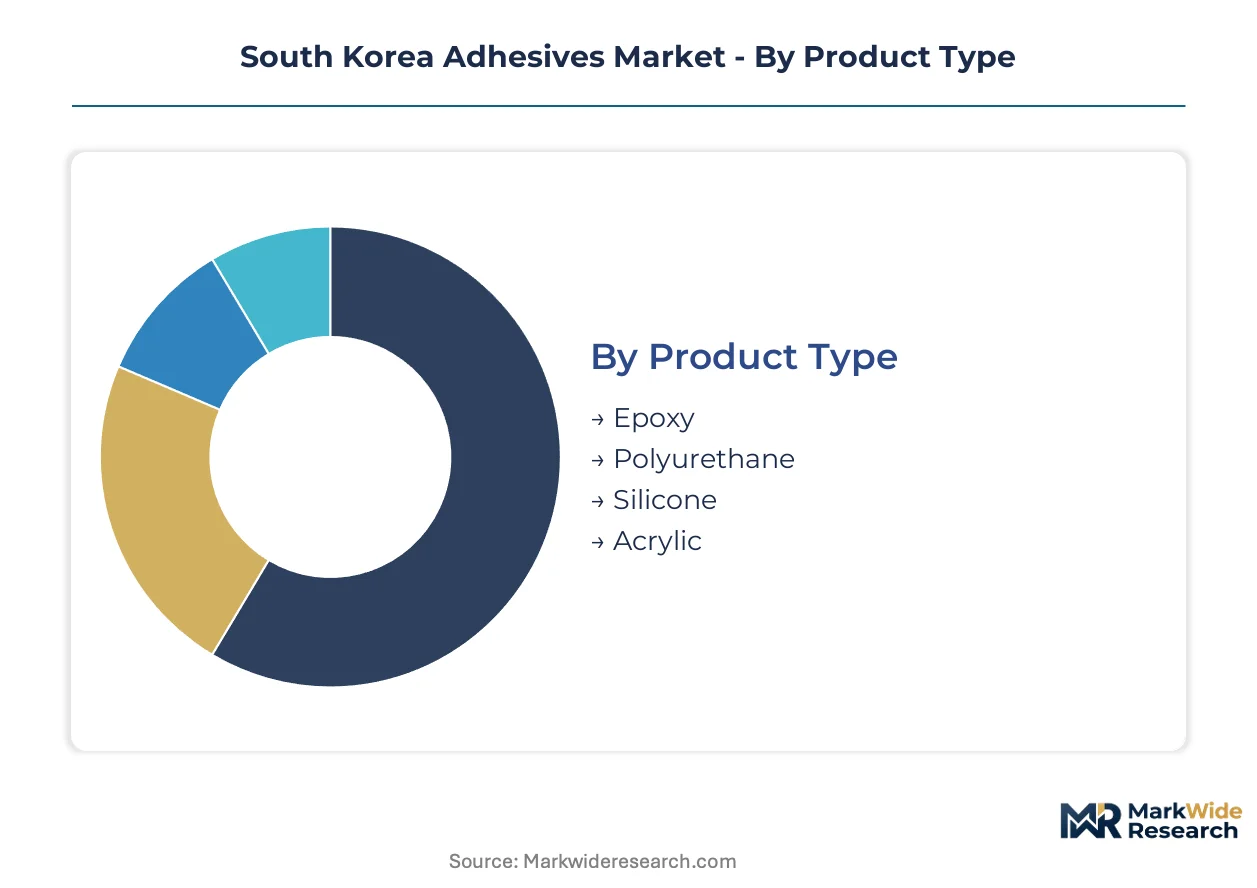
Segmentation reveals how adhesive chemistry, application intensity, and regulatory exposure create divergent margin profiles across Korean manufacturing clusters. Understanding these fault lines guides resource allocation for formulation development and distribution investment.
Product Type:
Chemistry determines thermal tolerance, substrate compatibility, and compliance burden under K-REACH substance evaluation tiers.
- Epoxy:Two-part thermosetting systems achieve lap-shear strengths exceeding thirty megapascals through cationic or amine curing mechanisms. Hyundai Motor Group structural bonding specifications in Ulsan favor toughened epoxy formulations for aluminum-intensive vehicle architectures. MFDS polymer registration thresholds above one ton annual volume compress development timelines for new epoxy hardener introductions.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture or catalyst activation, delivering flexible bonds across dissimilar substrates. Pyeongtaek battery plants specify flame-retardant polyurethane systems for pouch cell lamination where UL 94 V-0 ratings are mandatory.
- Silicone:Siloxane backbone polymers maintain elastomeric properties from minus sixty to plus two hundred degrees Celsius. Gwangju power electronics assemblers drive specification shifts toward thermally conductive silicone thermal interface materials.
- Acrylic:Free-radical polymerized systems dominate Korean packaging converters due to water-borne formulation availability and rapid UV curing compatibility.
Epoxy commands the established base in automotive and electronics assembly. The steepest expansion runs through silicone as thermal management demands intensify in battery and power semiconductor applications.
Industry Vertical:
Application intensity varies dramatically by sector, with specification complexity and contract duration shaping supplier relationships.
- Construction:KS certification requirements for structural glazing and flooring adhesives create compliance barriers favoring domestic compounders with established testing relationships. Seoul metropolitan area commercial development drives specification-grade silicone sealant consumption for curtain wall systems.
- Automotive:OEM direct contracting patterns concentrate purchasing power among Hyundai Motor Group and Kia Corporation supply chains. Ulsan and Asan manufacturing complexes synchronize just-in-time adhesive delivery with vehicle assembly sequences.
- Electronics:Die-attach adhesives with thermal conductivity above three watts per meter-kelvin anchor specification sheets for Seoul semiconductor packaging operations.
- Packaging:E-commerce fulfillment automation demands hot melt systems with set speeds enabling carton sealing throughput exceeding one hundred units per minute.
Construction anchors volume through infrastructure project pipelines. Electronics represents the fastest-growing trajectory as semiconductor packaging complexity multiplies bonding point density per device.
Formulation:
Carrier system selection determines volatile organic compound exposure, equipment compatibility, and cure kinetics in Korean manufacturing environments.
- Water-Based:Acrylic emulsion systems lead Korean packaging applications due to regulatory pressure on solvent emissions. Gyeonggi Province corrugated board converters retrofit stainless steel storage infrastructure to accommodate water-based transitions.
- Solvent-Based:Toluene and xylene carriers deliver rapid initial tack for footwear and furniture manufacturing. KISHA workplace exposure limits are rendering conventional contact cements obsolete in high-volume settings.
- Hot Melt:Thermoplastic EVA and polyolefin formulations sustain growth in automated fulfillment operations where rapid set speeds synchronize with conveyor throughput.
- Reactive:Two-component systems cure through polymerization rather than solvent evaporation, enabling high-performance bonds without volatile organic compound release.
Solvent-based formulations retain position in legacy manufacturing segments. Water-based alternatives are gaining share fastest as KISHA enforcement tightens and equipment retrofit capital becomes available.
End User:
Purchasing sophistication and specification authority fragment across direct manufacturing, subcontracting, and consumer channels.
- Manufacturers:Tier-1 automotive and electronics assemblers in Ulsan and Seoul metropolitan clusters mandate full material disclosure and carbon footprint documentation. Direct contracting with specialty chemical suppliers displaces traditional distributor relationships.
- Contractors:Regional construction firms in Gwangju and Jeonju depend on wholesale distributors for KS-certified product access and technical support.
- DIY Consumers:Home improvement retailers in Seoul and Busan stock commodity-grade cyanoacrylate and epoxy repair kits for household bonding applications.
- Exporters:Korean adhesive compounders serving ASEAN electronics assembly operations navigate divergent chemical registration requirements across destination markets.
Manufacturers concentrate purchasing value through direct supplier relationships. The steepest expansion trajectory runs through exporters as Korean compounders leverage K-REACH compliance credibility in regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area consumes specification-grade adhesives for electronics and automotive assembly, while Busan-Ulsan anchors heavy industrial demand and Gwangju-Honam shows underpenetrated construction potential. Each sub-region exhibits distinct chemistry preferences tied to dominant manufacturing clusters.
Seoul Capital Area
Smartphone and semiconductor packaging operations in Suwon and Pyeongtaek drive ultra-thin bonding film consumption for flexible circuit assembly. MFDS K-REACH enforcement compels full material disclosure from adhesive suppliers serving Gyeonggi Province electronics plants. Songdo and Pangyo tech corridors concentrate die-attach adhesive demand where thermal conductivity specifications exceed three watts per meter-kelvin.
Busan-Ulsan
Hyundai Motor Group manufacturing complexes in Ulsan specify toughened epoxy formulations for aluminum-intensive vehicle architectures. KISHA workplace exposure limits push solvent-based adhesive phase-out in favor of water-based and hot melt alternatives. Onsan petrochemical complexes supply captive resin streams to regional compounders serving maritime and automotive OEMs.
Daegu-Gyeongbuk
Furniture manufacturers in Gyeongsang Province adopt UV-LED curing systems to bond heat-sensitive substrates without thermal damage. MFDS polymer registration thresholds compress development timelines for new adhesive hardener introductions. Gumi electronics industrial park houses display panel assemblers consuming reactive polyurethane systems for optical bonding applications.
Daejeon-Sejong
Government research institutes in Daejeon drive public-sector green procurement guidelines specifying minimum bio-based carbon percentages. KS certification requirements for construction adhesives create compliance barriers favoring domestic compounders with established testing relationships. Sejong administrative city infrastructure projects consume specification-grade silicone sealants for curtain wall systems.
Gwangju-Honam
EV battery plants in Gwangju specify flame-retardant polyurethane systems with UL 94 V-0 ratings for pouch cell lamination. Construction adhesive consumption per capita lags Seoul by forty percent, indicating distribution partnership opportunities with regional building material wholesalers. Yeosu petrochemical complexes supply acrylic monomer and epoxy resin feedstocks to compounders serving underpenetrated Jeolla markets.
South Korea Adhesives Market Competitive Landscape
Capability concentration sits with European technical specialists; scale advantage sits with Korean petrochemical-integrated conglomerates. The market structures around three tiers: global formulation licensors with automotive OEM relationships, domestic construction-sector suppliers with KS certification infrastructure, and petrochemical-backward-integrated compounders with captive resin access. Dominant competitive moves include direct OEM contracting displacing distributor relationships and silicone synthesis capability acquisition for thermal management applications.
Among the named participants, Henkel AG & Co. KGaA and 3M exemplify the global formulation tier with European and US technical heritage respectively. KCC Corporation anchors domestic construction supply through extensive Korean distribution infrastructure. LG Chem occupies a position reflecting petrochemical backward integration, securing captive resin streams for acrylic and epoxy output. These three represent distinct archetypes: technical licensor, domestic infrastructure player, and integrated feedstock compounder.
| Leading Market Players |
|---|
| 3M |
| BURIM CHEMICAL CO., LTD |
| Henkel AG & Co. KGaA |
| OKONG Corp. |
| Unitech Co., Ltd |
| KCC Corporation |
| Samil Co. Ltd. |
| Aekyung Chemical Co. Ltd. |
| LG Chem |
| Others |
Value Network & Pricing Analysis
German and Japanese specialty curing agent suppliers anchor upstream concentration, directing margin pools toward compounders with captive hardener synthesis or long-term offtake security. Pricing power fragments across this supplier tier, with Korean formulators absorbing currency exposure and lead time volatility on aliphatic amines and anhydride accelerators.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and structural adhesive suppliers, insulating volume commitments from petrochemical feedstock spikes. Pricing stratifies across KS-certified premium tiers, UL-rated flame-retardant grades, and commodity construction formulations. Cost compression in water-based acrylic segments is intensifying because packaging converters lack pass-through leverage to e-commerce fulfillment operators. Construction contractors in Jeolla exhibit highest price sensitivity, while electronics assemblers in Gyeonggi prioritize thermal conductivity specifications over per-kilogram cost.
Supply Chain Analysis
Toll manufacturing concentration sits with Korean petrochemical-integrated compounders operating captive resin streams from Yeosu and Daesan complexes. Raw material dependencies center on naphtha-derived acrylic monomers, bisphenol-A epoxy precursors, and imported aliphatic amine hardeners. Single-source vulnerability runs through Japanese anhydride accelerator suppliers serving battery lamination specifications. Distribution runs through regional building material wholesalers for construction adhesives and direct OEM contracting for automotive and electronics grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where formulation technical support and KS certification consulting expand recurring revenue faster than commodity adhesive volume. Application engineering services for EV battery thermal management specifications represent the fastest-growing after-sales layer.
For Market Incumbents: Build regulatory compliance moats through early K-REACH polymer registration above one-ton thresholds, securing supply continuity commitments from Hyundai Motor Group and Seoul electronics clusters. Deepen backward integration into silicone synthesis capability as thermal interface materials displace legacy epoxy potting compounds. Channel control through exclusive distribution partnerships with Jeolla regional wholesalers defends against price-aggressive imports. For New Entrants and Emerging Players: Establish a beachhead in UV-LED curable cationic epoxy systems for Gyeongsang furniture manufacturers seeking heat-sensitive substrate bonding. The underpenetrated Gwangju construction adhesive market offers forty percent per-capita consumption gaps versus Seoul, unlockable through KS certification investment and local technical service presence. Direct contracting with mid-tier battery assemblers bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European formulation specialists holding automotive OEM technical heritage but lacking Asian manufacturing footprint. Five-to-ten-year viability hinges on K-REACH compliance infrastructure and silicone synthesis capability acquisition. Monitor MFDS enforcement intensity on polymer registration deadlines as inflection indicator for compounder consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Synthesis | Battery assemblers in Gwangju specify six watt-per-meter-kelvin thermal interface materials displacing epoxy systems. |
| KS Certification Infrastructure Investment | Construction adhesive approvals require six-month accelerated humidity aging studies favoring domestic testing relationships. |
| Direct OEM Contracting Expansion | Hyundai Motor Group procurement teams mandate full material disclosure and carbon footprint documentation bypassing distributors. |
| UV-LED Curable Formulation Development | Furniture manufacturers in Gyeongsang Province adopt three hundred ninety-five nanometer cationic epoxy systems for heat-sensitive substrates. |
| Regional Distribution Partnership in Jeolla | Gwangju and Jeonju construction adhesive consumption per capita lags Seoul by forty percent indicating volume growth potential. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, K-REACH registration databases, and KS certification records. Plant managers at Yeosu petrochemical complexes, procurement leads at Ulsan automotive OEMs, distribution channel partners in Seoul building material wholesale, and technical R&D directors at Gyeonggi electronics compounders contributed stakeholder perspectives. Bottom-up adhesive volume modeling triangulates against top-down petrochemical feedstock consumption analysis.
Forecast inputs include chemistry-grade tier differentiation, end-use industry application intensity, formulation carrier system compliance burden, and regional manufacturing cluster concentration across the analysis window. Modeled segmentation spans epoxy, polyurethane, silicone, and acrylic chemistries against construction, automotive, electronics, and packaging verticals. CAGRs derive from adhesive consumption intensity per unit of downstream output applied to projected vehicle, smartphone, and battery production volumes.
Stress conditions across naphtha cracking margin volatility, yen-euro currency exposure on imported hardeners, and KISHA solvent exposure limit enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on petrochemical feedstock pricing and regulatory phase-in schedules. Quarterly review of MFDS polymer registration enforcement patterns and automotive OEM direct contracting penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market