
 Asia-Pacific Sealants Market | 2026-2036
Asia-Pacific Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sealants Market Insights
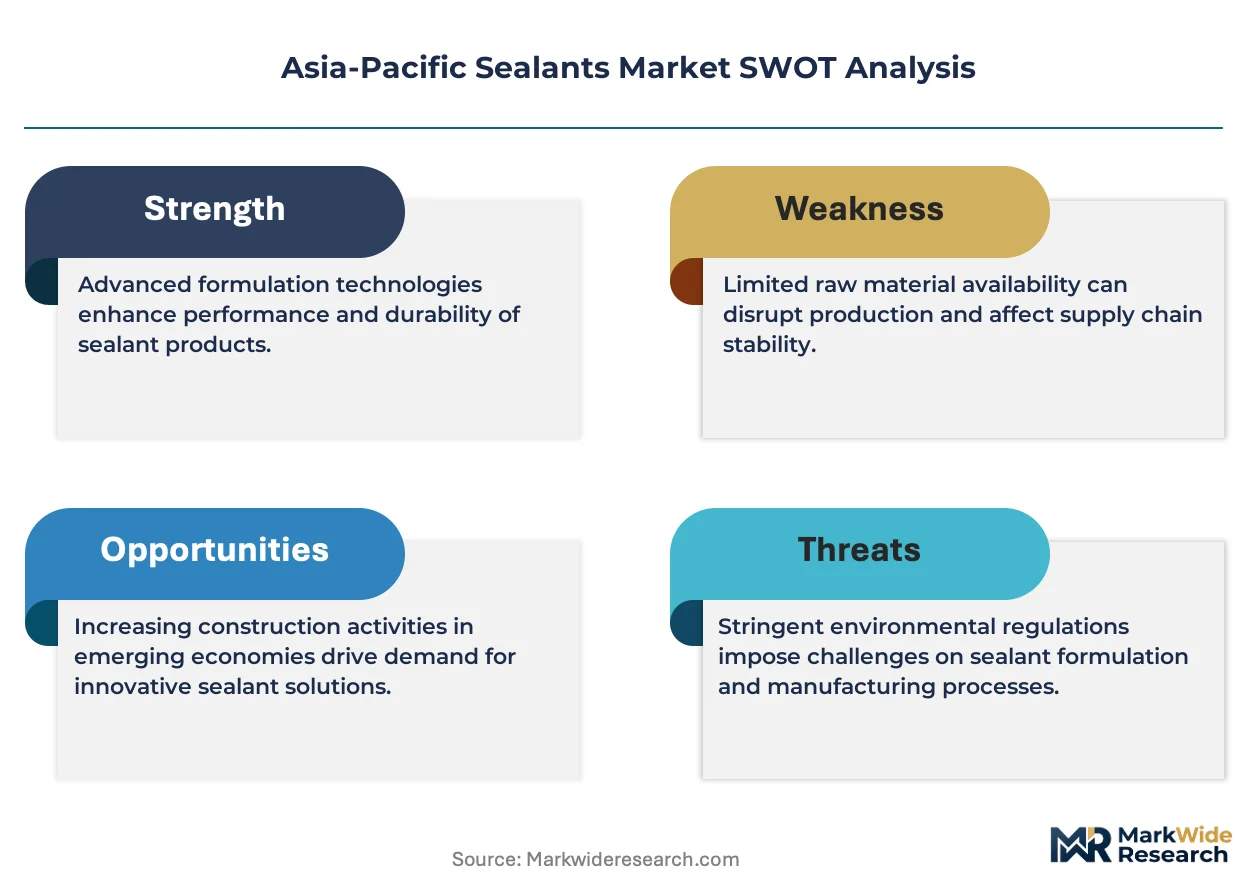
Skilled polymer chemist availability is rotating toward silicone formulation centers in South Korea and Japan, tightening talent pools for polyurethane specialists elsewhere. Sika AG leverages its construction-focused R&D hubs to sustain specification-grade product pipelines across Australian infrastructure tenders. Henkel AG & Co. KGaA anchors electronics assembly demand through its bonding chemistry portfolio serving semiconductor packaging lines in Taiwan and Malaysia. Dow competes on silane-modified polymer scale, controlling raw material access that extends formulation flexibility for regional OEMs.
Asia-Pacific sealants comprise elastomeric compounds—typically silicone (polysiloxane backbone, 20-50 Shore A hardness), polyurethane (isocyanate-cured, 300-800% elongation), acrylic (water-based emulsion, -20°C to 80°C service range), or butyl (polyisobutylene, <1% gas permeability)—engineered to fill gaps, block fluid ingress, and accommodate joint movement in assemblies. Silicone formulations dominate façade and glazing specifications where UV stability and 50-year durability ratings are specified, while polyurethane captures expansion joint and automotive underbody applications where abrasion resistance and paint compatibility matter. Acrylic water-based systems occupy interior construction and DIY renovation segments where low odor and tool cleanup drive specification, with butyl maintaining position in primary sealing of insulated glass units and roofing membranes.
Japan's METI enforces JIS A 5758 building sealant performance standards that mandate 7-day cure profiles and 25% joint movement capability, while Australia's NCC (National Construction Code) references AS 3740 waterproofing requirements that shape wet-area sealant specifications. China's GB 16776 standard for structural silicone sealants in glass curtain walls creates a compliance threshold that filters import eligibility and protects domestic formulators. South Korea's MFDS and KOSHA frameworks govern industrial chemical handling and workplace exposure limits that influence solvent-based product viability. Stakeholders must monitor how Vietnam's emerging technical regulation alignment with ASEAN harmonized standards reshapes import certification pathways and local manufacturing investment timing.
Market Dynamics
India's BIS certification tightening for structural glazing is filtering import eligibility and redirecting procurement toward domestic formulators with certified silicone portfolios. This regulatory compression is reshaping competitive positioning across Southeast Asian megaprojects and Australian infrastructure tenders.
Growth Catalysts
- ASEAN megaproject construction:Vietnam's manufacturing corridor and Indonesia's new capital development are pulling specification-grade silicone into high-performance building envelopes with 50-year durability ratings.
- Electronics assembly expansion:Taiwan and Malaysia semiconductor packaging lines require specialized electronic-grade sealants for moisture protection in advanced node chip fabrication.
- GB 16776 structural glazing mandate:China's curtain wall standard creates compliance thresholds that protect domestic formulators and accelerate certified product substitution for uncertified imports.
Market Restraints
- Silane monomer supply concentration:Dow and Wacker control upstream silane-modified polymer feedstock access, extending formulation flexibility only to preferred regional OEM partners.
- Polyurethane raw material volatility:Isocyanate and polyol pricing swings compress margin predictability for construction joint and automotive underbody applications.
- JIS A 5758 cure profile mandates:Japan's METI-enforced 7-day cure specifications and 25% joint movement requirements create technical barriers for fast-cure formulations seeking market entry.
Strategic Opportunities
- Philippines infrastructure gap:Underpenetrated commercial construction and limited domestic formulation capacity create first-mover advantage for certified silicone suppliers.
- Green building certification alignment:Australia's NCC referencing AS 3740 waterproofing requirements shapes wet-area sealant specifications favoring low-VOC water-based acrylic systems.
- Modular construction integration:Factory-built component assembly in South Korea and Japan demands pre-applied sealant solutions with controlled cure environments.
Industry Challenges
- Polyurethane formulation expertise scarcity:Skilled polymer chemist availability is rotating toward silicone centers in South Korea and Japan, tightening talent pools for isocyanate-cured system development.
- Multi-jurisdiction certification timelines:Vietnam's emerging technical regulation alignment with ASEAN harmonized standards creates uncertainty for import certification pathways and local manufacturing investment timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sealants Market |
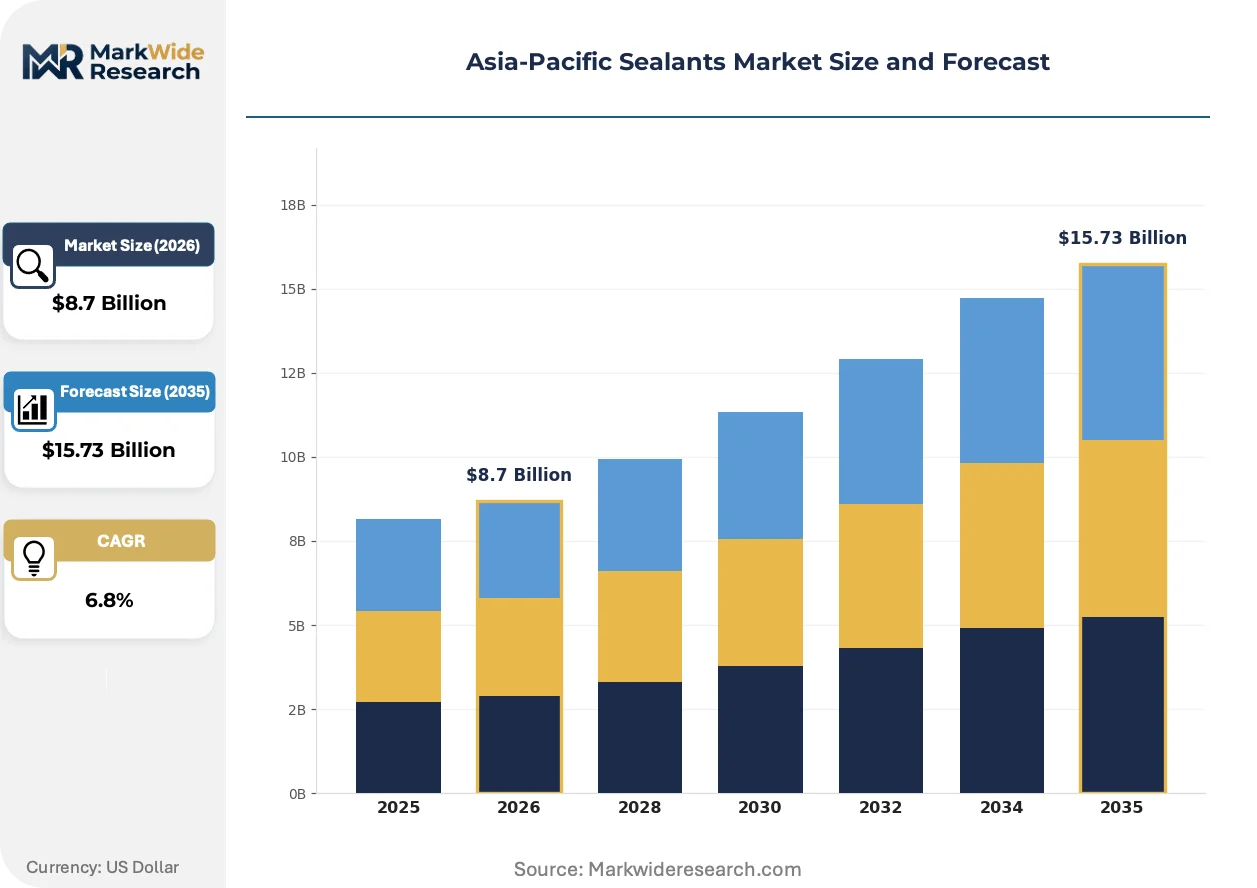
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Butyl End User: Construction, Automotive, Electronics, Aerospace Application: Bonding, Sealing, Coating, Insulation Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, Arkema, H.B. Fuller Company, BASF SE, Dow, Pidilite Industries Limited, Wacker Chemie AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sealants Market Trends and Innovations
Formulation chemistry is pivoting toward hybrid architectures that bridge performance gaps between established polymer families. This evolution is compressing traditional material boundaries and enabling specification substitution across construction and electronics end-uses.
Silane-modified polyether technology is decomposing the historical silicone-polyurethane performance tradeoff in expansion joint applications. Australian infrastructure contractors are specifying these hybrids for bridge and highway projects requiring both UV stability and abrasion resistance. The technology is decomposing procurement silos that previously separated façade specialists from civil engineering suppliers.
Japan's METI is tightening JIS A 5758 building sealant performance standards with enhanced durability testing protocols. Domestic formulators are reformulating portfolios to meet accelerated weathering requirements, while import-dependent suppliers face extended certification timelines. Façade and glazing contractors in Tokyo and Osaka are consolidating procurement around pre-qualified domestic product lines.
Electronics assemblers in Taiwan and Malaysia are compressing supplier bases around sealant vendors with integrated bonding chemistry portfolios. Semiconductor packaging lines now specify single-source accountability for moisture protection and die-attach materials. This concentration is most visible in advanced packaging facilities where process contamination risks override historical multi-sourcing preferences.
Asia-Pacific Sealants Market Segmentation
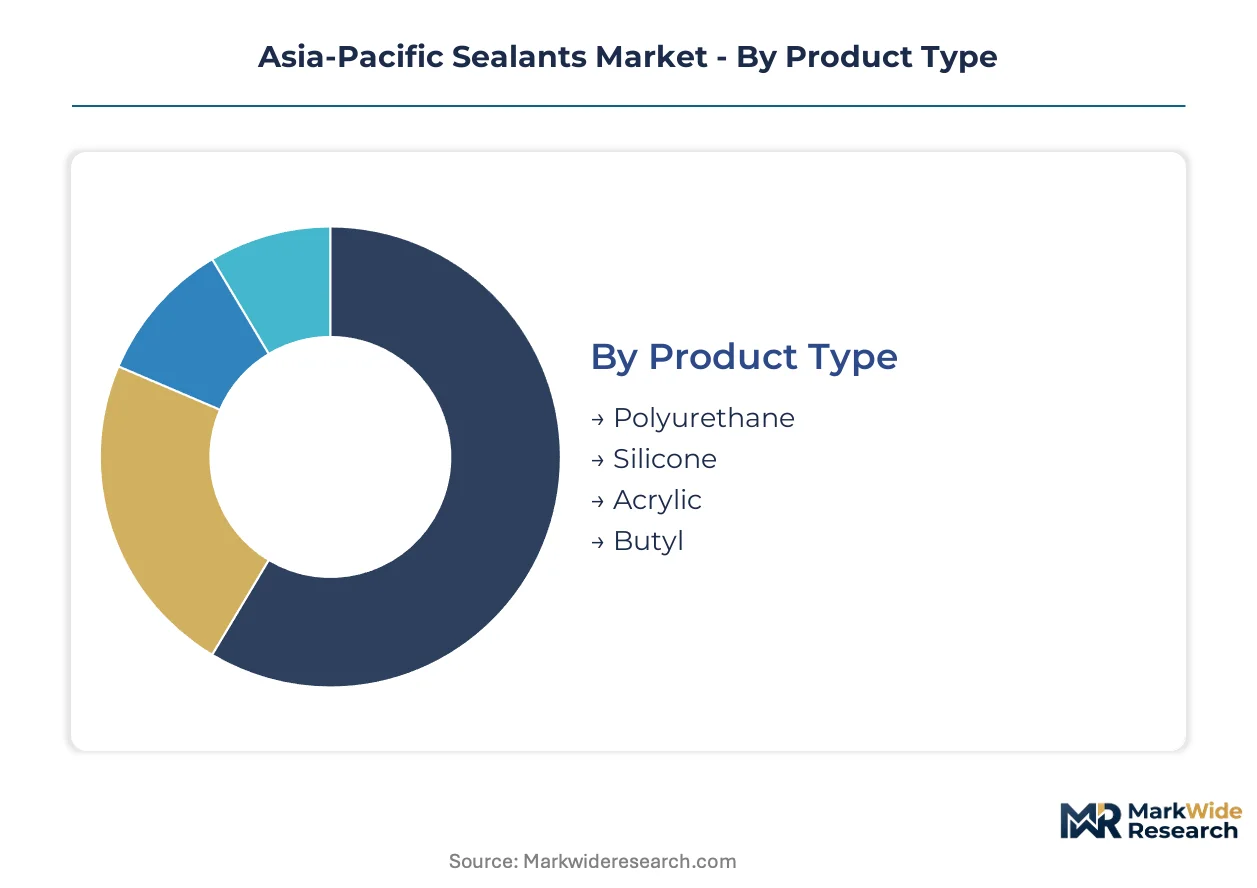
Segmentation in Asia-Pacific sealants reveals how formulation chemistry, end-use specifications, and channel economics fragment procurement patterns across construction megaprojects and precision electronics. Understanding these divides exposes where specification power concentrates and where price competition dominates.
Product Type:
Margin pools concentrate in high-performance formulations where certification barriers and raw material access create pricing power for qualified suppliers.
- Silicone:Polysiloxane backbone systems delivering 20-50 Shore A hardness with 50-year UV stability ratings dominate structural glazing specifications across China's GB 16776-mandated curtain wall projects and Australian high-rise envelopes. Demand concentrates in Vietnam's manufacturing corridor where Southeast Asian megaprojects specify certified portfolios for building envelope durability.
- Polyurethane:Isocyanate-cured formulations achieving 300-800% elongation capture expansion joint and automotive underbody applications where abrasion resistance and paint compatibility matter. Procurement concentrates in Japanese automotive assembly and Australian civil infrastructure, though margin predictability suffers from isocyanate and polyol pricing volatility.
- Acrylic:Water-based emulsion systems operating across -20°C to 80°C service ranges occupy interior construction and DIY renovation segments where low odor and tool cleanup drive specification in Australia's NCC-governed wet areas.
- Butyl:Polyisobutylene compositions with sub-1% gas permeability maintain position in primary sealing of insulated glass units and roofing membranes across temperate climate zones.
Silicone holds installed capacity across certified structural glazing lines. Polyurethane is rotating up the share rankings in civil infrastructure hybrids.
End User:
Volume concentrates in construction, but value capture tilts toward electronics where contamination risks justify premium positioning.
- Construction:Façade, glazing, and waterproofing applications across Southeast Asian megaprojects and Australian infrastructure tenders pull specification-grade silicone and polyurethane formulations. India's BIS certification tightening for structural glazing is filtering procurement toward domestic formulators with certified portfolios.
- Electronics:Semiconductor packaging lines in Taiwan and Malaysia require specialized electronic-grade sealants for moisture protection in advanced node chip fabrication, with procurement compressing around vendors offering integrated bonding chemistry portfolios.
- Automotive:Underbody sealing and NVH management applications in Japanese and South Korean vehicle assembly specify polyurethane systems where paint compatibility and durability ratings matter.
- Aerospace:Fuel tank sealing and pressure boundary applications demand qualified silicone formulations meeting stringent outgassing and temperature cycling specifications.
Construction holds installed capacity across regional formulators. Electronics is rotating up the share rankings on advanced packaging demand.
Application:
Specification intensity varies sharply between structural bonding and commodity sealing, fragmenting supplier economics.
- Bonding:Structural adhesion in curtain walls, automotive panels, and semiconductor die-attach requires load-bearing cure profiles and long-term durability validation, concentrating procurement around qualified portfolios.
- Sealing:Gap-filling and fluid ingress blocking across building envelopes and industrial assemblies represents the largest volume application, with performance requirements scaling from commodity interior grades to certified structural systems.
- Coating:Protective layer applications in roofing and industrial maintenance favor spray-applied polyurethane and acrylic systems where application speed drives contractor preference.
- Insulation:Thermal and acoustic barrier applications in building envelopes and transportation equipment integrate sealant chemistry with foam systems, often specified as part of integrated envelope solutions.
Sealing holds installed capacity across formulation types. Bonding is rotating up the share rankings on structural certification requirements.
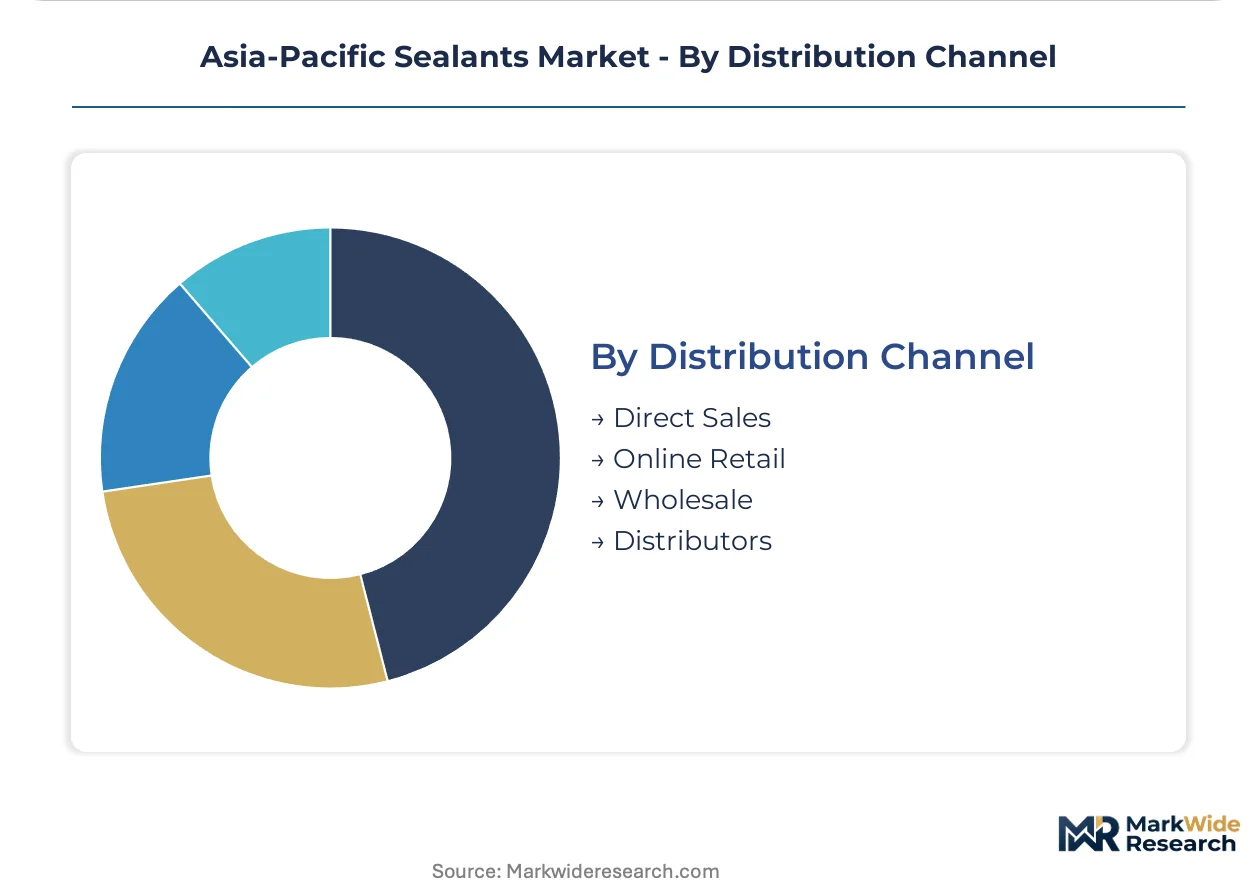
Distribution Channel:
Channel economics split between specification-driven direct engagement and price-sensitive wholesale volumes.
- Direct Sales:Specification-grade silicone and polyurethane for structural glazing and electronics packaging moves through manufacturer-direct technical sales supporting certification documentation and application engineering.
- Distributors:Regional stocking distributors serve construction contractors and automotive aftermarket with qualified portfolios, particularly in markets like Philippines where domestic formulation capacity remains limited.
- Wholesale:Bulk volume channels move commodity acrylic and butyl grades for interior construction and general maintenance, competing on price and availability rather than technical support.
- Online Retail:DIY renovation segments in Australia and Japan increasingly specify small-format acrylic and silicone through digital channels where product data sheets and certification marks substitute for technical sales contact.
Distributors hold installed capacity across construction-centric markets. Direct sales is rotating up the share rankings on electronics and structural glazing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB 16776 structural glazing standards that filter import eligibility and protect domestic silicone formulators. This regulatory anchor shapes procurement patterns across the region's largest construction market.
China
Curtain wall megaprojects in Shanghai and Shenzhen pull certified silicone formulations for 50-year durability specifications. SAMR's GB 16776 compliance thresholds accelerate substitution of uncertified imports. The Yangtze River Delta concentrates domestic formulator capacity serving high-rise envelope contracts.
Japan
Automotive underbody sealing and electronics packaging demand polyurethane systems with paint compatibility validation. METI enforces JIS A 5758 building sealant standards mandating 7-day cure profiles and 25% joint movement capability. Tokyo-Osaka industrial corridors concentrate reformulation activity around accelerated weathering protocols.
India
Structural glazing certification mandates from BIS redirect procurement toward domestic silicone portfolios with qualified test documentation. Commercial construction in Mumbai and Delhi-NCR specifies certified products for high-performance envelopes. Domestic formulators expand capacity to capture redirected import volume.
South Korea
Semiconductor packaging lines in the Seoul Capital Area require electronic-grade sealants for moisture protection in advanced node fabrication. MFDS and KOSHA frameworks govern industrial chemical handling and workplace exposure limits. Busan-Ulsan manufacturing corridors concentrate bonding chemistry production for electronics assembly.
Australia
Infrastructure tenders across New South Wales and Victoria specify silicone-polyurethane hybrids for bridge and highway expansion joints. The NCC references AS 3740 waterproofing requirements shaping wet-area acrylic specifications. Sydney-Melbourne construction corridors concentrate specification-grade procurement around certified portfolios.
Asia-Pacific Sealants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific sealants market. Multinational chemical conglomerates with silane-modified polymer capabilities anchor the high-performance specification tier, while regional formulators compete on price-accessible construction grades. Three archetypes dominate: integrated polymer feedstock controllers, construction-specialized specification houses, and electronics-focused bonding chemistry suppliers. Competitive moves concentrate on backward integration into raw material access and geographic expansion through certified distribution partnerships.
Among diversified chemical conglomerates, Dow and Wacker Chemie AG occupy positions as upstream feedstock anchors controlling silane-modified polymer access. Sika AG exemplifies the construction-specialized archetype with specification-grade portfolios aligned to infrastructure tender requirements. Henkel AG & Co. KGaA represents the electronics-focused bonding chemistry tier serving semiconductor packaging lines in Taiwan and Malaysia.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| Arkema |
| H.B. Fuller Company |
| BASF SE |
| Dow |
| Pidilite Industries Limited |
| Wacker Chemie AG |
| Others |
Pricing and Supply Chain Analysis
Silane-modified polyether substitution for conventional silicone and polyurethane systems is redrawing supply geography toward South Korean and Japanese formulation hubs while compressing price premiums for mid-performance tiers across Australian infrastructure and Southeast Asian megaprojects.
Pricing Analysis
Price spreads between Japanese JIS A 5758-certified structural grades and commodity Southeast Asian construction tiers reach multiples of three to five, with certification documentation and 50-year durability warranties as the primary differentiation drivers. Three-tier pricing structure across specification-grade, qualified-standard, and commodity-economy levels reflects GB 16776 compliance thresholds and BIS certification status. Cost compression in economy acrylic and butyl segments is intensifying due to raw material volatility and wholesale channel oversupply. Small contractors and DIY renovators exhibit highest price sensitivity, while electronics assemblers and curtain wall specifiers prioritize contamination risk mitigation and warranty backing over unit economics.
Supply Chain Analysis
Silane monomer feedstock chokepoints at Dow and Wacker production complexes in the United States and Germany tether regional formulation flexibility to preferred OEM offtake agreements. Upstream supply concentrates in China, South Korea, and Japan for silicone base polymers, with Germany and the United States anchoring specialty silane-modified polyether intermediates. Polyurethane systems draw from isocyanate and polyol streams vulnerable to petrochemical pricing swings and energy cost passthroughs. Single-source vulnerability around electronic-grade sealant purification creates qualification bottlenecks for advanced node semiconductor packaging. Distribution runs through manufacturer-direct technical sales for specification grades and regional stocking distributors for construction volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific sealants are approaching a platform-economics inflection where hybrid formulation architectures and integrated bonding chemistry portfolios create winner-take-most dynamics in electronics assembly and structural glazing procurement.
For Market Incumbents: Consolidate specification-grade certification portfolios around GB 16776 and JIS A 5758 compliance to defend against emerging domestic formulators in India and Vietnam. Deepen backward integration into silane-modified polymer feedstock or lock long-term offtake with Dow and Wacker to secure formulation flexibility as raw material access tightens. For New Entrants and Emerging Players: Lead with Philippines infrastructure gap penetration, where limited domestic formulation capacity and underpenetrated commercial construction create first-mover advantage for certified silicone suppliers. Target wet-area acrylic specifications in Australia's NCC-governed residential renovation segment through digital channel positioning with embedded certification data sheets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors construction-specialized specification houses with anchored infrastructure tender relationships and electronics-focused bonding chemistry suppliers with semiconductor packaging line qualifications. Over the long-term viability window, acquisition targets should demonstrate either captive raw material access or irreplicable certification documentation. The signal to watch as inflection indicator is Vietnam's technical regulation alignment pace with ASEAN harmonized standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Feedstock | Dow and Wacker's upstream control over silane-modified polymers limits formulation flexibility for non-preferred regional OEMs. |
| GB 16776 Certification Investment | China's SAMR structural glazing standard filters import eligibility and protects domestic formulator market share. |
| Philippines Distribution Partnership | Limited domestic formulation capacity creates first-mover advantage for certified silicone suppliers in commercial construction. |
| Hybrid Formulation R&D Expansion | Silane-modified polyether technology bridges silicone-polyurethane performance gaps in Australian bridge and highway projects. |
| Electronics Assembly Channel Concentration | Taiwan and Malaysia semiconductor packaging lines compress supplier bases around integrated bonding chemistry portfolios. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with polymer chemists, construction procurement managers, electronics assembly engineers, and distribution channel partners across South Korea, Japan, Australia, and Southeast Asia; and secondary validation through customs trade records, BIS certification registries, GB standards documentation, and SEC filings from diversified chemical conglomerates. Bottom-up demand modeling triangulated against top-down macro construction and electronics production indicators.
Across the projection horizon, the analytical framework modeled segmentation across formulation chemistry, end-use industry, application intensity, and distribution channel economics. CAGRs derived from volume-demand buildups by country and product tier, cross-referenced against raw material availability constraints and regulatory compliance timelines. Key inputs included ASEAN megaproject pipeline tracking, semiconductor packaging capacity expansion schedules, and automotive assembly platform standardization trends.
The analysis sits within stated boundaries; outcomes outside sustained construction investment flows, stable isocyanate-polyol pricing, and electronics assembly reshoring patterns would require recalibration. Practitioners should keep alternative scenarios live as Vietnam's ASEAN harmonization trajectory and India's BIS enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market